
 Europe B2B Brown Sugar Market | 2026-2036
Europe B2B Brown Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe B2B Brown Sugar Market Analysis
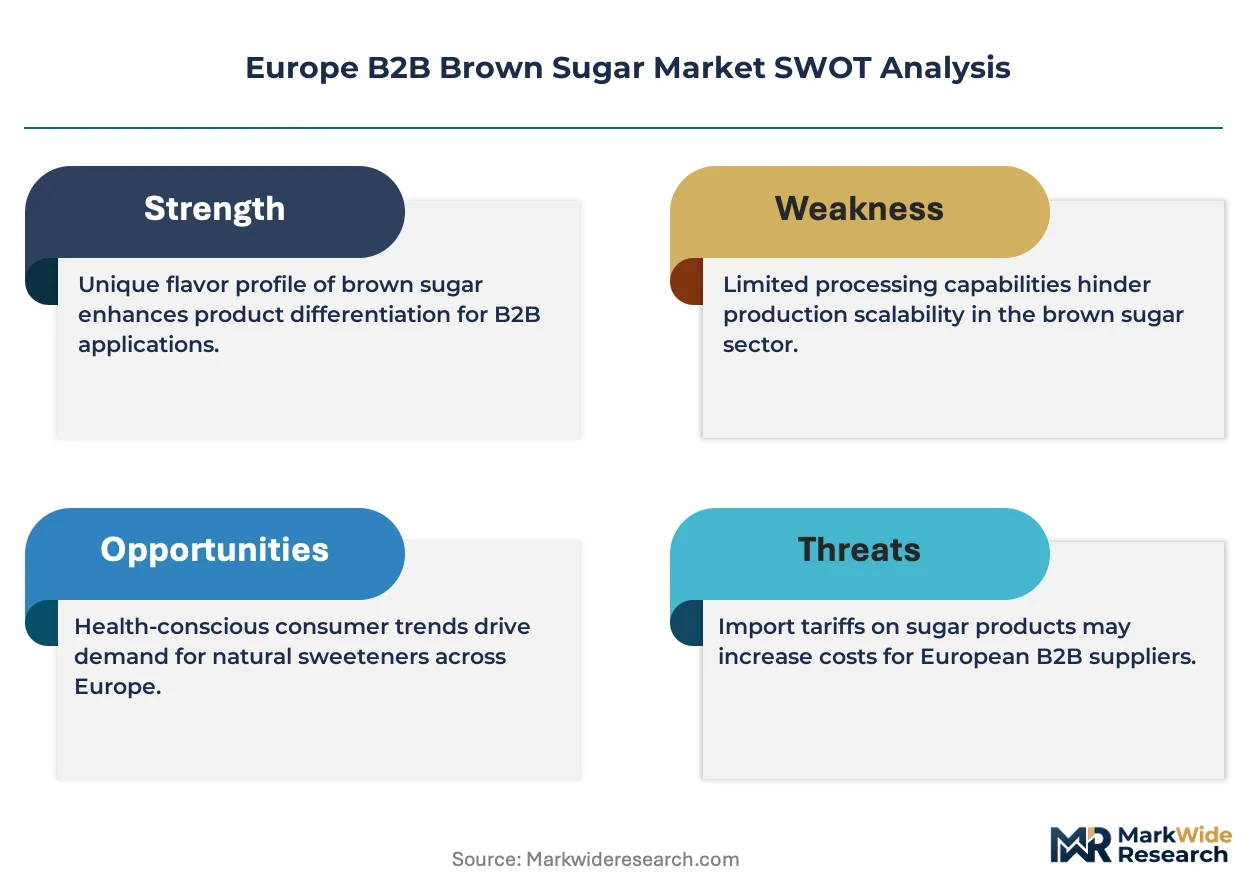
Central European beet sugar processors is pivoting toward specialty brown sugar grades to offset commodity price volatility. Nordzucker AG leverages its Nordic and German milling footprint to sustain bulk supply contracts with industrial bakeries. Sudzucker AG anchors Central European distribution through integrated refineries in Poland and Austria. Agrana Group competes on organic certification depth, sourcing from contracted beet farms across Hungary and Romania.
B2B brown sugar denotes partially refined sucrose retaining molasses content, typically 3.5-6.5% by mass, which imparts moisture retention, caramelization acceleration, and distinct flavor profiles in industrial food production. Conventional brown sugar dominates volume flows to beverage sector blenders seeking cost-stable sweetening inputs, while organic brown sugar captures expanding margin pools from clean-label confectionery shops in France and Italy. Liquid brown sugar grows fastest among packaging formats as automated dosing systems spread through industrial bakery lines, though bulk containers still occupy the majority of tonnage moved through direct sales channels.
EMA food-contact standards, EU Green Deal emissions benchmarks, and REACH chemical safety protocols collectively shape processor compliance costs and product certification requirements for brown sugar entering European food chains. EFSA nutritional labeling rules pressure reformulation toward reduced-sugar variants, redirecting some B2B demand toward concentrated molasses extracts and alternative sweetener blends. Stakeholders must monitor how the EU AI Act and evolving CSRD disclosure mandates reshape supply chain traceability investments across beet-growing regions.
Market Dynamics
Central European beet sugar processors face mounting pressure from the EU Green Deal emissions benchmarks, forcing capital reallocation toward molasses recovery systems and carbon capture retrofits at refineries across Poland and Austria.
Growth Catalysts
- Clean-label confectionery mandates:French and Italian artisanal chocolate houses now specify organic brown sugar with certified molasses content above 4.5% for caramelization control in praline production.
- F-Gas Regulation compliance deadlines:Industrial bakeries in Germany's Hamburg-Munich corridor accelerate equipment upgrades, creating pull for liquid brown sugar compatible with automated dosing infrastructure.
- EMA food-contact standard harmonization:Cross-border ingredient sourcing between Hungary and Romania gains efficiency as mutual recognition agreements reduce duplicate testing burdens for brown sugar shipments.
Market Restraints
- Beet supply concentration:Weather volatility in the Danube basin threatens yield stability for processors dependent on contracted Hungarian and Romanian farms.
- Natural gas price exposure:Crystallization and drying stages at refineries remain tethered to continental energy markets, compressing margins during winter demand spikes.
- Stevia and monk fruit substitution:Beverage blenders in the Netherlands and Belgium reformulate reduced-sugar variants, displacing conventional brown sugar volumes in carbonated soft drink applications.
Strategic Opportunities
- CSRD disclosure mandates:Integrated reporting requirements create first-mover advantage for processors with farm-level traceability systems already deployed across beet-growing regions.
- Liquid format penetration:Industrial bakery lines in Spain and Portugal present underexploited demand for pumpable brown sugar syrups eliminating manual handling stages.
- EU AI Act supply chain applications:Predictive quality algorithms for molasses consistency attract investment from refineries seeking to reduce batch rejection rates in high-value organic grades.
Industry Challenges
- REACH chemical safety documentation:Processors struggle to compile substance volume tracking for processing aids used in sulfur dioxide reduction at beet reception facilities.
- Legacy ERP integration:Farm-to-fork traceability modules clash with decades-old inventory systems at mid-sized Central European mills, delaying certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe B2B Brown Sugar Market |
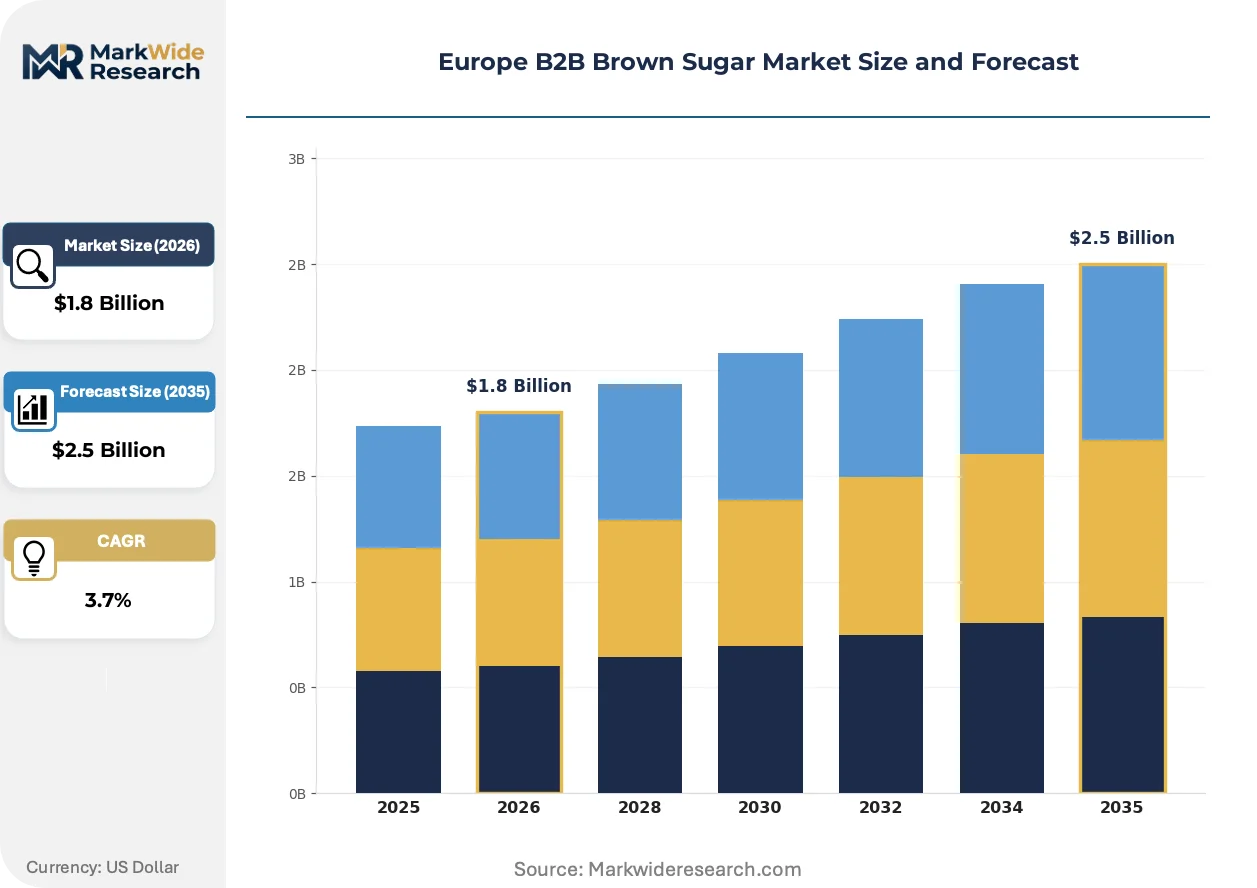
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Brown Sugar, Conventional Brown Sugar, Liquid Brown Sugar, Sugar Cubes Packaging Type: Bags, Bulk Containers, Sachets, Tubs End User: Food Industry, Beverage Sector, Bakery Sector, Confectionery Shops Distribution Channel: Direct Sales, Wholesalers, Online Retail, Supermarkets |
| Companies Covered | Agrana Group, Suedzucker Polska, Sudzucker AG, Nordzucker AG, Billington’s, Tate & Lyle PLC, ASR Group, Cargill Inc., Nordic Sugar A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe B2B Brown Sugar Market Emerging Trajectories
Processing technology and procurement logic are converging to reshape how brown sugar moves through European food manufacturing, with automation and compliance demands rewriting established supply relationships.
Continuous centrifugal separation technology is unifying molasses retention control with energy efficiency gains at integrated refineries. German industrial bakeries adopting liquid brown sugar formats are retrofitting dosing lines at pace, compressing the advantage window for traditional crystal suppliers who lack pumpable product portfolios.
EFSA nutritional labeling rules are forcing reformulation dialogues between sugar processors and confectionery houses. The industrial consequence is a bifurcation in procurement specifications, with premium accounts demanding organic certification depth while commodity buyers prioritize cost stability through long-term beet supply contracts.
Direct sourcing arrangements between food manufacturers and beet cooperatives are displacing traditional merchant intermediary roles. French clean-label confectionery shops now contract directly with Hungarian organic farms, fragmenting volume concentration that previously flowed through Nordzucker and Sudzucker distribution networks. This pattern is most visible in the Paris-Lyon artisanal corridor, where traceability premiums override historical supplier loyalty.
Europe B2B Brown Sugar Market Segmentation
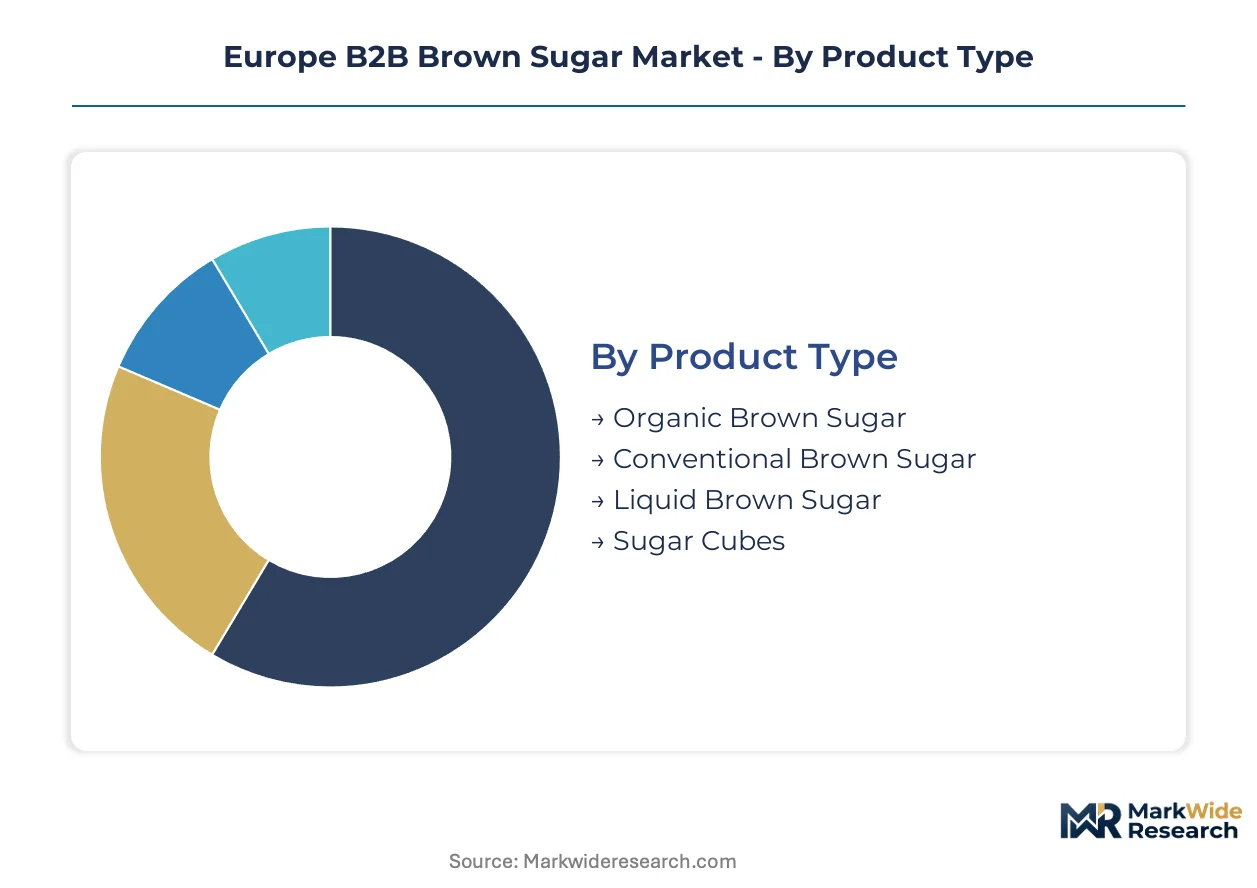
European B2B brown sugar procurement splits across four dimensions that each reshape capital deployment and margin capture. Product certification depth, packaging automation compatibility, end-use specification intensity, and channel traceability requirements create divergent investment profiles for processors serving industrial food chains.
Product Type:
Capital intensity peaks with organic certification infrastructure and liquid processing lines, while conventional crystallization requires lower upfront outlays but exposes processors to commodity margin compression.
- Organic Brown Sugar:Beet supply must meet EU organic farming standards with three-year conversion periods and segregated processing streams. French and Italian clean-label confectionery houses in the Paris-Lyon corridor now mandate certified molasses content above 4.5% for caramelization control, tightening farm-level audit requirements.
- Liquid Brown Sugar:Pumpable syrups demand specialized evaporators and automated dosing compatibility that retrofit poorly into legacy crystal lines. German industrial bakeries along the Hamburg-Munich corridor are retrofitting equipment at pace, compressing the advantage window for traditional suppliers lacking pumpable portfolios.
- Conventional Brown Sugar:Partially refined sucrose with standardized 3.5-6.5% molasses content serves beverage blenders seeking cost-stable inputs.
- Sugar Cubes:Compressed formats for foodservice dispensing require dedicated molding presses and moisture-controlled packaging.
Most installed capacity flows through Conventional Brown Sugar. Expansion is steepest in Liquid Brown Sugar.
Packaging Type:
Automation readiness and handling labor costs divide procurement patterns, with bulk formats dominating volume tonnage and sachet lines capturing premium positioning in artisanal channels.
- Bulk Containers:Tote bins and tanker shipments eliminate intermediate handling for high-volume bakery and beverage accounts. Polish and Austrian refineries anchor Central European distribution through direct bulk contracts with industrial food manufacturers.
- Bags:Multi-wall paper and woven polypropylene formats balance protection with manual handling feasibility for mid-scale processors.
- Sachets:Single-serve portions target foodservice and artisanal retail in France and Italy where portion control and brand presentation command price premiums.
- Tubs:Reclosable rigid packaging serves specialty confectionery shops requiring repeated access without moisture degradation.
Volume concentrates in Bulk Containers. Margin expansion concentrates in Sachets.
End User:
Specification stringency and reformulation pressure vary sharply across food manufacturing verticals, with confectionery and beverage sectors driving divergent product development priorities.
- Confectionery Shops:Artisanal chocolate houses and praline producers demand precise molasses content for caramelization chemistry. French clean-label mandates are redirecting procurement toward direct farm contracts that fragment traditional processor distribution networks.
- Beverage Sector:Carbonated soft drink and ready-to-drink tea blenders in the Netherlands and Belgium are reformulating reduced-sugar variants, displacing conventional brown sugar volumes while creating demand for concentrated molasses extracts.
- Food Industry:Sauces, dressings, and prepared meals manufacturers prioritize cost stability through long-term beet supply contracts.
- Bakery Sector:Industrial bread and pastry lines in Germany and Spain are adopting liquid formats to eliminate manual scaling stages.
Specification intensity peaks with Confectionery Shops. Volume scale peaks with Food Industry.
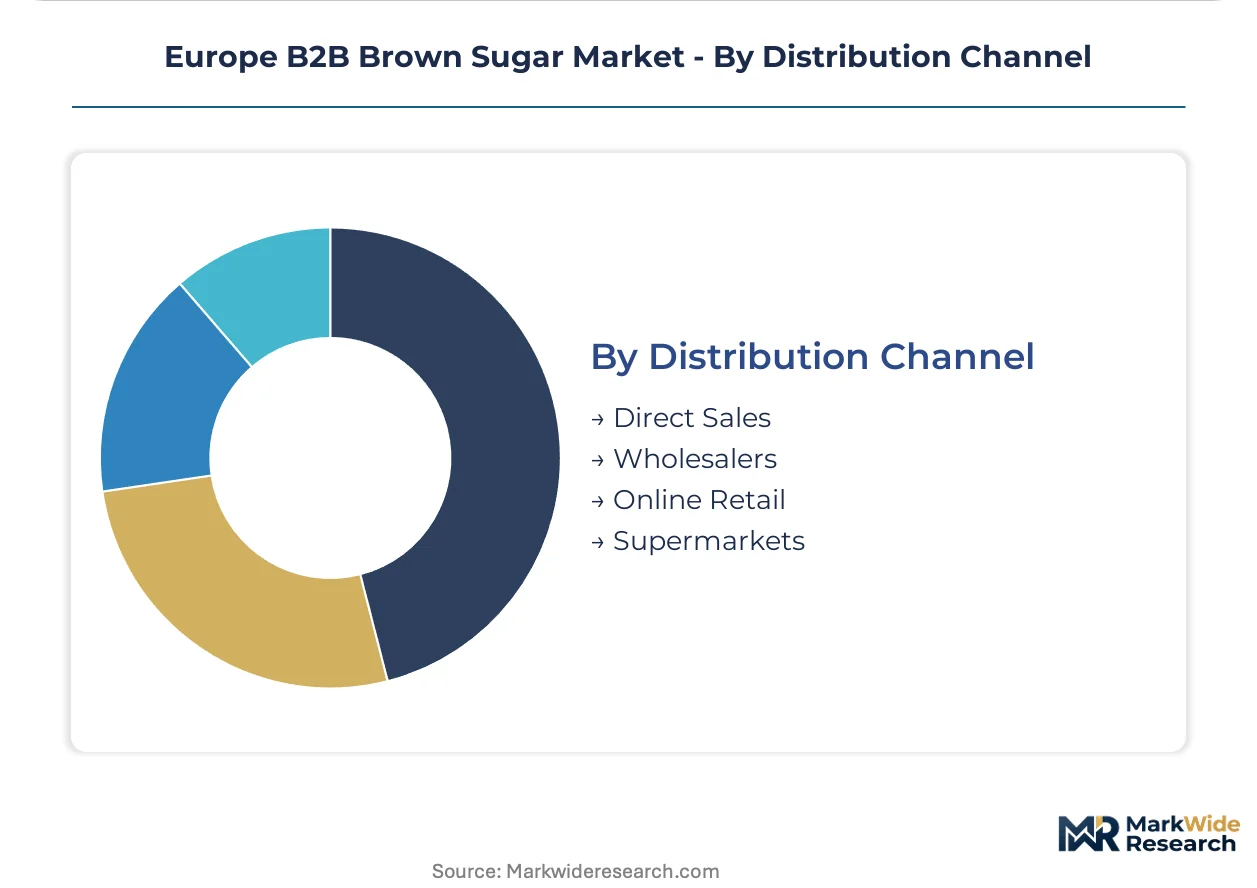
Distribution Channel:
Traceability depth and working capital requirements segment channel economics, with direct arrangements displacing traditional merchant intermediaries in premium tiers.
- Direct Sales:Processor-to-manufacturer contracts enable farm-level traceability documentation required by CSRD disclosure mandates. Hungarian and Romanian beet cooperatives are now contracting directly with French confectionery houses, bypassing Nordzucker and Sudzucker distribution networks.
- Wholesalers:Merchant intermediaries retain relevance for mid-scale bakery and foodservice accounts lacking procurement scale for direct negotiation.
- Online Retail:Digital procurement platforms are gaining traction among smaller confectionery shops seeking transparent certification documentation.
- Supermarkets:Retail grocery channels serve incidental B2B demand from small foodservice operators and institutional kitchens.
Volume flows predominantly through Direct Sales. Channel innovation concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as processors migrate capacity toward jurisdictions with favorable F-Gas Regulation phase-out timelines and accessible carbon capture retrofit financing. The EU Green Deal's emissions benchmarks create compliance cost gaps between member states with divergent national subsidy programs for industrial decarbonization.
Germany
Industrial bakeries along the Hamburg-Munich corridor drive liquid brown sugar procurement for automated dosing infrastructure. The F-Gas Regulation's 2030 equipment replacement deadlines accelerate capital deployment toward compatible syrup handling systems. Refinery clusters in Lower Saxony and Bavaria anchor Central European bulk distribution networks.
France
Artisanal confectionery houses in the Paris-Lyon corridor specify organic brown sugar with certified molasses content above 4.5% for praline caramelization chemistry. EFSA nutritional labeling rules pressure reformulation toward reduced-sugar variants with concentrated molasses extracts. Direct farm contracting with Hungarian cooperatives fragments traditional processor distribution channels.
Poland
Sudzucker AG's integrated refineries leverage EU structural funds for molasses recovery system upgrades that meet Green Deal emissions benchmarks. Bulk container shipments to German industrial food manufacturers concentrate throughput at Baltic port facilities. The country's natural gas price exposure compresses crystallization stage margins during winter demand spikes.
Hungary
Organic beet farming across the Great Hungarian Plain supplies French clean-label confectionery shops through direct cooperative arrangements bypassing Nordzucker networks. Three-year conversion periods and segregated processing streams tighten farm-level audit requirements. Danube basin weather volatility threatens yield stability for contracted supply obligations.
Netherlands
Beverage blenders in Rotterdam and Amsterdam reformulate carbonated soft drinks with stevia and monk fruit substitutes, displacing conventional brown sugar volumes. REACH chemical safety documentation requirements complicate substance volume tracking for processing aids. Port logistics infrastructure supports transshipment of bulk containers to Belgian food industry accounts.
Europe B2B Brown Sugar Market Vendor Landscape
German and Austrian producers anchor the scale-driven tier; Nordic and British specialists hold differentiated positions in organic certification depth. Central European beet sugar processing exhibits moderate consolidation around integrated refinery networks with captive beet supply contracts. Three archetypes dominate: diversified agribusiness conglomerates with multi-commodity portfolios, regionally focused sugar cooperatives with farmer ownership structures, and specialty organic processors with direct farm relationships. Competitive moves concentrate on CSRD-aligned traceability system deployment and liquid format capacity expansion for automated bakery lines.
Within the diversified agribusiness tier, Cargill Inc. and Tate & Lyle PLC represent global-scale entities with multi-sweetener portfolios that extend beyond brown sugar into alternative ingredients and functional syrups. Among Central European cooperative structures, Sudzucker AG and Nordzucker AG exemplify the vertically integrated model with controlled beet supply chains spanning multiple member states. Agrana Group occupies a position within the specialty organic segment, leveraging contracted farm relationships across Hungary and Romania to serve clean-label confectionery demand in France and Italy.
| Leading Market Players |
|---|
| Agrana Group |
| Suedzucker Polska |
| Sudzucker AG |
| Nordzucker AG |
| Billington's |
| Tate & Lyle PLC |
| ASR Group |
| Cargill Inc. |
| Nordic Sugar A/S |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between organic and conventional brown sugar manifests in parallel supply chain configurations across Europe. Premium organic tiers command farm-level traceability investments and segregated processing streams, while commodity-grade flows concentrate through bulk distribution networks anchored in German and Polish refining clusters.
Pricing Analysis
Distributor margin layers compress as direct sales channels expand between Hungarian beet cooperatives and French confectionery houses. Three-tier pricing structure across premium organic, standard industrial, and economy beverage grades reflects molasses content precision and certification depth. Cost compression in conventional crystallization tiers intensifies because natural gas price exposure at Polish and Austrian refineries feeds through to contract renegotiations. Beverage blenders in the Netherlands exhibit highest price sensitivity, while Paris-Lyon artisanal chocolate houses absorb premiums for certified molasses consistency above 4.5%.
Supply Chain Analysis
EU Green Deal domestic-content benchmarks reshape sourcing toward refineries with accessible carbon capture retrofit financing in Germany, Poland, and Austria. Raw material dependencies center on beet supply from the Great Hungarian Plain, sulfur dioxide processing aids, and molasses recovery system components. Single-source vulnerability concentrates in Danube basin weather exposure threatening yield stability for contracted Hungarian and Romanian farms. Distribution runs through direct processor-to-manufacturer contracts displacing traditional Nordzucker and Sudzucker merchant intermediary roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in liquid format conversion and organic certification depth as automation capital and clean-label premiums offset commodity price volatility.
For Market Incumbents: To counter direct farm contracting fragmentation, deploy CSRD-aligned traceability systems across beet-growing regions and retrofit liquid processing capacity for automated German bakery lines. Captive supply integration into Hungarian organic farming cooperatives preserves volume concentration against cooperative bypass threats. For New Entrants and Emerging Players: Digital procurement platforms for smaller French and Italian confectionery shops offer the most penetrable entry vector. Target underexploited Spanish and Portuguese industrial bakery demand for pumpable brown sugar syrups. Lead with transparent online certification documentation to differentiate against legacy processor opacity. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized Central European mills struggle with legacy ERP integration against farm-to-fork traceability mandates. Long-term viability favors processors with deployed molasses recovery systems and organic certification infrastructure. Watch F-Gas Regulation compliance deadlines as equipment replacement cycle inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Format Capacity Expansion | Captures German Hamburg-Munich corridor automation retrofit demand from industrial bakeries. |
| Backward Integration into Organic Beet Farming | Secures three-year conversion period supply for French clean-label confectionery procurement. |
| Molasses Recovery System Deployment | Aligns Polish and Austrian refineries with EU Green Deal emissions benchmarks. |
| Direct Farm Cooperative Partnerships | Bypasses Nordzucker and Sudzucker distribution networks for Paris-Lyon traceability premiums. |
| Predictive Quality Algorithm Investment | Reduces batch rejection rates in high-value organic grades under EU AI Act frameworks. |
Methodological Framework
Bottom-up food manufacturer procurement modeling reconciled against top-down beet supply tracking forms the analytical core of this study. Primary interviews with Central European refinery operations managers, French confectionery procurement directors, German industrial bakery supply chain leads, and Hungarian agricultural cooperative representatives combined with secondary validation from EU trade customs data, EFSA regulatory filings, and F-Gas Regulation compliance databases. Top-down and bottom-up estimates triangulate through cross-referencing processor capacity announcements against end-user contract disclosures.
Historical trendline analysis of brown sugar grade premiums and packaging format shifts informs the projection framework. Segmentation dimensions span product certification tier, packaging automation compatibility, end-use specification intensity, and distribution channel traceability depth across the analysis window. CAGRs derive from fitted growth curves adjusted for regulatory compliance cost trajectories and substitution elasticity from stevia and monk fruit in beverage applications.
The model assumes a particular technology adoption path; alternative pathways for continuous centrifugal separation and automated dosing infrastructure would alter the outlook. Forecasts reflect assumptions about EU Green Deal implementation pacing and organic farming conversion rates. Weather volatility in the Danube basin and natural gas price spikes represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Germany Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
Isomaltulose Market
Sweeteners
Floral Nectar Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Trehalose Market
Sweeteners
Australia Allulose Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Sweeteners Market
Sweeteners
Europe Stevia Market