
 Raw Beetroot Sugar Market | 2026-2036
Raw Beetroot Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Raw Beetroot Sugar Market Analytics
European beet sugar processing capacity is shifting toward eastern growing regions as climate patterns alter sowing calendars. Südzucker AG leverages vertical integration from seed supply to refined output across Germany and Poland. Nordzucker AG sustains coastal refining advantages in northern Europe with specialized liquid sugar lines. Tereos Group competes through cooperative sourcing networks in France that anchor regional beet supply security.
Raw beetroot sugar denotes sucrose extracted from Beta vulgaris roots through diffusion, liming, carbonation, and crystallization, yielding purity levels comparable to cane-derived equivalents for industrial formulation. Crystal sugar dominates bulk procurement by beverage manufacturers seeking consistent dissolution rates, while liquid sugar captures margin pools in automated bakery production lines where handling efficiency outweighs per-unit premiums. Granulated variants occupy mature retail channels with stable pricing, and powdered formats extend into confectionery applications demanding rapid blend integration.
The EU Green Deal and REACH frameworks govern agricultural input restrictions and processing chemical standards, compelling beet processors to certify carbon intensity thresholds for market access. EFSA sucrose purity benchmarks shape food-grade specifications that determine eligibility for infant nutrition and pharmaceutical excipient applications. Stakeholders must monitor evolving EU F-Gas Regulation impacts on refrigeration-dependent storage infrastructure and assess backward integration into seed biotechnology as climate adaptation intensifies.
Market Dynamics
Climate vulnerability in cane sugar belts is accelerating beetroot sugar procurement across European food processors, while EU Green Deal agricultural mandates restructure crop rotation incentives and carbon intensity certification requirements for market access.
Growth Catalysts
- EU Green Deal crop rotation incentives:Agricultural sustainability mandates reward beet cultivation diversity, expanding sowable acreage across Germany and Poland.
- Carbon intensity thresholds:Processors certifying low-carbon output gain preferential access to infant nutrition and pharmaceutical excipient supply chains under EFSA benchmarks.
- Cooperative sourcing networks:Regional beet supply security through farmer-processor partnerships anchors processing capacity in eastern growing regions.
Market Restraints
- Input cost volatility:Natural gas prices govern diffusion and crystallization energy economics, compressing processor margins during supply shocks.
- Supply concentration risk:Coastal refining infrastructure in northern Europe faces sea-level exposure and F-Gas Regulation compliance burdens for refrigeration-dependent storage.
- Substitution threat:High-fructose corn syrup and alternative sweeteners capture beverage formulation share where dissolution-rate tolerances permit.
Strategic Opportunities
- Seed biotechnology integration:Climate-adapted Beta vulgaris cultivars from specialized breeders enable sowing calendar extension into marginal growing zones.
- Liquid sugar automation:Automated bakery production lines favor handling efficiency over per-unit premiums, capturing margin pools in industrial channels.
- Eastern European processing expansion:Poland and adjacent markets offer greenfield refining capacity with proximity to expanding beet cultivation.
Industry Challenges
- Refrigeration infrastructure capex:EU F-Gas Regulation phase-down schedules force storage facility retrofits or replacement with alternative cooling systems.
- EFSA certification timelines:Sucrose purity benchmarking for food-grade and pharmaceutical applications requires extended analytical validation cycles.
- Legacy cane sugar formulation lock-in:Beverage manufacturers face recipe recertification costs and sensory testing burdens when switching beet-derived inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raw Beetroot Sugar Market |
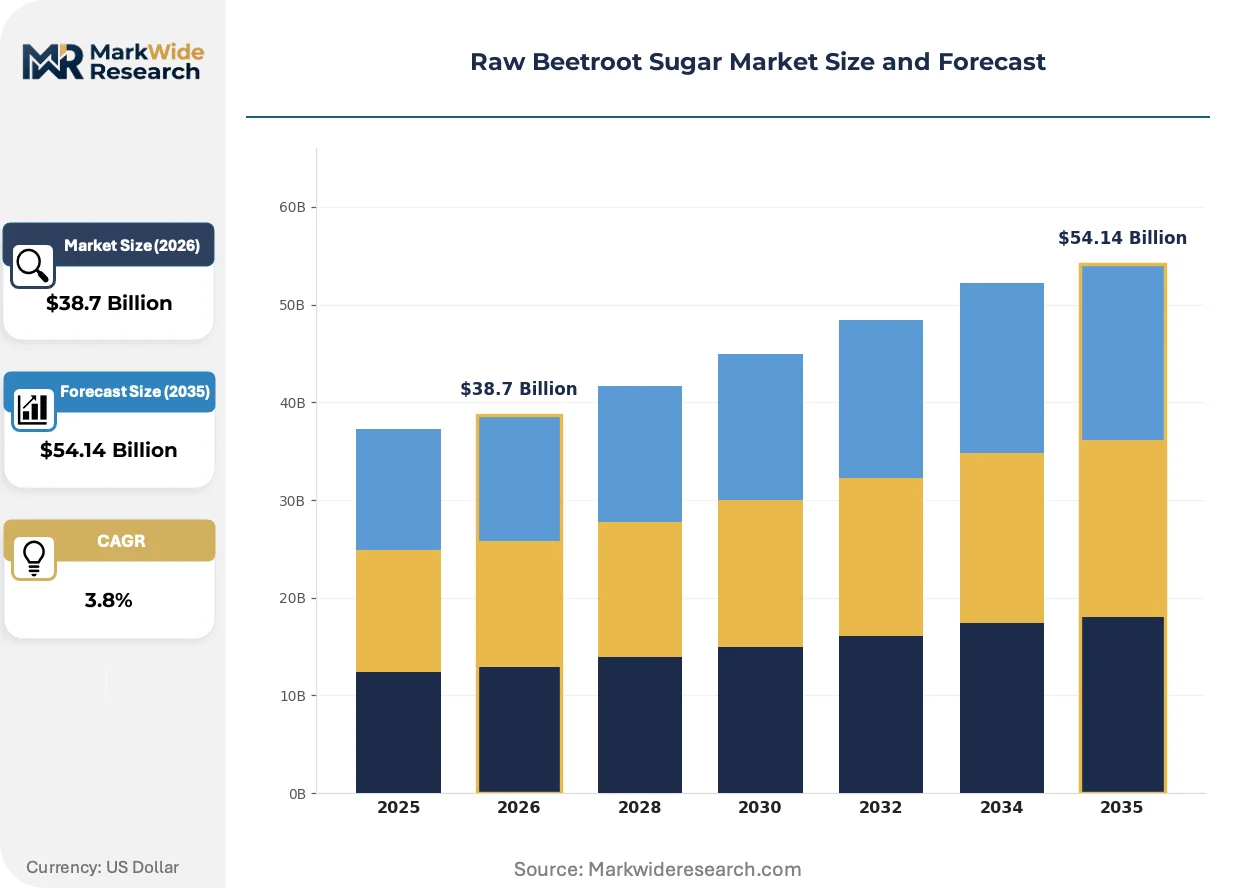
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystal Sugar, Liquid Sugar, Granulated Sugar, Powdered Sugar End User: Food Industry, Beverage Industry, Bakery Sector, Confectionery Manufacturers Distribution Channel: Online Retail, Hypermarkets, Supermarkets, Wholesale Distributors Packaging Type: Bags, Bulk Containers, Sachets, Bottles |
| Companies Covered | Südzucker AG, Nordzucker AG, Tereos Group, British Sugar, Cosun Beet Company, American Crystal Sugar Company, Michigan Sugar Company, Amalgamated Sugar Company, Pfeifer & Langen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raw Beetroot Sugar Market Evolving Landscape
Diffusion optimization technologies and regulatory carbon accounting are rewriting processing economics, while demand patterns shift toward automated handling formats and supply chain transparency requirements reshape procurement criteria.
Membrane filtration is rewriting extraction efficiency benchmarks in beet sugar processing. German and Polish processors deploy ceramic and polymeric membranes to reduce liming and carbonation chemical loads. This technology is compressing water and energy intensity per ton of refined output, enabling compliance with tightening EU industrial emissions standards.
REACH frameworks govern agricultural input restrictions and processing chemical standards across European beet sugar operations. Industrial consequence includes mandatory substitution of certain liming agents and carbonation reagents with lower-toxicity alternatives. Infant nutrition and pharmaceutical excipient applications face heightened purity documentation requirements, with processors investing in analytical laboratory capacity.
Buyers are consolidating procurement around processors offering bundled carbon intensity certification and supply traceability. Large beverage manufacturers and industrial bakeries now require batch-level sustainability documentation, displacing spot-market purchasing. This pattern is most visible in Germany, where Nordzucker and Südzucker have invested in blockchain-anchored supply chain tracking systems.
Raw Beetroot Sugar Market Segmentation
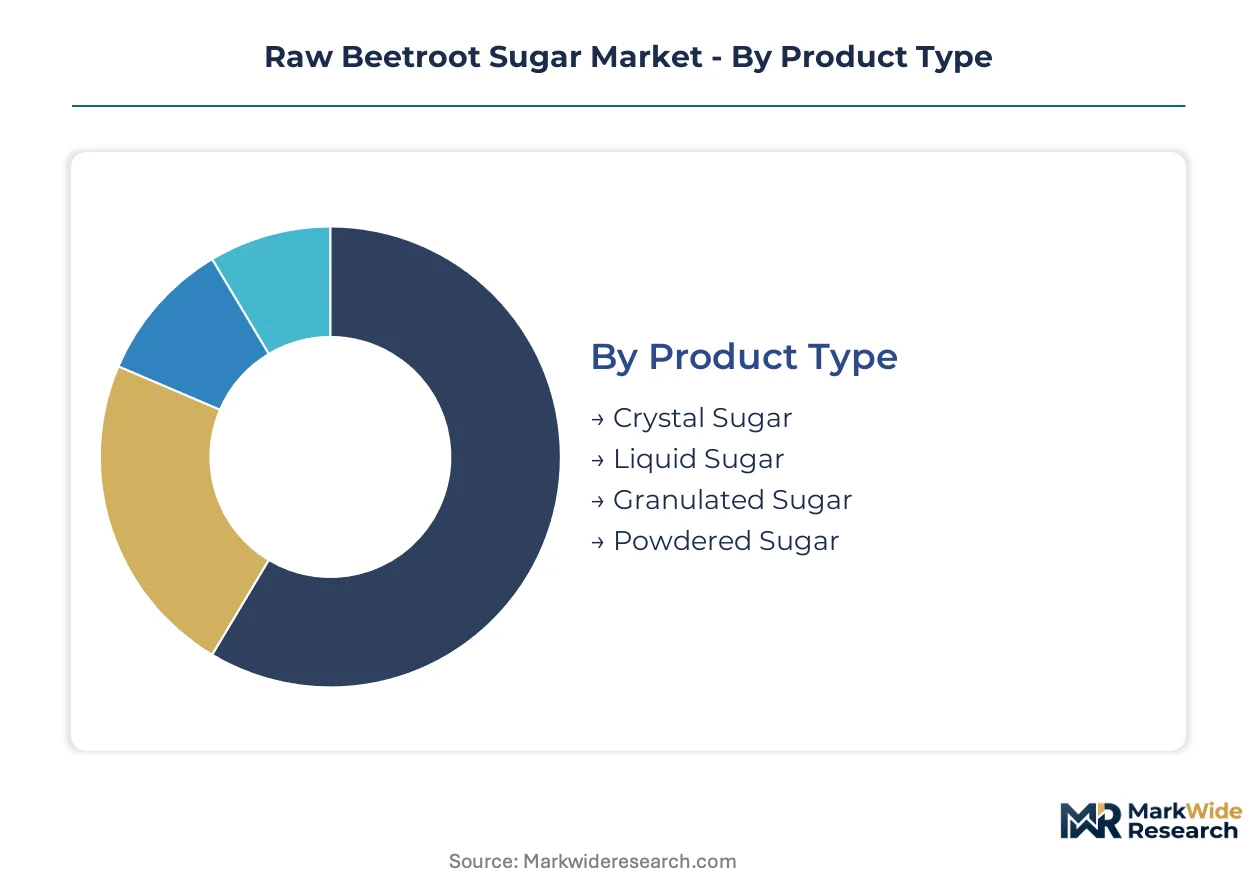
Raw beetroot sugar procurement patterns diverge sharply between bulk industrial channels and precision retail formats. Processors and manufacturers configure supply contracts around dissolution specifications, handling automation, and carbon certification tiers rather than commodity pricing alone.
Product Type:
Crystal formats integrate into standalone industrial systems requiring precise dissolution control, while liquid and powdered variants embed into automated production lines where handling efficiency dominates formulation decisions.
- Crystal Sugar:Sucrose crystallized to specific grain sizes enables controlled dissolution rates in beverage manufacturing. German beverage processors anchor procurement volumes here, driven by recipe recertification requirements that lock in consistent crystal specifications.
- Liquid Sugar:Pre-dissolved sucrose solutions eliminate crystallization handling in automated bakery lines. Polish and German industrial bakeries concentrate demand for this segment, prioritizing pumping efficiency and reduced labor over per-kilogram premiums.
- Granulated Sugar:Standard retail-grade crystals for consumer channels and small-scale food service.
- Powdered Sugar:Finely milled sucrose with anti-caking agents for confectionery dusting and rapid blend integration.
Volume placements concentrate in Crystal Sugar; the faster expansion belongs to Liquid Sugar.
End User:
Cost tier stratification separates commodity-scale buyers from premium-certified segments where EFSA purity documentation commands substantial contract premiums.
- Food Industry:Broad-spectrum processors of sauces, preserves, and prepared meals requiring bulk sucrose with consistent carbohydrate profiles. Eastern European manufacturing clusters drive procurement growth as production capacity shifts toward Poland and adjacent markets.
- Beverage Industry:Carbonated and still drink manufacturers with stringent dissolution-rate tolerances and carbon intensity certification requirements. German bottlers anchor this tier, leveraging blockchain-anchored supply traceability from Nordzucker and Südzucker processing networks.
- Bakery Sector:Industrial and artisanal bread and pastry producers with automated liquid sugar handling systems.
- Confectionery Manufacturers:Specialized sugar applications for candy, chocolate, and gum requiring precise thermal behavior and texture control.
Food Industry captures the largest procurement volumes; Beverage Industry claims the steepest expansion trajectory as cane sugar substitution accelerates.
Distribution Channel:
Supply concentration patterns favor wholesale and hypermarket channels where volume scale justifies dedicated logistics infrastructure and batch-level sustainability documentation.
- Wholesale Distributors:Bulk procurement aggregators serving industrial bakeries and beverage manufacturers with tanker and silo delivery systems. German and Polish distribution networks anchor regional supply security through processor partnerships.
- Hypermarkets:Large-format retail with private-label sugar lines and industrial-scale packaging. French cooperative sourcing networks through Tereos Group concentrate volume here, leveraging regional beet supply proximity.
- Supermarkets:Mid-scale retail channels with branded and standard-tier sugar offerings.
- Online Retail:Direct-to-consumer and small-business procurement with specialty and organic-certified sugar variants.
Wholesale Distributors command the heaviest volume flows; Online Retail is climbing the fastest as procurement digitization penetrates smaller manufacturing operations.
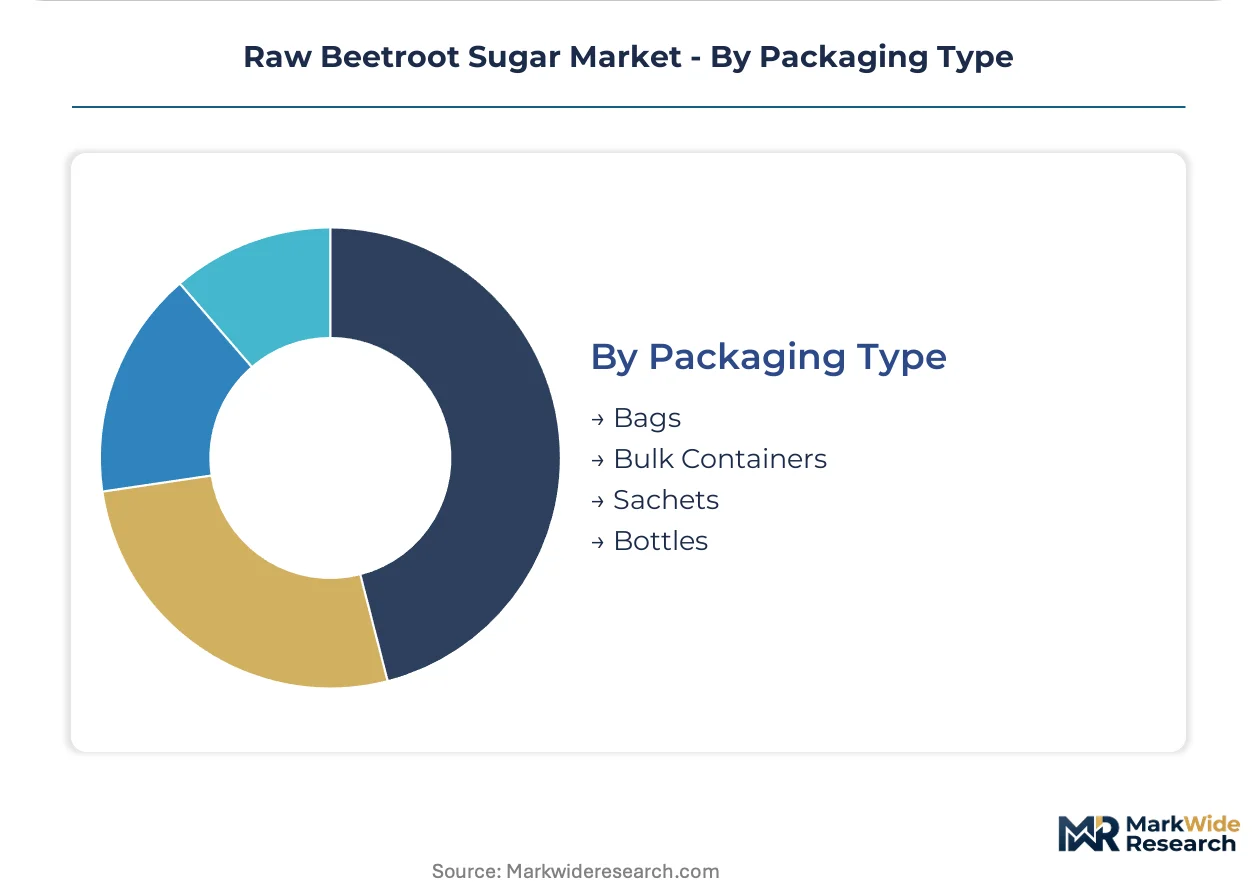
Packaging Type:
Customer type segmentation separates industrial tanker-fed operations from retail-dependent channels where packaging format directly determines shelf placement and handling economics.
- Bulk Containers:Industrial-scale silo and tanker deliveries for automated production lines with continuous sucrose feed systems. German coastal refining infrastructure through Nordzucker specializes in liquid bulk formats with refrigerated storage compliance.
- Bags:Standard 25-50kg woven polypropylene for mid-scale food manufacturers and food service distributors. Polish processing expansion favors bagged crystal output for eastern European manufacturing clusters.
- Sachets:Single-serve and small-format retail for hospitality and consumer convenience segments.
- Bottles:Liquid sugar dispensing formats for specialty bakery and confectionery applications.
Bulk Containers dominate industrial procurement; Bags retain the broadest geographic penetration across manufacturing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beet cultivation belts anchor regional processing capacity across temperate zones with suitable sowing calendars and established diffusion infrastructure. Climate adaptation is redrawing cultivation maps as traditional growing regions face calendar compression.
Germany
Südzucker AG and Nordzucker AG anchor continental processing capacity through integrated seed-to-refinery networks. The EU Green Deal's crop rotation incentives expand sowable acreage in Lower Saxony and Bavaria. Magdeburg and Hanover host specialized liquid sugar lines serving automated bakery production.
France
Tereos Group operates cooperative sourcing networks that secure regional beet supply security across Picardy and Champagne-Ardenne. REACH frameworks govern liming agent substitutions in processing plants. Lille and Reims concentrate refining infrastructure with carbon intensity certification capabilities.
Poland
Eastern expansion of beet cultivation exploits EU agricultural sustainability mandates for crop diversification. The country's national agricultural regulator oversees seed biotechnology trials for climate-adapted cultivars. Poznan and Wroclaw anchor greenfield processing capacity with proximity to expanding cultivation zones.
United Kingdom
British Sugar maintains coastal refining advantages with specialized infrastructure for pharmaceutical-grade output. EFSA sucrose purity benchmarks determine eligibility for infant nutrition supply chains. Norfolk and Suffolk host concentrated beet processing with blockchain-anchored traceability systems.
United States
American Crystal Sugar Company and Michigan Sugar Company serve industrial formulation demand across the Upper Midwest. The country's national agricultural regulator oversees beet seed certification programs. Minnesota and North Dakota concentrate cultivation with rail-linked bulk distribution to beverage manufacturers.
Raw Beetroot Sugar Market Competitive Landscape
Global majors compete with regional champions across processing scale and vertical integration depth. The vendor base clusters around three tiers: integrated European conglomerates with seed-to-refinery control, cooperative-backed regional processors with farmer-processor partnerships, and North American agricultural cooperatives with bulk commodity focus. Strategic moves center on membrane filtration technology licensing and eastern European capacity expansion.
Among German-based processors, Südzucker AG and Nordzucker AG exemplify the integrated conglomerate archetype with captive seed supply and multi-format output lines. Tereos Group represents the cooperative-backed model through its farmer-owned sourcing structure in France. These three entities anchor competitive positioning around carbon intensity certification and supply chain transparency investments that large beverage manufacturers now require.
| Leading Market Players |
|---|
| Südzucker AG |
| Nordzucker AG |
| Tereos Group |
| British Sugar |
| Cosun Beet Company |
| American Crystal Sugar Company |
| Michigan Sugar Company |
| Amalgamated Sugar Company |
| Pfeifer & Langen GmbH |
| Others |
Value Network & Pricing Analysis
German beverage manufacturers anchor procurement volumes through long-term offtake contracts, locking contract-based pricing that bundles carbon intensity certification with batch-level traceability documentation. This buyer concentration enables processors to command premiums for EFSA-compliant output while spot-market exposure concentrates in smaller Polish and French bakery operations.
Pricing Analysis
Warranty-equivalent service bundling separates contract tiers, with premium agreements covering refrigerated storage compliance and blockchain-anchored documentation against unbundled spot transactions. Three-tier pricing structure across certified pharmaceutical-grade, food-grade with carbon documentation, and standard industrial tiers reflects EFSA purity benchmarks and REACH chemical compliance investments. Cost compression in standard crystal grades intensifies as high-fructose corn syrup substitution threatens beverage formulation share. Industrial bakeries in Poland exhibit highest price sensitivity due to automated liquid sugar handling efficiency priorities, while German infant nutrition manufacturers accept substantial premiums for pharmaceutical-grade certification.
Supply Chain Analysis
Natural gas supply rests on Norwegian pipeline flows and LNG spot markets, governing diffusion and crystallization energy economics across German and Polish processing infrastructure. Seed biotechnology inputs draw from specialized Beta vulgaris breeders in Germany and Denmark, while ceramic membrane filtration components source from Japanese and German specialty engineering firms. Single-source vulnerability concentrates in coastal refining infrastructure facing EU F-Gas Regulation phase-down schedules for refrigeration-dependent storage. Distribution runs through processor-direct tanker networks for liquid sugar and wholesale distributor silo systems for crystal formats, with rail-linked bulk containers serving eastern European manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into seed biotechnology and carbon accounting certification infrastructure defines competitive positioning, as climate-adapted cultivars and documented low-carbon output determine market access under EU Green Deal mandates.
For Market Incumbents: Anticipate membrane filtration technology licensing wars by securing exclusive partnerships with ceramic and polymeric membrane engineering specialists before competitive diffusion optimization spreads. Defend against eastern European greenfield entrants by extending cooperative sourcing networks into Poland through farmer-processor equity partnerships that lock beet supply security. Prioritize EFSA certification laboratory capacity expansion to capture pharmaceutical excipient and infant nutrition premiums before regulatory timelines lengthen. For New Entrants and Emerging Players: Enter via liquid sugar automation partnerships with industrial bakery equipment manufacturers, embedding pre-dissolved sucrose solutions into pumping infrastructure specifications that create switching costs. Target Polish greenfield processing capacity with proximity to expanding beet cultivation zones in Poznan and Wroclaw corridors, exploiting EU agricultural sustainability mandates for crop diversification incentives. Pursue cooperative sourcing network structures that mirror Tereos Group's farmer-owned model to secure regional beet supply anchoring. For Investors and Strategic Acquirers: The window for entry favors seed biotechnology specialists with climate-adapted Beta vulgaris cultivar pipelines and membrane filtration engineering capabilities that enable compliance with tightening EU industrial emissions standards. Long-term viability hinges on carbon intensity certification infrastructure and blockchain-anchored traceability systems that large beverage manufacturers now require as procurement criteria. Watch EU F-Gas Regulation enforcement acceleration and EFSA sucrose purity benchmark revisions as inflection indicators that would reshape processing economics and certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Biotechnology | Climate-adapted Beta vulgaris cultivars from German and Danish breeders extend sowing calendars into marginal zones. |
| Membrane Filtration Technology Licensing | Ceramic and polymeric membrane deployment reduces liming agent loads under REACH substitution mandates. |
| Carbon Intensity Certification Infrastructure | Blockchain-anchored supply chain tracking from Nordzucker and Südzucker networks meets beverage manufacturer procurement requirements. |
| Eastern European Greenfield Capacity Expansion | Polish processing facilities in Poznan and Wroclaw capture proximity advantages to expanding beet cultivation belts. |
| Cooperative Sourcing Network Formation | Farmer-processor partnerships anchor regional beet supply security against spot-market price volatility exposure. |
Research Methodology
Document review covered EU agricultural subsidy databases, EFSA sucrose purity benchmark filings, and REACH chemical substitution guidance, complemented by interviews with beet processing plant managers, beverage manufacturer procurement directors, bakery automation equipment specialists, and agricultural cooperative board members. Secondary validation drew from customs trade data on beet sugar flows, SEC filings of publicly traded processors, national agricultural regulator seed certification records, and EU Green Deal implementation progress reports. Bottom-up volume estimates from cultivation acreage and processing capacity were triangulated against top-down demand projections from end-use industry consumption patterns.
Output projections span the analysis window across product type segmentation by crystal, liquid, granulated, and powdered formats; end-use segmentation by food industry, beverage industry, bakery sector, and confectionery manufacturers; and distribution channel segmentation by wholesale distributors, hypermarkets, supermarkets, and online retail. CAGRs were derived from regression analysis of historical cultivation yields, processing capacity utilization trends, and substitution elasticity estimates between beet sugar and cane sugar alternatives. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and EFSA certification timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price shock scenarios and accelerated high-fructose corn syrup substitution in beverage formulations. Projections reflect assumptions regarding EU Green Deal crop rotation incentive continuity and REACH chemical substitution enforcement intensity. A small set of named triggers warrants ongoing watch: membrane filtration technology cost curves, seed biotechnology cultivar approval velocities, and carbon intensity certification standard harmonization across member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Compressible Sugar Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Methyl Glucose Market
Sweeteners
Fructose Market
Sweeteners
Tagatose Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Saccharin Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
China Saccharin Market