
 Sugar Free Carbonated Drinks Market | 2026-2036
Sugar Free Carbonated Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Carbonated Drinks Market Outlook
Single-source sweetener procurement is decoupling from legacy supply agreements as brands diversify risk across multiple high-intensity sweetener suppliers. The Coca-Cola Company leverages its captive stevia cultivation partnerships to secure volume and price stability. PepsiCo anchors its zero-sugar portfolio through aspartame and sucralose dual-formulation flexibility. Red Bull GmbH specializes in smaller-batch monk fruit trials for premium energy positioning.
Sugar free carbonated drinks are non-alcoholic beverages produced by dissolving carbon dioxide in water, adding acidulants, flavoring agents, and high-potency sweeteners such as aspartame, sucralose, stevia glycosides, or monk fruit extract, typically yielding less than 0.5 grams of sugar per serving. These formulations serve commercial purposes across retail, foodservice, and vending channels where calorie reduction drives repeat purchase behavior. Cola variants still occupy the largest absolute volume position, though lemon-lime and ginger ale segments are expanding faster in health-store and online channels where clean-label positioning commands margin premiums. The stevia sweetener category leads in new product introductions, while aspartame sustains its cost advantage in mass-market supermarket placements.
FDA nutrition labeling requirements and the EPA's beverage container sustainability mandates shape product design and packaging decisions across the United States. The USDA's organic certification pathway creates a parallel premium tier for stevia and monk fruit formulations in health stores. Stakeholders must monitor evolving FDA positions on aspartame safety classifications and state-level sugar tax proposals that could either accelerate or complicate category growth trajectories.
Market Dynamics
Sweetener supply diversification is fragmenting procurement strategies as brands reduce dependence on single-source aspartame contracts and cultivate parallel stevia and monk fruit supplier relationships across multiple continents.
Growth Catalysts
- FDA Alternative Sweetener Guidance:The FDA's updated labeling framework for high-intensity sweeteners is accelerating clean-label reformulation investments across North American manufacturing facilities.
- Fitness Channel Expansion:Health-conscious millennials and Gen Z consumers are pulling zero-sugar carbonates into gym vending networks and wellness retail formats at accelerating velocity.
- Direct-to-Consumer Subscription Models:Digital-native beverage startups are bypassing traditional supermarket slotting fees through recurring delivery platforms that capture lifetime value data.
Market Restraints
- Aspartame Input Concentration:Three chemical manufacturers control the majority of high-purity aspartame supply, creating price volatility exposure for mass-market brands.
- Stevia Agricultural Risk:Stevia leaf cultivation concentrates in specific subtropical growing regions vulnerable to climate-induced yield fluctuations.
- EPA Container Mandates:The EPA's beverage packaging sustainability requirements are forcing capital-intensive line retrofits for rPET integration and lightweighting compliance.
Strategic Opportunities
- USDA Organic Certification Pathway:The USDA organic seal creates premium pricing power for stevia and monk fruit formulations in natural grocery channels.
- Foodservice Fountain Dispensing:Untapped white space exists in restaurant and cinema fountain systems where post-mix zero-sugar options remain underdeveloped.
- State-Level Sugar Tax Preemption:Proactive lobbying to shape municipal sugar tax frameworks before enactment creates regulatory certainty advantages.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise in high-intensity sweetener masking and acidulant balance commands premium compensation and extended recruitment cycles.
- Clean-Label Certification Timelines:Third-party non-GMO and organic verification processes extend new product launch windows by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Carbonated Drinks Market |
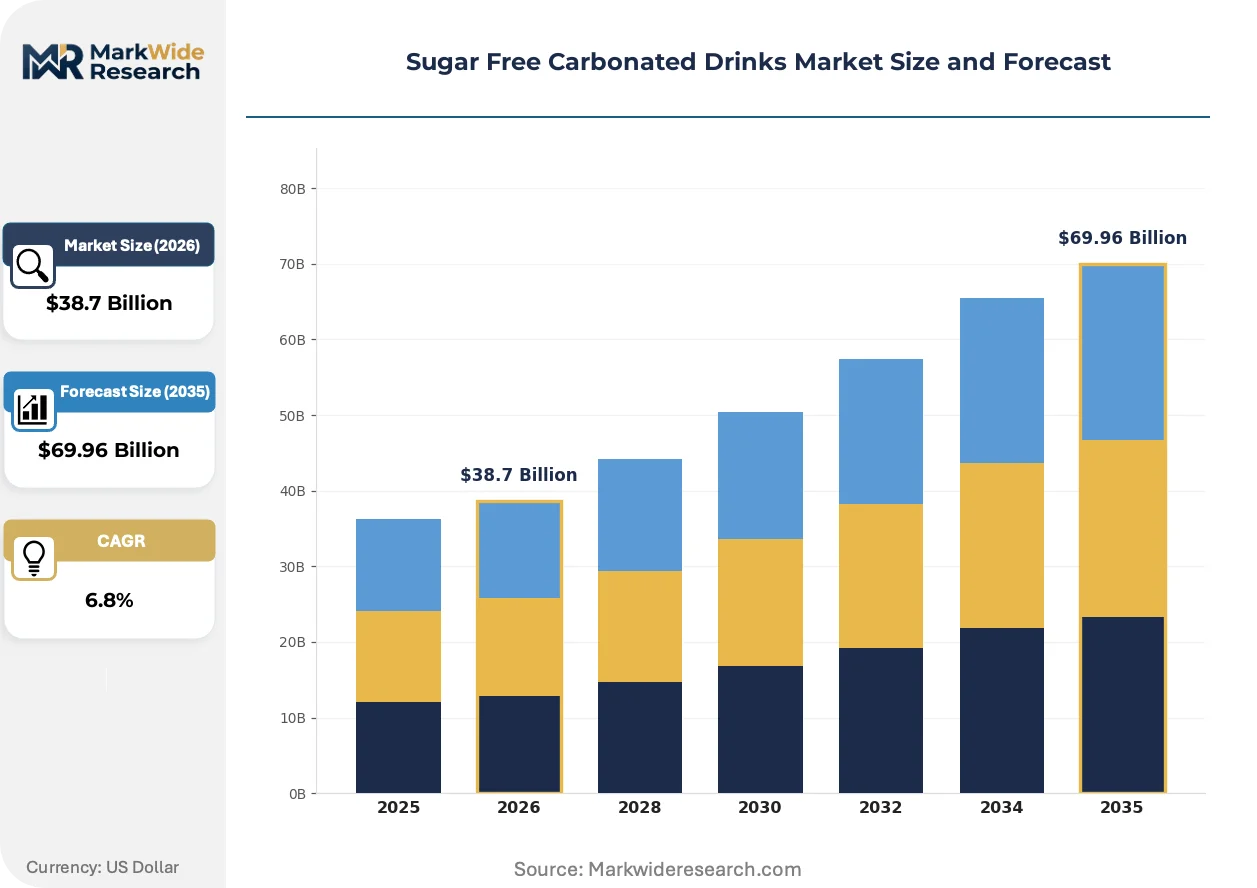
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cola, Lemon-Lime, Root Beer, Ginger Ale Sweetener Type: Stevia, Aspartame, Sucralose, Monk Fruit Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Stores Consumer Segment: Health Conscious, Diabetic Consumers, Fitness Enthusiasts, Budget Shoppers |
| Companies Covered | Monster Beverage Corporation, Nestlé Inc., The Coca-Cola Company, Britvic plc, Red Bull GmbH, PepsiCo Inc., Suntory Holdings Limited, Asahi Group Holdings Ltd., Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Carbonated Drinks Market Strategic Shifts
Reformulation chemistry is advancing faster than packaging innovation, with sweetener blends and natural flavor masking systems commanding disproportionate R&D investment relative to container sustainability.
Stevia glycoside purification technology is overtaking conventional extraction methods in premium product lines. Brands targeting health-store channels are adopting enzymatically modified stevia molecules that eliminate bitter aftertaste. This shift is compressing demand for traditional Reb-A extracts and forcing legacy suppliers to upgrade processing capabilities.
REACH chemical registration requirements in Europe are tightening purity specifications for imported high-intensity sweeteners. Manufacturers exporting to EU member states must demonstrate full supply chain transparency through extended safety data sheets. Carbonated beverage brands with European distribution are responding by qualifying secondary stevia suppliers with pre-registered substance dossiers.
Subscription-based replenishment is displacing impulse supermarket purchases among core zero-sugar consumers. Digital-native buyers in metropolitan US markets are locking into automated delivery schedules for multi-flavor variety packs. This behavioral pivot is most visible in coastal cities where direct-to-consumer fulfillment infrastructure achieves same-day delivery density.
Sugar Free Carbonated Drinks Market Segmentation
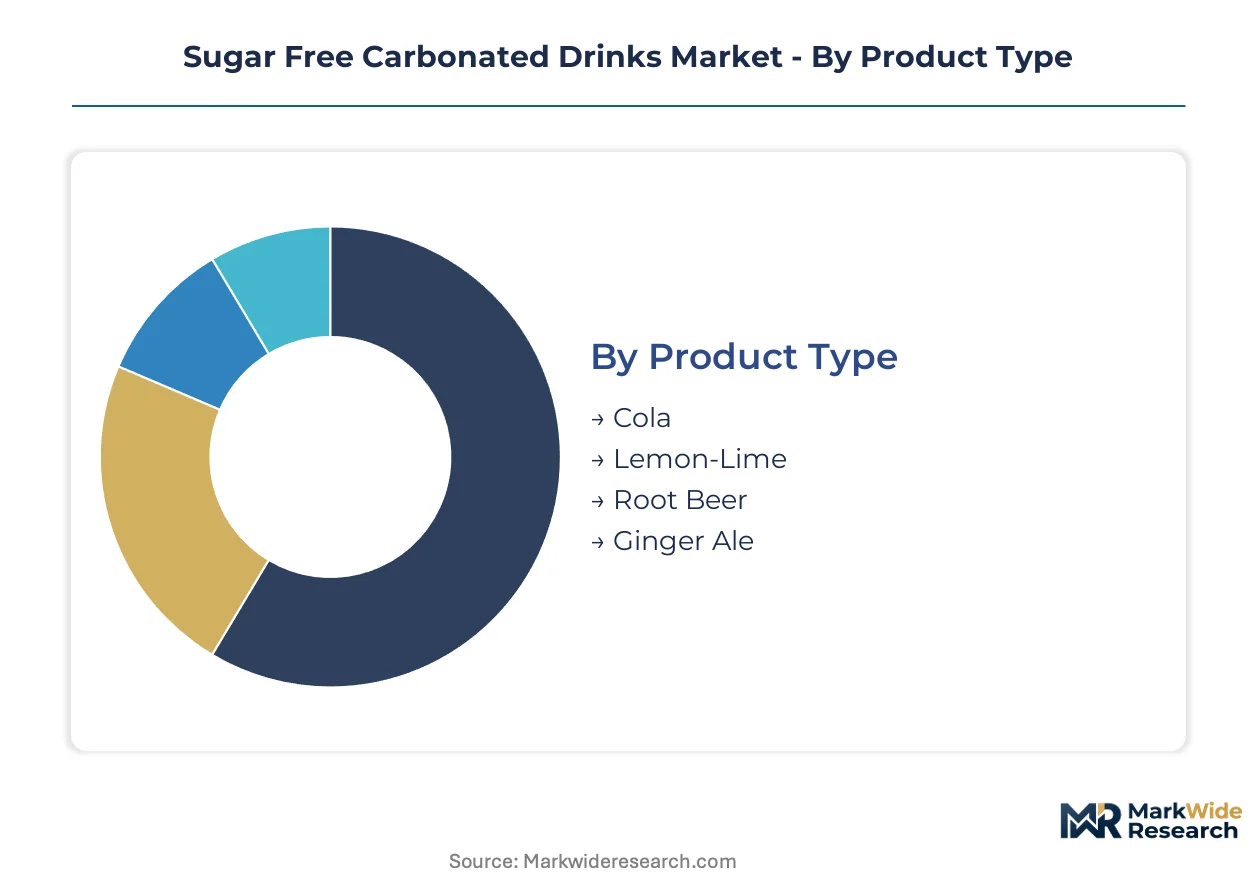
Sweetener chemistry and channel access define competitive position in zero-sugar carbonates. Formulation choices determine margin structure, while distribution format shapes customer acquisition economics and lifetime value.
Product Type:
Flavor profile drives repeat purchase frequency and brand loyalty more than calorie claims alone.
- Cola:Classic caramel-acid formulations with phosphoric acid and caffeine dominate absolute volume. United States supermarket placements anchor household penetration, though aging demographics in this segment create retention risk.
- Lemon-Lime:Citric acid-based clear formulations with citrus terpene flavor systems are expanding most quickly. Health-store channels in coastal United States cities pull this segment toward clean-label positioning with stevia and natural colorants.
- Root Beer:Wintergreen-sassafras flavor profiles with vanilla top notes serve nostalgic purchase occasions. Regional concentration in Midwest United States markets limits national scale.
- Ginger Ale:Ginger extract formulations with variable heat levels occupy mixer and wellness use cases. Premium pricing in foodservice fountain systems offsets lower retail velocity.
Volume sits with Cola; growth tilts toward Lemon-Lime.
Sweetener Type:
Input cost volatility and clean-label certification timelines segment procurement strategies across price tiers.
- Stevia:Purified glycoside extracts from Stevia rebaudiana leaf deliver zero-calorie sweetness with USDA organic pathway eligibility. Enzymatically modified Reb-M molecules eliminate bitter aftertaste in premium United States health-store placements.
- Aspartame:Methyl ester dipeptide compounds maintain cost advantage in mass-market supermarket channels. FDA safety classification reviews create regulatory overhang for brands dependent on this input.
- Sucralose:Chlorinated sucrose derivatives provide thermal stability for fountain and vending applications. Dual-formulation flexibility with aspartame hedges supply concentration risk.
- Monk Fruit:Mogroside V extracts from Siraitia grosvenorii support premium energy positioning with natural positioning claims. Limited cultivation in subtropical China regions constrains volume scaling.
Cost position favors Aspartame; certification and margin expansion favor Stevia.
Distribution Channel:
Channel selection determines slotting fee exposure, data capture depth, and subscription economics.
- Supermarkets:Traditional grocery retail with high-frequency foot traffic and established planogram slots. United States mass-market brands defend shelf space through trade spending and promotional calendars.
- Online Retailers:Direct-to-consumer platforms with automated replenishment and variety-pack configurations. Same-day delivery density in metropolitan United States markets reduces churn.
- Convenience Stores:Impulse-oriented cold vault placements with single-serve pricing. Traffic patterns tied to fuel and tobacco purchases limit health-positioned SKU success.
- Health Stores:Curated natural grocery formats with educated staff and clean-label filtration. USDA organic and non-GMO verification requirements extend onboarding timelines.
Transaction volume concentrates in Supermarkets; customer lifetime value concentrates in Online Retailers.
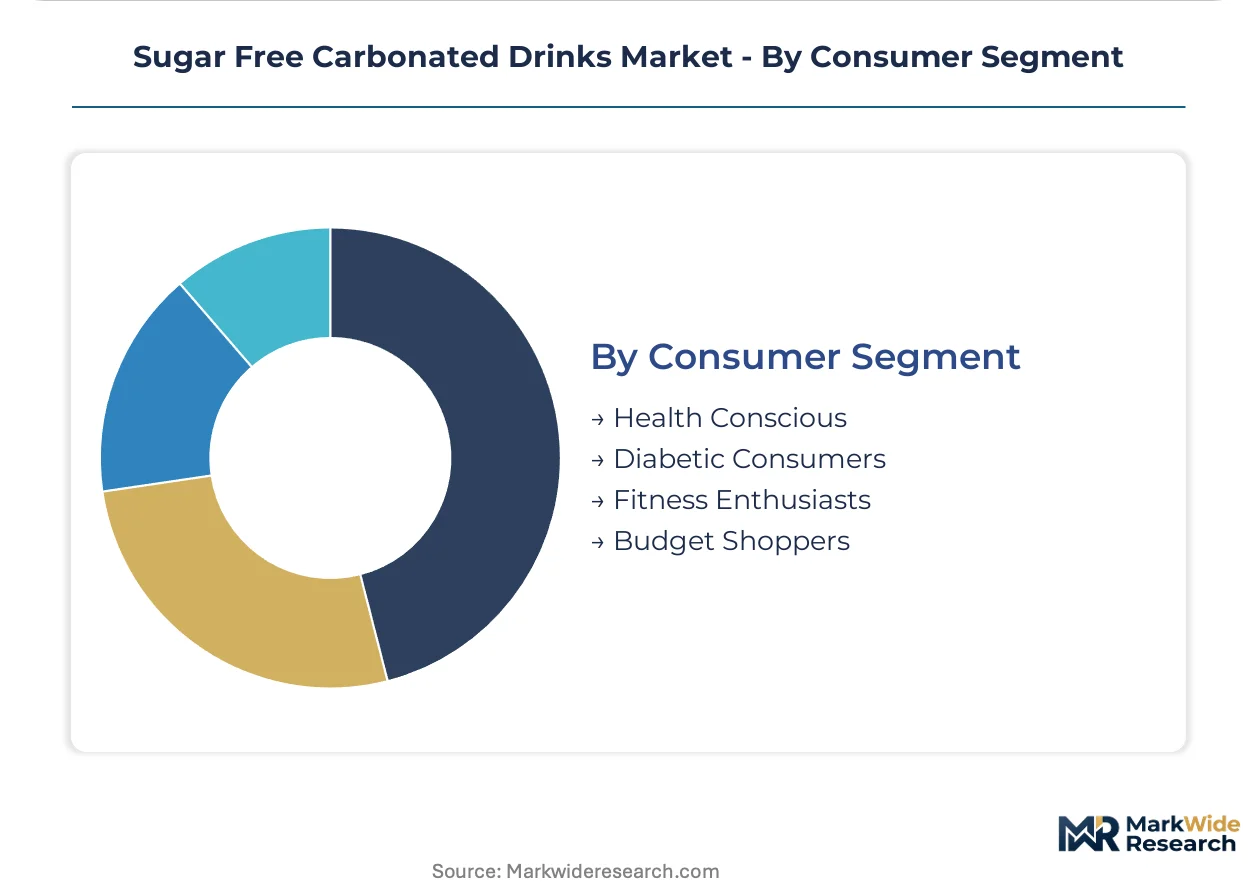
Consumer Segment:
Health motivation intensity and price sensitivity partition addressable market into distinct value propositions.
- Health Conscious:Broad wellness-motivated buyers prioritizing ingredient transparency and clean labels. United States coastal metropolitan markets show highest per-capita consumption.
- Diabetic Consumers:Medically necessitated zero-sugar adherence with glycemic control requirements. Physician and dietitian recommendation channels drive trial.
- Fitness Enthusiasts:Gym-adjacent consumption with performance and recovery framing. United States fitness channel expansion pulls carbonates into vending networks previously dominated by sports drinks.
- Budget Shoppers:Price-driven purchase decisions with private-label acceptance. Mass-market supermarket promotions and multi-pack discounts capture this cohort.
Spend per transaction peaks with Fitness Enthusiasts; population scale peaks with Health Conscious.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia leaf cultivation concentrates in Paraguay and China, anchoring raw material flows for zero-sugar carbonation. Alternative sweetener processing clusters in the United States and Germany convert agricultural inputs into beverage-grade ingredients. Finished product manufacturing distributes across North American, European, and Asian metropolitan markets where health-conscious consumption accelerates.
United States
Fitness channel expansion and direct-to-consumer subscription models drive category velocity in coastal metropolitan markets. FDA alternative sweetener labeling guidance shapes reformulation timelines across North American manufacturing facilities. Atlanta and Chicago anchor concentrate production and flavor chemistry R&D for mass-market zero-sugar portfolios.
Germany
REACH chemical registration requirements tighten purity specifications for imported high-intensity sweeteners entering EU distribution networks. EFSA safety assessments influence aspartame and stevia glycoside formulation choices across continental beverage operations. Bavaria hosts advanced extraction technology providers serving enzymatically modified stevia purification for premium health-store channels.
China
Monk fruit cultivation in Guangxi Zhuang Autonomous Region supplies mogroside V extracts for premium energy positioning in Asian and export markets. SAMR food additive regulations govern high-intensity sweetener approval pathways and label claim verification. Yangtze River Delta manufacturing clusters integrate stevia processing with carbonated beverage contract production for domestic and international brands.
Japan
Aging demographics and diabetic consumer segments sustain steady per-capita consumption of zero-sugar carbonates in convenience and pharmacy channels. METI industrial standards guide beverage container lightweighting and rPET integration compliance timelines. Kanto region Tokyo-Osaka corridor concentrates formulation R&D for clean-label stevia and monk fruit blends targeting health-conscious urban professionals.
Brazil
Private-label expansion in supermarket channels captures price-sensitive consumers shifting from full-sugar carbonates. ANVISA food additive regulations structure high-intensity sweetener import and domestic manufacturing compliance requirements. São Paulo state anchors South American beverage production infrastructure with integrated flavor compounding and aseptic filling capabilities for zero-sugar line extensions.
Sugar Free Carbonated Drinks Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbent beverage conglomerates and specialty energy drink manufacturers reposition around sweetener chemistry differentiation. Market structure consolidates around three to four multinational holding companies with diversified refreshment portfolios, supplemented by focused energy specialists and regional bottling networks. Strategic archetypes include captive agricultural integration players, dual-formulation flexibility specialists, and digital-native subscription brands. Competitive moves concentrate on M&A for niche sweetener technology access and capacity expansion for enzymatically modified stevia processing.
Within the multinational beverage tier, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven archetypes with diversified zero-sugar portfolios spanning cola, lemon-lime, and flavored variants. Red Bull GmbH occupies a premium energy specialist position emphasizing smaller-batch monk fruit trials for differentiated positioning. Among Japanese beverage conglomerates, Suntory Holdings Limited represents Asia-Pacific market anchoring with integrated distribution across multiple sweetener formulation tiers.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| Nestlé Inc. |
| The Coca-Cola Company |
| Britvic plc |
| Red Bull GmbH |
| PepsiCo Inc. |
| Suntory Holdings Limited |
| Asahi Group Holdings Ltd. |
| Keurig Dr Pepper Inc. |
| Others |
Value Chain & Pricing Dynamics
Flavor chemist talent concentration in the Chicago-Atlanta corridor drives labor-cost differentials that widen pricing-tier spreads between mass-market aspartame formulations and premium stevia blends.
Pricing Analysis
After-sales service bundling separates contract-manufacturing arrangements from unbundled spot purchases of high-intensity sweetener inputs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with USDA organic and non-GMO verification commanding margin premiums. Price erosion runs through the aspartame-dependent mass-market tier as private-label entrants compress shelf-price positioning. Budget shoppers exhibit highest price sensitivity, while fitness enthusiasts and diabetic consumers show lowest elasticity due to health-motivated purchase drivers.
Supply Chain Analysis
Dual-sourcing requirements from PepsiCo and Coca-Cola procurement teams mandate multi-supplier qualification for stevia glycosides across Paraguay, China, and Kenya cultivation zones. Raw material dependencies center on stevia leaf extracts, aspartame methyl ester compounds, and monk fruit mogroside V concentrates. Single-source vulnerability concentrates in the three-manufacturer aspartame synthesis segment. Distribution runs through integrated beverage concentrate networks, regional bottling cooperatives, and direct-to-consumer fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar-free carbonated drinks sector sits in a sweetener-technology transition phase, with enzymatically modified stevia glycosides displacing legacy Reb-A extracts and aspartame-dependent formulations.
For Market Incumbents: Deepen backward integration into stevia cultivation partnerships to lock in organic-certified supply volumes before competitor land-bank accumulation accelerates. Expand in-house flavor chemistry R&D capacity in the Atlanta corridor to reduce reliance on scarce external talent. Defend against digital-native subscription entrants by capturing same-day delivery density in coastal metropolitan markets through owned fulfillment infrastructure. For New Entrants and Emerging Players: Enzymatically modified stevia purification technology offers a technology-first wedge against incumbent cost advantages in mass-market channels. Target foodservice fountain dispensing systems as the most penetrable white space, where post-mix zero-sugar options remain underdeveloped relative to retail saturation. Pursue health-store channel entry with USDA organic certification as the lead go-to-market credential, leveraging extended onboarding timelines as competitive moat against fast-follower replication. For Investors and Strategic Acquirers: The window for entry favors specialty stevia extraction technology providers with pre-registered EU REACH dossiers and enzymatic modification capabilities. Long-term viability hinges on positioning upstream of formulation R&D bottlenecks rather than downstream brand aggregation. Watch FDA aspartame safety classification reviews as the critical inflection signal that would accelerate capital reallocation toward natural sweetener infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Stevia Modification Investment | Purification technology eliminates bitter aftertaste, unlocking health-store premium pricing. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures lifetime value data and bypasses supermarket slotting fees. |
| USDA Organic Certification Pathway | Organic seal creates pricing power in natural grocery channels with educated staff filtration. |
| Foodservice Fountain System Expansion | Post-mix zero-sugar penetration in restaurants and cinemas addresses underdeveloped white space. |
| Dual-Sweetener Formulation Flexibility | Aspartame-sucralose blending hedges supply concentration risk from three-manufacturer dominance. |
Study Parameters
Multi-period observation of sweetener procurement contracts, new product launch velocities, and channel shift indicators anchored the trend analysis, supplemented by interviews with beverage formulation chemists, category buyers at health-store retailers, supply chain directors at multinational concentrate producers, and regulatory affairs specialists at FDA-focused consultancies. Secondary validation drew from FDA guidance document archives, EPA beverage container mandate filings, USDA organic certification databases, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Input-output matrices mapped sweetener input costs through formulation tiers to finished-product price positioning across distribution channels. Segmentation dimensions modeled include flavor profile, sweetener chemistry type, distribution format, and consumer health motivation intensity. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted price evolution. Industry-specific forecast inputs incorporated FDA regulatory timeline probabilities and climate-induced yield fluctuation scenarios for subtropical stevia cultivation zones.
Several conditions sit outside the modeled scope, including state-level sugar tax enactment timing, breakthrough natural sweetener approvals beyond stevia and monk fruit, and abrupt shifts in consumer clean-label preference intensity. Forecasts reflect documented assumptions about regulatory stability and agricultural yield continuity. Deviation in FDA aspartame safety classification or EPA packaging mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market