
 Global Low Intensity Sweeteners Market | 2026-2036
Global Low Intensity Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Intensity Sweeteners Market Outlook
The capital-intensity divergence between integrated fermentation specialists and commodity importers is collapsing as bioprocess yields improve and capex requirements fall. Südzucker AG leverages its beet-sugar infrastructure to anchor European supply of polyol sweeteners. Tate & Lyle plc competes through specialty starch and sweetener formulation expertise in North American beverage applications. Cargill sustains global origination networks that control agricultural feedstock costs for its erythritol and stevia operations.
Low intensity sweeteners are non-caloric or reduced-calorie sugar substitutes typically delivering sweetness potency below that of sucrose, often manufactured through fermentation, enzymatic conversion, or extraction from botanical sources such as stevia rebaudiana leaves. These compounds serve primarily to reduce added sugars in processed foods and beverages while maintaining palatability and functional properties like bulking and browning. The stevia segment leads volume growth as clean-label demand from beverage producers outpaces synthetic alternatives, while sucralose occupies mature, cost-sensitive applications in confectionery where thermal stability requirements dominate formulation decisions. Powder and granulated forms capture the majority of industrial procurement given handling efficiency in high-throughput food manufacturing, though liquid concentrates are gaining share in dairy product applications requiring homogeneous dispersion.
The FDA governs sweetener safety through GRAS determinations and food additive petitions, while the EMA and EFSA jointly influence European market access through novel food approvals and purity specifications that filter supplier eligibility. The EU's Farm to Fork Strategy tightens contaminant thresholds and traceability requirements, forcing upstream investment in extraction and purification infrastructure. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and calibrate R&D portfolios between natural-extraction and fermentation-derived platforms before regulatory divergence hardens into separate technical standards.
Market Dynamics
Formulation mandates from EU Nutri-Score labeling and FDA nutrition panel updates are forcing simultaneous reformulation across beverage, bakery, and dairy categories, compressing supplier qualification timelines and rewarding integrated fermentation platforms over commodity traders.
Growth Catalysts
- Clean-label beverage reformulation:Major soft drink bottlers in Germany and the United States are replacing synthetic high-intensity sweeteners with stevia glycosides to meet retailer procurement standards.
- Fermentation yield improvements:Bioprocess advances in erythritol and allulose production are collapsing unit economics and expanding food-grade availability beyond pharmaceutical-grade legacy supply.
- EU Farm to Fork Strategy:Contaminant threshold tightening and full-chain traceability requirements are disqualifying non-compliant importers and consolidating procurement around vertically integrated European producers.
Market Restraints
- Feedstock cost volatility:Beet sugar and corn dextrose prices fluctuate with climate-driven harvest variability, compressing polyol sweetener margins for non-captive processors.
- Upstream supply concentration:Stevia leaf extraction capacity concentrates in Chinese processing clusters, creating single-source vulnerability for Western formulators seeking GRAS or novel food compliance.
- Thermal stability limitations:Rebaudioside A degrades under standard confectionery baking temperatures, restricting clean-label penetration in industrial cookie and cracker applications.
Strategic Opportunities
- Underpenetrated Indian food processing:FSSAI approval acceleration for stevia and monk fruit extracts opens reformulation pathways in India's branded dairy and traditional sweets sectors.
- Precision fermentation platforms:Convergence of synthetic biology and enzymatic glycosylation enables rare steviol glycoside production without agricultural cultivation.
- Direct-to-manufacturer liquid concentrates:Dairy processors in France and Italy are bypassing distributor networks for bulk tanker deliveries of high-concentration monk fruit solutions.
Industry Challenges
- Novel food approval timelines:EFSA safety dossier reviews for emerging sweeteners extend 18-36 months, freezing pipeline commercialization and consuming regulatory affairs bandwidth.
- Cross-functional formulation expertise scarcity:Food technologists capable of balancing bulking, browning, and sweetness intensity in reduced-sugar bakery systems command premium compensation and limited availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Intensity Sweeteners Market |
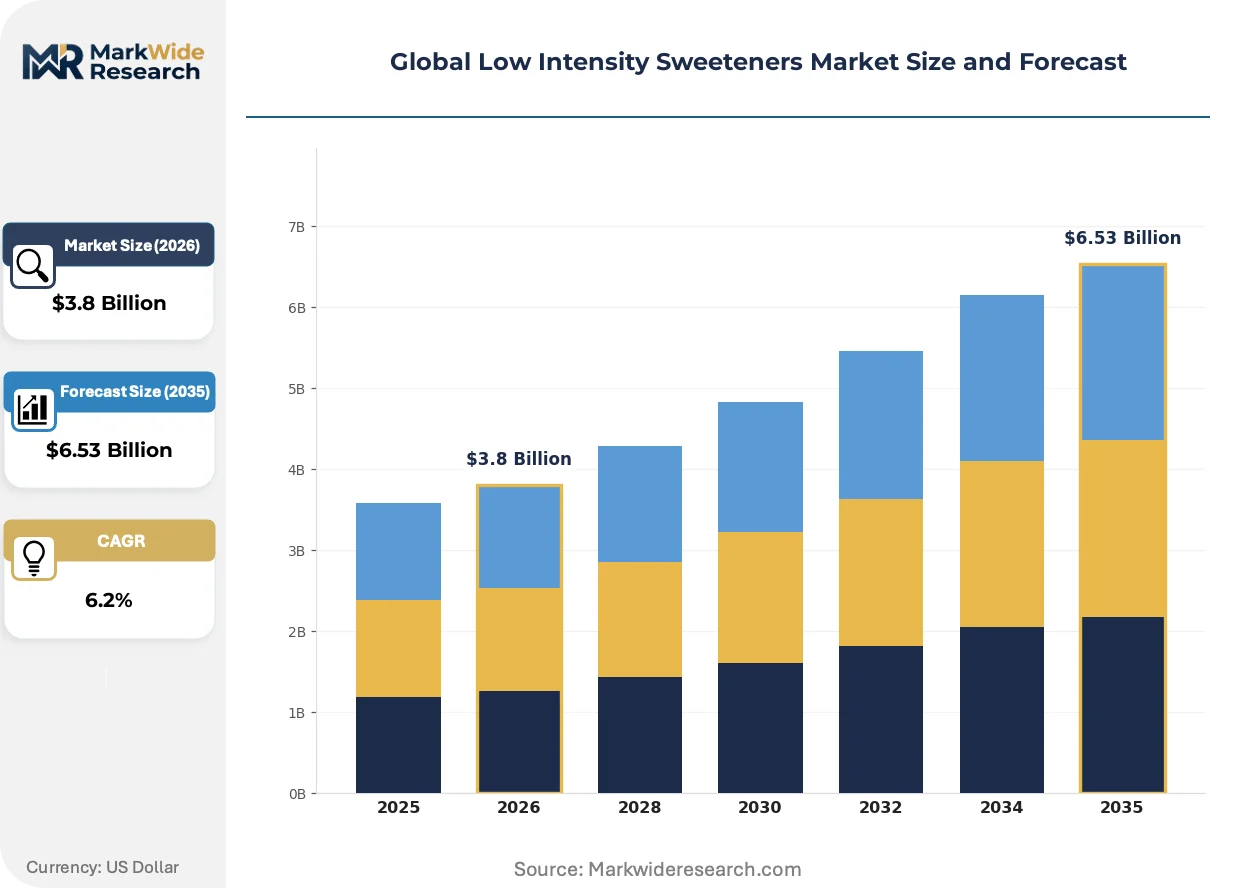
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acesulfame K, Aspartame, Sucralose, Stevia Application: Beverages, Dairy Products, Bakery, Confectionery End User: Food Manufacturers, Beverage Producers, Retailers, Personal Care Form: Powder, Liquid, Granulated, Tablet |
| Companies Covered | Roquette Frères, Südzucker AG, Ingredion Incorporated, Samyang Corporation, Whole Earth Brands, Archer Daniels Midland Company, Cargill, Hylen Co Ltd, Tate & Lyle plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Intensity Sweeteners Market Strategic Shifts
Bioprocess engineering and regulatory data requirements are converging to reward manufacturers with in-house analytical capabilities and captive agricultural supply, while punishing traders dependent on spot-market feedstock procurement.
Enzymatic glycosylation of steviol precursors is supplanting traditional leaf-extraction methods for rebaudioside M and D production. North American beverage formulators are adopting these fermentation-derived glycosides at accelerating rates to achieve clean-label positioning without the bitter aftertaste associated with legacy stevia extracts. This technology is compressing demand for Chinese leaf-processing capacity and reshaping supplier qualification criteria toward biotech-platform capabilities.
REACH substance registration expansions and EFSA purity specification updates are tightening residual solvent limits for extraction-based sweeteners. European ingredient distributors are rejecting non-compliant Asian supply lots and redirecting procurement toward fermentation-certified European production. Bakery and confectionery segments with complex thermal processing requirements face the steepest compliance cost escalations.
Long-term offtake contracting is displacing spot-market purchasing among multinational beverage and dairy processors. Tier-one formulators in Germany and the United States are locking three-to-five-year supply agreements with fermentation specialists to secure volume and hedge against novel food approval delays. This behavioral shift concentrates procurement leverage among integrated producers with demonstrated regulatory track records and certified capacity expansion pipelines.
Global Low Intensity Sweeteners Market Segmentation
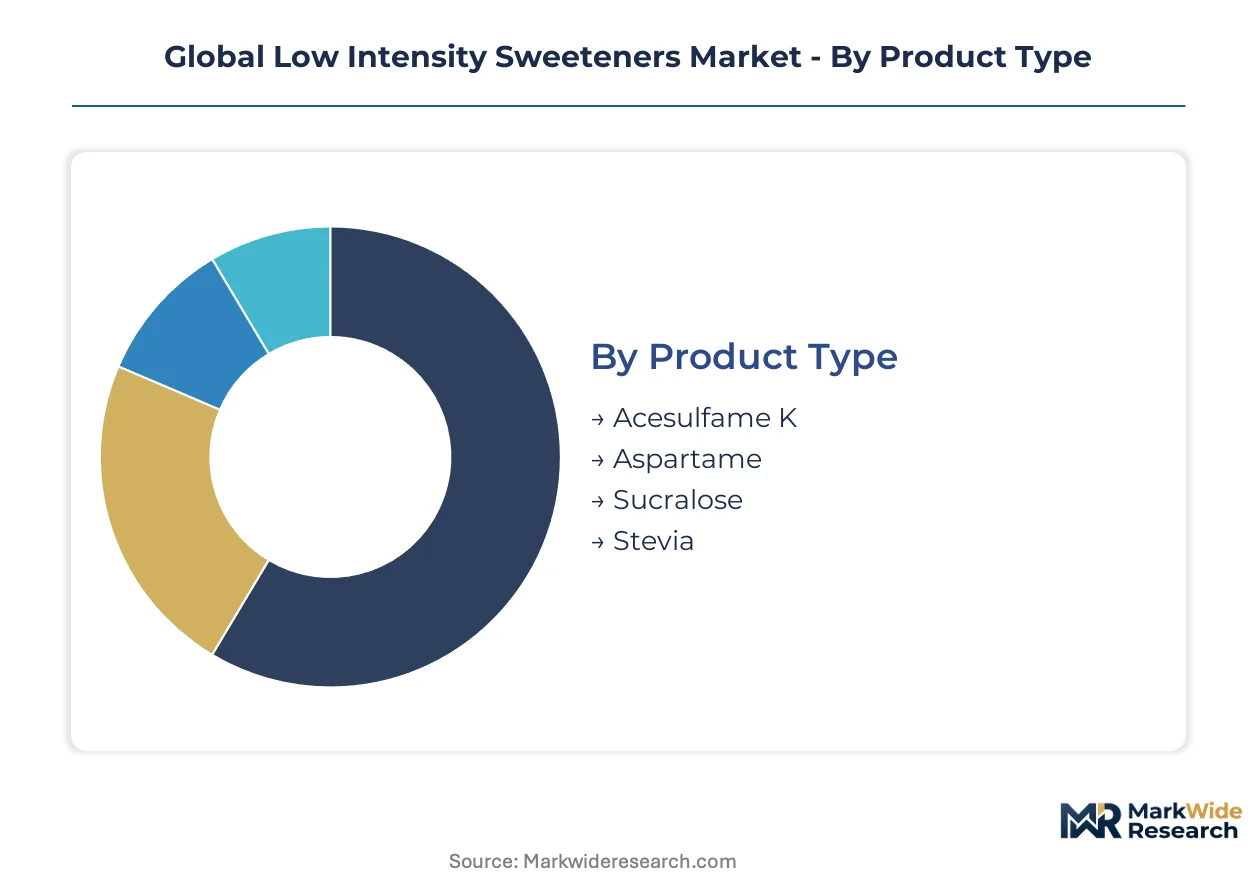
Sweetener procurement channels diverge sharply by physical form and end-use specifications. Industrial buyers route bulk powder through distributor networks while beverage formulators increasingly source liquid concentrates direct from fermentation specialists.
Product Type:
Channel strategy varies by production platform — fermentation-derived polyols flow through integrated supplier relationships while extraction-based botanicals concentrate in specialty distributor networks.
- Stevia:Glycoside blends extracted from stevia rebaudiana leaves deliver clean-label positioning for beverage reformulation in Germany and the United States. Demand concentrates in soft drink bottlers replacing synthetic high-intensity alternatives to meet retailer procurement standards, though thermal degradation limits penetration in baked applications.
- Sucralose:Chlorinated disaccharide manufactured through selective substitution of sucrose hydroxyl groups provides exceptional thermal stability for confectionery processing. Cost-sensitive manufacturers in mature markets favor this segment where heat tolerance dominates formulation decisions over label claims.
- Acesulfame K:Synthetic oxathiazinone compound serving stable sweetness in acidic beverage matrices.
- Aspartame:Dipeptide methyl ester restricted to non-thermal applications by phenylalanine labeling requirements.
Sucralose dominates installed base in heat-processed categories. Stevia is where expansion concentrates as clean-label mandates accelerate across North American and European beverage portfolios.
Application:
Margin structure inverts across categories — beverage applications reward volume scale while bakery and confectionery demand formulation expertise premiums.
- Beverages:Carbonated soft drinks, flavored waters, and functional drinks constitute the primary absorption channel for low-intensity sweetener volume. German private-label reformulation and U.S. bottler portfolio shifts are compressing supplier qualification timelines and favoring fermentation platforms with regulatory track records.
- Bakery:Reduced-sugar bread, cakes, and pastries require complex bulking agent systems to compensate for sucrose's functional contributions beyond sweetness. Industrial bakery modernization in Germany is outpacing other national markets as EU Nutri-Score labeling forces simultaneous reformulation across product lines.
- Dairy Products:Yogurt, ice cream, and flavored milk applications favoring homogeneous dispersion of liquid concentrate formats.
- Confectionery:Hard candies and chewing gums where thermal stability and crystallization control determine sweetener selection.
Beverages capture volume concentration. Bakery is climbing the fastest as labeling mandates force reformulation across European industrial production.
End User:
Procurement leverage concentrates among multinational formulators with captive technical capabilities, while smaller food manufacturers remain dependent on distributor intermediaries.
- Food Manufacturers:Industrial bakery, snack, and prepared food producers sourcing bulk powder and granulated formats through high-throughput manufacturing channels. These buyers prioritize handling efficiency and lot-to-lot consistency over unit cost minimization.
- Beverage Producers:Soft drink bottlers and dairy processors with direct supplier relationships and long-term offtake contracting. Tier-one formulators in Germany and the United States are locking three-to-five-year supply agreements to hedge against novel food approval delays.
- Retailers:Private-label brand owners specifying sweetener systems for contract manufacturers.
- Personal Care:Oral care and cosmetic formulators utilizing sweetness for palatability masking in non-food applications.
Beverage producers command procurement leverage through volume concentration. Food manufacturers represent the deepest expansion opportunity as reformulation mandates extend beyond beverages.
Form:
Physical format selection tracks manufacturing infrastructure — legacy powder handling systems dominate established production while liquid dosing equipment enables concentrate adoption.
- Powder:Spray-dried and crystalline formats optimized for pneumatic conveying and bulk storage in high-throughput food manufacturing. Majority of industrial procurement flows through this channel given established handling infrastructure and dust-control protocols.
- Liquid:Aqueous and solvent-based concentrates enabling precise dosing and homogeneous dispersion in dairy and beverage applications. French and Italian dairy processors are bypassing distributor networks for bulk tanker deliveries of high-concentration solutions.
- Granulated:Free-flowing agglomerated particles for table-top and small-batch food service applications.
- Tablet:Compressed single-serve formats for consumer retail and food service portion control.
Powder dominates installed manufacturing base. Liquid is gaining share fastest as dairy processors retrofit dosing infrastructure for concentrate delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between German fermentation specialists and Chinese extraction clusters is reshaping procurement leverage across the value chain. Western formulators pay premiums for regulatory-compliant supply while Asian processors absorb compliance cost escalations.
United States
Soft drink bottlers in Atlanta and Chicago are accelerating stevia glycoside adoption to meet retailer clean-label standards. The FDA's updated nutrition facts panel mandates added sugar disclosure, compressing reformulation timelines. California dairy processors in the Central Valley are retrofitting liquid concentrate dosing infrastructure for monk fruit solutions.
Germany
Private-label reformulation and industrial bakery modernization in Bavaria and North Rhine-Westphalia are outpacing other national markets. The EU's Nutri-Score labeling requirements force simultaneous portfolio shifts across beverage and baked goods categories. Hamburg anchors European polyol distribution through integrated beet-sugar infrastructure.
China
Stevia leaf extraction capacity concentrates in processing clusters serving Western formulators seeking GRAS compliance. The country's national food safety regulator tightens contaminant thresholds for export-oriented production. Yangtze River Delta facilities face margin compression from REACH-aligned purity specification upgrades.
France
Dairy processors in Normandy and Brittany are bypassing distributor networks for bulk tanker deliveries of high-concentration sweetener solutions. EFSA novel food approval timelines freeze pipeline commercialization for emerging fermentation-derived glycosides. The Paris Basin concentrates formulation R&D for reduced-sugar yogurt and ice cream applications.
India
FSSAI approval acceleration for stevia and monk fruit extracts opens reformulation pathways in branded dairy and traditional sweets sectors. Maharashtra food manufacturers in Mumbai-Pune corridor pilot clean-label bakery systems. Gujarat processing hubs expand extraction capacity for domestic and export-grade botanical sweetener supply.
Global Low Intensity Sweeteners Market Competitive Environment
Concentration sits with integrated fermentation specialists controlling captive agricultural feedstock and regulatory track records. The supplier base stratifies between bioprocess platforms with certified capacity expansion pipelines and commodity traders dependent on spot-market procurement. Three archetypes dominate: beet-sugar infrastructure owners, specialty starch formulators, and global origination networks. Competitive moves center on long-term offtake contracting and backward integration into extraction and purification infrastructure.
Within the integrated infrastructure tier, Südzucker AG and Tate & Lyle plc exemplify divergent platform strategies. Südzucker leverages Central European beet-sugar assets to anchor polyol supply security. Tate & Lyle occupies a position in North American beverage formulation expertise. Cargill represents the global origination archetype, with agricultural feedstock control spanning multiple continents and downstream erythritol operations.
| Leading Market Players |
|---|
| Roquette Frères |
| Südzucker AG |
| Ingredion Incorporated |
| Samyang Corporation |
| Whole Earth Brands |
| Archer Daniels Midland Company |
| Cargill |
| Hylen Co Ltd |
| Tate & Lyle plc |
| Others |
Value Chain & Pricing Dynamics
REACH substance registration expansions and EFSA purity specification updates gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant Asian processors while rewarding European fermentation platforms with certified analytical capabilities. Buyers now segment procurement across certification tiers that carry distinct premium structures.
Pricing Analysis
Configured-to-order pricing for rare steviol glycosides commands substantial premiums over standard rebaudioside A extracts. Long-term offtake contracting dominates the pricing model among multinational beverage processors, with price differentiation driven by EFSA novel food compliance status and volume scale commitments. Pricing pressure stems from bioprocess yield improvements in erythritol and allulose that collapse unit economics for legacy extraction methods. Beverage producers show lowest price sensitivity given reformulation mandates, while industrial bakery manufacturers face acute cost compression from simultaneous Nutri-Score compliance requirements.
Supply Chain Analysis
Strategic stockpiling of stevia leaf inventory dominates procurement behavior among Western formulators seeking to hedge against Chinese processing cluster disruptions. Raw material supply concentrates in China for leaf extraction, Germany for beet-sugar derived polyols, and the United States for corn-based erythritol feedstock. The chain draws from agricultural commodities—beet sugar, corn dextrose, and stevia leaves—that fluctuate with climate-driven harvest variability. Single-source vulnerability in Yangtze River Delta extraction capacity constitutes the primary structural risk. Distribution runs through integrated fermentation specialists for tier-one formulators, while specialty distributor networks serve smaller food manufacturers lacking direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement leverage is concentrating among multinational beverage and dairy processors capable of locking multi-year supply agreements, fragmenting competitive position for smaller formulators dependent on spot-market access.
For Market Incumbents: Shield market position by accelerating backward integration into extraction and purification infrastructure ahead of EFSA contaminant threshold tightening. Prioritize certification investment in novel food approval track records to consolidate procurement leverage against emerging precision fermentation platforms. Capacity expansion in Central European beet-sugar corridors anchors polyol supply security against feedstock cost volatility. For New Entrants and Emerging Players: Differentiate on rare steviol glycoside production via enzymatic glycosylation platforms that bypass agricultural cultivation constraints. Target India's branded dairy and traditional sweets sectors where FSSAI approval acceleration opens reformulation pathways with limited incumbent penetration. Pursue direct-to-manufacturer liquid concentrate delivery models that bypass established distributor networks in French and Italian dairy processing clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food ingredient conglomerates seeking to divest non-core sweetener assets amid portfolio rationalization. Long-term viability centers on bioprocess platforms with demonstrated regulatory track records and certified capacity expansion pipelines rather than commodity extraction operations. Monitor EFSA safety dossier review acceleration as the critical inflection signal for pipeline commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purification Infrastructure | Captive EFSA-compliant capacity secures procurement preference from German beverage formulators facing Nutri-Score mandates. |
| Precision Fermentation Platform Development | Synthetic biology convergence enables rare glycoside production without Chinese leaf-processing dependency. |
| Long-term Offtake Contracting | Three-to-five-year volume commitments hedge tier-one processors against novel food approval delays. |
| Direct-to-Manufacturer Liquid Concentrate Delivery | Bulk tanker bypass of distributor networks captures margin in French and Italian dairy applications. |
| Regulatory Track Record Certification | Demonstrated EFSA and FDA compliance history concentrates procurement leverage among qualified suppliers. |
Study Parameters
The analysis maps stevia glycosides, polyol sweeteners, and synthetic alternatives, each validated through fermentation specialists, extraction processors, beverage formulator procurement leads, and regulatory affairs directors. Primary interviews with these stakeholders combined with secondary validation from FDA GRAS notifications, EFSA novel food approvals, EU Farm to Fork Strategy documentation, and customs trade data. Bottom-up volume modeling and top-down value triangulation cross-check segment outputs against disclosed capacity expansions and offtake agreements.
Consistency checks validated outputs against external benchmarks including disclosed fermentation yield improvements and announced capacity additions across the projection horizon. The analytical framework models product type, application category, physical form, and geographic production hub dimensions. CAGRs derive from segmented growth rate analysis calibrated to regulatory approval timelines and reformulation mandate implementation schedules. Feedstock cost volatility indices and bioprocess yield curves constitute key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Nutri-Score enforcement or accelerated FSSAI approval timelines would require recalibration. Forecasts reflect assumptions regarding regulatory divergence between EFSA and FDA standards, climate-driven agricultural commodity fluctuations, and precision fermentation platform commercialization trajectories. Revision becomes warranted when WHO non-sugar sweetener guidance crosses implementation thresholds or when Chinese extraction capacity consolidation disrupts Western formulator supply security.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
D Psicose Market
Sweeteners
Sweeteners Market
Sweeteners
Glucose Syrup Market
Sweeteners
Galactose Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Fructose Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Mannitol Market
Sweeteners
Compressible Sugar Market
Sweeteners
North America Stevia Market