
 Sugar Syrups Market | 2026-2036
Sugar Syrups Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Syrups Market Outlook
The EU Green Deal is recalibrating sweetener procurement across European food and beverage manufacturers, pushing formulators toward lower-carbon syrup supply chains. Cargill Corporation leverages its integrated corn processing network to secure feedstock transparency for European buyers. Tate & Lyle PLC anchors its positioning through specialty starch and sweetener R&D facilities in the region. Archer Daniels Midland competes on bulk syrup volume and agricultural origination scale across multiple EU member states.
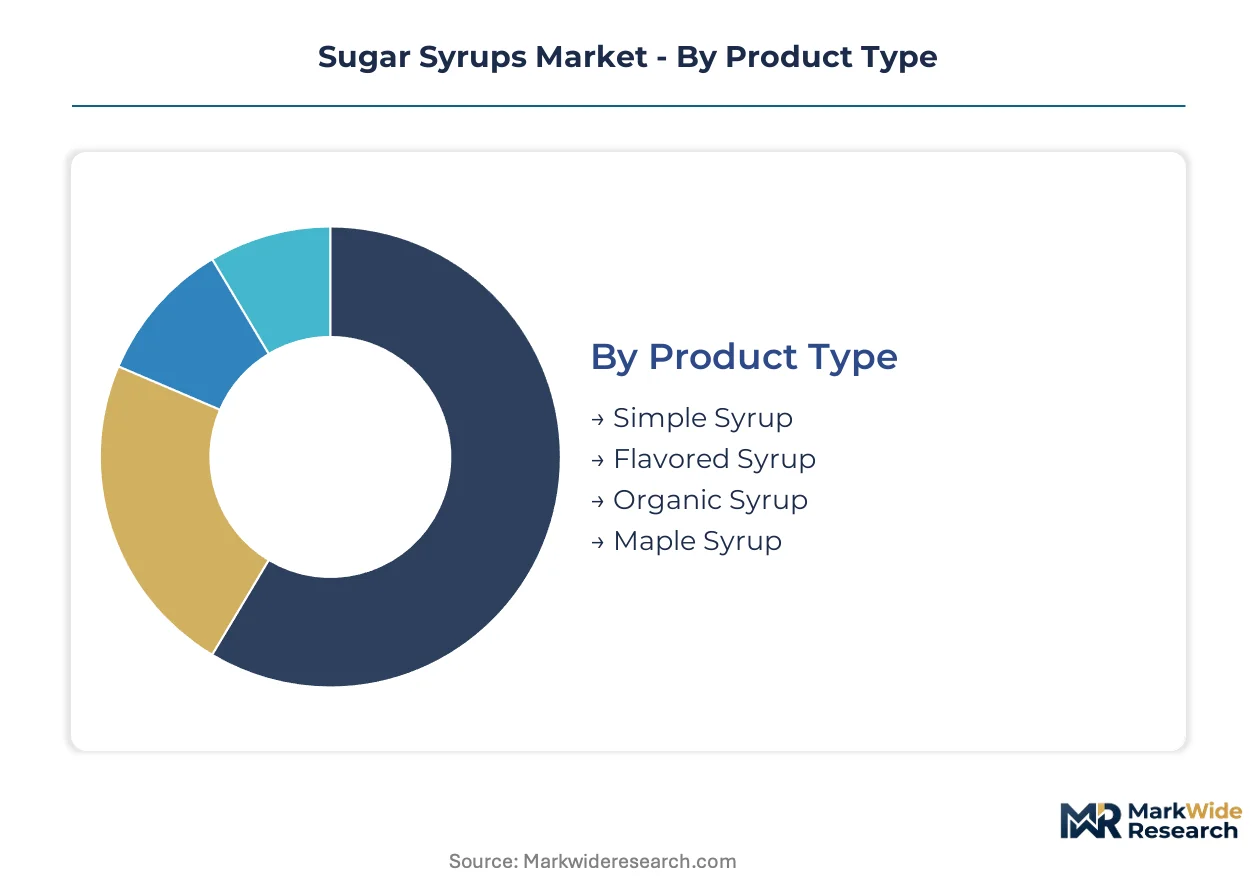
Sugar syrups are concentrated aqueous solutions of sucrose, glucose, fructose, or mixed saccharides, typically ranging from 60 to 80 degrees Brix, produced through enzymatic hydrolysis or thermal inversion of refined sugar sources for industrial sweetening, humectancy, and browning control. Simple syrup maintains dominant volume share in beverage manufacturing due to its neutral flavor profile and dissolution efficiency, while organic syrup commands premium positioning in clean-label bakery and confectionery channels. Flavored syrup segments attract margin concentration from specialty coffee chains and mixology applications.
EMA food contact regulations, EFSA additive safety assessments, and EU organic certification standards collectively govern syrup composition, labeling claims, and import eligibility across the European trading bloc. Compliance with REACH chemical registration and F-Gas Regulation cooling requirements in processing facilities shapes capital allocation for syrup producers. Stakeholders must monitor evolving EU Deforestation Regulation traceability mandates and their downstream impact on cane and beet sugar sourcing.
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing cane and beet sugar syrup processors to rebuild procurement systems around geolocated farm verification, compressing supplier qualification timelines and elevating compliance costs across European beverage and bakery supply chains.
Growth Catalysts
- Clean-label beverage reformulation:German, French, and Italian beverage manufacturers are accelerating adoption of organic and flavored syrup variants to meet consumer transparency demands and EU organic certification standards.
- REACH and F-Gas Regulation compliance:European food processors are recalibrating ingredient sourcing strategies to satisfy chemical registration and cooling requirements in processing facilities, creating procurement pull for certified low-carbon syrup supply chains.
- Specialty coffee chain expansion:Mixology applications and premium coffee formats across urban European centers are driving margin concentration in flavored syrup segments with customized viscosity and sweetness profiles.
Market Restraints
- Beet sugar price volatility:Input cost fluctuations for European beet sugar feedstock concentrate margin pressure on regional syrup processors without backward integration into agricultural origination.
- Cane sugar supply concentration:Sourcing dependencies on specific tropical origin zones expose European formulators to climate-driven harvest variability and shipping route disruptions.
- Enzymatic hydrolysis technical ceiling:Current industrial biocatalyst efficiency limits constrain the cost-competitive production of specific glucose-fructose ratios demanded by premium beverage applications.
Strategic Opportunities
- Eastern European bakery penetration:Poland, Romania, and Czech Republic markets show underdeveloped clean-label syrup adoption relative to Western European benchmarks, presenting first-mover positioning for organic-certified suppliers.
- EU Green Deal carbon accounting:Integrated corn processing networks can leverage feedstock transparency credentials to capture premium positioning among sustainability-scored procurement tenders.
- Direct-to-foodservice digital channels:Specialty syrup producers are bypassing traditional ingredient distributors through B2B platform sales to independent coffee roasters and craft confectioners.
Industry Challenges
- ESG data architect scarcity:European syrup processors struggle to hire personnel capable of building geolocated farm verification systems compliant with EU Deforestation Regulation traceability mandates.
- Multi-certification timeline compression:Simultaneous pursuit of EU organic, REACH, and EFSA additive safety assessments creates overlapping audit burdens that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Syrups Market |
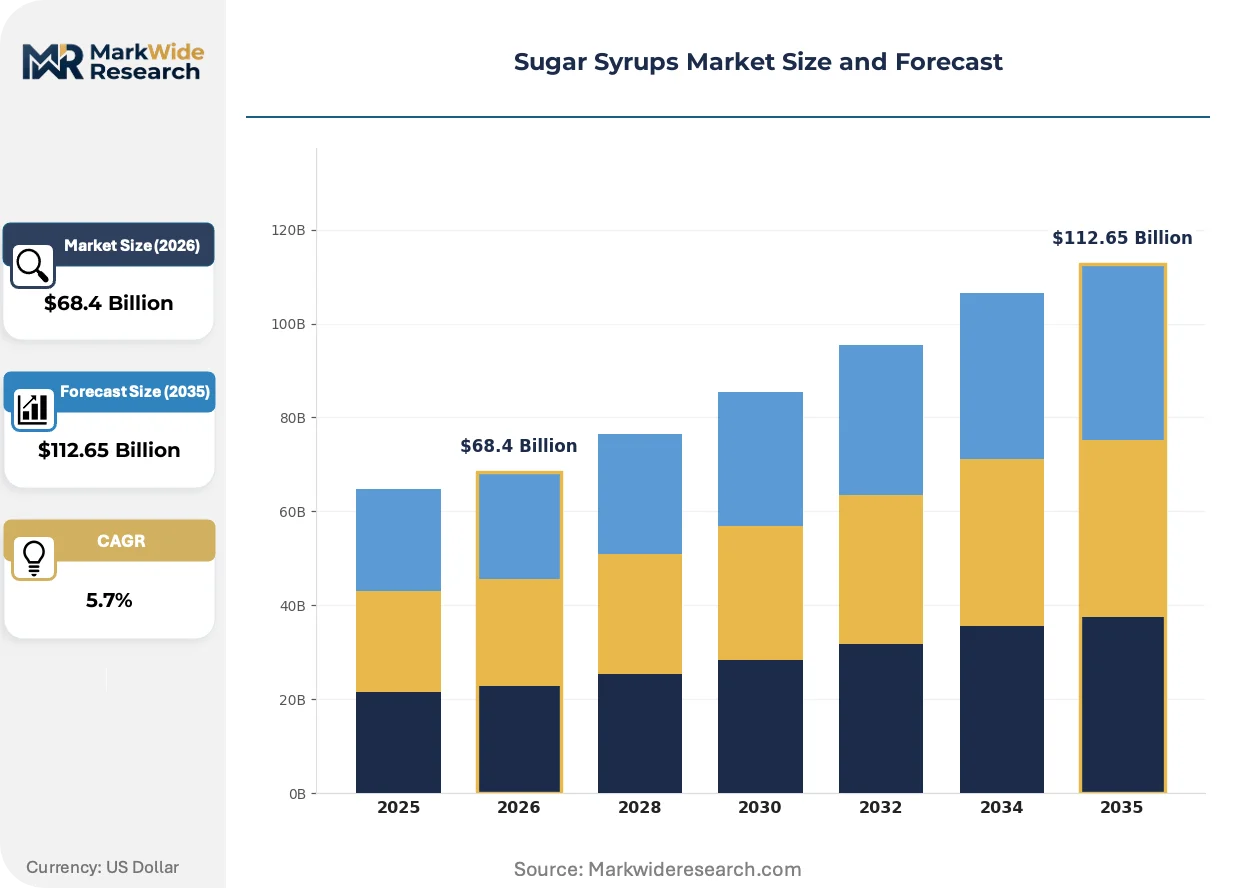
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simple Syrup, Flavored Syrup, Organic Syrup, Maple Syrup Application: Beverages, Confectioneries, Baking, Sauces Distribution Channel: Online Retail, Grocery Stores, Food Service, Specialty Stores End User: Food Manufacturers, Restaurants, Bakers, Home Cooks |
| Companies Covered | Archer Daniels Midland, Cargill Corporation, Tate & Lyle PLC, Ingredion, Roquette Freres SA, Tereos, Illovo Sugar, Monin Inc., AGRANA Beteiligungs-AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Syrups Market Strategic Shifts
Digital traceability infrastructure and enzymatic process intensification are converging to reshape how European syrup producers validate origin claims and optimize saccharide conversion efficiency.
Membrane filtration coupled with real-time Brix monitoring is automating quality control in continuous syrup production lines. Mid-scale European beverage ingredient manufacturers are deploying these systems to reduce batch-to-batch variation and cut laboratory testing overhead. The technology is automating the shift from manual sampling protocols to closed-loop process control, compressing the competitive gap between artisan and industrial syrup suppliers.
EU F-Gas Regulation phase-down schedules are accelerating capital redeployment toward ammonia and CO2-based cooling systems in syrup processing facilities. European thermal inversion plants face retrofit deadlines that favor greenfield investments with integrated carbon capture over legacy equipment upgrades. German and French processors are absorbing the steepest compliance costs due to older installed bases of hydrofluorocarbon-dependent equipment.
Foodservice operators are consolidating supplier relationships around single-source syrup portfolios with bundled technical support and formulation consulting. Independent coffee chains across Italy and Spain are displacing fragmented multi-vendor procurement with preferred partnership agreements that lock in volume commitments against recipe co-development services. This concentration is most visible in Mediterranean markets where specialty coffee culture expansion outpaces internal R&D capacity.
Sugar Syrups Market Segmentation
Sugar syrup procurement strategies diverge sharply across product grades and end-use specifications, with certification requirements and viscosity standards determining supplier qualification timelines. Segmentation reveals how formulation complexity, channel access, and customer technical capabilities reshape competitive positioning within each category.
Product Type:
EU organic certification, EFSA additive safety assessments, and REACH chemical registration impose tiered compliance burdens that segment producers by verification depth and traceability infrastructure investment.
- Simple Syrup:Aqueous sucrose solution standardized at 60-66 degrees Brix through thermal inversion or direct dissolution, prized for neutral flavor and instant solubility. German and French beverage manufacturers consume the dominant volume for soft drink and ready-to-drink tea reformulation, though margin compression intensifies as private-label sourcing displaces branded procurement.
- Flavored Syrup:Infused formulations incorporating natural extracts, artificial flavorants, or compounded essences at customized viscosity profiles. Italian specialty coffee chains and Spanish mixology bars drive specification innovation, demanding low-water-activity formulations that withstand steam wand exposure without caramelization defects.
- Organic Syrup:Certified feedstock from EU-recognized organic cultivation with full farm-to-facility chain of custody documentation. Clean-label bakery channels in France and premium confectionery producers absorb premium positioning.
- Maple Syrup:Grade A and processing-grade classifications from Acer saccharum sap concentration, subject to Canadian Food Inspection Agency equivalency agreements for EU import eligibility. Niche positioning in gourmet retail and artisan foodservice applications.
Leading the category by volume: Simple Syrup. Growing fastest: Flavored Syrup.
Application:
End-use viscosity requirements and thermal stability demands segment syrup specifications by processing intensity and finished-product shelf life targets.
- Beverages:Dilutable concentrates for carbonated soft drinks, still beverages, and alcoholic mixers requiring rapid dissolution and microbial stability. German reformulation programs prioritize reduced-sugar variants with modified glucose-fructose ratios.
- Confectioneries:Humectant and anti-crystallization functions in hard candies, caramels, and fondants. Italian producers lead specification stringency for texture control in traditional regional specialties.
- Baking:Maillard reaction acceleration and moisture retention in industrial and artisan bakery. French clean-label mandates are accelerating organic syrup substitution for invert syrups in croissant and brioche production.
- Sauces:Viscosity modification and sweetness balance in condiments and savory preparations. Foodservice operators in Spain consolidate procurement around multi-functional syrup portfolios.
Highest margin concentration: Confectioneries. Steepest volume expansion: Beverages.
Distribution Channel:
Customer technical sophistication and order fragmentation determine channel economics, with direct relationships capturing formulation-intensive accounts.
- Online Retail:Direct-to-consumer and small-batch foodservice procurement through B2B platforms. Independent coffee roasters in Italy bypass traditional distributors for specialty flavored syrups with customized sweetness profiles.
- Grocery Stores:Packaged retail formats for home cooking and small commercial users. Private-label concentration in German and French supermarket chains compresses branded shelf space.
- Food Service:Bulk dispensing systems and technical support bundles for restaurant and café operators. Preferred partnership agreements are displacing fragmented multi-vendor procurement across Mediterranean markets.
- Specialty Stores:Gourmet retail and artisan ingredient suppliers serving premium home bakers and small confectioners. Maple syrup and organic variants command disproportionate margin here.
Dominant volume flow: Food Service. Channel gaining share fastest: Online Retail.
End User:
Scale and technical capability stratify end users by formulation support requirements and quality assurance sophistication.
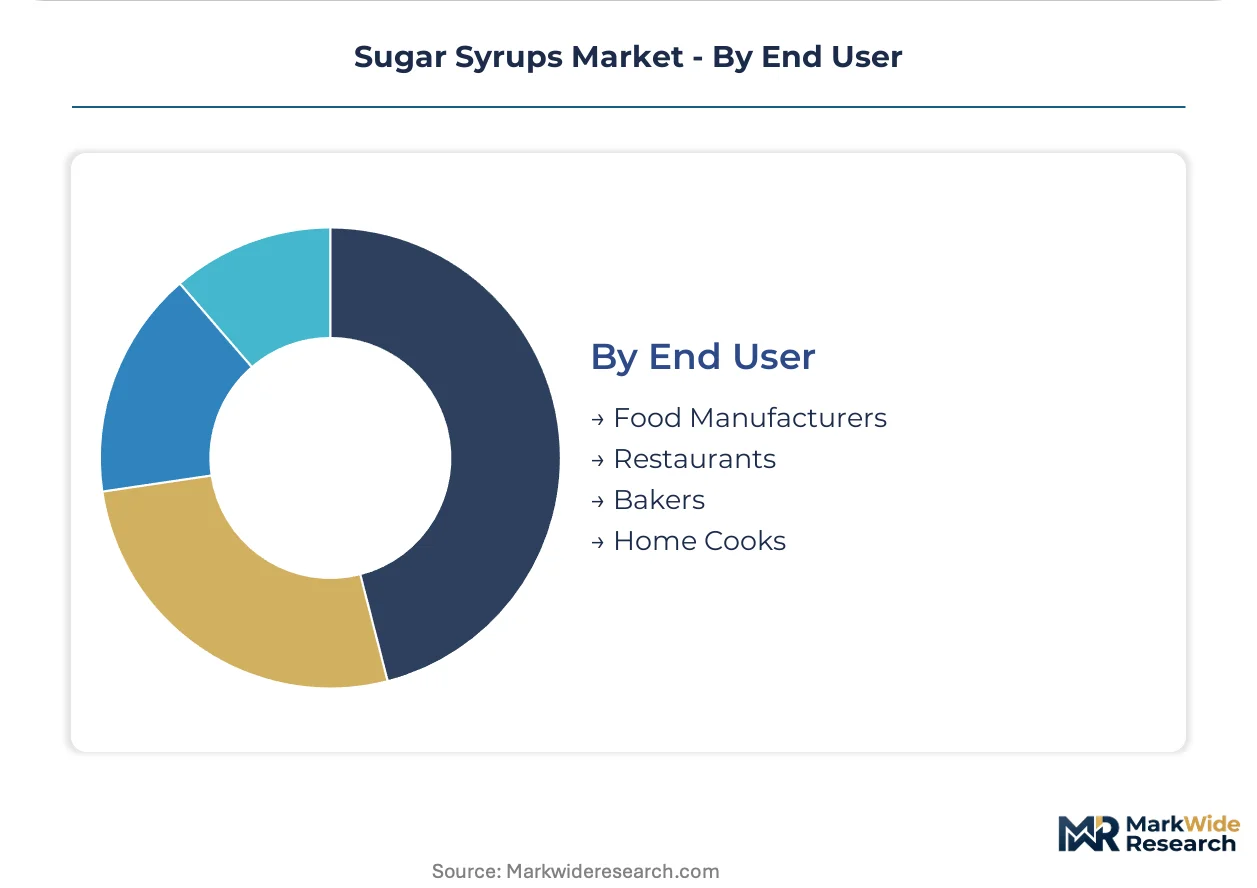
- Food Manufacturers:Industrial-scale procurement with integrated R&D collaboration and regulatory documentation. EU Deforestation Regulation traceability mandates force rebuild of supplier qualification systems.
- Restaurants:Menu-specific syrup applications with demand for technical training and equipment compatibility. Specialty coffee chain expansion across urban European centers drives flavored syrup specification.
- Bakers:Artisan and industrial bakery operations requiring consistent fermentation behavior and crust color development. Clean-label pressures accelerate organic syrup adoption in France.
- Home Cooks:Small-volume retail purchasers with price sensitivity and convenience priorities. Grocery and online channels compete for this fragmented demand pool.
Largest absolute consumption: Food Manufacturers. Fastest specification evolution: Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg's port infrastructure anchors European syrup import flows, handling concentrated sucrose shipments from tropical origins and distributing refined products across German beverage manufacturing clusters.
Germany
Beverage reformulation programs in Berlin and Munich drive procurement of organic syrup variants. REACH chemical registration requirements force processors to rebuild supplier qualification systems. The North Rhine-Westphalia industrial corridor concentrates enzymatic hydrolysis capacity for glucose-fructose syrup production.
France
Clean-label bakery mandates in Paris accelerate organic syrup substitution for traditional invert syrups. EFSA additive safety assessments govern flavored syrup composition for confectionery applications. The Île-de-France region hosts specialty coffee chain procurement headquarters demanding customized viscosity profiles.
Italy
Specialty coffee culture expansion in Milan and Rome concentrates margin in flavored syrup segments. EU organic certification standards shape import eligibility for cane-derived products. Veneto and Emilia-Romagna industrial zones supply artisan confectioners with region-specific sweetness formulations.
Spain
Mixology applications in Barcelona and Madrid drive specification innovation for low-water-activity syrups. F-Gas Regulation cooling requirements compress retrofit timelines for thermal inversion plants. Andalusian foodservice operators consolidate procurement around bundled technical support agreements.
Poland
Underdeveloped clean-label adoption in Warsaw and Krakow presents first-mover positioning for organic-certified suppliers. EU Deforestation Regulation traceability mandates elevate compliance costs for new market entrants. The Silesian industrial region attracts greenfield syrup processing investments with modern ammonia-based cooling infrastructure.
Sugar Syrups Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and traceability infrastructure investment. The vendor base stratifies between integrated agricultural processors with captive feedstock supply and specialist flavor houses with formulation consulting capabilities. Three archetypes dominate: diversified agribusiness conglomerates with corn processing networks, beet sugar cooperatives with regional origination control, and boutique syrup blenders serving foodservice direct. Competitive moves concentrate on backward integration into agricultural verification systems and preferred partnership agreements with specialty coffee chains.
Within the agribusiness tier, Archer Daniels Midland and Cargill Corporation exemplify scale-driven positioning through integrated origination networks. Tate & Lyle PLC occupies a specialist position anchored by European R&D infrastructure for starch and sweetener modification. These three entities represent divergent strategic postures: bulk volume leverage, feedstock transparency credentials, and technical formulation support respectively.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill Corporation |
| Tate & Lyle PLC |
| Ingredion |
| Roquette Freres SA |
| Tereos |
| Illovo Sugar |
| Monin Inc. |
| AGRANA Beteiligungs-AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned beet sugar cooperatives across Germany and France anchor regional pricing discipline through backward integration into agricultural origination, compressing margin capture for independent syrup blenders while sovereign-backed Brazilian cane processors leverage export credit facilities to undercut contract benchmarks during harvest surplus windows.
Pricing Analysis
Value-based pricing anchored to Maillard reaction performance in industrial bakery applications commands premium positioning over commodity simple syrup tiers. Three-tier pricing structure across organic-certified, conventional food-grade, and bulk industrial grades reflects EU Deforestation Regulation compliance costs and enzymatic hydrolysis efficiency differentials. Pricing pressure stems from private-label concentration in German and French grocery retail displacing branded procurement. Food manufacturers exhibit highest price sensitivity due to reformulation volume scale, while specialty coffee chains absorb premium viscosity customization with minimal negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian cane sugar feedstock concentration for EU import-dependent processors, exposing margin stability to climate-driven harvest variability and shipping route disruptions through the Panama Canal. Geographic supply draws from Germany, France, and Brazil as dominant origination points, with Polish greenfield investments emerging as diversification hedges. Raw material dependencies center on beet sugar tonnage, corn starch for glucose-fructose syrup, and natural flavorant extracts for infused variants. Tariff exposure from EU-Mercosur trade negotiations creates procurement uncertainty for cane-derived inputs. Distribution runs through Hamburg port infrastructure for bulk import flows, with direct-to-foodservice digital channels bypassing traditional ingredient distributors for specialty flavored variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar syrups market functions as a vertical-integration race where control over geolocated farm verification systems separates premium-margin players from commodity competitors, with EU Deforestation Regulation traceability mandates forcing accelerated capital deployment into agricultural origination networks.
For Market Incumbents: Anchor market position through captive beet sugar origination in the North Rhine-Westphalia corridor and preferred partnership agreements with Italian specialty coffee chains. Certification investment in EU organic and REACH compliance creates switching costs against emerging Polish entrants. Defensive consolidation should target distressed flavor houses in Spain with established mixology channel relationships. For New Entrants and Emerging Players: Enter via direct-to-foodservice digital platforms targeting independent coffee roasters in Warsaw and Krakow where clean-label adoption lags Western European benchmarks. Poland presents the most penetrable geography due to underdeveloped organic syrup procurement infrastructure. A formulation consulting bundled offer displaces fragmented multi-vendor relationships prevalent in Mediterranean markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale enzymatic hydrolysis specialists in the Silesian industrial region with modern ammonia-based cooling infrastructure compliant with F-Gas Regulation phase-down schedules. Long-term viability hinges on feedstock transparency credentials scoring sustainability procurement tenders. Watch EU-Mercosur trade ratification progress as inflection indicator for cane sugar import cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Origination | Cargill's corn processing network secures geolocated farm verification for EU Deforestation Regulation compliance. |
| Green Manufacturing Transition | Ammonia-based cooling retrofits in German thermal inversion plants satisfy F-Gas Regulation phase-down mandates. |
| Long-term Supply Agreement | Preferred partnership contracts with Italian specialty coffee chains lock volume against recipe co-development services. |
| Joint Venture | Polish greenfield investments attract European beverage manufacturers seeking deforestation-free cane sugar alternatives. |
| Product Line Extension | Low-water-activity flavored syrups withstand steam wand exposure for Spanish mixology bar specifications. |
Study Parameters
Independent corroboration across syrup procurement managers at German beverage manufacturers, technical directors at French bakery ingredient suppliers, and sustainability officers at Italian specialty coffee chains underwrites the qualitative findings. Primary interviews with plant engineers at enzymatic hydrolysis facilities, distribution channel partners in Hamburg port logistics, and regulatory affairs leads navigating REACH registration complemented secondary validation through EU customs trade data, EFSA additive safety assessment filings, and SEC disclosures from publicly traded agribusiness conglomerates. Bottom-up volume modeling from individual facility capacity and top-down demand estimation from end-use consumption patterns were reconciled through iterative triangulation.
Comparable-period anchoring tied projection assumptions to historical reformulation program adoption curves and clean-label certification penetration rates observed across the analysis window. Segmentation dimensions modeled include product type certification tier, application viscosity requirement, distribution channel technical support intensity, and end-user scale sophistication. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint extrapolation. Industry-specific forecast inputs incorporated EU Green Deal carbon accounting scoring trends and specialty coffee chain expansion pipeline data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU-Mercosur trade agreement suspension or accelerated F-Gas Regulation enforcement timelines. Forecasts reflect documented assumptions regarding enzymatic hydrolysis efficiency improvement curves and beet sugar price volatility persistence. Beet sugar cooperative consolidation, climate-driven tropical harvest disruption, and ESG data architect hiring scarcity represent specific risk factors that could revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
D Psicose Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Xylitol Market
Sweeteners
Mannitol Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Corn Syrup Market
Sweeteners
Stevia Market
Sweeteners
Sweet Modulator Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Sweeteners Market