
 Global Brown Sugar Market | 2026-2036
Global Brown Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brown Sugar Market Analysis
The capital-intensity divergence between integrated refiners and commodity processors is reorganizing competitive tiers in brown sugar. ASR Group leverages captive cane supply across the Caribbean basin to sustain margin stability. Südzucker AG anchors its European position through beet-sugar backward integration into molasses recovery. Cargill Incorporated competes on bulk logistics scale, moving raw sugar through Gulf Coast terminals into North American refineries.
Brown sugar denotes crystalline sucrose retaining variable molasses content, typically 3.5-6.5% by mass for light grades and up to 10% for dark varieties, manufactured through either direct crystallization of cane juice or molasses reintroduction into refined white sugar. Its hygroscopic properties and distinct flavor profile serve baking, beverage formulation, and confectionery applications where moisture retention and caramel notes carry functional value. The organic brown sugar segment commands premium shelf positioning as clean-label procurement expands across European and North American retail channels. Food manufacturers represent the fastest-growing end-user category, with industrial bakeries standardizing brown sugar inclusions for texture consistency across frozen dough platforms.
The FDA governs added-sugar disclosure on U.S. nutrition labels, directly pressuring reformulation toward lower-inclusion recipes or alternative sweetener blends. India's FSSAI mandates molasses-content thresholds and country-of-origin traceability for imported crystalline sugars, raising compliance costs for non-integrated traders. The EU Green Deal's deforestation-free supply-chain rules will reshape cane-sourcing verification requirements for European processors. Stakeholders must monitor how carbon-border adjustments and evolving clean-label definitions recalibrate procurement priorities across premium and commodity brown sugar tiers.
Market Dynamics
Molasses-content verification requirements under India's FSSAI and the EU Green Deal's deforestation-free supply-chain rules are forcing cane-sugar processors to rebuild traceability infrastructure, compressing margins for non-integrated traders while advantaging refiners with captive plantation networks.
Growth Catalysts
- Clean-label procurement mandates:European retailers are expanding shelf space for certified organic brown sugar varieties, pulling volume through specialty distributors in Germany and France.
- Indonesia's packaged food expansion:Industrial bakeries and confectionery manufacturers in Jakarta and Surabaya are standardizing brown sugar inclusions for moisture retention in tropical climates.
- FDA added-sugar disclosure rules:U.S. nutrition label reforms are pressuring food manufacturers toward lower-inclusion recipes that preserve functional properties through concentrated molasses grades.
Market Restraints
- Raw cane price volatility:Weather-driven harvest fluctuations in Brazil and Thailand transmit directly to brown sugar input costs, destabilizing processor margins.
- Beet-sugar supply concentration:European brown sugar production depends on molasses recovery from Südzucker AG and Nordzucker-controlled beet processing, creating bottleneck risk.
- High-intensity sweetener substitution:Stevia and monk fruit extracts are displacing brown sugar in reduced-calorie beverage formulations, eroding share in carbonated soft drinks.
Strategic Opportunities
- Vietnam's underpenetrated bakery sector:Artisan bread consumption in Ho Chi Minh City and Hanoi is climbing, creating first-mover advantage for specialty brown sugar importers.
- EU carbon-border adjustment mechanism:The phased implementation of CBAM will penalize high-emission cane sourcing, rewarding processors with verified low-carbon supply chains.
- E-commerce ingredient platforms:Direct-to-bakery digital procurement channels are bypassing traditional foodservice distributors, enabling margin capture by specialty refiners.
Industry Challenges
- Molasses-content assay standardization:Discrepancies between refractometer and chromatography testing methods create compliance friction for exporters serving multiple regulatory jurisdictions.
- Legacy refinery retrofit costs:Brown sugar crystallization lines require stainless steel equipment upgrades to prevent corrosion from acidic molasses residues, demanding capital deployment that commodity processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brown Sugar Market |
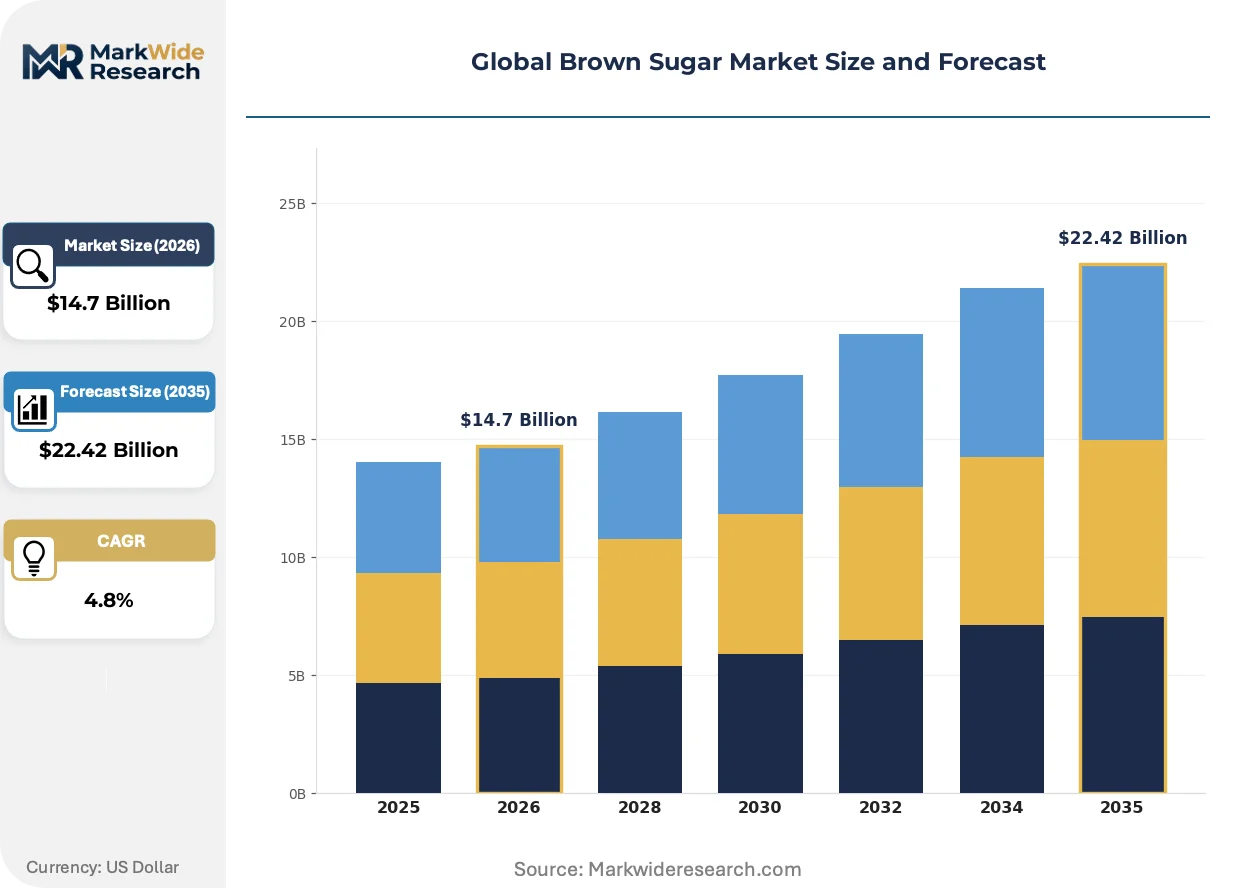
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Brown Sugar, Non-Organic Brown Sugar, Raw Brown Sugar, Refined Brown Sugar Application: Baking, Beverages, Confectionery, Food Seasoning Distribution Channel: Retail Stores, Online Stores, Wholesalers, Foodservice End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | ASR Group, Cargill Incorporated, Südzucker AG, Tate & Lyle PLC, American Crystal Sugar Company, Taikoo Sugar Limited, Louis Dreyfus Company, Wilmar International Ltd., Agrana Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brown Sugar Market Emerging Trajectories
Processing technology and procurement verification systems are reshaping how brown sugar moves from cane field to industrial bakery, with implications for cost structures and competitive positioning across light and dark grade segments.
Membrane filtration for molasses fractionation is fragmenting traditional crystallization economics. Specialty refiners in Maharashtra and São Paulo are deploying ceramic microfiltration to extract targeted flavor compounds for premium brown sugar blends. Artisan chocolate manufacturers in Belgium and Switzerland are adopting these concentrated molasses syrups for precise caramel note control, compressing demand for commodity-grade crystalline product.
The EU Green Deal's deforestation-free supply-chain rules are mandating geolocation verification for every cane shipment entering European refineries. Processors must integrate satellite monitoring and farm-level documentation systems by 2025. Caribbean basin suppliers with established plantation traceability are capturing contract premiums, while traders dependent on spot-market sourcing face exclusion from EU retail channels.
Direct sourcing contracts between industrial bakeries and brown sugar refiners are displacing traditional foodservice distribution tiers. Frozen dough manufacturers in the U.S. Midwest and Ontario are negotiating annual volume commitments with Gulf Coast refiners to lock in moisture-retention specifications. This channel compression is most visible in North American private-label retail bakery, where procurement teams are consolidating supplier bases to three to four certified refiners per region.
Global Brown Sugar Market Segmentation
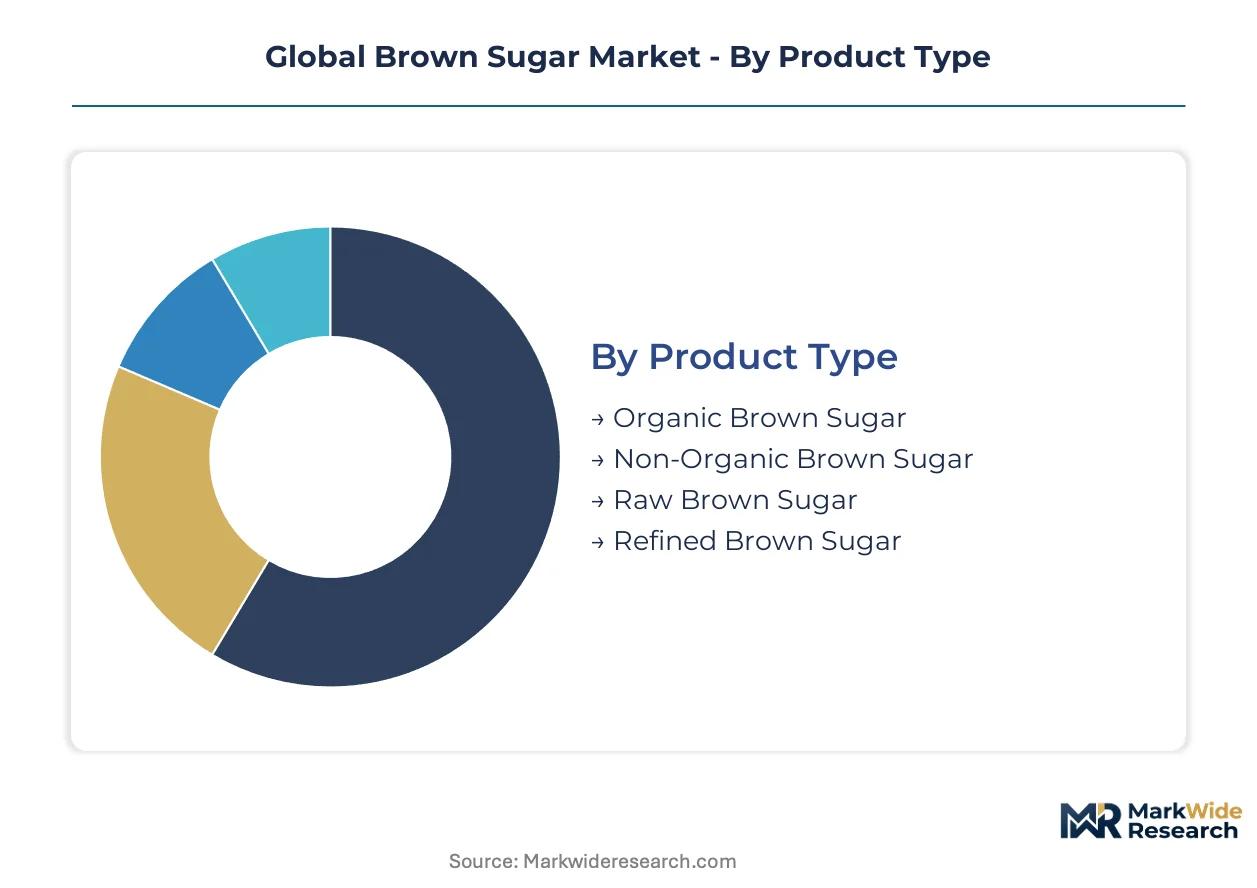
Brown sugar flows through distinct procurement channels shaped by molasses content specifications, certification requirements, and end-use functional demands. Segmentation reveals where margin concentrates across organic premiums, industrial bulk, and foodservice intermediation tiers.
Product Type:
Channel mix varies sharply by grade: organic and specialty dark varieties move through premium retail and direct-to-bakery contracts, while refined light grades dominate industrial procurement.
- Organic Brown Sugar:Certified varieties command shelf-space premiums in European and North American retail channels. Clean-label mandates from German and French retailers are pulling volume through specialty distributors, with FSSAI molasses-content verification adding compliance layers for Indian imports.
- Non-Organic Brown Sugar:Commodity-grade crystalline product with standard molasses content serves cost-sensitive industrial bakeries and beverage formulators. Indonesian packaged food manufacturers in Jakarta and Surabaya are standardizing these grades for moisture retention in tropical climates.
- Raw Brown Sugar:Minimal-processing cane juice crystallization retains full mineral content for artisan applications.
- Refined Brown Sugar:Molasses reintroduction into white sugar base enables precise specification control for frozen dough platforms.
By volume, Non-Organic Brown Sugar leads. By growth pace, Organic Brown Sugar is expanding most quickly.
Application:
Cost tier stratification separates premium recipe inclusions from commodity bulk purchases across functional use cases.
- Baking:Moisture retention and caramelization control drive specification intensity. Industrial bakeries in the U.S. Midwest and Ontario negotiate annual volume commitments with Gulf Coast refiners to lock in frozen dough performance standards.
- Beverages:FDA added-sugar disclosure rules are pressuring reformulation toward lower-inclusion recipes that preserve mouthfeel through concentrated molasses grades.
- Confectionery:Precise crystal size distribution requirements favor direct refiner relationships over distributor tiers.
- Food Seasoning:Small-batch savory applications in artisan meat curing and sauce reduction favor specialty dark grades.
Volume concentration sits with Baking. Margin expansion is strongest in Beverages.
Distribution Channel:
Customer type determines channel selection: households and small restaurants favor retail accessibility, while food manufacturers and chain bakeries bypass intermediaries.
- Retail Stores:Supermarket and hypermarket shelf placement captures household demand and small restaurant replenishment cycles. EU Green Deal deforestation-free verification requirements are reshaping procurement documentation for products entering these channels.
- Online Stores:Direct-to-bakery digital procurement platforms are bypassing traditional foodservice distributors, enabling margin capture by specialty refiners serving artisan chocolate manufacturers in Belgium and Switzerland.
- Wholesalers:Bulk consolidation serves mid-scale food manufacturers without direct refiner contracts.
- Foodservice:Distributor tiers face compression as procurement teams consolidate supplier bases.
Retail Stores maintain volume leadership. Online Stores show the steepest expansion trajectory.
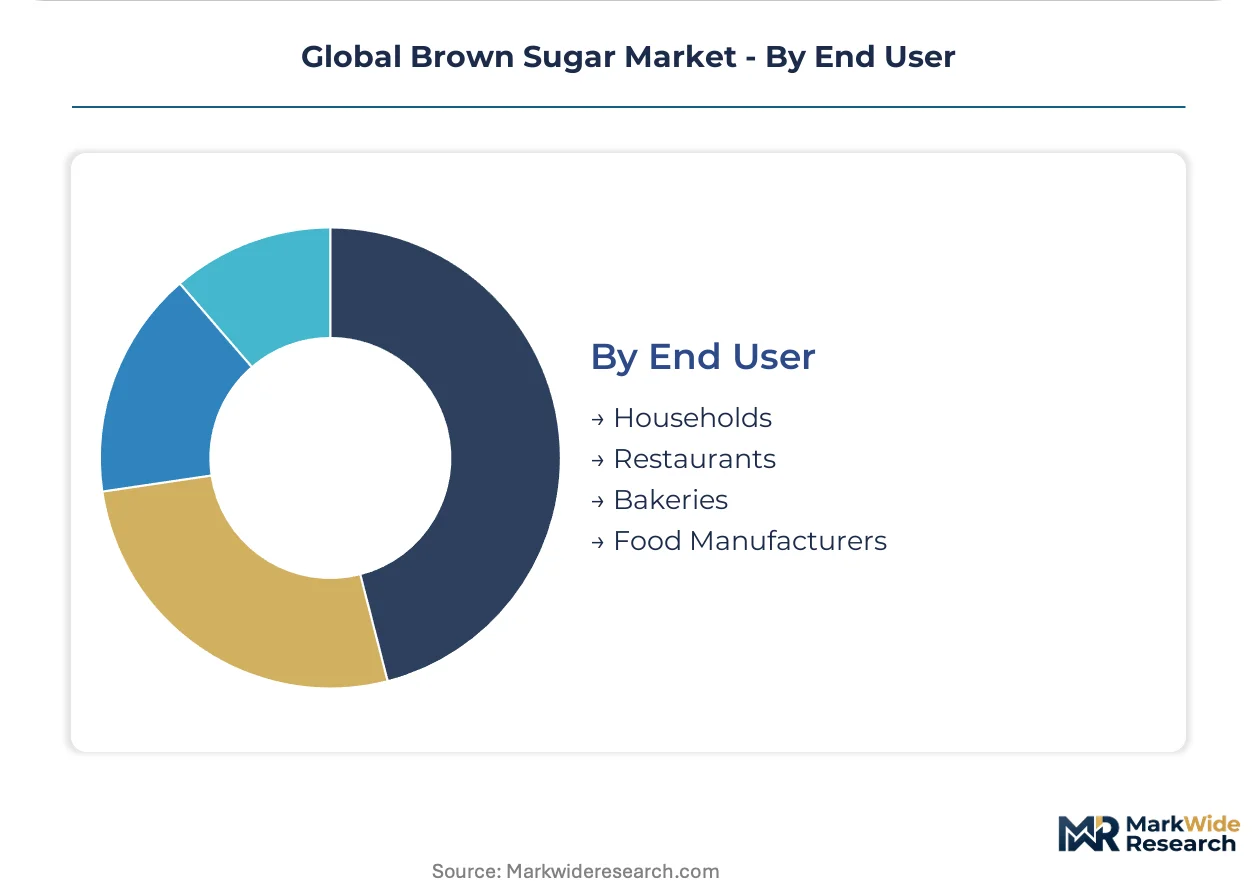
End User:
Supply concentration aligns with scale: integrated refiners serve food manufacturers directly, while fragmented household demand flows through retail layers.
- Food Manufacturers:Frozen dough and packaged confectionery producers represent the steepest demand expansion. Direct sourcing contracts with Gulf Coast and Caribbean basin refiners are displacing traditional foodservice distribution tiers.
- Bakeries:Artisan bread consumption in Ho Chi Minh City and Hanoi is climbing, creating first-mover advantage for specialty brown sugar importers targeting Vietnam's underpenetrated sector.
- Restaurants:Menu differentiation through house-made desserts and specialty beverages drives premium grade procurement.
- Households:Price-sensitive bulk purchasing favors standard light and dark varieties through retail channels.
Food Manufacturers lead by volume. Bakeries are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia channels brown sugar primarily into packaged food manufacturing, whereas Germany and the United States concentrate procurement in artisan bakery and clean-label retail channels. Brazil and India diverge again: Brazilian mills feed export-oriented refined sugar streams, while Indian processors navigate tightening domestic molasses-content regulations.
United States
Frozen dough manufacturers in the Midwest and Ontario corridor negotiate direct annual volume commitments with Gulf Coast refiners to lock in moisture-retention specifications. FDA added-sugar disclosure rules pressure reformulation toward lower-inclusion recipes that preserve functional properties through concentrated molasses grades. Industrial bakeries in Chicago and Minneapolis standardize brown sugar inclusions for texture consistency across frozen dough platforms.
Germany
Clean-label procurement mandates from German and French retailers expand shelf space for certified organic brown sugar varieties, pulling volume through specialty distributors. EU Green Deal deforestation-free supply-chain rules mandate geolocation verification for every cane shipment entering European refineries by 2025. Südzucker AG anchors its position through beet-sugar backward integration into molasses recovery, serving industrial bakeries in Bavaria and North Rhine-Westphalia.
India
FSSAI has tightened molasses-content labeling rules for crystalline sweeteners, mandating thresholds and country-of-origin traceability for imported sugars. Maharashtra and Uttar Pradesh refiners deploy ceramic microfiltration to extract targeted flavor compounds for premium brown sugar blends. Specialty distributors in Mumbai and Delhi navigate compliance layers for organic imports serving artisan chocolate manufacturers.
Indonesia
Industrial bakeries and confectionery manufacturers in Jakarta and Surabaya standardize brown sugar inclusions for moisture retention in tropical climates. The country's fast-growing packaged food sector concentrates demand in light and dark grades for snack and instant noodle applications. Procurement teams at multinational food manufacturers in the Greater Jakarta area consolidate supplier bases to three to four certified refiners per region.
Brazil
São Paulo specialty refiners deploy membrane filtration for molasses fractionation, fragmenting traditional crystallization economics. The country's cane-sugar processors leverage established plantation traceability to capture contract premiums under EU Green Deal verification requirements. Export-oriented refineries in the Center-South region serve Caribbean basin traders dependent on spot-market sourcing now facing exclusion from EU retail channels.
Global Brown Sugar Market Vendor Landscape
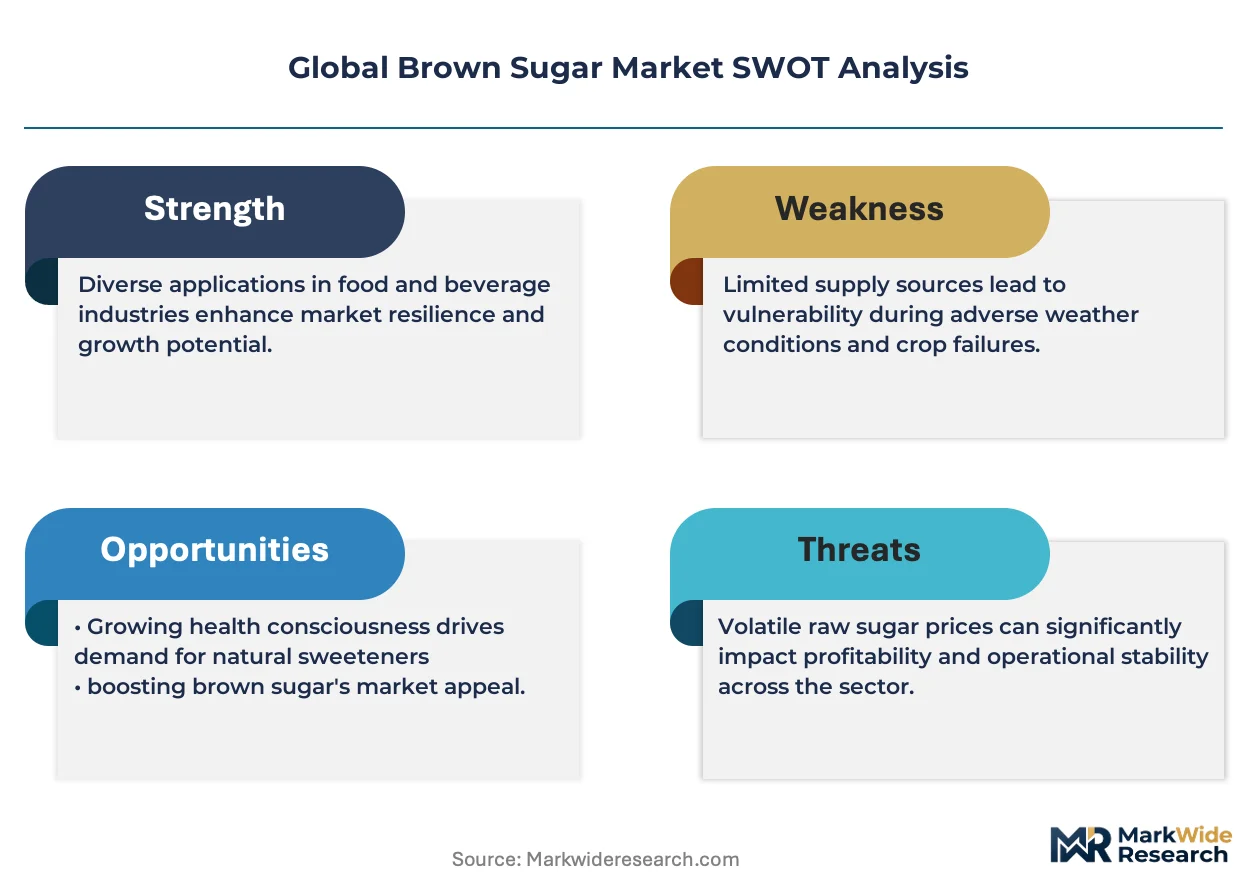
A small set of integrated leaders sits above a broader specialist tier in brown sugar processing. ASR Group and Südzucker AG control captive cane and beet supply respectively, insulating margin stability from raw price volatility. Commodity processors without plantation networks face compressed margins under tightening traceability rules. Dominant competitive moves include backward integration into molasses recovery and direct sourcing contracts that displace foodservice distribution tiers.
Within the integrated refiner tier, ASR Group and Südzucker AG exemplify divergent feedstock strategies: the former leverages Caribbean basin cane supply while the latter anchors European position through beet-sugar operations. Cargill Incorporated occupies a position at the scale-driven end, competing on bulk logistics through Gulf Coast terminals into North American refineries. These three entities represent how geographic feedstock access and logistics infrastructure determine competitive positioning under tightening regulatory verification requirements.
| Leading Market Players |
|---|
| ASR Group |
| Cargill Incorporated |
| Südzucker AG |
| Tate & Lyle PLC |
| American Crystal Sugar Company |
| Taikoo Sugar Limited |
| Louis Dreyfus Company |
| Wilmar International Ltd. |
| Agrana Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal deforestation-free verification gates both supply qualification and price differentiation, forcing European processors to absorb satellite monitoring costs while Caribbean basin suppliers with captive plantation networks capture contract premiums for traceable cane.
Pricing Analysis
Long-term offtake contracts between frozen dough manufacturers and Gulf Coast refiners anchor North American pricing, while spot-market sourcing faces compression under India's FSSAI molasses-content thresholds and traceability mandates. Pricing stratifies across organic certification tiers, with EU retailers paying premiums for geolocation-verified supply against commodity-grade Indonesian packaged food procurement. Cost compression in light-grade industrial segments is intensifying as Brazilian weather volatility transmits directly to raw cane input costs. Food manufacturers with direct refiner relationships exhibit lowest price sensitivity; spot-dependent traders in Southeast Asia face highest exposure.
Supply Chain Analysis
Strait of Malacca transit underwrites molasses supply flows from Indian Ocean producers to Southeast Asian refineries, creating logistics vulnerability for Indonesian packaged food manufacturers. Raw material sourcing draws from Brazilian Center-South cane, Indian Maharashtra juice, and European beet molasses recovery. Single-source vulnerability concentrates in Südzucker-controlled beet processing for EU brown sugar production. Distribution runs through direct-to-bakery digital platforms bypassing traditional foodservice tiers, with specialty refiners capturing margin from artisan chocolate manufacturers in Belgium and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement fragmentation across European retail channels creates niche expansion opportunities for certified organic and specialty dark-grade producers with verified low-carbon supply chains.
For Market Incumbents: Shield margin stability through captive cane supply expansion in the Caribbean basin and backward integration into molasses recovery infrastructure. ASR Group's plantation network model offers defensive template against traceability compliance cost inflation. Prioritize stainless steel crystallization line upgrades to prevent acidic molasses corrosion and extend equipment life. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated artisan bakery sector, where Ho Chi Minh City and Hanoi bread consumption climbs without established specialty brown sugar supply relationships. Target direct-to-bakery digital procurement channels for first-mover positioning. Lead with concentrated molasses syrup offerings for Belgian and Swiss chocolate manufacturers seeking precise caramel note control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane filtration-equipped specialty refining, favoring processors with ceramic microfiltration deployment capability. Over the projection horizon, acquisition targets with established EU Green Deal geolocation verification systems and FSSAI-compliant Indian import pathways offer strongest viability. Monitor EU carbon-border adjustment mechanism implementation as inflection signal for low-carbon supply chain premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Recovery | Südzucker AG's beet-sugar integration anchors European margin stability against raw price volatility. |
| Direct-to-Bakery Digital Procurement Launch | Specialty refiners bypass foodservice distributors to capture margin from artisan chocolate manufacturers. |
| Ceramic Microfiltration Capacity Deployment | Maharashtra and São Paulo refiners extract targeted flavor compounds for premium brown sugar blends. |
| EU Deforestation-Free Certification Investment | Caribbean basin suppliers with plantation traceability capture contract premiums under Green Deal rules. |
| Vietnam Market Entry Partnership | Specialty importers target Ho Chi Minh City artisan bakeries with moisture-retention grade positioning. |
Methodological Framework
The analysis maps organic certification tiers, molasses-content grades, and distribution channel structures, each validated through refinery operations managers, retail category buyers, and food manufacturer procurement leads. Primary interviews with cane plantation directors, specialty distributor logistics heads, and frozen dough platform engineers combined with secondary validation from FSSAI regulatory filings, EU Green Deal documentation, and U.S. FDA nutrition label guidance. Customs trade data from Brazilian, Indian, and Indonesian port authorities anchored supply-side triangulation against bottom-up refinery capacity surveys.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. Segmentation dimensions modeled include product type (organic, non-organic, raw, refined), application (baking, beverages, confectionery, seasoning), and distribution channel (retail, online, wholesale, foodservice). CAGRs derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost trajectories. Industry-specific inputs incorporated molasses-content assay standardization timelines and EU carbon-border adjustment mechanism phase-in assumptions.
Material uncertainties — weather-driven harvest fluctuations in Brazil and Thailand, FSSAI enforcement intensity, EU Green Deal geolocation verification system readiness — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and clean-label procurement mandate adoption curves. Practitioners should keep alternative scenarios live as carbon-border adjustment mechanisms and clean-label definition evolutions reshape procurement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Citrus Molasses Market
Sweeteners
Floral Nectar Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Food Sweetener Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Beetroot Molasses Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Sugar Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Saudi Arabia Allulose Market