
 India Food Sweetener Market | 2026-2036
India Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Sweetener Market Foresight
Modern trade and e-commerce procurement channels for bulk sweetener sourcing is narrowing as large-format retailers consolidate vendor lists and direct-to-manufacturer contracts multiply. Cargill Incorporated leverages its crushing and refining infrastructure across Uttar Pradesh and Bihar to sustain supply continuity for industrial buyers. Balrampur Chini Mills Ltd. anchors the domestic sucrose segment through integrated sugarcane processing complexes. Tate & Lyle PLC differentiates via specialty starch and texturant portfolios that complement its sweetener offerings in India.
India food sweeteners comprise caloric and non-caloric substances—sucrose, high-fructose syrups, polyols, and high-intensity compounds such as steviol glycosides and sucralose—formulated to impart sweetness, modify viscosity, or extend shelf stability in processed foods. Sucralose and stevia lead the high-intensity category as beverage manufacturers pursue FSSAI-compliant reduced-sugar claims without sacrificing taste parity. The bakery industry and confectionery businesses drive bulk sucrose demand, while soft drinks and dairy products applications pull fastest growth for natural-origin alternatives where clean-label positioning commands shelf space premiums.
FSSAI labeling regulations, the PLI scheme for food processing, and BIS quality specifications collectively determine which sweetener grades gain formulation access in packaged foods and beverages. Compliance costs favor suppliers with in-house analytical and regulatory affairs capabilities, squeezing unorganized traders out of branded supply chains. Stakeholders must monitor evolving FSSAI notification timelines and state-level excise variations on sugar-based inputs to anticipate margin shifts and procurement restructuring.
Market Dynamics
FSSAI clean-label mandates and PLI scheme incentives are compressing reformulation timelines across India's beverage and bakery sectors. Procurement concentration in Maharashtra and Gujarat is forcing mid-tier suppliers to consolidate or exit branded supply chains entirely.
Growth Catalysts
- PLI Scheme for Food Processing:Central government production-linked incentives are accelerating capital deployment into natural sweetener extraction and refining capacity across Uttar Pradesh and Bihar.
- Beverage Manufacturers:Maharashtra and Gujarat-based soft drink and dairy processors are scaling steviol glycoside and sucralose procurement to meet FSSAI-compliant reduced-sugar labeling requirements.
- Organized Retail Penetration:Western and southern Indian states with deep modern trade networks are pulling premium natural-origin sweeteners through direct-to-manufacturer contracting models.
Market Restraints
- Sugarcane Input Volatility:Monsoon-dependent cane yields in Uttar Pradesh and Maharashtra create sucrose price instability that compresses margins for integrated sugar processors.
- High-Intensity Patent Concentration:Global specialty chemical suppliers control core steviol glycoside and sucralose process patents, limiting domestic formulation autonomy.
- BIS Certification Friction:Bureau of Indian Standards quality specifications for polyols and starch derivatives impose 12-18 month approval timelines that delay product launches.
Strategic Opportunities
- Tamil Nadu and Karnataka Clusters:Southern Indian states with underpenetrated natural sweetener distribution present white space for direct procurement relationships with dairy and confectionery processors.
- Clean-Label Bakery Applications:Erythritol and maltitol formulations are gaining shelf space in premium biscuit and cake segments where FSSAI-compliant reduced-sugar claims command positioning premiums.
- E-Commerce Bulk Sourcing:B2B platform procurement is emerging as a channel innovation enabling mid-tier food processors to bypass traditional distributor markups on high-intensity sweeteners.
Industry Challenges
- Analytical Capability Scarcity:In-house FSSAI compliance testing and regulatory affairs functions are concentrated among top-tier suppliers, squeezing unorganized traders from branded supply chains.
- Reformulation Integration Complexity:Legacy bakery and confectionery production lines require 18-24 month retrofit cycles to accommodate rheological differences between sucrose and polyol alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Sweetener Market |
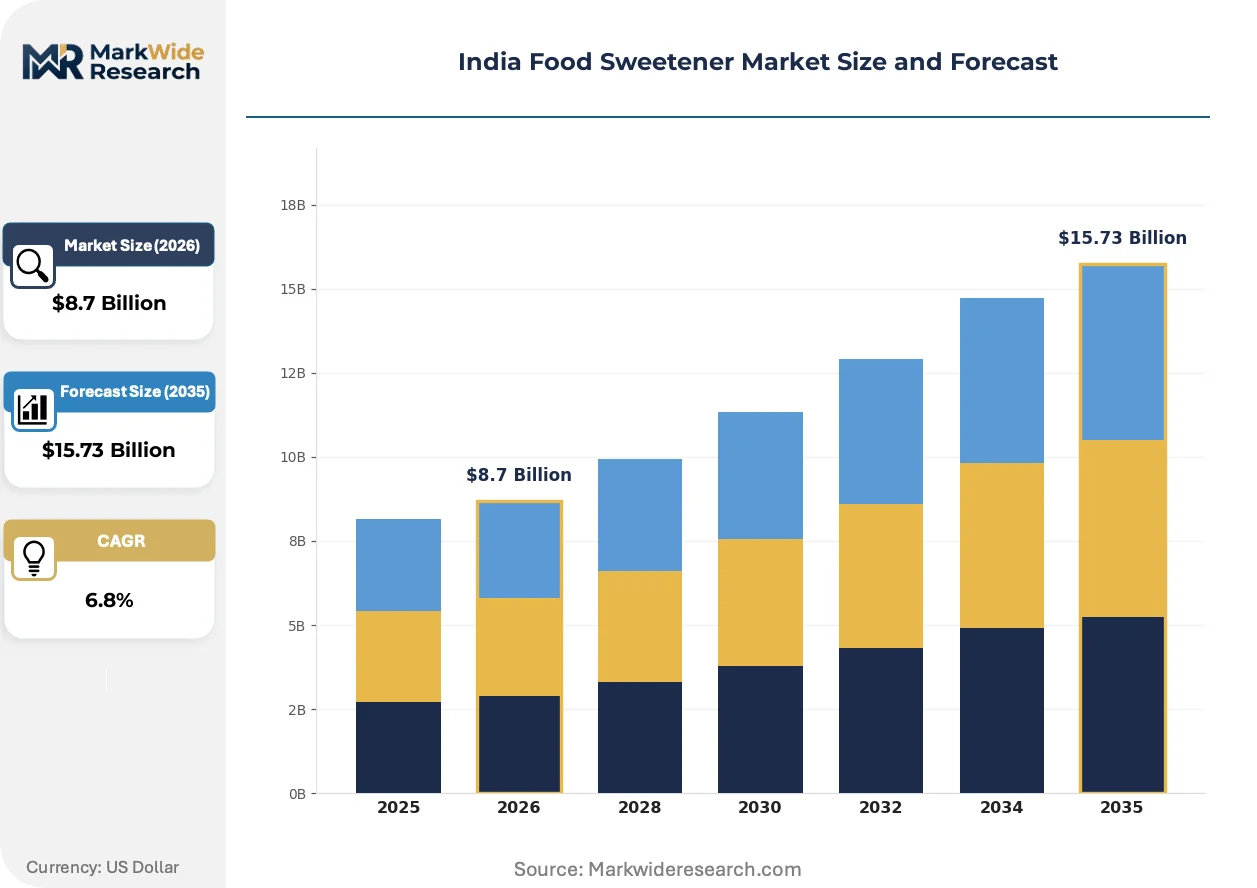
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Sucralose, Aspartame, Saccharin End User: Beverage Manufacturers, Bakery Industry, Confectionery Businesses, Food Service Providers Application: Soft Drinks, Baked Goods, Sauces, Dairy Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Service Distributors |
| Companies Covered | International Flavors & Fragrances Inc., Ingredion Incorporated, Cargill Incorporated, Balrampur Chini Mills Ltd., Ajinomoto Co. Inc., Tate & Lyle PLC, Kerry Group plc, Shree Renuka Sugars Ltd., Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Sweetener Market Shifts & Advancements
Enzymatic bioprocessing and precision fermentation are collapsing cost structures for natural-origin high-intensity sweeteners. Regulatory clarity on FSSAI notification timelines is compressing competitive windows for first-mover formulation claims.
Steviol glycoside extraction via enzymatic bioprocessing is collapsing the cost premium between natural and synthetic high-intensity sweeteners. Beverage manufacturers in Maharashtra are adopting these inputs at 3x prior-year volumes. The technology is collapsing incumbent sucralose positioning in mid-tier soft drink segments where taste parity now aligns with clean-label requirements.
FSSAI's sequential clean-label notification releases are creating compliance windows that favor suppliers with pre-positioned analytical infrastructure. Industrial buyers are consolidating vendor lists to partners capable of real-time regulatory interpretation. The bakery and confectionery segment is most affected, with processors accelerating BIS certification timelines to capture shelf space ahead of mandate enforcement.
Direct-to-manufacturer contracting is displacing traditional distributor networks for bulk sweetener procurement. Large-format retailers in Gujarat and Karnataka are consolidating vendor lists and mandating supplier traceability documentation. This pattern is most visible in western Indian states where organized retail penetration enables volume-commitment pricing models that bypass legacy commission structures.
India Food Sweetener Market Segmentation
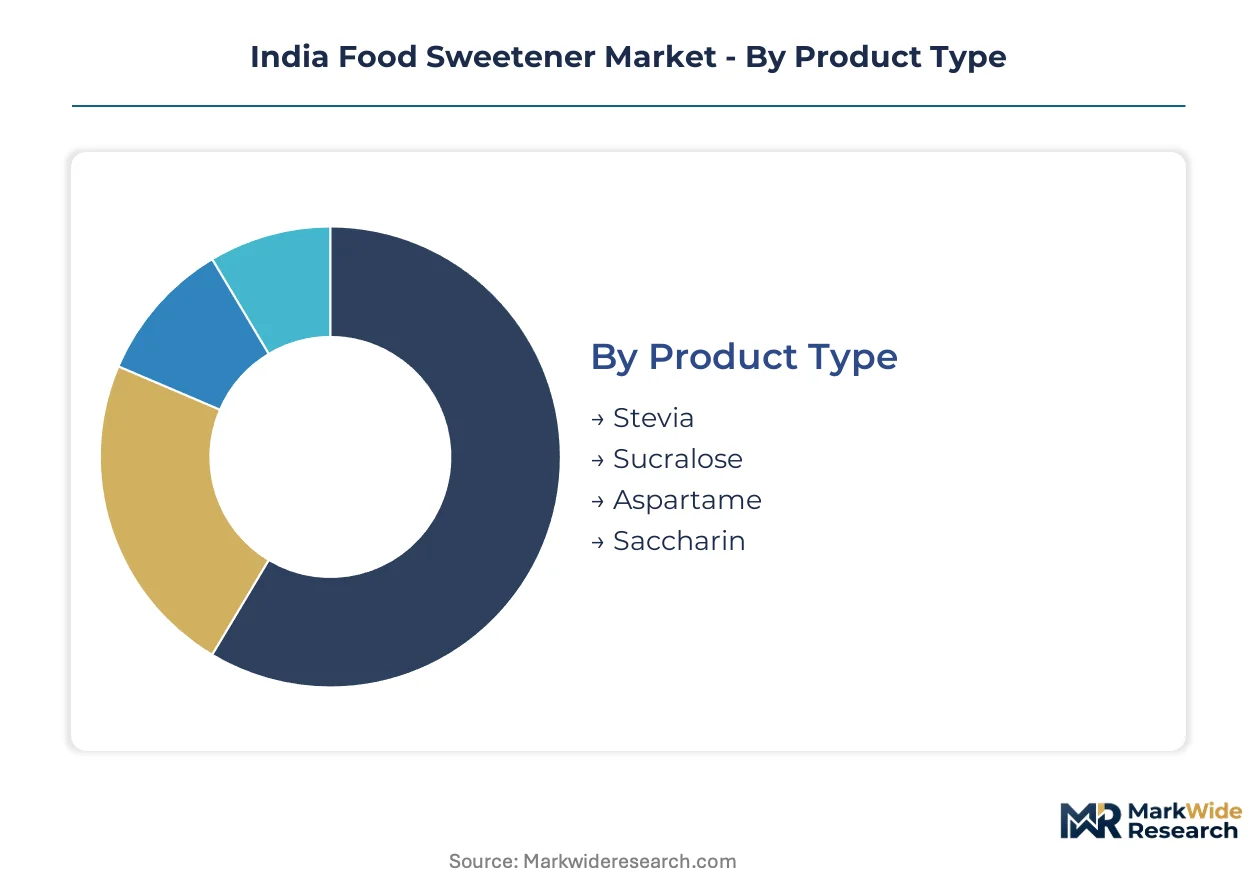
Sweetener procurement patterns in India diverge sharply across product chemistry, end-use specifications, and channel access. Each segmentation dimension carries distinct margin structures and regulatory compliance burdens that reshape vendor selection criteria.
Product Type:
After-sales technical support intensity varies dramatically across sweetener chemistries, with natural-extraction products demanding far more formulation troubleshooting than synthetic alternatives.
- Stevia:Steviol glycosides extracted from Stevia rebaudiana leaves deliver zero-calorie sweetness with FSSAI-recognized clean-label status. Maharashtra and Gujarat beverage manufacturers are expanding procurement threefold for reduced-sugar soft drink lines where regulatory positioning commands shelf premiums. Enzymatic bioprocessing advances are collapsing cost premiums against synthetic alternatives.
- Sucralose:A chlorinated sucrose derivative providing heat-stable sweetness at 600x sucrose potency. Bakery and confectionery processors in Karnataka and Tamil Nadu favor this input for high-temperature applications where stevia's thermal degradation limits utility. Patent-controlled process technology constrains domestic manufacturing autonomy.
- Aspartame:A dipeptide methyl ester delivering intense sweetness with caloric contribution negligible at typical use levels. Dairy processors leverage this input for flavored milk and yogurt applications where cost minimization outweighs clean-label positioning.
- Saccharin:The oldest high-intensity synthetic, now relegated to economy-tier applications and tabletop sweetener sachets. BIS quality specifications and lingering consumer safety perceptions restrict formulation access in premium packaged foods.
Stevia holds the largest share; momentum sits with sucralose as thermal stability requirements expand across India's bakery sector.
End User:
Volume concentration and margin capture split unevenly across customer categories, with organized manufacturers extracting pricing leverage unavailable to fragmented downstream buyers.
- Beverage Manufacturers:Maharashtra and Gujarat-based soft drink and dairy processors command the steepest procurement volumes, consolidating vendor lists around suppliers with real-time FSSAI regulatory interpretation capabilities. Direct-to-manufacturer contracting is displacing traditional distributor networks.
- Bakery Industry:Premium biscuit and cake segments in western Indian states are pulling erythritol and maltitol formulations where reduced-sugar claims enable shelf space premiums. Legacy production lines require 18-24 month retrofit cycles to accommodate polyol rheology.
- Confectionery Businesses:Hard candy and chocolate manufacturers balance sucrose cost volatility against clean-label reformulation timelines. Tamil Nadu and Karnataka clusters present underpenetrated distribution white space.
- Food Service Providers:Hotels, restaurants, and institutional catering operations source bulk sweeteners through food service distributors with limited technical support. Price sensitivity dominates procurement criteria.
Beverage manufacturers command volume leadership; the bakery industry is climbing the fastest as clean-label mandates compress reformulation windows.
Application:
Functional requirements—thermal stability, pH tolerance, solubility profiles—determine sweetener selection more than sweetness intensity alone.
- Soft Drinks:Carbonated and still beverages represent the dominant consumption channel, with stevia and sucralose formulations displacing sucrose in FSSAI-compliant reduced-sugar lines. Maharashtra processors are scaling procurement at unprecedented rates.
- Baked Goods:Cookies, cakes, and biscuits require heat-stable inputs where sucralose maintains sweetness through Maillard browning temperatures. Clean-label positioning is gaining traction in premium segments.
- Sauces:Ketchup, condiments, and savory preparations leverage high-intensity sweeteners for minimal-calorie sweetness enhancement. Volume concentration remains modest relative to beverage and bakery channels.
- Dairy Products:Flavored milk, yogurt, and ice cream applications favor aspartame and sucralose for cold-process compatibility. Southern Indian dairy cooperatives are emerging as significant procurement clusters.
Soft drinks anchor volume; dairy products are gaining share fastest as southern Indian processors expand flavored product portfolios.
Distribution Channel:
Channel selection determines technical support access, minimum order quantities, and traceability documentation availability.
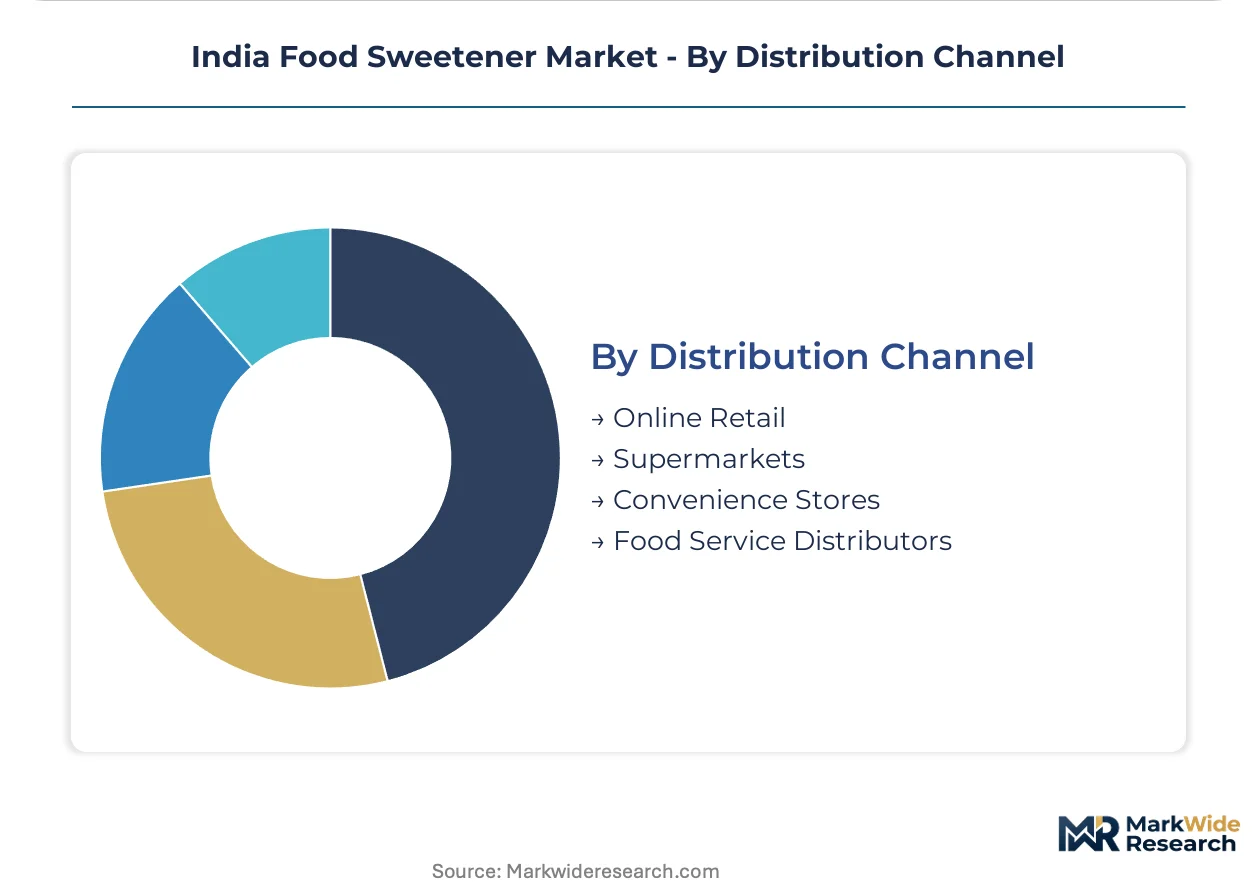
- Online Retail:B2B platform procurement enables mid-tier food processors to bypass traditional distributor markups on high-intensity sweeteners. Real-time price transparency and consolidated vendor lists are compressing legacy commission structures.
- Supermarkets:Large-format retailers in Gujarat and Karnataka are mandating supplier traceability documentation and consolidating vendor lists around partners with FSSAI pre-certification. Volume-commitment pricing models favor scaled suppliers.
- Convenience Stores:Fragmented retail networks serve small-scale food processors and tabletop sweetener consumers with limited technical support and higher per-unit pricing.
- Food Service Distributors:Institutional and hospitality channels combine sweetener supply with broader ingredient portfolios, sacrificing specialization for procurement convenience.
Supermarkets dominate branded packaged food supply; online retail is expanding most quickly as mid-tier processors seek cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI clean-label mandates anchor Maharashtra's procurement dominance, while PLI scheme incentives reshape capacity geography across India's sugarcane belt. Western and southern states concentrate beverage manufacturing demand, forcing supplier consolidation around regulatory-compliant partners.
Maharashtra
Pune and Mumbai beverage clusters drive steviol glycoside procurement at triple prior-year volumes for reduced-sugar soft drink lines. FSSAI notification timelines compress competitive windows for formulation claims. Organized retail penetration enables direct-to-manufacturer contracting that bypasses legacy distributor markups.
Gujarat
Ahmedabad and Surat dairy processors scale sucralose sourcing for flavored milk applications. BIS quality specifications for polyol inputs impose certification delays that favor pre-certified suppliers. Large-format retailers consolidate vendor lists around partners with traceability documentation capabilities.
Uttar Pradesh
Meerut and Muzaffarnagar sugar complexes anchor domestic sucrose supply through integrated crushing and refining infrastructure. PLI scheme incentives accelerate capital deployment into natural sweetener extraction capacity. Monsoon-dependent cane yields create price volatility that compresses processor margins.
Karnataka
Bengaluru bakery and confectionery clusters present underpenetrated distribution white space for erythritol and maltitol formulations. Clean-label positioning gains traction in premium biscuit segments. Southern dairy cooperatives expand flavored product portfolios that pull high-intensity sweetener demand.
Tamil Nadu
Chennai food processors accelerate BIS certification timelines to capture shelf space ahead of mandate enforcement. Legacy production lines require extended retrofit cycles to accommodate polyol rheology differences. E-commerce bulk sourcing channels emerge as mid-tier processors seek cost efficiency.
India Food Sweetener Market Competitive Landscape
Integrated sugar processors and global specialty chemical suppliers split the market between commodity sucrose and high-intensity alternatives. Tiered vendor consolidation favors scaled partners with in-house FSSAI compliance infrastructure. Three archetypes dominate: domestic integrated mills with captive cane supply, multinational ingredient houses with regulatory pre-certification, and regional distributors being squeezed from branded supply chains. Competitive moves center on direct contracting displacement of distributor networks and enzymatic bioprocessing capacity expansion.
Among global specialty suppliers, Tate & Lyle PLC and Cargill Incorporated occupy positions anchored by technical service capabilities and crushing infrastructure respectively. Domestic integrated processing is exemplified by Balrampur Chini Mills Ltd., which represents the sucrose-centric archetype with upstream cane control. These three entities sit within a structure where regulatory interpretation capabilities determine vendor list survival.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Ingredion Incorporated |
| Cargill Incorporated |
| Balrampur Chini Mills Ltd. |
| Ajinomoto Co. Inc. |
| Tate & Lyle PLC |
| Kerry Group plc |
| Shree Renuka Sugars Ltd. |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Meerut and Muzaffarnagar sugar complexes in Uttar Pradesh anchor domestic sucrose capacity, with monsoon-dependent cane yields transmitting volatility into processor margins and downstream contract pricing power. PLI scheme incentives for natural sweetener extraction are compressing cost premiums between synthetic and natural-origin alternatives, reshaping procurement negotiations for beverage manufacturers in Maharashtra and Gujarat.
Pricing Analysis
Price spreads between Uttar Pradesh sucrose and imported high-intensity alternatives widen during deficient monsoon cycles, forcing bakery processors toward contract-based long-term offtake structures. Price differentiation hinges on FSSAI certification grade and volume scale, with pre-certified suppliers commanding shelf space premiums. Pricing pressure stems from enzymatic bioprocessing advances collapsing stevia cost structures against incumbent sucralose positioning. Organized beverage manufacturers exhibit lowest price sensitivity due to clean-label mandate compliance requirements, while food service distributors remain most exposed to spot market fluctuations.
Supply Chain Analysis
Tariff exposure between India and ASEAN stevia extract suppliers dominates supply chain risk calculus for natural-origin processors. Domestic supply concentrates in Uttar Pradesh, Maharashtra, and Karnataka, drawing from sugarcane, stevia leaf, and synthetic precursor feedstocks. Single-source vulnerability persists in steviol glycoside extraction enzymes and sucralose process patents controlled by global specialty chemical houses. Distribution runs through direct-to-manufacturer contracting with large-format retailers, displacing legacy distributor networks in western and southern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Maharashtra and Gujarat beverage manufacturers consolidating vendor lists around FSSAI-compliant partners, squeezing unorganized traders from branded supply chains and compressing supplier margins.
For Market Incumbents: Harden regulatory interpretation capabilities through in-house analytical infrastructure investment to defend vendor list positioning against emerging enzymatic bioprocessing specialists. Prioritize backward integration into stevia leaf sourcing across Uttar Pradesh and Bihar to secure input cost stability against monsoon-driven cane volatility. Lock in direct-to-manufacturer contracts with organized retailers before BIS certification timelines close competitive windows. For New Entrants and Emerging Players: Build out Tamil Nadu and Karnataka dairy cooperative relationships as the most penetrable white space for high-intensity sweetener distribution currently served by fragmented channels. Target bakery industry retrofit cycles in Bengaluru and Chennai where 18-24 month production line upgrades create formulation partnership entry points. Lead with e-commerce bulk sourcing platforms to bypass traditional distributor markups and capture mid-tier processor price sensitivity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FSSAI clean-label mandate enforcement timelines will permanently stratify compliant and non-compliant supplier tiers. Acquisition targets should screen for domestic integrated mills with captive cane supply and pre-positioned BIS certification infrastructure. Monitor PLI scheme capital deployment announcements as the inflection signal for natural sweetener extraction capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioprocessing Capacity Expansion | Collapses cost premiums between stevia and synthetic alternatives for Maharashtra beverage processors. |
| Backward Integration into Stevia Cultivation | Secures leaf supply continuity for Uttar Pradesh extraction facilities amid volatile cane economics. |
| FSSAI Pre-Certification Investment | Accelerates product launch timelines ahead of sequential clean-label notification enforcement. |
| Direct-to-Manufacturer Contracting | Bypasses distributor markups for Gujarat and Karnataka large-format retailer supply. |
| BIS Quality Specification Alignment | Eliminates 12-18 month approval delays blocking polyol formulation access in premium bakery segments. |
Research Methodology
Initial hypotheses were tested against primary input from FSSAI regulatory affairs leads, beverage procurement directors, sugar mill operations heads, and bakery R&D formulation specialists and refined through secondary validation against FSSAI notification databases, BIS quality specification records, PLI scheme disbursement filings, and organized retail vendor consolidation announcements. Bottom-up demand modeling across end-use segments was triangulated with top-down supply capacity assessments from integrated crushing and refining infrastructure.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by sweetener chemistry, application functional requirements, and distribution channel access. CAGRs were derived from volume trajectory analysis incorporating PLI scheme incentive impact, FSSAI compliance cost absorption, and enzymatic bioprocessing adoption curves. Industry-specific forecast inputs included monsoon-indexed cane yield projections and BIS certification pipeline velocity.
Practitioners should monitor FSSAI notification release schedules, PLI scheme capital deployment announcements, and monsoon deviation indices for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Muscovado Sugar Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Icing Sugar Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Fructose Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Molasses Market
Sweeteners
Sucralose Market
Sweeteners
Maltodextrin Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Europe Starch Sweetener Market