
 Resistant Maltodextrin Market | 2026-2036
Resistant Maltodextrin Market Size, Share, and Industry Trends Forecast 2026-2036
Resistant Maltodextrin Market Analytics
Modular ingredient bundling is decoupling as food manufacturers seek standalone resistant maltodextrin rather than pre-blended fiber systems. Roquette Frères S.A. leverages its European starch processing heritage to anchor premium-grade supply for pharmaceutical applications. Matsutani Chemical Industry Co., Ltd. dominates Asia-Pacific production through proprietary enzymatic technology developed for soluble fiber conversion. Tate & Lyle PLC extends its ingredient portfolio by competing on clean-label positioning in North American beverage formulations.
Resistant maltodextrin is a soluble dietary fiber produced through controlled enzymatic hydrolysis of starch, yielding glucose polymers with α-1,2 and α-1,3 glycosidic bonds that resist human digestive enzymes while fermenting in the colon. The ingredient typically delivers 90% dietary fiber content on a dry basis and functions as a low-calorie bulking agent, prebiotic substrate, and sugar replacer in reduced-calorie foods. Pulverized and granulated formats lead current volume due to their compatibility with dry-mix applications in baking and confectionery, though liquid variants are gaining traction in dairy and sauce applications where dispersibility without grit determines formulation acceptance. Spray-dried grades command margin premiums for their instant solubility in sports nutrition and clinical nutrition products where mouthfeel consistency overrides cost sensitivity.
FDA's Nutrition Facts labeling rules and EFSA's health claims framework collectively shape product positioning and market access requirements for resistant maltodextrin suppliers seeking dual-territory distribution. China's SAMR enforces GB standards for soluble dietary fiber content claims, creating compliance thresholds that domestic producers like Baolingbao Biology navigate more fluidly than importers. Stakeholders must monitor evolving prebiotic classification debates across regulators, as fiber-specific health claim permissions will determine which end-user segments—pharmaceuticals versus general food—offer sustainable margin expansion.
Market Dynamics
Modular ingredient bundling is decoupling as food manufacturers seek standalone resistant maltodextrin rather than pre-blended fiber systems, forcing suppliers to reposition enzymatic processing capabilities as direct-to-formulator services.
Growth Catalysts
- FDA's updated dietary fiber definition:The clarified regulatory standing under Nutrition Facts labeling rules has removed formulation uncertainty for US-based sports nutrition manufacturers accelerating integration of this soluble fiber.
- Enzymatic hydrolysis technology:Advances in controlled starch processing are expanding production yields while maintaining the α-1,2 and α-1,3 glycosidic bond structures essential for digestive resistance.
- China:Domestic enzymatic processing capacity scaling by producers like Baolingbao Biology is creating concentrated supply hub effects for both local food brands and export markets.
Market Restraints
- Corn starch input volatility:Feedstock price swings tied to agricultural commodity cycles compress margin predictability for enzymatic processors dependent on consistent raw material costs.
- Supply concentration in Asia-Pacific:Proprietary enzymatic technology holders in Japan and China control premium-grade output, creating geographic single-source vulnerability for European and North American formulators.
- Prebiotic classification uncertainty:EFSA's pending determinations on fiber-specific health claim permissions create regulatory friction delaying pharmaceutical-grade product launches in European markets.
Strategic Opportunities
- Clinical nutrition expansion:Spray-dried instant solubility grades command margin premiums in medical foods where mouthfeel consistency overrides cost sensitivity, opening white space beyond sports nutrition.
- SAMR's GB standards compliance:China's soluble dietary fiber content claim thresholds favor domestic producers with fluid regulatory navigation, creating acquisition targets for multinational ingredient portfolios.
- Liquid variant development:Dairy and sauce applications where dispersibility without grit determines formulation acceptance represent underpenetrated segments for hydrolyzed starch derivatives beyond dry-mix dominance.
Industry Challenges
- Enzymatic process engineering talent:Scarcity of specialists capable of optimizing α-amylase and transglucosidase reaction conditions for consistent bond formation slows capacity expansion timelines.
- Dual-territory certification complexity:Simultaneous FDA and EFSA compliance for health claim permissions requires extended validation studies, stretching R&D-to-commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistant Maltodextrin Market |
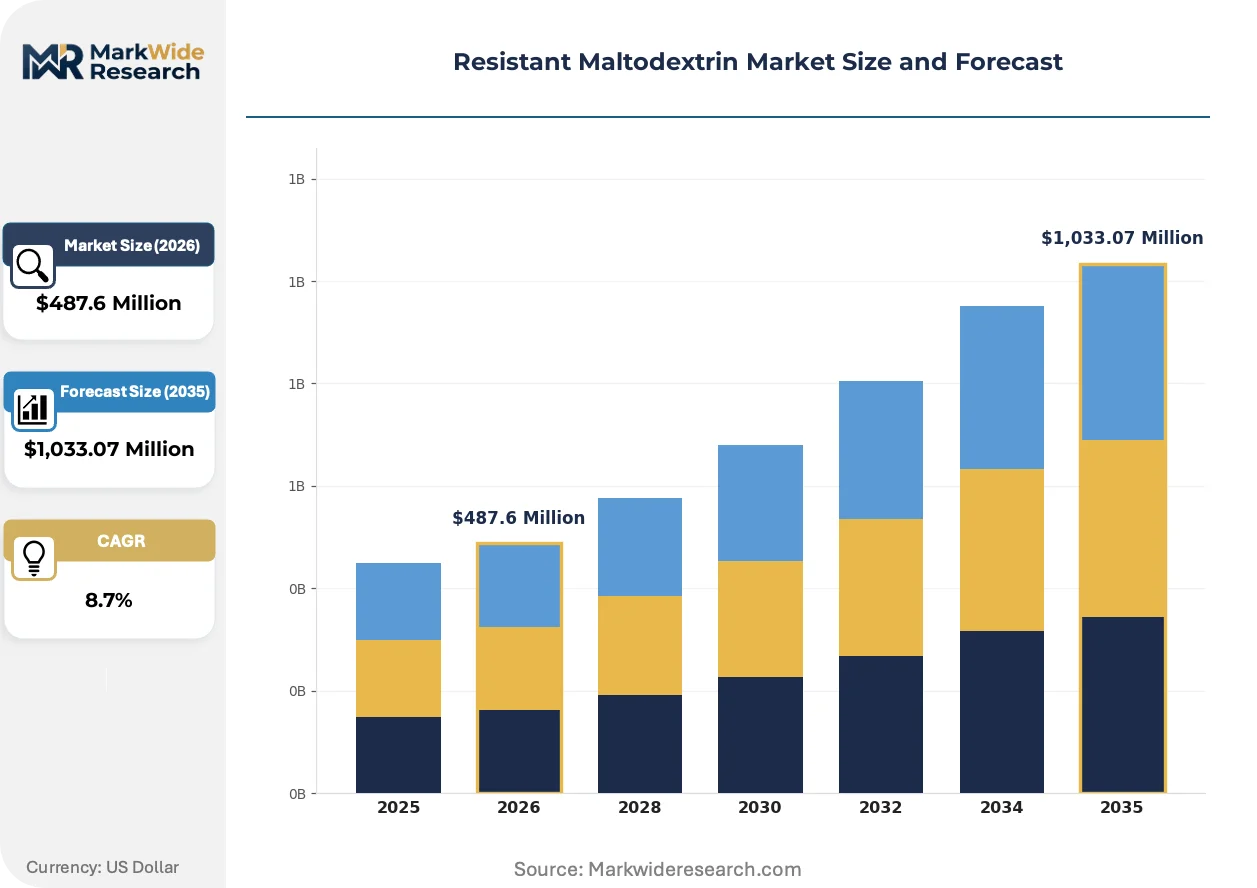
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulverized, Granulated, Liquid, Spray-Dried End User: Food & Beverage, Pharmaceuticals, Dietary Supplements, Sports Nutrition Distribution Channel: Online, Offline, Direct Sales, Retail Application: Baking, Confectionery, Dairy Products, Sauces |
| Companies Covered | Roquette Frères S.A., Cargill Incorporated, Matsutani Chemical Industry Co., Ltd., Baolingbao Biology Co., Ltd., Grain Processing Corporation, Ingredion Incorporated, Archer Daniels Midland Company, Bailong Chuangyuan, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistant Maltodextrin Market Evolving Landscape
Enzymatic processing platforms are fragmenting into specialized service offerings as ingredient suppliers compete on technical differentiation rather than commodity scale.
Precision enzymatic hydrolysis is modularizing resistant maltodextrin production into configurable output specifications. Pharmaceutical formulators in Germany and Switzerland now specify exact glucose polymer chain length distributions for colon fermentation kinetics. This capability unbundling is compressing the traditional premium commanded by integrated starch processors.
EFSA's evolving health claims framework is reshaping product positioning requirements for European market access. Fiber-specific prebiotic classifications now determine whether suppliers target pharmaceutical margins or general food commodity pricing. Clinical nutrition segments in France and Italy are responding with dedicated regulatory affairs functions to secure Article 13.5 claims.
Formulator procurement is consolidating around direct supplier relationships that bypass traditional ingredient distributors. Sports nutrition manufacturers in California and Texas now negotiate enzymatic processing capacity contracts with named output specifications. This disintermediation is most visible in North American beverage formulations where clean-label positioning demands transparent supply chain documentation.
Resistant Maltodextrin Market Segmentation
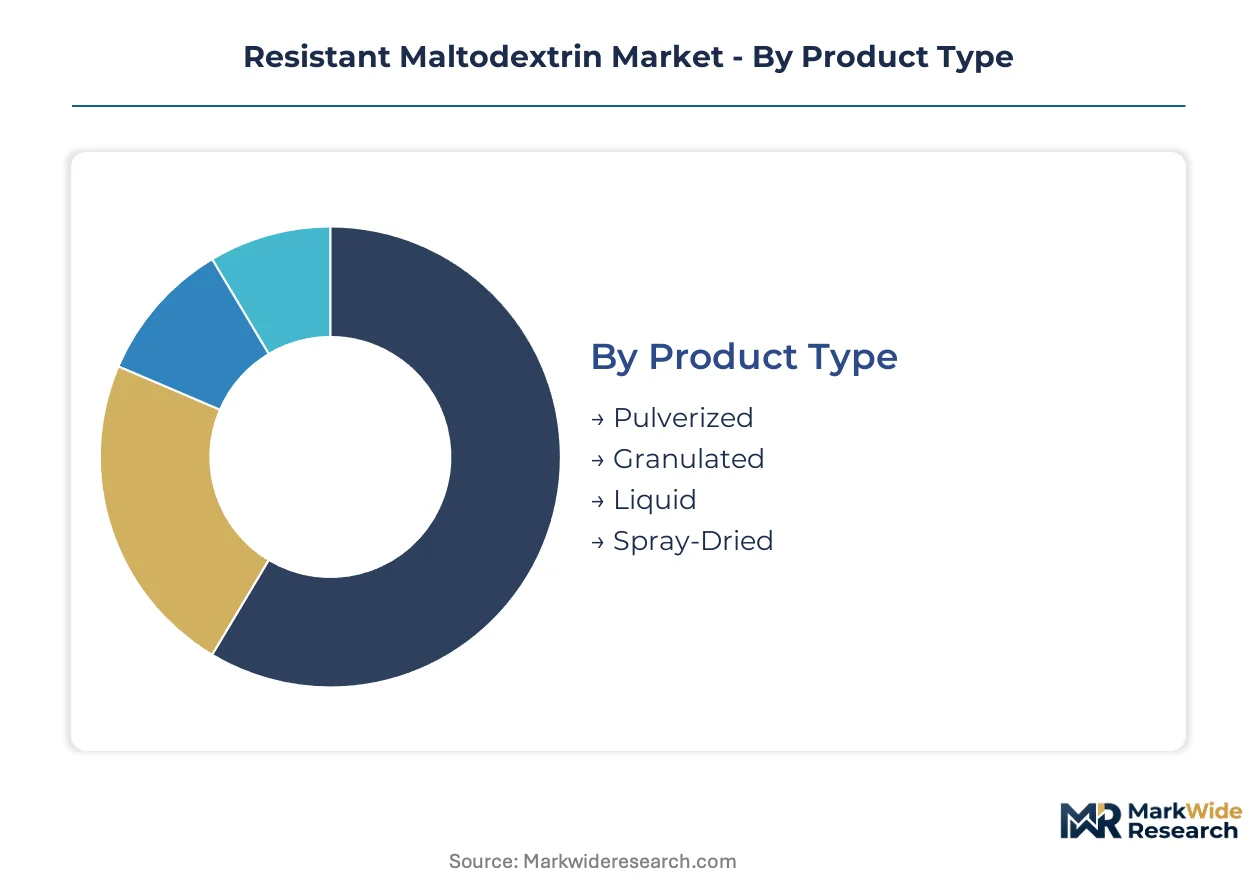
Resistant maltodextrin procurement patterns diverge sharply across format specifications and end-use requirements. Formulators select physical variants based on solubility kinetics, while channel choices reflect supply chain documentation demands for clean-label positioning.
Product Type:
Equipment refresh cycles in dry-mix manufacturing are accelerating format-specific adoption as legacy systems reach replacement thresholds.
- Pulverized:Fine particle size distribution below 100 microns enables homogeneous dispersion in flour-based matrices. Demand clusters in industrial baking operations across Germany and Italy where dust-free handling systems justify powder format premiums despite respiratory safety investments.
- Granulated:Free-flowing agglomerates reduce caking during pneumatic conveying and storage. North American confectionery manufacturers favor this grade for continuous coating lines where uniform particle size prevents segregation in chocolate and compound applications.
- Liquid:Pre-hydrated solutions eliminate dust exposure and reduce batch variability in high-moisture systems. Dairy processors in France specify hydrolyzed starch derivatives for yogurt and beverage bases where instant incorporation without shear heating preserves protein stability.
- Spray-Dried:Rapid reconstitution properties command specification in clinical nutrition and medical foods. Instant solubility without grit formation meets dysphagia-grade requirements in hospital and aged-care formulations.
Volume placements concentrate in Pulverized; the faster expansion belongs to Spray-Dried.
End User:
Cost tier stratification separates commodity fiber buyers from premium-grade pharmaceutical purchasers.
- Food & Beverage:Mass-market reformulation drives bulk procurement of standard-grade resistant maltodextrin for sugar reduction and fiber fortification. Bakery and beverage manufacturers in China integrate enzymatically processed soluble fiber to meet GB standard content claims.
- Pharmaceuticals:cGMP-compliant production with validated chain length distributions supports prebiotic medical food development. German and Swiss formulators specify exact fermentation kinetics for colon-targeted delivery systems.
- Dietary Supplements:Capsule and powder blend applications favor granulated formats for flow properties. US contract manufacturers source standalone fiber to replace pre-blended systems in private-label gut health products.
- Sports Nutrition:Protein-fiber co-formulations demand instant solubility without viscosity build. California-based manufacturers specify spray-dried grades for ready-to-mix applications where mouthfeel consistency determines repeat purchase.
Food & Beverage anchors current volume; Pharmaceuticals climbs the fastest as Article 13.5 health claim validations progress through EFSA.
Distribution Channel:
Customer type fragmentation—multinational formulators versus regional processors—determines channel selection and service intensity.
- Online:Digital procurement platforms serve small-to-mid scale supplement manufacturers seeking transparent documentation. Japanese and South Korean buyers utilize B2B marketplaces for technical-grade resistant maltodextrin with batch-specific certificates.
- Offline:Traditional ingredient distributors maintain inventory positions for just-in-time bakery and confectionery operations. European regional distributors stock multiple grades to service mixed-product portfolios.
- Direct Sales:Named-supplier contracts bypass intermediaries for enzymatic processing capacity with output specifications. North American beverage formulators negotiate direct relationships to secure clean-label supply chain transparency.
- Retail:Packaged consumer fiber supplements reach end-users through pharmacy and health store channels. Finished goods positioning emphasizes prebiotic benefits on front-of-pack labeling.
Offline channels dominate current placements; Direct Sales gains share fastest as procurement consolidation accelerates.
Application:
Supply concentration in enzymatic processing hubs shapes regional application specialization.
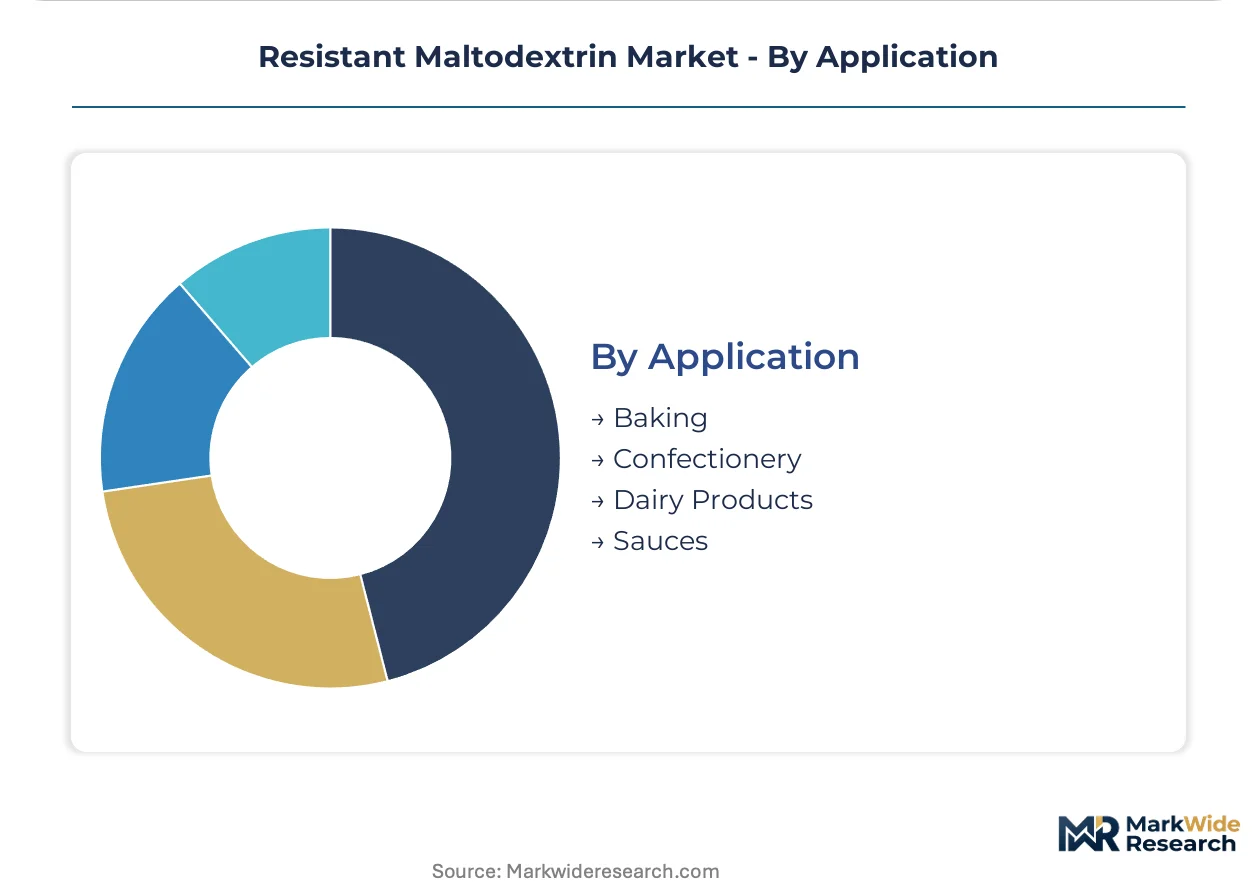
- Baking:Water-binding and crumb softening functions replace traditional hydrocolloids in reduced-calorie bread. Italian and Spanish industrial bakeries specify resistant maltodextrin for clean-label fiber claims without gluten matrix disruption.
- Confectionery:Low-calorie bulking maintains texture in sugar-free chocolates and gummies. Swiss and Belgian manufacturers utilize granulated grades for precision dosing in continuous enrobing operations.
- Dairy Products:Fermented milk applications leverage prebiotic fermentation for synbiotic positioning. French yogurt producers integrate liquid variants for homogeneous distribution without grit.
- Sauces:Viscosity modification and caloric reduction in pourable dressings and condiments. US foodservice manufacturers specify hydrolyzed starch derivatives for stable emulsions under refrigerated distribution.
Baking holds the largest volume position; Dairy Products shows the steepest expansion trajectory as synbiotic formulation proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzymatic processing capacity concentrates in Asia-Pacific while formulation demand clusters in Western Europe and North America, creating a trade-dependent supply architecture. China and Japan anchor production output through proprietary starch hydrolysis platforms. Germany, Switzerland, and the United States drive premium-grade consumption in pharmaceutical and clinical nutrition segments.
China
Domestic food brands and export markets absorb expanding enzymatic processing output from Shandong Province producers. SAMR's GB standards for soluble dietary fiber content claims create compliance thresholds that domestic manufacturers navigate with regulatory fluency unavailable to importers. Baolingbao Biology scales production capacity in Dezhou to serve both local bakery reformulation and international sports nutrition contracts.
Japan
Proprietary enzymatic technology development for soluble fiber conversion sustains premium-grade supply dominance. METI industrial standards shape fermentation-derived ingredient quality benchmarks that differentiate Japanese output from commodity alternatives. Osaka-based chemical processors supply spray-dried instant solubility grades to European pharmaceutical formulators seeking validated chain length distributions.
Germany
cGMP-compliant pharmaceutical formulators in Baden-Württemberg specify exact glucose polymer chain length distributions for colon-targeted delivery systems. EFSA's pending Article 13.5 health claim determinations delay product launches while extending validation study timelines. Heidelberg and Mannheim clusters attract contract manufacturing investment for medical foods targeting dysphagia-grade requirements.
Switzerland
Precision fermentation kinetics specification drives pharmaceutical-grade procurement from domestic and cross-border suppliers. Swissmedic medical food regulations enforce documentation standards that filter commodity fiber from premium-tier sourcing pools. Basel pharmaceutical corridors integrate resistant maltodextrin into synbiotic formulations for hospital and aged-care distribution.
United States
California and Texas sports nutrition manufacturers negotiate direct enzymatic processing capacity contracts with named output specifications. FDA's clarified dietary fiber definition under Nutrition Facts labeling rules removed formulation uncertainty for US-based brands accelerating integration. Clean-label positioning demands in North American beverage formulations drive transparent supply chain documentation requirements.
Resistant Maltodextrin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure shaped by enzymatic processing capability depth. The vendor base separates into three strategic archetypes: integrated starch processors with backward agricultural supply control, enzymatic technology licensors monetizing proprietary conversion platforms, and regional toll manufacturers serving formulation-specific output contracts. Capacity expansion and direct-to-formulator relationship building represent the dominant competitive moves as ingredient bundling decouples.
Within the integrated processor tier, Roquette Frères S.A. and Cargill Incorporated anchor European and North American supply respectively through captive starch sourcing infrastructure. Matsutani Chemical Industry Co., Ltd. exemplifies the enzymatic technology licensor archetype, occupying a position where proprietary conversion platforms command specification-driven premiums. Tate & Lyle PLC sits within the formulation-partnership specialist category, competing on clean-label positioning transparency for North American beverage customers. These three company types collectively represent the competitive vectors reshaping procurement consolidation around direct supplier relationships.
| Leading Market Players |
|---|
| Roquette Frères S.A. |
| Cargill Incorporated |
| Matsutani Chemical Industry Co., Ltd. |
| Baolingbao Biology Co., Ltd. |
| Grain Processing Corporation |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Bailong Chuangyuan |
| Tate & Lyle PLC |
| Others |
Value Network & Pricing Analysis
Enzymatic process engineering specialists in Osaka and Shandong Province command wage premiums that propagate through spray-dried grade pricing, widening the spread between pharmaceutical-tier and food-grade resistant maltodextrin by roughly one-third. Labor-cost differentials between Japanese precision fermentation clusters and Chinese commodity-scale facilities anchor the three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Cost-down pressure on standard-grade material accelerates because corn starch feedstock volatility compresses margin buffers for toll manufacturers without captive agricultural supply. Three-tier pricing structure across premium, standard, and economy levels separates cGMP-validated pharmaceutical grades from food-grade powders and unbranded commodity hydrolysates. Certification tier—specifically FDA GRAS self-affirmation versus EFSA Article 13.5 health claim validation—drives the steepest price differentiation. Food and beverage manufacturers exhibit highest price sensitivity, while clinical nutrition formulators accept premiums for documented chain length distributions.
Supply Chain Analysis
Direct-to-formulator channels handle sports nutrition and pharmaceutical demand, bypassing traditional ingredient distributors for transparent supply chain documentation. Production gravity centers on China, Japan, and Germany, with proprietary enzymatic technology holders in Osaka and Shandong controlling premium-grade output. Raw material dependencies rest on corn starch from North American and Brazilian agricultural supply, plus specialized α-amylase and transglucosidase enzyme preparations. Single-source vulnerability for European and North American formulators creates structural risk, as geographic concentration of enzymatic processing capacity limits alternative sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained enzymatic processing capacity props pricing power for incumbent technology holders, with talent scarcity in precision fermentation engineering extending lead times for new entrants.
For Market Incumbents: Lock in formulator-direct relationships by offering named-output specification contracts that preempt distributor intermediation, while adding spray-dried capacity in Dezhou or Osaka to capture pharmaceutical-tier margin expansion. Defensive positioning requires deepening backward integration into corn starch sourcing to buffer agricultural commodity cycles, and securing EFSA Article 13.5 claim validations ahead of competitors to anchor premium positioning. For New Entrants and Emerging Players: FDA's clarified dietary fiber definition under Nutrition Facts labeling rules opens a window for US-based toll manufacturers to serve California and Texas sports nutrition brands seeking domestic enzymatic processing alternatives to Asian supply. Liquid variant development for French dairy and US foodservice sauce applications represents the most penetrable white space, with clean-label supply chain transparency as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic technology licensors given EFSA's pending prebiotic classification determinations as a catalyst for pharmaceutical-grade margin expansion. Long-term viability favors acquisition targets with validated cGMP production and existing health claim submissions, particularly Chinese domestic producers with fluid SAMR GB standards navigation. The signal to watch is EFSA's Article 13.5 opinion publication timeline for resistant maltodextrin-specific prebiotic claims.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Dezhou and Osaka facilities capture pharmaceutical-grade margin premiums as clinical nutrition demand accelerates. |
| Backward Integration into Corn Starch | Captive agricultural supply buffers Roquette Frères and Cargill against commodity price volatility compressing toll processor margins. |
| EFSA Article 13.5 Health Claim Validation | Regulatory approval pathway separates premium pharmaceutical-tier suppliers from commodity food-grade competitors in European markets. |
| Direct-to-Formulator Channel Development | Bypassing traditional distributors meets California sports nutrition clean-label documentation requirements for transparent supply chains. |
| Liquid Variant Formulation Partnerships | Collaboration with French dairy processors penetrates synbiotic yogurt segments where dispersibility without grit determines specification. |
Research Methodology
Document review covered FDA GRAS notifications, EFSA health claim applications, SAMR GB standard filings, and enzymatic processing patent landscapes, complemented by interviews with plant managers at starch hydrolysis facilities, procurement leads at North American sports nutrition manufacturers, regulatory affairs directors navigating dual-territory certification, and technical R&D heads specifying chain length distributions. Secondary validation drew from customs trade data for resistant maltodextrin flows, SEC 10-K filings of diversified ingredient conglomerates, and Japanese METI industrial production statistics. Bottom-up capacity assessments and top-down demand modeling were triangulated against cross-referenced primary intelligence.
Output specifications across pulverized, granulated, liquid, and spray-dried formats were modeled against end-use segmentation in food and beverage, pharmaceuticals, dietary supplements, and sports nutrition, with distribution channel dynamics incorporated throughout the forecast period. CAGRs were derived from elasticity-adjusted volume projections and value-tier pricing trajectories. Key inputs included enzymatic processing yield curves, corn starch price correlation coefficients, and regulatory approval timeline assumptions for prebiotic health claim permissions.
The model assumes a particular technology adoption path; alternative pathways for precision enzymatic hydrolysis with novel transglucosidase variants would alter the outlook for chain length distribution specifications and fermentation kinetics. Forecasts reflect documented assumptions on SAMR enforcement consistency and EFSA opinion timelines, with periodic stress-testing of base assumptions recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South America Food Sweetener Market
Sweeteners
Galactose Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Date Sugar Market
Sweeteners
Muscovado Sugar Market
Sweeteners
China Allulose Market
Sweeteners
Sanding Sugar Market
Sweeteners
Food Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Natural Stevia Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Citrus Molasses Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Sugar Beet Juice Extract Market