
 North America Starch Sweetener Market | 2026-2036
North America Starch Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
North America Starch Sweetener Market Analytics
Product bundling between liquid glucose and maltodextrin portfolios is hardening procurement patterns among large beverage and bakery buyers. Ingredion Incorporated leverages its corn wet milling network to sustain supply security across Midwest production facilities. Cargill, Incorporated anchors volume through direct sales relationships with multinational food accounts. Tate & Lyle PLC differentiates via specialty dextrose grades for pharmaceutical applications.
North America starch sweeteners comprise glucose polymers, fructose-enriched syrups, and oligosaccharides derived from enzymatic hydrolysis of corn, wheat, or potato starch, typically specified by dextrose equivalent values ranging from 20 to 100 DE for controlled sweetness, viscosity, and humectancy in processed foods. High fructose corn syrup retains the largest revenue pool due to entrenched beverage industry contracts, though maltodextrin exhibits the fastest structural expansion as clean-label bulking agents displace traditional sweeteners in sports nutrition and infant formula formulations.
The FDA governs starch sweetener labeling through added-sugar disclosure mandates and GRAS notification pathways, while the USDA influences demand via school nutrition standards and commodity procurement programs for federal food assistance. Health Canada and the PMRA coordinate cross-border residue and purity standards that shape import-export flows between U.S. and Canadian processing facilities. Stakeholders must monitor evolving federal biofuel policy and its competition for corn feedstock, as ethanol blend mandates directly tighten starch raw material availability for sweetener production.
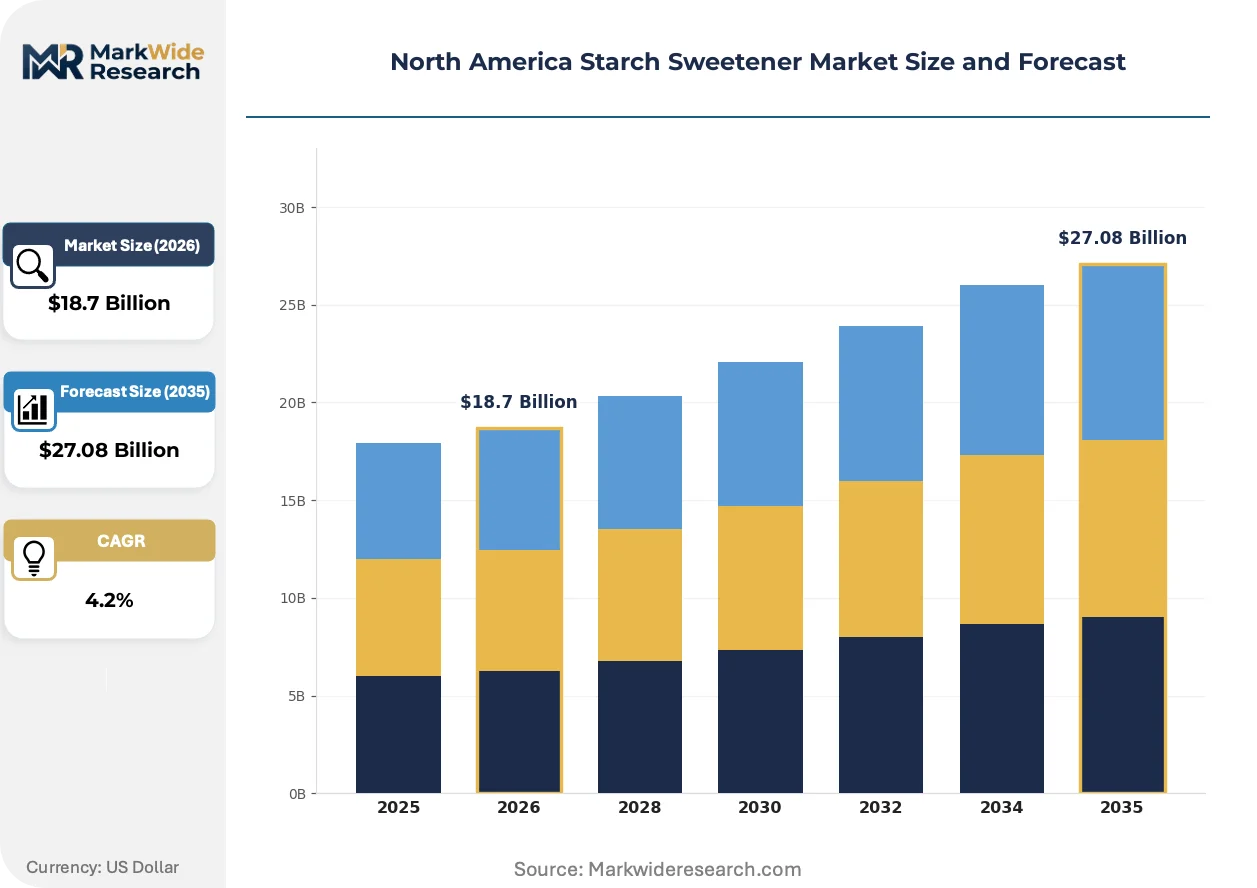
Market Dynamics
Beverage reformulation mandates and FDA added-sugar disclosure rules are compressing refined sugar demand while redirecting procurement toward enzymatically modified starch sweeteners across U.S. and Canadian manufacturing corridors.
Growth Catalysts
- Clean-label bulking agents:Maltodextrin is displacing traditional sweeteners in sports nutrition and infant formula as manufacturers seek reduced-sugar claims without sacrificing mouthfeel or shelf stability.
- FDA nutrition labeling overhaul:Updated added-sugar disclosure requirements are accelerating ingredient substitution decisions among packaged food and beverage producers.
- Great Lakes manufacturing corridor:Concentrated corn processing infrastructure and beverage industry headquarters clustering creates procurement efficiencies and supply security advantages.
Market Restraints
- Corn feedstock competition:Federal ethanol blend mandates tighten starch raw material availability as biofuel policy diverts corn supply away from sweetener production.
- Cross-border regulatory friction:Health Canada and PMRA residue and purity standards create compliance complexity for integrated U.S.-Canadian processing networks.
- Fructose substitution pressure:Allulose and rare sugar alternatives threaten high fructose corn syrup volumes in reduced-calorie beverage segments.
Strategic Opportunities
- Pharmaceutical-grade dextrose:Injectable and parenteral nutrition applications command premium pricing as compounding pharmacy standards tighten.
- Canadian prairie wheat starch:Underutilized Prairie processing capacity offers geographic diversification from corn-dependent U.S. Midwest supply.
- School nutrition procurement:USDA commodity programs for federal food assistance create institutional volume anchors resistant to consumer trend volatility.
Industry Challenges
- Enzyme engineering talent scarcity:Specialized biochemists capable of optimizing glucoamylase and pullulanase performance command compensation premiums that compress facility margins.
- Retrofitting legacy wet mills:Converting aging facilities for specialty maltodextrin grades requires capital deployment timelines that conflict with quarterly earnings pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Starch Sweetener Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Dextrose, Maltodextrin, Liquid Glucose Application: Beverages, Bakery Products, Confectionery, Dairy Products End User: Food & Beverage Industry, Pharmaceutical Sector, Cosmetic Industry, Animal Feed Distribution Channel: Direct Sales, E-commerce, Wholesalers, Retail Stores |
| Companies Covered | Tate & Lyle PLC, Grain Processing Corp, Ingredion Incorporated, SC Foods Co., Ltd., Tereos Starch & Sweeteners, Cargill, Incorporated, Roquette Frères, Sweetener Products Co., The Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Starch Sweetener Market Evolving Landscape
Enzymatic hydrolysis precision and continuous processing automation are compressing production economics while enabling dextrose equivalent customization that legacy batch systems cannot achieve.
Precision enzyme engineering is rewriting starch conversion economics. Custom glucoamylase blends now enable manufacturers to target specific DE values within tighter tolerances than commodity enzyme cocktails permit. Beverage and bakery technical teams are adopting these tailored biocatalysts to reduce off-flavors and improve process consistency. The technology is rewriting competitive positioning by rewarding facilities with in-house enzyme optimization capabilities over those dependent on generic supplier formulations.
The FDA added-sugar disclosure mandate is forcing label architecture redesigns across packaged food portfolios. Manufacturers must now aggregate all free sugars and syrups under a single line item, making high fructose corn syrup concentration visually prominent to consumers. Beverage category managers are responding with stealth reformulation—blending maltodextrin with high-potency sweeteners to maintain sweetness perception while reducing declared added-sugar totals.
Direct supplier relationships are displacing distributor intermediaries among multinational food accounts. Large buyers are consolidating procurement through single-source technical partnerships that bundle liquid glucose, maltodextrin, and specialty dextrose grades under unified specification management. This concentration is most visible in the U.S. Great Lakes corridor, where beverage headquarters proximity to corn wet milling infrastructure enables just-in-time delivery contracts that inventory-heavy distributors cannot match.
North America Starch Sweetener Market Segmentation
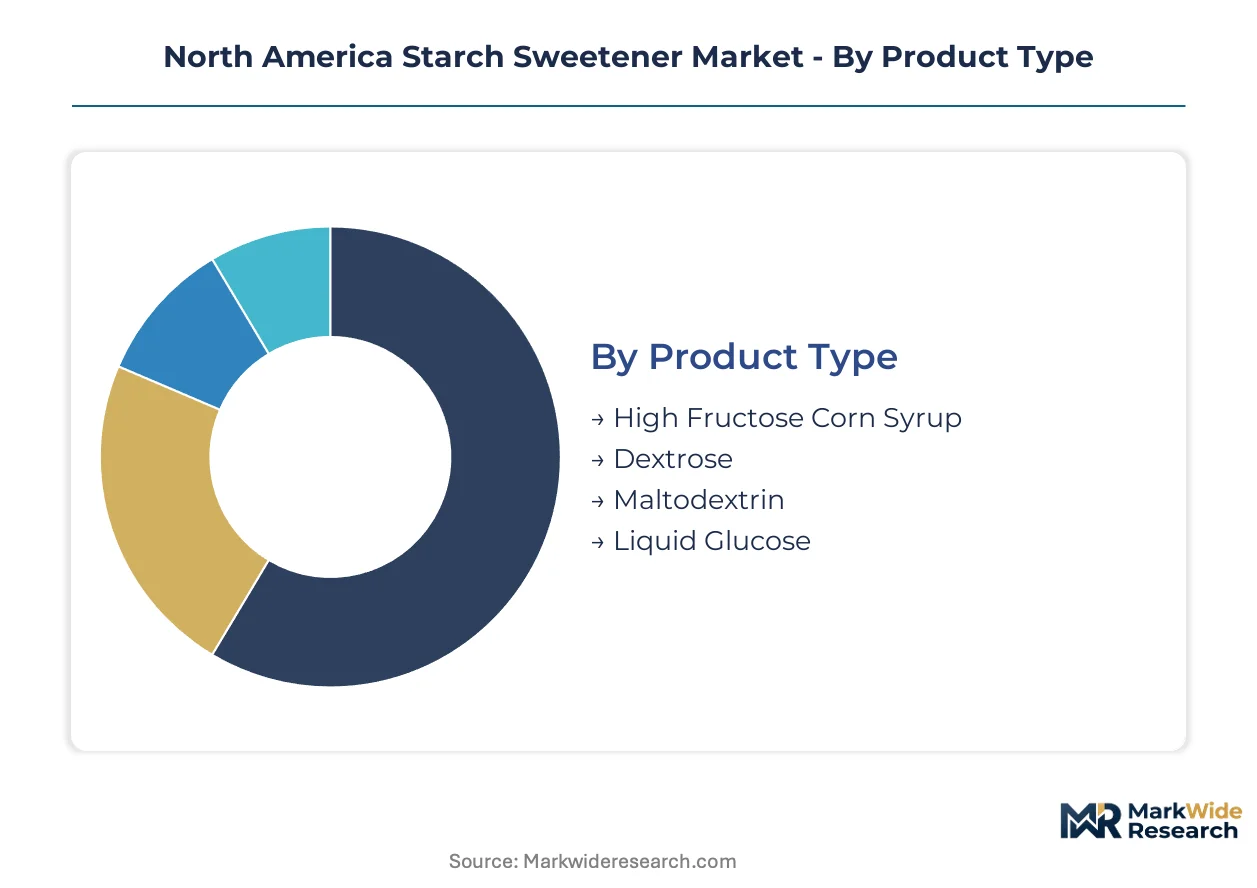
Starch sweetener procurement patterns diverge sharply between commodity volume plays and specification-driven premium tiers. Buyers segment their supplier relationships by application sensitivity, with beverage contracts demanding supply security while pharmaceutical accounts prioritize certification depth.
Product Type:
Volume concentration separates entrenched beverage sweeteners from emerging clean-label alternatives, with margin structures inverting across the DE specification range.
- High Fructose Corn Syrup:Fructose-enriched syrups produced through enzymatic isomerization of glucose, typically standardized at 42% or 55% fructose content for controlled sweetness intensity. Procurement concentrates in the U.S. Great Lakes corridor where beverage industry headquarters cluster near corn wet milling infrastructure, though FDA added-sugar disclosure mandates are compressing declared usage rates in reformulated portfolios.
- Maltodextrin:Glucose polymers ranging from 3 to 20 DE valued for bulking functionality without excessive sweetness contribution. Sports nutrition and infant formula manufacturers across the U.S. Midwest and Canadian Prairie regions are displacing traditional sweeteners with maltodextrin to achieve reduced-sugar label claims while preserving mouthfeel and shelf stability.
- Dextrose:Crystalline glucose monohydrate specified by pharmaceutical compendia for parenteral nutrition and injectable applications.
- Liquid Glucose:Viscous syrup intermediates bridging starch hydrolysis and finished sweetener production.
Mature deployment sits with High Fructose Corn Syrup in carbonated beverage supply chains. Newer deployment is concentrated in Maltodextrin as clean-label formulation accelerates.
Application:
End-use differentiation tracks regulatory exposure, with federally monitored categories demanding documentation depth that private-label retail channels bypass.
- Beverages:The largest demand pool spanning carbonated soft drinks, sports drinks, and flavored waters where sweetness perception must balance caloric reduction targets. Reformulation programs at U.S. and Canadian headquarters locations are redirecting procurement toward enzymatically modified syrups that reduce refined sugar totals while maintaining consumer taste acceptance.
- Bakery Products:Humectancy and browning control drive starch sweetener selection in industrial bread and cake manufacturing. Large bakery buyers in the U.S. Great Lakes region are consolidating procurement through bundled liquid glucose and maltodextrin contracts that specification-managed distributors struggle to match.
- Confectionery:Controlled crystallization and texture modification for hard candies and chewing gum applications.
- Dairy Products:Fermentation substrates and sweetness modulation in flavored milk and yogurt production.
Established formulation patterns dominate Beverages. Bakery Products represent the fastest-moving application tier as clean-label bread claims proliferate.
End User:
Customer type determines specification stringency, with cGMP requirements separating pharmaceutical procurement from commodity food purchasing.
- Food & Beverage Industry:The foundational demand base spanning multinational manufacturers and regional processors. Direct supplier relationships are displacing distributor intermediaries among large accounts consolidating liquid glucose, maltodextrin, and specialty dextrose under unified technical partnerships.
- Pharmaceutical Sector:Injectable and parenteral nutrition applications command premium pricing as USP-grade dextrose monohydrate requirements tighten. Compounding pharmacy standards and FDA enforcement patterns are concentrating procurement among facilities with dedicated pharmaceutical production lines.
- Cosmetic Industry:Humectant and viscosity-modifying applications in personal care formulations.
- Animal Feed:Palatability enhancement and energy density in livestock and pet nutrition.
Volume leadership resides with Food & Beverage Industry procurement networks. Pharmaceutical Sector specifications are climbing the fastest as parenteral nutrition standards tighten.
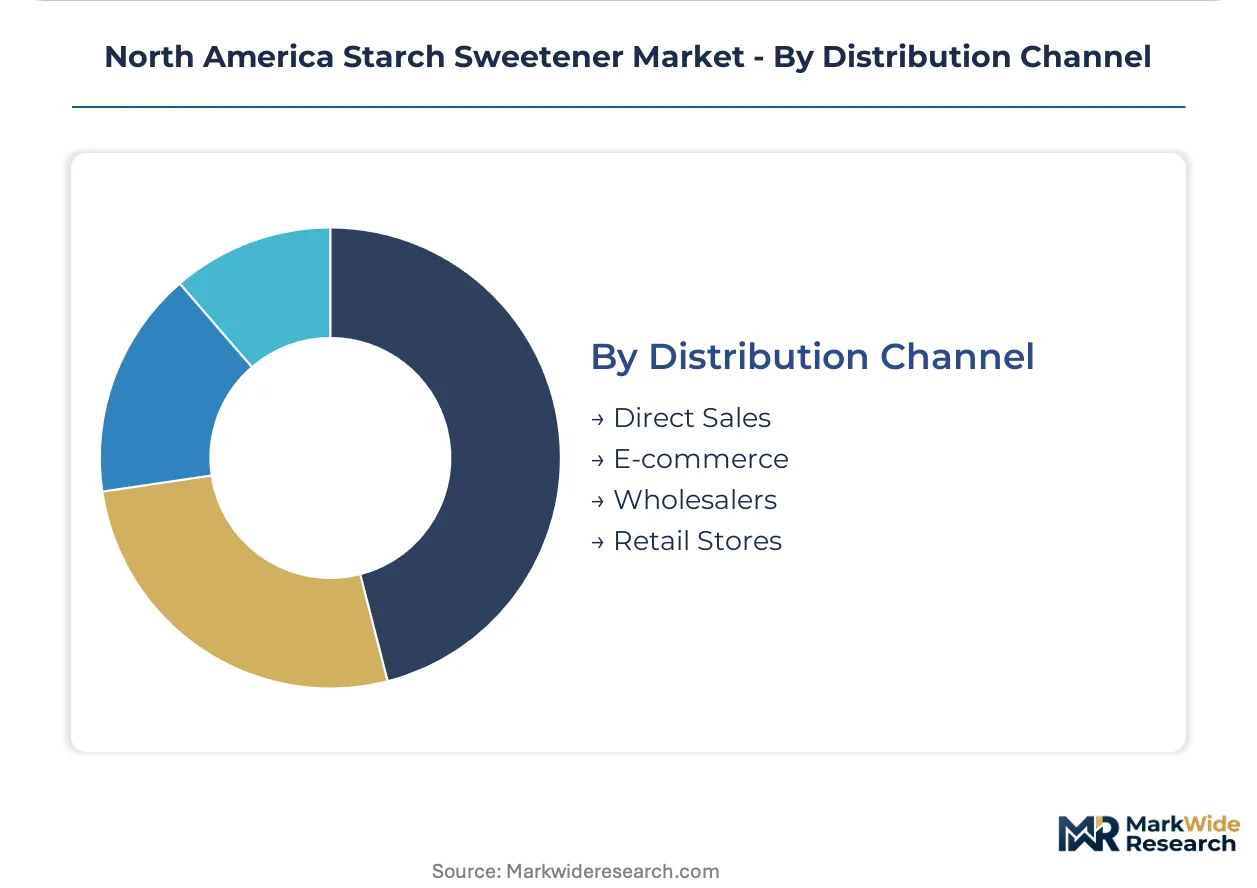
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with proximity to corn processing infrastructure enabling direct relationships.
- Direct Sales:Technical partnership models bundling multiple sweetener grades under unified specification management. Multinational food accounts in the U.S. Great Lakes corridor leverage headquarters proximity to Midwest wet milling facilities for just-in-time delivery contracts.
- Wholesalers:Inventory aggregation serving mid-tier processors lacking volume to justify direct mill relationships.
- E-commerce:Specification documentation and sample fulfillment for niche and startup formulations.
- Retail Stores:Consumer-packaged glucose and specialty starch products for small-scale foodservice.
Direct Sales infrastructure anchors large-account procurement. E-commerce channels are expanding most quickly as formulation startups seek flexible minimum order quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Great Lakes manufacturing corridor anchors North American starch sweetener production through concentrated corn wet milling infrastructure and proximity to beverage industry headquarters. Federal biofuel policy and FDA labeling mandates are reshaping procurement patterns across integrated U.S.-Canadian processing networks.
United States
Beverage reformulation programs and FDA added-sugar disclosure rules are accelerating ingredient substitution decisions among packaged food manufacturers. The USDA influences demand through school nutrition standards and commodity procurement programs for federal food assistance. The Great Lakes corridor—spanning Illinois, Indiana, and Michigan—hosts clustered corn processing facilities serving just-in-time delivery contracts with multinational beverage accounts.
Canada
Health Canada and the PMRA coordinate cross-border residue and purity standards that shape import-export flows between U.S. and Canadian processing facilities. The Canadian Prairie provinces offer underutilized wheat starch processing capacity as geographic diversification from corn-dependent U.S. Midwest supply. Toronto and Montreal serve as distribution hubs for pharmaceutical-grade dextrose serving parenteral nutrition applications.
Mexico
Beverage manufacturing expansion in central Mexico is driving regional demand for liquid glucose and high fructose corn syrup as multinational brands localize production. Mexican regulatory alignment with U.S. FDA standards facilitates cross-border supply chain integration for integrated North American accounts. The Bajío region and Mexico City metro area concentrate formulation facilities serving both domestic consumption and export markets.
North America Starch Sweetener Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North America starch sweetener market. The vendor base organizes around three strategic archetypes: integrated agribusiness conglomerates with captive corn supply, specialty ingredient pure-plays targeting pharmaceutical and nutrition applications, and regional processors leveraging geographic proximity to end-use clusters. Dominant competitive moves include backward integration into corn origination and capacity expansion for specialty maltodextrin grades.
Among integrated agribusiness conglomerates, Cargill, Incorporated and Ingredion Incorporated exemplify the scale-driven archetype through their Midwest corn wet milling networks. Tate & Lyle PLC occupies a position within the specialty pure-play tier, differentiating via specification depth for pharmaceutical-grade dextrose. These three anchors represent contrasting strategic postures—commodity volume security versus premium specification management—within a market where procurement consolidation favors direct technical partnerships over distributor intermediaries.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Grain Processing Corp |
| Ingredion Incorporated |
| SC Foods Co., Ltd. |
| Tereos Starch & Sweeteners |
| Cargill, Incorporated |
| Roquette Frères |
| Sweetener Products Co. |
| The Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
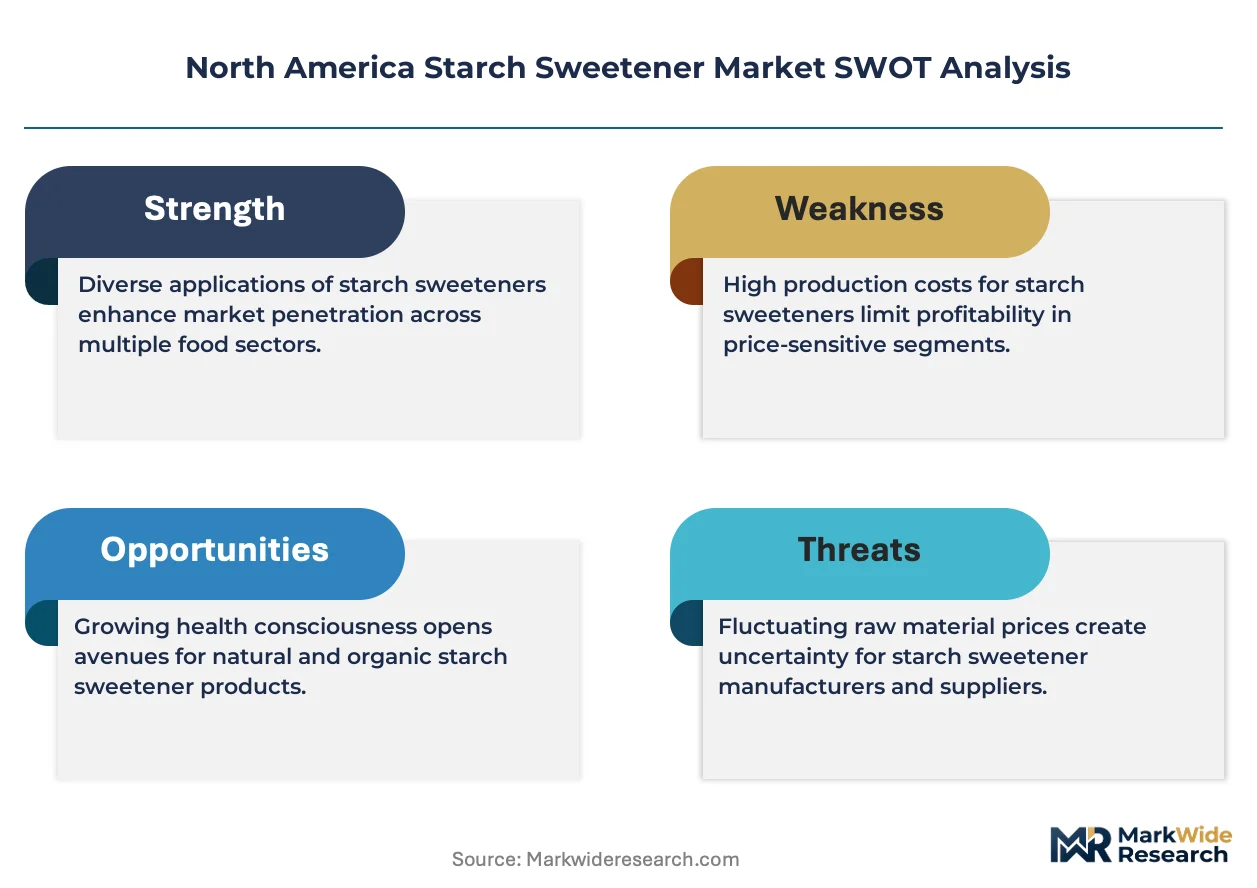
Multinational beverage procurement consolidation in the U.S. Great Lakes corridor anchors contract-based long-term offtake pricing with volume-tier discounts that commodity spot buyers cannot access. FDA added-sugar disclosure mandates and ethanol blend policy competition for corn feedstock create asymmetric cost pressure across buyer tiers.
Pricing Analysis
Short lead-time premiums of 15-20% apply to pharmaceutical-grade dextrose orders outside standard quarterly contracting cycles, while spot maltodextrin inventory clears at discounted rates during harvest-season corn supply surges. Three-tier pricing structure across premium pharmaceutical certification, standard food-grade specifications, and economy feed-grade tiers separates buyers by documentation depth and purity requirements. Cost compression in standard food-grade syrups is intensifying because beverage reformulation programs are shrinking high fructose corn syrup contract volumes. Regional bakery cooperatives exhibit the highest price sensitivity due to thin margins and limited specification flexibility, while parenteral nutrition compounders show minimal sensitivity given patient-safety liability exposure.
Supply Chain Analysis
Corn supply rests on U.S. Midwest harvests, Canadian Prairie wheat starch alternatives, and limited Mexican sorghum processing that diversifies mono-crop dependency. Enzyme biocatalysts, wet milling equipment, and crystallization infrastructure constitute the critical input trinity with limited second-source availability. Single-source vulnerability concentrates in specialty glucoamylase suppliers whose optimization capabilities determine facility yield differentials. Distribution runs through direct mill-to-plant pipeline contracts for large accounts, with regional wholesalers filling mid-tier processor gaps and e-commerce platforms serving formulation startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around procurement scale advantages as FDA labeling mandates and enzyme talent scarcity force sub-scale facilities toward exit or acquisition.
For Market Incumbents: Deploy backward integration into corn origination and captive enzyme engineering capabilities to defend margin position against allulose substitution threats in reduced-calorie beverages. Expand specialty maltodextrin capacity in the Canadian Prairie provinces to diversify geographic supply exposure from ethanol policy-driven corn tightness in the U.S. Midwest. For New Entrants and Emerging Players: Precision enzyme engineering partnerships with university biochemistry departments offer a technology-first wedge against incumbent generic biocatalyst dependence. Target pharmaceutical-grade dextrose compounding pharmacy supply as the most penetrable segment given tightening USP standards that incumbent commodity mills struggle to meet without dedicated production line investment. For Investors and Strategic Acquirers: The window for entry favors specialty pure-plays with pharmaceutical certification depth over commodity volume players facing structural demand compression. Long-term viability hinges on reformulation tailwinds in sports nutrition and infant formula that outlast beverage sector volatility. Watch Health Canada-PMRA regulatory harmonization progress as the signal indicating cross-border processing network integration feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Cargill and Ingredion captive supply networks neutralize ethanol mandate-driven feedstock competition. |
| Specialty Maltodextrin Capacity Expansion | Clean-label sports nutrition demand outpaces legacy high fructose corn syrup infrastructure depreciation schedules. |
| Pharmaceutical-Grade Certification Investment | USP-grade dextrose monohydrate production lines command 40-60% pricing premiums over food-grade specifications. |
| Direct Technical Partnership Consolidation | Multinational beverage accounts bypass distributor intermediaries for unified liquid glucose-maltodextrin specification management. |
| Prairie Wheat Starch Geographic Diversification | Underutilized Canadian processing capacity reduces corn-dependent U.S. Midwest supply concentration risk. |
Research Methodology
Document review covered FDA GRAS notification filings, USDA commodity procurement program records, and Health Canada-PMRA cross-border residue standards, complemented by interviews with corn wet milling plant managers, beverage category procurement directors, pharmaceutical compounding pharmacy operators, and enzyme biocatalyst technical specialists. Secondary validation drew from SEC 10-K disclosures of integrated agribusiness conglomerates, American Chemistry Council starch industry reports, and U.S. Energy Information Administration ethanol production data. Bottom-up facility capacity modeling and top-down demand segmentation triangulation anchored volume and value estimates.
Historical production capacity utilization rates were cross-referenced against panel input from procurement executives at multinational food accounts to calibrate demand elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type by dextrose equivalent specification, application by regulatory exposure tier, end user by certification stringency, and distribution channel by buyer scale and technical service requirements. CAGRs were derived from weighted average of trend extrapolation and scenario-adjusted growth assumptions, with corn feedstock competition intensity and beverage reformulation program velocity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden biofuel policy reversals, novel rare sugar commercialization breakthroughs, and trade barrier disruptions affecting U.S.-Canada integrated processing networks. Forecasts reflect documented assumptions about enzyme engineering talent availability and continued FDA enforcement patterns on added-sugar disclosure. A small set of named triggers warrants ongoing watch: Health Canada regulatory harmonization progress, Prairie wheat starch processing utilization rates, and pharmaceutical-grade dextrose spot pricing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Smoked Sugar Market
Sweeteners
Xylose Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Methyl Glucose Market
Sweeteners
Corn Sweeteners Market
Sweeteners
France Food Sweetener Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Low-Fat Sugar Market