
 Natural Sweetener Blends Market | 2026-2036
Natural Sweetener Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Sweetener Blends Market Analytics
Food formulation chemists with dual expertise in sensory science and glycemic response modeling is redrawing competitive boundaries in natural sweetener blends. Cargill leverages its vertically integrated stevia supply chain from South American cultivation to finished extract. Tate & Lyle PLC anchors European demand through its proprietary Reb M stevia technologies. Ingredion competes by specializing in monk fruit-erythritol combinations for beverage applications.
Natural sweetener blends combine two or more non-caloric or low-caloric sweetening agents—typically steviol glycosides, mogrosides from monk fruit, or sugar alcohols like erythritol—to achieve sucrose-like taste profiles while minimizing aftertaste and glycemic impact. These formulations rely on precise ratios, often 50-300 times sweeter than sucrose on a weight basis, requiring bulking agents to maintain functional properties in baked and liquid products. Stevia-based blends occupy the largest volume position due to regulatory acceptance across major food agencies and established agricultural supply chains. Monk fruit extracts represent the fastest-expanding product type as cultivation expands in Guangxi province and extraction yields improve. Erythritol blends command premium positioning in keto and diabetic-targeted products where cooling effects and crystallization behavior prove critical.
The FDA's enforcement of added-sugar disclosure on Nutrition Facts panels and the EFSA's novel food authorization requirements for stevia derivatives shape product development timelines and market access conditions. FSSAI in India and China's NMPA maintain divergent purity standards for glycoside content that fragment international formulation strategies. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and anticipate how front-of-pack warning labels in Latin American markets could redirect blend composition priorities.
Market Dynamics
Beverage reformulation mandates from FDA and EFSA are compressing development cycles for natural sweetener blends, forcing simultaneous optimization of taste masking, bulking functionality, and glycemic labeling claims.
Growth Catalysts
- EFSA Novel Food Authorization:Streamlined pathways for steviol glycoside derivatives accelerate European product launches and reduce regulatory lag for blend innovators.
- Diabetic-targeted foodservice:Institutional dining operators in the United States specify low-glycemic sweetener systems for menu compliance with healthcare procurement standards.
- Enzymatic bioconversion:Biosynthesis of rare steviol glycosides like Reb M reduces agricultural land requirements and stabilizes input costs for high-purity extracts.
Market Restraints
- Stevia leaf supply concentration:Cultivation clusters in Paraguay and China expose processors to climate volatility and geopolitical trade friction.
- Monk fruit extraction yield limits:Mogroside recovery rates from Siraitia grosvenorii fruit constrain volume scalability despite expanding Guangxi province acreage.
- FSSAI purity standard divergence:India's glycoside content thresholds differ from Codex Alimentarius, forcing duplicate analytical validation for export-bound formulations.
Strategic Opportunities
- Brazil ANVISA front-of-pack warnings:Mandatory sugar disclosure labels redirect CPG formulation priorities toward natural sweetener blends in Latin America's largest processed food market.
- Keto bakery expansion:Erythritol-allulose combinations address crystallization and browning gaps in sugar-free artisan bread and pastry applications.
- Direct-to-beverage-manufacturer supply:Ingredient houses bypass traditional distribution tiers by co-lending formulation scientists to brand R&D facilities.
Industry Challenges
- Sensory-formulation chemist scarcity:Dual expertise in flavor chemistry and glycemic response modeling commands premium compensation and extends hiring timelines.
- Clean-label certification backlog:Third-party non-GMO and organic verification queues delay product launches by six to twelve months.
- Legacy sugar infrastructure retrofit costs:Dry blending equipment designed for crystalline sucrose requires modification to handle hygroscopic natural sweetener powders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Sweetener Blends Market |
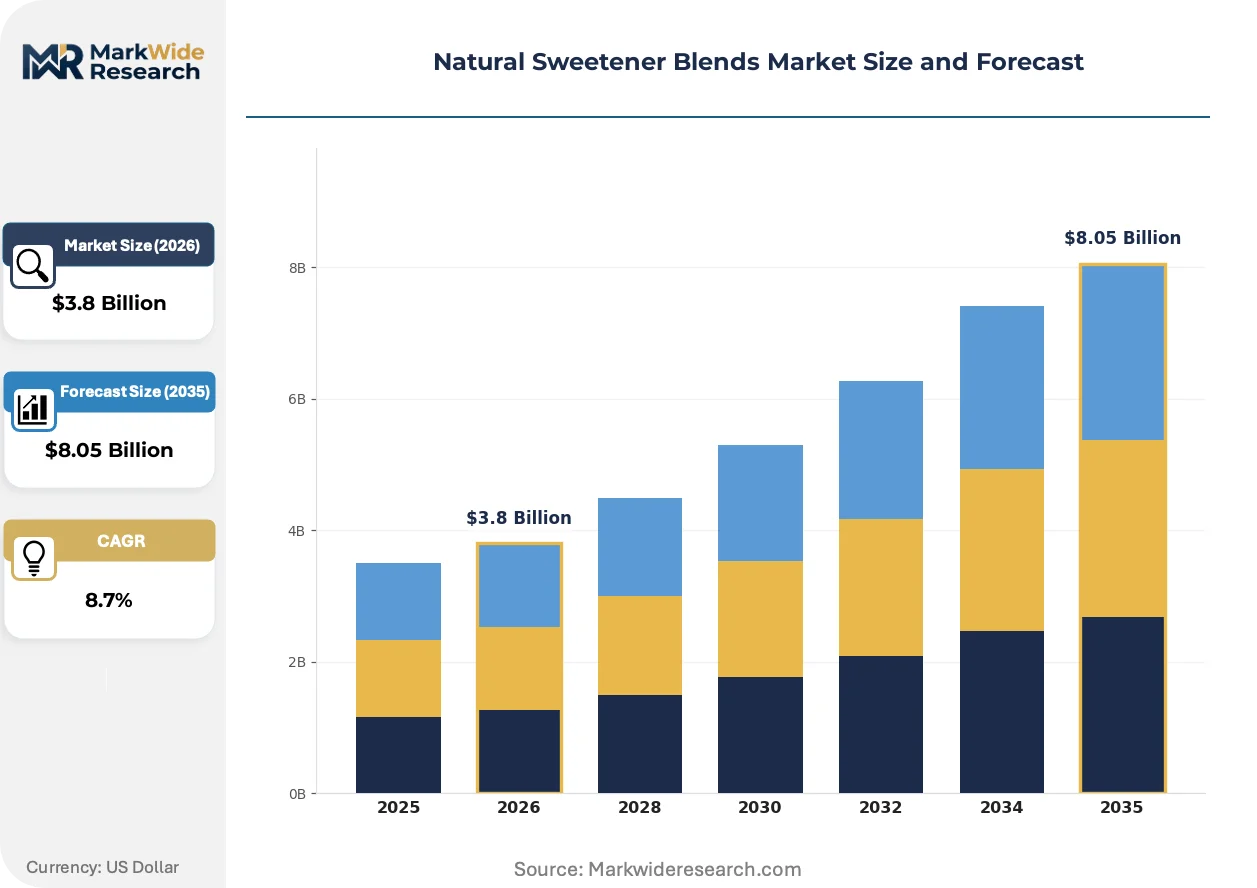
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Monk Fruit, Agave Syrup, Erythritol Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Bakeries, Healthcare Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Whole Earth Sweetener Co., LLC, Steviva Ingredients, GLG Lifetech Corporation, Cargill, Archer Daniels Midland Company, Tate & Lyle PLC, Ingredion, Lantic Inc., Bayn Europe AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Sweetener Blends Market Evolving Landscape
Precision fermentation and enzymatic bioprocessing are collapsing the cost curve for rare glycoside production, while regulatory labeling mandates force simultaneous innovation across taste engineering and nutritional claim substantiation.
Biosynthetic Reb M production via microbial fermentation is decomposing the traditional agricultural supply chain for high-purity steviol glycosides. Beverage manufacturers in North America and Western Europe are adopting these ingredients at accelerating rates for zero-sugar carbonated and still drinks. This technology is compressing price premiums between commodity stevia extracts and rare glycoside variants, eroding the historical cost barrier to clean-label sugar replacement.
EFSA's tightened specifications for steviol glycoside specifications in novel food applications is extending safety dossier requirements for new molecular variants. European blend manufacturers must now generate chronic toxicity data packages that add eighteen to twenty-four months to product approval timelines. Premium positioned brands are responding by concentrating R&D investment on established glycoside combinations rather than unproven molecular structures.
Brand procurement teams are consolidating sweetener supplier relationships from multi-source commodity purchasing to single-partner co-development agreements. Large beverage and dairy processors now embed ingredient scientists within supplier technical service organizations to compress formulation iteration cycles. This pattern is most pronounced in the United States, where clean-label competitive pressure demands simultaneous launch coordination across multiple product lines.
Natural Sweetener Blends Market Segmentation
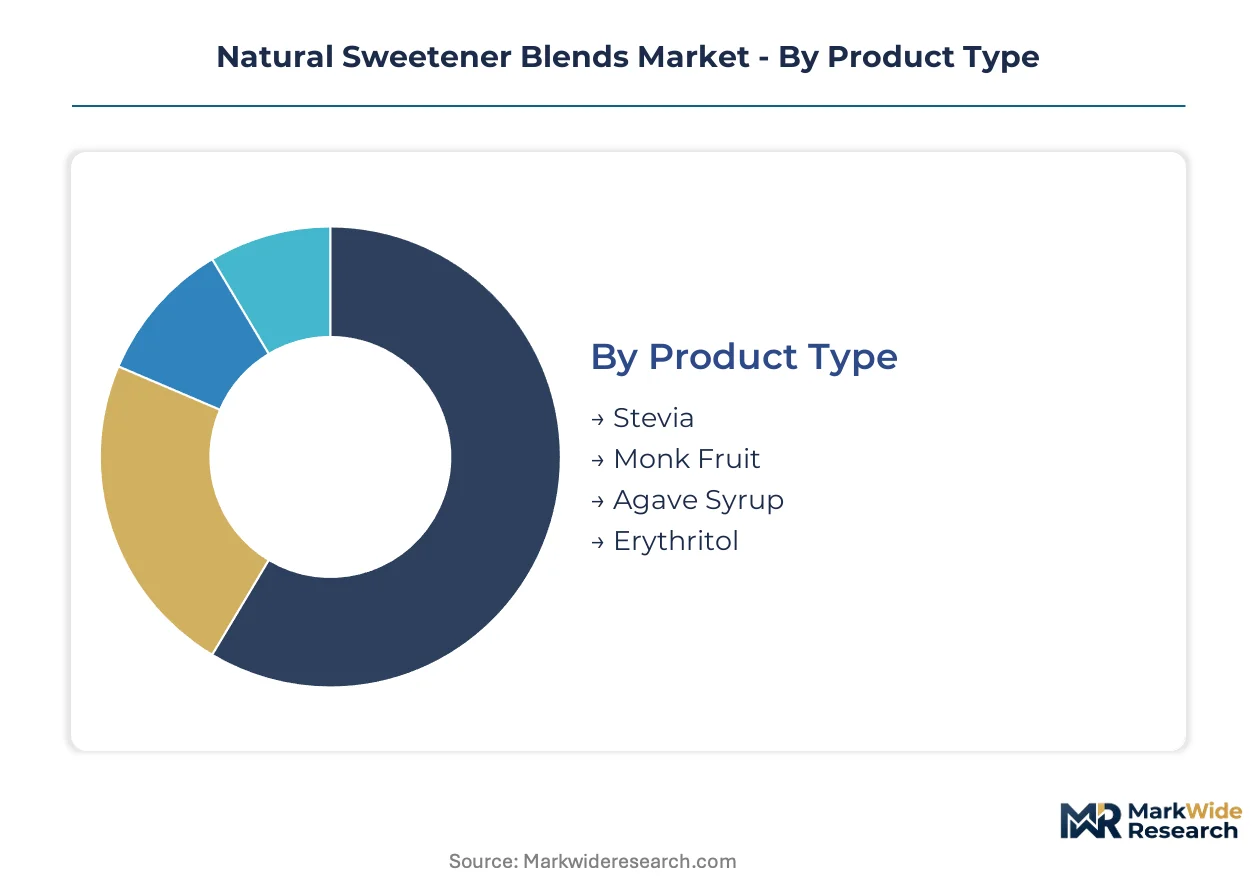
Natural sweetener blend formulation requires precise alignment between glycoside specifications and end-use functional demands. Regulatory thresholds for steviol glycoside purity diverge across FDA, EFSA, and FSSAI jurisdictions, forcing segment-specific compliance strategies.
Product Type:
Regulatory differentiation in glycoside authorization thresholds steers procurement toward approved molecular variants in each jurisdiction.
- Stevia:Reb A and Reb M glycosides dominate beverage applications due to established FDA GRAS status and EFSA novel food clearance. EFSA's tightened chronic toxicity dossier requirements now favor established glycosides over experimental variants, compressing approval timelines for conventional extracts.
- Monk Fruit:Mogrosides from Siraitia grosvenorii supply chains in Guangxi province are expanding cultivation acreage, though extraction yield constraints limit volume scalability. FSSAI maintains divergent purity thresholds from Codex Alimentarius, fragmenting export formulation strategies for Indian-bound products.
- Agave Syrup:Inulin-rich fructooligosaccharide blends serve prebiotic-positioned dairy applications with lower glycemic indexing than sucrose.
- Erythritol:Sugar alcohol crystallization properties anchor keto-targeted bakery segments where cooling effects and Maillard reaction suppression prove critical.
Stevia handles the majority of throughput; monk fruit is the fastest mover on share.
Application:
Cost tier stratification separates premium clean-label positioning from commodity sugar replacement in mass-market categories.
- Beverages:Carbonated and still drink manufacturers compress development cycles to meet FDA added-sugar disclosure mandates. Enzymatic bioconversion of rare glycosides reduces agricultural input costs for zero-sugar portfolios.
- Bakery:Erythritol-allulose combinations address browning and moisture retention gaps in artisan bread applications. Bulking agent requirements drive higher per-unit formulation costs than liquid applications.
- Dairy:Fermented product pH stability demands limit glycoside selection to acid-tolerant variants.
- Confectionery:Hard candy and chocolate tempering requirements favor sugar alcohol blends with precise crystallization control.
Beverages command the largest formulation volume; bakery is expanding most quickly as keto positioning penetrates retail channels.
End User:
Customer type concentration among multinational CPGs concentrates R&D investment in co-development partnerships with ingredient houses.
- Food Manufacturers:Procurement teams consolidate supplier relationships from multi-source commodity purchasing to single-partner technical service agreements.
- Beverage Producers:Embedded formulation scientists at supplier facilities compress iteration cycles for simultaneous multi-line launches.
- Bakeries:Artisan and industrial segments diverge on clean-label certification requirements and price elasticity.
- Healthcare:Institutional dining operators in the United States specify low-glycemic systems for menu compliance with healthcare procurement standards.
Food manufacturers anchor volume demand; healthcare procurement is climbing the fastest on specification intensity.
Distribution Channel:
Supply concentration in direct-to-manufacturer technical service bypasses traditional distribution tiers for formulation-critical accounts.
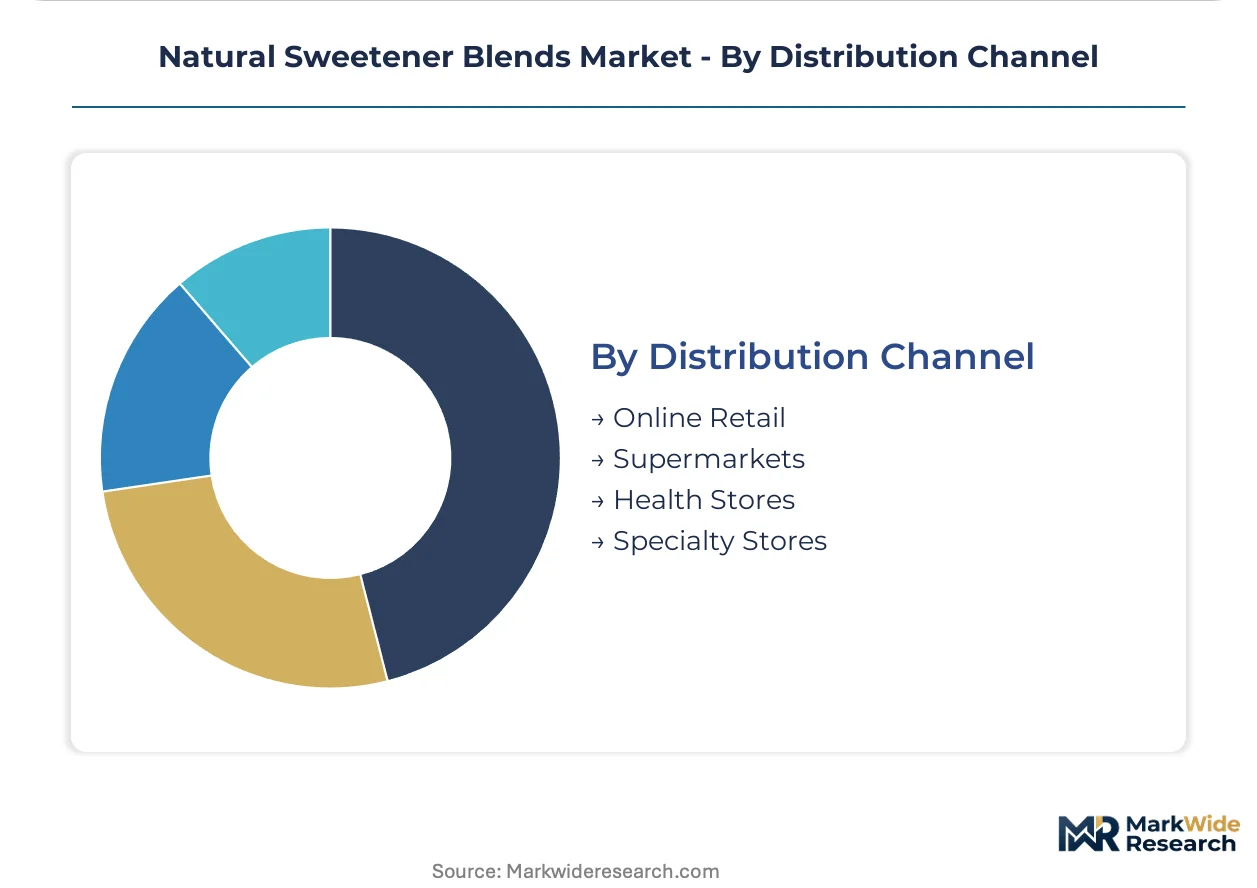
- Online Retail:Direct-to-consumer erythritol and monk fruit powders serve keto and diabetic self-formulation segments with subscription replenishment models.
- Supermarkets:Mass-market stevia tabletop sweeteners compete on price-per-serving equivalence to sucrose.
- Health Stores:Premium organic and non-GMO certified blends command shelf space through third-party verification badges.
- Specialty Stores:Professional bakery and beverage supply channels provide technical specification sheets for commercial formulation.
Supermarkets move the highest unit volumes; online retail is gaining share fastest on subscription retention metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of added-sugar disclosure on Nutrition Facts panels anchors United States demand, while EFSA novel food pathways and divergent FSSAI standards fragment formulation strategies across jurisdictions. Procurement teams navigate multi-regulatory compliance as clean-label pressure intensifies.
United States
Beverage manufacturers accelerate zero-sugar carbonated drink launches under FDA added-sugar labeling mandates. Institutional dining operators specify low-glycemic sweetener systems for healthcare procurement compliance. Chicago and Minneapolis host embedded formulation scientists from ingredient houses compressing R&D iteration cycles.
Germany
EFSA novel food authorization requirements for steviol glycoside derivatives compress European product launch timelines. Chronic toxicity dossier standards now favor established glycoside combinations over experimental variants. Hamburg and Frankfurt concentrate blend manufacturing technical service operations for CPG co-development partnerships.
China
NMPA maintains divergent purity standards for glycoside content that complicate export-bound formulation strategies. Guangxi province cultivation expansion drives monk fruit mogroside supply growth despite extraction yield constraints. Shanghai and Guangzhou anchor stevia leaf processing clusters serving domestic beverage reformulation demand.
India
FSSAI glycoside content thresholds differ from Codex Alimentarius, forcing duplicate analytical validation for export formulations. Domestic clean-label dairy and beverage segments drive stevia blend procurement from multinational ingredient suppliers. Mumbai and Bangalore concentrate food manufacturer R&D facilities navigating multi-jurisdictional compliance.
Brazil
ANVISA front-of-pack sugar warning labels redirect CPG formulation priorities toward natural sweetener blends in Latin America's largest processed food market. Beverage and dairy processors accelerate reduced-sugar portfolio development under mandatory disclosure requirements. São Paulo anchors technical service operations for regional blend customization.
Natural Sweetener Blends Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the natural sweetener blends market. Vertically integrated agricultural processors command supply security advantages in stevia leaf sourcing, while specialized bioconversion firms occupy rare glycoside production niches. Three archetypes dominate: integrated agribusiness conglomerates, enzymatic bioprocessing specialists, and regional formulation service providers. Competitive moves concentrate on co-development partnerships embedding scientists at customer R&D facilities and backward integration into captive agricultural supply.
Within the integrated agribusiness tier, Cargill and Tate & Lyle PLC exemplify supply chain control strategies spanning cultivation through finished extract production. Ingredion occupies a position among formulation specialists emphasizing monk fruit-erythritol combinations for beverage applications. These three anchors represent divergent strategic postures: agricultural supply security, proprietary bioconversion technology, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Whole Earth Sweetener Co., LLC |
| Steviva Ingredients |
| GLG Lifetech Corporation |
| Cargill |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Ingredion |
| Lantic Inc. |
| Bayn Europe AB |
| Others |
Value Network & Pricing Analysis
Scale economies in stevia leaf processing concentrate pricing power among vertically integrated extractors operating multi-tonne purification facilities in Paraguay and China. This concentration anchors price floors for commodity Reb A extracts while enzymatic bioconversion of rare glycosides compresses premiums between standard and high-purity tiers.
Pricing Analysis
Geographic price spreads between Paraguayan field extracts and Chinese-refined high-purity glycosides reflect freight differentials and FSSAI purity validation costs. Three-tier pricing structure across premium rare-glycoside, standard Reb A, and economy-grade stevia extracts stratifies procurement by application sensitivity. Cost compression in commodity stevia stems from Guangxi province cultivation expansion and biosynthetic Reb M fermentation scale-up. Beverage manufacturers exhibit lowest price sensitivity due to co-development contract structures, while artisan bakeries face acute margin pressure from bulking agent requirements.
Supply Chain Analysis
Container availability constraints on the Shanghai-Santos trade lane elevate inbound logistics costs for Brazilian beverage processors sourcing Chinese-refined monk fruit extracts. Stevia leaf supply concentrates in Paraguay and China, while monk fruit cultivation clusters in Guangxi province. Raw material dependencies span steviol glycoside-rich leaf biomass, mogroside-bearing Siraitia grosvenorii fruit, and corn-derived erythritol feedstock. Single-source vulnerability in Paraguayan leaf procurement exposes processors to climate volatility. Distribution runs through direct-to-manufacturer technical service agreements that bypass traditional ingredient distribution tiers for formulation-critical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among multinational beverage and dairy CPGs has shifted negotiating leverage toward buyers capable of embedding scientists at supplier R&D facilities. This buyer-power concentration rewards ingredient houses with co-development capabilities and punishes commodity-only extractors.
For Market Incumbents: Consolidate supplier relationships into captive stevia leaf sourcing through backward integration into Paraguayan cultivation cooperatives or Chinese processing joint ventures. Biosynthetic Reb M fermentation capacity represents the priority defensive investment against agricultural supply volatility. EFSA chronic toxicity dossier requirements favor established glycoside combinations over experimental variants, reducing R&D risk for incumbents with approved molecular portfolios. For New Entrants and Emerging Players: Technical service gaps in artisan bakery formulation support present the most penetrable white-space opportunity, as incumbents concentrate R&D investment on high-volume beverage accounts. Keto-targeted erythritol-allulose blends for browning-critical bread applications offer segment entry with lower regulatory burden than novel glycoside authorization. Direct co-location of formulation chemists at regional bakery R&D facilities provides differentiated go-to-market positioning against distributor-dependent competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic bioprocessing specialists with demonstrated microbial fermentation scale-up capabilities over legacy agricultural extractors. Long-term viability across the analysis window hinges on biosynthetic rare glycoside cost curves collapsing below field-extracted equivalents. Acquisition target archetype: bioconversion firms with validated Reb M production strains and existing beverage manufacturer offtake agreements. The signal to watch is FDA novel food petition filings for non-steviol glycoside sweeteners indicating regulatory pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Scale-Up | Biosynthetic Reb M production collapses agricultural land requirements for high-purity stevia extracts. |
| Backward Integration into Cultivation | Captive Paraguayan leaf supply secures glycoside input cost stability against climate volatility. |
| Co-Development Partnership Expansion | Embedded formulation scientists at CPG R&D facilities compress product launch iteration cycles. |
| Regulatory Dossier Consolidation | EFSA novel food authorization investments favor established glycosides over experimental variants. |
| Regional Technical Service Hubs | São Paulo and Bangalore facilities enable localized blend customization for ANVISA and FSSAI compliance. |
Research Methodology
The analysis maps stevia extract, monk fruit concentrate, and sugar alcohol blend sub-sectors, each validated through formulation chemists, procurement directors at beverage manufacturers, and regulatory affairs specialists at ingredient houses. Primary interviews with sensory scientists, glycemic response modelers, and clean-label certification auditors combined with secondary validation from FDA GRAS notices, EFSA novel food opinions, FSSAI glycoside standards, and customs trade data. Bottom-up volume estimates triangulate against top-down category spending analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include glycoside type, application functional requirements, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from installed capacity expansion trajectories, patent filing trends in enzymatic bioconversion, and beverage manufacturer reformulation announcement tracking. Industry-specific forecast inputs incorporate Guangxi province monk fruit acreage expansion rates and EFSA chronic toxicity study completion timelines.
Material uncertainties — regulatory authorization delays for novel glycoside variants, climate disruption in Paraguayan cultivation zones, and front-of-pack warning label expansion beyond Brazil — sit outside the modeled envelope. Forecasts reflect assumptions about enzymatic bioprocessing cost reduction trajectories and clean-label procurement standard diffusion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Africa Stevia Market
Sweeteners
Mannitol Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
India Food Sweetener Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Erythritol Market
Sweeteners
Sugar Market
Sweeteners
Xylose Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
China Allulose Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Xylitol Injection Market