
 Vegan Salad Dressing Market | 2026-2036
Vegan Salad Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Salad Dressing Market Analytics
Specialty grocery retail is reshaping how vegan salad dressing reaches consumers, with natural-product chains and online subscription services commanding shelf space once held by conventional supermarkets. Sir Kensington's leverages premium positioning through clean-label formulations to sustain price premiums in crowded condiment aisles. Follow Your Heart anchors West Coast distribution density while Primal Kitchen competes on paleo-aligned ingredient credentials across national club-store channels.
Vegan salad dressing comprises emulsified or separated oil-and-acid preparations formulated without egg yolk, dairy derivatives, or honey, typically stabilized using plant-based gums, modified starches, or mustard flour to achieve pourable or spoonable viscosity. These products serve commercial foodservice and retail consumers seeking allergen-free, cholesterol-free alternatives to traditional dressings. Balsamic and ranch variants occupy the largest volume positions, while tahini-based formulations represent the fastest-growing sub-segment driven by Mediterranean dietary patterns and sesame-allergen labeling clarity. Bottle packaging dominates retail velocity, though pouch formats gain traction in foodservice portion-control applications and single-serve meal-kit integrations.
FDA labeling requirements for plant-based claims and EFSA novel-food assessments for emerging protein emulsifiers create compliance thresholds that favor established manufacturers with regulatory affairs capacity. EU Green Deal agricultural sourcing standards and California Proposition 65 chemical disclosure rules add layer costs for imported ingredient supply chains. Stakeholders must monitor evolving definitions of "vegan" across jurisdictions, as inconsistent legal standards threaten cross-border formulation uniformity and brand positioning coherence.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are compressing ingredient declarations while foodservice operators accelerate plant-based menu integration, forcing manufacturers to reformulate emulsion systems without traditional stabilizers.
Growth Catalysts
- Fast-casual chain expansion:Restaurant operators including Sweetgreen and Cava are standardizing vegan dressing SKUs across regional footprints, creating pull-through demand for bulk-format stabilized emulsions.
- EU Green Deal sourcing standards:Agricultural certification requirements for imported oils are favoring European domestic sunflower and rapeseed processors over Mediterranean olive oil dependence.
- Modified starch innovation:Cold-water-swelling waxy maize derivatives from Ingredion and Cargill are replacing gum arabic in cost-optimized retail formulations, improving pour viscosity stability.
Market Restraints
- Sesame seed price volatility:Tahini base materials face supply disruption from Ethiopian and Sudanese crop cycles, compressing margins on Mediterranean-positioned SKUs.
- Single-source gum dependency:Locust bean harvest concentration in Morocco and Spain creates emulsifier supply risk for clean-label formulations avoiding xanthan.
- California Proposition 65 litigation:Acrylamide and heavy metal disclosure requirements for roasted seed ingredients impose compliance costs disproportionately on smaller craft producers.
Strategic Opportunities
- Meal-kit channel integration:Blue Apron and HelloFresh are requesting single-serve pouch formats with 90-day ambient stability, opening contract manufacturing demand for retort-capable processors.
- India FSSAI vegan labeling:New Delhi's pending definition of plant-based claims creates first-mover advantage for exporters establishing local formulation standards ahead of domestic competitor maturation.
- Precision fermentation emulsifiers:Convergence of synthetic biology with lipid chemistry promises egg-free lecithin replacements with superior oxidative stability for extended-shelf retail.
Industry Challenges
- Food technologist scarcity:Formulation expertise in plant-protein stabilization and clean-label rheology modification commands premium compensation, constraining R&D throughput at mid-tier manufacturers.
- Dual certification timelines:Simultaneous USDA Organic and Non-GMO Project verification processes extend product launch cycles by 8-14 months, delaying revenue recognition on reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Salad Dressing Market |
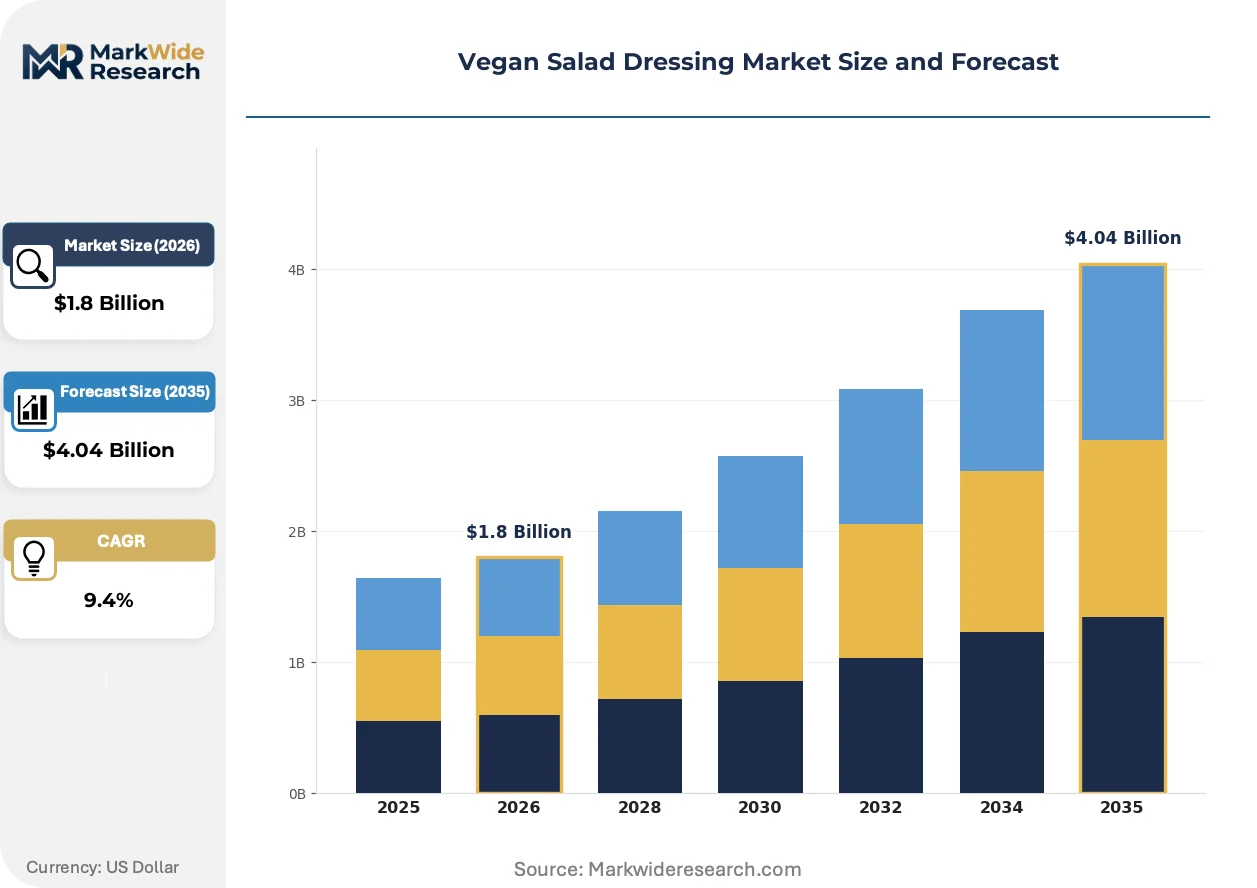
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balsamic, Caesar, Ranch, Tahini Ingredient Type: Oils, Vinegars, Herbs, Spices Flavor Profile: Sweet, Savory, Spicy, Tangy Packaging Type: Bottles, Pouches, Tubs, Sachets |
| Companies Covered | Sir Kensington's, Amy's Kitchen, Follow Your Heart, Litehouse, B&G Foods, Primal Kitchen, Just Salad, Meridian Foods Limited, Daiya Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Salad Dressing Market Evolving Landscape
Reformulation priorities are pivoting from simple dairy replacement toward functional performance parity in emulsion stability, oxidative shelf life, and mouthfeel replication, with technology investment concentrating on protein-starch hybrid systems.
High-pressure processing (HPP) is hybridizing with traditional thermal pasteurization in refrigerated dressing manufacturing, enabling clean-label pathogen reduction without the cooked off-notes associated with standard retort methods. Premium refrigerated brands at Whole Foods and Sprouts are adopting HPP lines at 40% faster capex deployment than conventional thermal systems. This dual-technology approach is compressing the shelf-life gap between refrigerated and shelf-stable segments, blurring traditional category boundaries.
EFSA's 2023 updated guidance on novel food status for precision-derived lipids is requiring separate safety assessments for fermentation-produced phospholipids intended as egg yolk replacers. European manufacturers reformulating with these ingredients face 18-24 month approval timelines that U.S. competitors bypass under GRAS self-determination. The regulatory friction is concentrating next-generation emulsifier development investment in North American pilot facilities rather than Dutch or Danish food-tech clusters.
Direct-to-consumer subscription models are displacing conventional grocery velocity as the primary trial mechanism for emerging vegan dressing brands, with Thrive Market and Brandless capturing household penetration ahead of shelf placement. This channel shift compresses traditional slotting fee economics and demands packaging formats optimized for parcel shipping durability rather than retail shelf presence. The behavioral pivot is most visible in coastal U.S. metropolitan markets where meal-planning app integration drives replenishment automation.
Vegan Salad Dressing Market Segmentation
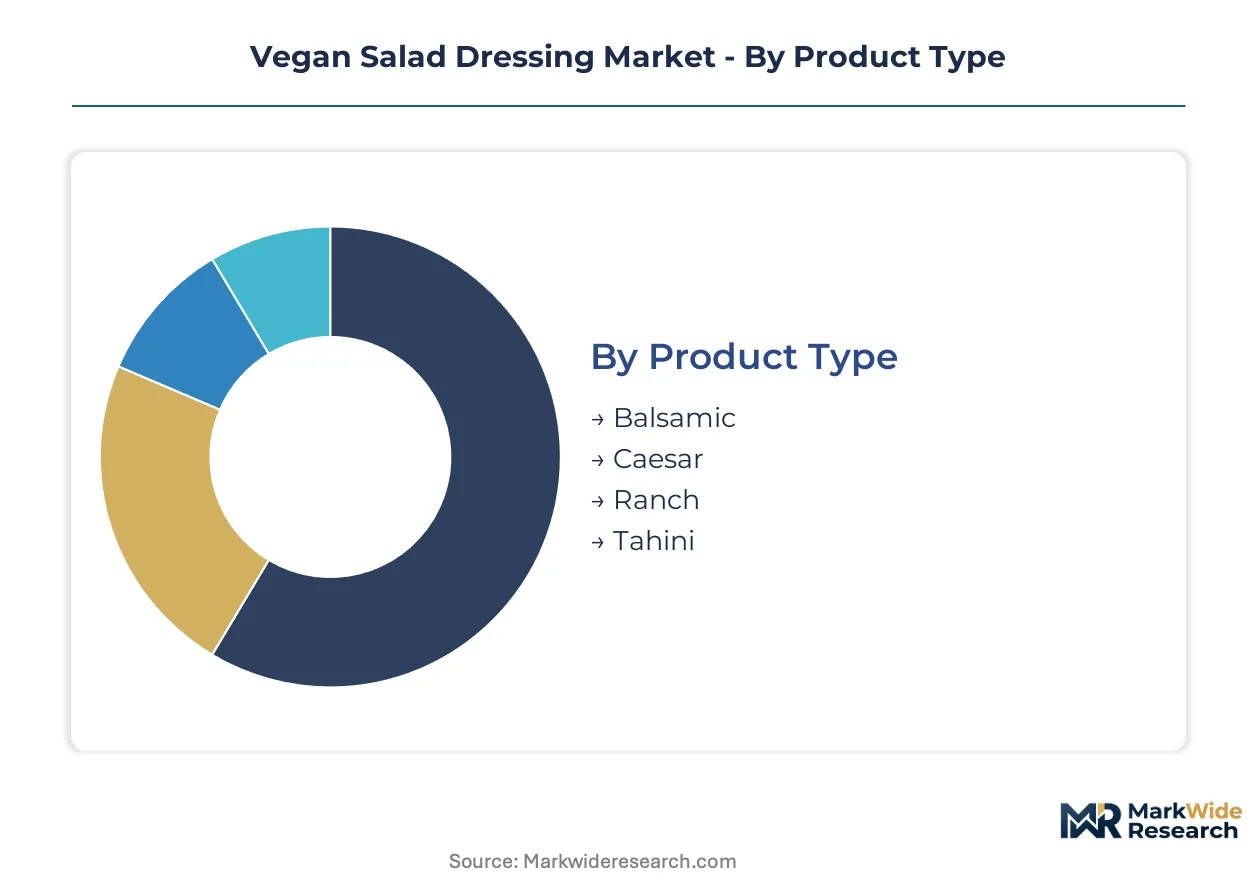
Vegan salad dressing segmentation reflects divergent paths between commodity retail velocity and emerging foodservice formats. Manufacturers optimize formulations, packaging, and flavor architectures to capture distinct usage occasions across refrigerated retail shelves and commercial kitchen prep lines.
Product Type:
Mature variants anchor retail distribution while Mediterranean-positioned formats accelerate through specialty channels.
- Balsamic:Acid-forward emulsions built on grape must reduction and wine vinegar bases dominate refrigerated case placement at Whole Foods and Sprouts. Italian import heritage commands price premiums in coastal U.S. metropolitan markets where consumers prioritize provenance labeling.
- Tahini:Sesame paste suspensions stabilized with modified starches or gum blends represent the steepest expansion curve, driven by Levantine and Mediterranean restaurant menu integration. Ethiopian and Sudanese sesame supply volatility compresses margins on this sub-segment.
- Caesar:Anchovy-free formulations using nutritional yeast and miso for umami depth target allergen-sensitive households through natural-product retailers.
- Ranch:Herb-and-onion profiles relying on cultured cashew or sunflower bases occupy the largest volume position in conventional grocery condiment aisles.
Ranch retains volume leadership; tahini holds the steepest expansion curve.
Ingredient Type:
Cost tier differentiation separates premium cold-pressed positioning from commodity refined oil formulations.
- Oils:Extra-virgin olive, avocado, and sunflower oils constitute the functional backbone of emulsion stability. EU Green Deal sourcing standards favor European domestic rapeseed and sunflower processors over Mediterranean olive dependence for mass-market SKUs.
- Vinegars:Apple cider, balsamic, and rice wine varieties provide acid balance and clean-label preservation without synthetic antimicrobials. California Proposition 65 heavy metal disclosure requirements apply to aged balsamic imports with concentrated lead residues.
- Herbs:Freeze-dried basil, dill, and parsley deliver visual differentiation and flavor complexity in premium refrigerated lines.
- Spices:Turmeric, smoked paprika, and black pepper support functional positioning around anti-inflammatory or antioxidant claims in direct-to-consumer subscription channels.
Oils command the highest cost share; vinegars drive the most rapid clean-label reformulation activity.
Flavor Profile:
Application context dictates preference architecture between meal-kit convenience and restaurant-style experience replication.
- Savory:Garlic, onion, and umami-forward profiles dominate foodservice portion-control pouches for fast-casual salad chains. These formulations prioritize emulsion stability under ambient holding conditions over refrigerated freshness signaling.
- Sweet:Maple, date, and reduced balsamic formulations target family household segments through conventional supermarket placement. Sugar content thresholds determine USDA Organic certification eligibility and Non-GMO Project verification timelines.
- Spicy:Harissa, sriracha, and jalapeño infusions capture trial-oriented consumers through Thrive Market and Brandless subscription models.
- Tangy:Citrus-forward and amplified acid profiles serve meal-kit integration where brightness compensates for limited fresh produce quality in parcel-shipped boxes.
Savory maintains foodservice dominance; spicy gains share fastest through digital-native retail.
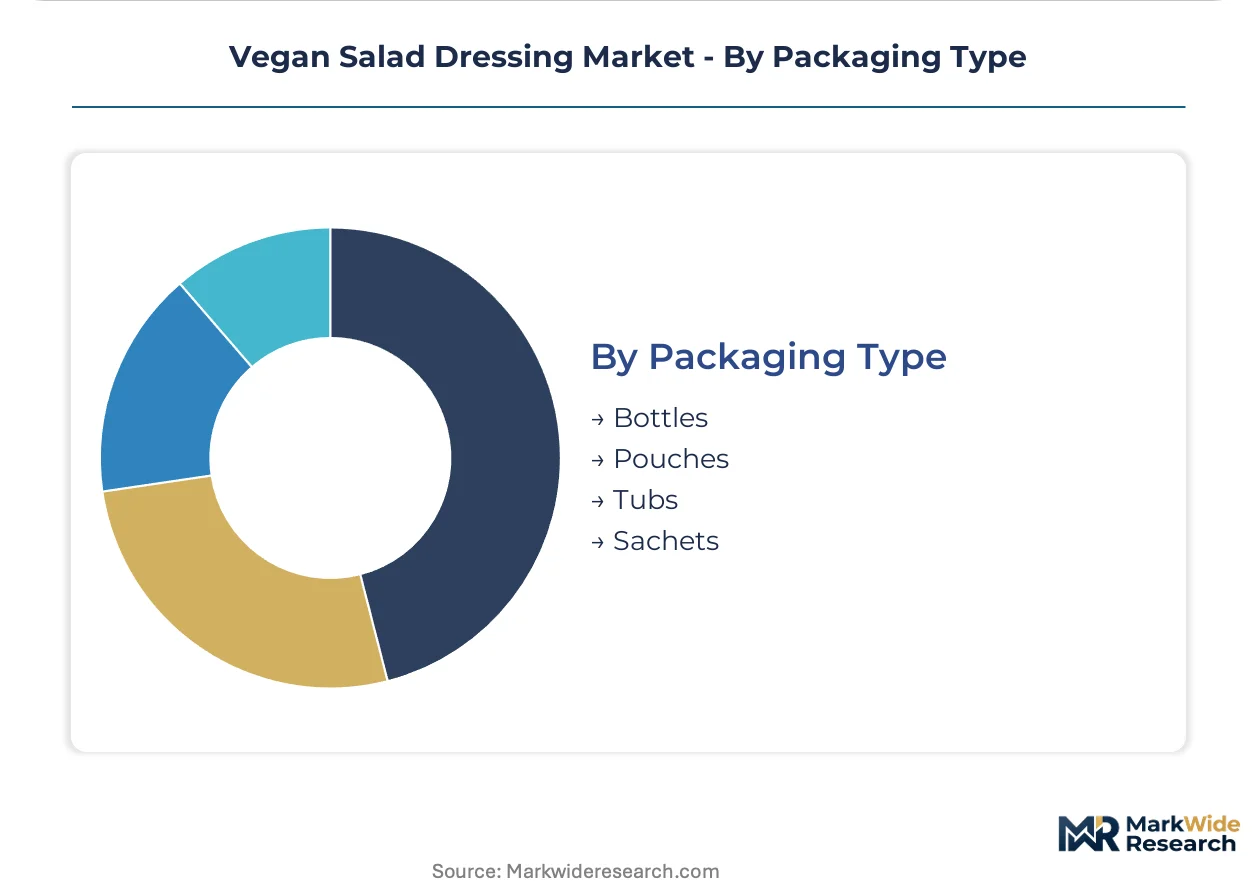
Packaging Type:
Customer type separation between retail pantry stockers and foodservice operators drives format innovation.
- Bottles:Glass and PET containers with pour-control closures dominate retail velocity at conventional and specialty grocers. Shelf presence requirements dictate label real estate for certification logos and ingredient transparency claims.
- Pouches:Flexible multilayer films with spout fitments serve Blue Apron and HelloFresh single-serve meal-kit specifications demanding 90-day ambient stability. Retort processing capability constrains contract manufacturer selection for this format.
- Tubs:Wide-mouth polyethylene containers target foodservice bulk users and deli counter scoop service in co-manufactured private label programs.
- Sachets:Pillow-pack foil laminates address airline, hospitality, and institutional feeding channels with strict portion-cost controls.
Bottles retain retail volume leadership; pouches climb the fastest through meal-kit channel integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach logistics corridor underwrites United States distribution dominance for refrigerated vegan dressing imports from Mediterranean suppliers, while Rotterdam's cold-chain hub anchors European cross-border consolidation.
United States
Specialty grocery retail maturation and fast-casual chain standardization drive demand concentration. FDA clean-label guidance and California Proposition 65 chemical disclosure rules impose compliance layering on imported ingredient supply chains. Los Angeles and San Francisco Bay Area clusters host formulation R&D facilities serving West Coast distribution density.
Germany
Discounter private-label expansion and organic certification premiums shape consumption patterns. EU Green Deal agricultural sourcing standards favor domestic rapeseed processors over Mediterranean olive oil dependence. Berlin-Brandenburg corridor hosts clean-label contract manufacturing capacity serving pan-European retail.
United Kingdom
Meal-kit subscription penetration and natural-product retail consolidation accelerate format innovation. EFSA novel-food assessments for precision-fermentation emulsifiers create 18-24 month approval timelines that U.S. competitors bypass. London-Southeast logistics cluster concentrates direct-to-consumer fulfillment infrastructure.
France
Balsamic heritage positioning and gastronomic retail culture sustain premium price architecture. REACH chemical registration requirements and EFSA guidance on plant-based claims create formulation uniformity challenges. Île-de-France hosts multinational condiment R&D centers adapting Mediterranean recipes for vegan reformulation.
India
Urban middle-class dietary diversification and foodservice Westernization expand addressable market. FSSAI pending vegan labeling definition creates first-mover advantage for exporters establishing local formulation standards. Maharashtra and Karnataka industrial corridors host emerging contract manufacturing capacity for ambient-stable pouch formats.
Vegan Salad Dressing Market Competitive Landscape
On the supply side, the industry is tiered between multinational condiment portfolios, natural-product specialists, and emerging direct-to-consumer brands. Three strategic archetypes dominate: heritage clean-label specialists leveraging West Coast distribution density, paleo-aligned functional food players competing on ingredient credentials, and fast-casual vertical integrators capturing foodservice pull-through. Capacity expansion and portfolio diversification constitute the dominant competitive moves, with manufacturers retooling for retort-capable pouch production and refrigerated HPP line deployment.
Within the heritage specialist tier, Sir Kensington's and Follow Your Heart exemplify premium positioning through clean-label formulation discipline, while Primal Kitchen occupies a position on the paleo-functional vector. These three entities anchor distinct competitive vectors: East Coast condiment heritage, West Coast natural-product retail density, and national club-store functional positioning respectively. Meridian Foods Limited represents the UK-based specialist archetype serving European organic certification requirements.
| Leading Market Players |
|---|
| Sir Kensington's |
| Amy's Kitchen |
| Follow Your Heart |
| Litehouse |
| B&G Foods |
| Primal Kitchen |
| Just Salad |
| Meridian Foods Limited |
| Daiya Foods |
| Others |
Value Network & Pricing Analysis
Sesame seed price volatility originating from Ethiopian and Sudanese crop cycles compresses margins on tahini-based SKUs while simultaneously widening spreads between Mediterranean-positioned premium lines and commodity ranch formulations. This input-cost instability forces manufacturers to dual-source oil bases and absorb working-capital hits from inventory pre-positioning, reshaping both tier boundaries and supplier financing structures.
Pricing Analysis
Volume-discount tiering structures separate refrigerated HPP-treated premium SKUs from retort-stable commodity pouches and foodservice bulk tubs. Price differentiation hinges on USDA Organic certification status and clean-label gum arabic avoidance. Pricing pressure stems from locust bean harvest concentration in Morocco and Spain, which elevates emulsifier costs disproportionately for mid-tier clean-label players. Foodservice operators exhibit highest price sensitivity due to portion-cost controls, while direct-to-consumer subscription buyers tolerate premiums for oxidative stability and single-serve convenience.
Supply Chain Analysis
Extended payment terms from fast-casual chains including Sweetgreen and Cava strain contract manufacturer liquidity, accelerating supply-chain finance facility adoption among retort-capable processors. Raw material dependencies center on Ethiopian sesame paste, Spanish locust bean gum, and European sunflower oil from rapeseed processors favored under EU Green Deal sourcing standards. Single-source gum vulnerability in Morocco and Spain creates emulsifier supply risk. Distribution runs through Port of Long Beach logistics corridors for Mediterranean refrigerated imports and Rotterdam cold-chain hubs for European cross-border consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in plant-protein stabilization and clean-label rheology modification commands premium compensation, constraining R&D throughput and creating bottlenecks for mid-tier manufacturers seeking dual USDA Organic and Non-GMO Project certification.
For Market Incumbents: Harden formulation IP protection around cold-water-swelling waxy maize derivatives from Ingredion and Cargill, which anchor cost-optimized retail viscosity stability. Deepen backward integration into high-pressure processing line deployment at 40% faster capex velocity than thermal systems to compress shelf-life gaps between refrigerated and shelf-stable segments. Defend against precision-fermentation emulsifier entrants by accelerating GRAS self-determination timelines that European competitors cannot match under EFSA novel-food assessments. For New Entrants and Emerging Players: Build out India FSSAI vegan labeling compliance ahead of New Delhi's pending definition, establishing local formulation standards before domestic competitor maturation. Target Maharashtra and Karnataka industrial corridors for ambient-stable pouch contract manufacturing capacity, where meal-kit channel integration with Blue Apron and HelloFresh specifications creates pull-through demand. Pursue direct-to-consumer subscription models through Thrive Market and Brandless, where parcel-shipping-optimized packaging displaces conventional slotting fee economics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors heritage clean-label specialists with West Coast distribution density and regulatory affairs capacity. Long-term viability over the next decade hinges on retort-capable processing infrastructure and HPP line deployment flexibility. Acquisition target archetype: mid-tier manufacturers with established fast-casual chain relationships but constrained by food technologist scarcity. Watch precision-fermentation phospholipid approval timelines under EFSA guidance as inflection indicator for next-generation emulsifier competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Retort-Capable Pouch Manufacturing Scale-Up | Enables 90-day ambient stability specifications for Blue Apron and HelloFresh meal-kit integrations. |
| High-Pressure Processing Line Deployment | Compresses shelf-life gaps between refrigerated and shelf-stable segments without cooked off-notes. |
| Backward Integration into Sunflower Oil Processing | Reduces EU Green Deal compliance costs by favoring European domestic rapeseed over Mediterranean olive dependence. |
| Precision Fermentation Emulsifier R&D Investment | Develops egg-free lecithin replacements with superior oxidative stability under GRAS self-determination pathways. |
| Direct-to-Consumer Subscription Channel Launch | Captures household penetration through Thrive Market and Brandless ahead of conventional grocery slotting. |
Research Methodology
Operator-level perspectives from foodservice procurement directors at fast-casual chains, R&D formulation leads at clean-label specialists, contract manufacturing operations heads, and specialty grocery category buyers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA labeling guidance documents, EFSA novel-food assessment databases, EU Green Deal agricultural sourcing standards, California Proposition 65 disclosure filings, and India FSSAI regulatory notices. Bottom-up SKU-level velocity data triangulated against top-down macroeconomic consumption indicators across the analysis window.
Scenario-bracketing around sesame supply disruption severity, fast-casual chain standardization velocity, and precision-fermentation emulsifier approval timelines structured the analytical framework. Segmentation dimensions modeled include product type, ingredient grade tier, packaging format, flavor profile architecture, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and forward-looking elasticity assumptions, with specific inputs for cold-water-swelling starch adoption curves and HPP line deployment rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational condiment portfolios or breakthrough precision-fermentation commercialization would shift outcomes. Macroeconomic commodity volatility, regulatory reclassification of vegan labeling definitions, or technological disruption in protein-stabilization systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
White Fungus Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
United States Tofu Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Global Nata De Coco Market