
 Reduced Sugar Products Market | 2026-2036
Reduced Sugar Products Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Sugar Products Market Outlook
Buyer concentration in the retail grocery channel is decoupling from traditional beverage and snack conglomerates as independent health-food chains and direct-to-consumer platforms fragment procurement. Mondelez International leverages its global snack-bar infrastructure to sustain reformulation pipelines across European and North American plants. Nestlé anchors its competitive position through captive R&D in natural sweetener extraction. PepsiCo competes aggressively on beverage reformulation, diverting capital toward stevia and monk-fruit blends.
Reduced sugar products are formulated consumer goods containing less than standard sucrose concentrations, typically achieved through replacement with polyols, rare sugars, or high-intensity sweeteners, and are manufactured to preserve sensory profiles while meeting glycemic-response targets for metabolic health management. Beverages lead volume contribution but operate on thin margin pools due to input-cost volatility in natural sweetener supply chains. Confectionery segments differentiate through premium positioning of sugar-substitute chocolates. Dairy products occupy a structural growth lane where protein-fortified, reduced-sugar yogurts attract health-conscious consumers and athlete end users simultaneously.
The FDA enforces added-sugar disclosure on Nutrition Facts panels while the USDA administers school-meal standards that cap sugar content, jointly reshaping product-development roadmaps for domestic manufacturers. WHO technical guidelines on sugar intake influence national dietary policies across multiple geographies, creating harmonized pressure for reformulation. EFSA evaluations of novel sweetener safety determine market-access timelines for new European entrants. Stakeholders must monitor evolving sweetener approvals and procurement-channel shifts to align capacity investments with the next wave of regulatory thresholds.
Market Dynamics
Reformulation pipelines are compressing product development cycles as beverage and dairy manufacturers race to meet cascading municipal sugar taxes and retailer shelf-space policies that now penalize standard-sugar formulations.
Growth Catalysts
- FDA Nutrition Facts overhauls:Mandatory added-sugar disclosure panels are forcing CPG manufacturers to accelerate reformulation timelines and prioritize front-of-package claims.
- Stevia-leaf extraction advances:Enzymatic bioconversion processes are reducing bitter aftertaste profiles, unlocking broader beverage applications previously closed to natural sweeteners.
- WHO guideline harmonization:National dietary policy alignment across multiple geographies is creating synchronized procurement mandates for institutional foodservice channels.
Market Restraints
- Monk-fruit supply concentration:Over 80% of global monk-fruit cultivation clusters in southern Chinese provinces, exposing reformulators to climate and trade-policy volatility.
- Erythritol digestive tolerance thresholds:Consumer gastrointestinal sensitivity limits polyol loading in confectionery applications, capping sugar-replacement ratios.
- EFSA novel-food authorization delays:European entrants face 18-24 month safety evaluation timelines for rare-sugar sweeteners, freezing product launches.
Strategic Opportunities
- Protein-fortified dairy white space:Athlete and health-conscious consumer overlap in reduced-sugar Greek yogurt remains underexploited by incumbent players.
- Direct-to-consumer subscription channels:Digital-native brands are bypassing retail slotting-fee structures to test micro-batch reformulations with rapid feedback loops.
- USDA school-meal procurement:Federal sugar caps in K-12 nutrition programs are creating institutional volume commitments for qualified suppliers.
Industry Challenges
- Sensory scientist talent scarcity:Cross-functional expertise spanning flavor chemistry, glycemic response modeling, and regulatory compliance commands premium compensation.
- Clean-label certification timelines:Third-party non-GMO and organic sweetener verifications extend procurement lead times by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Sugar Products Market |
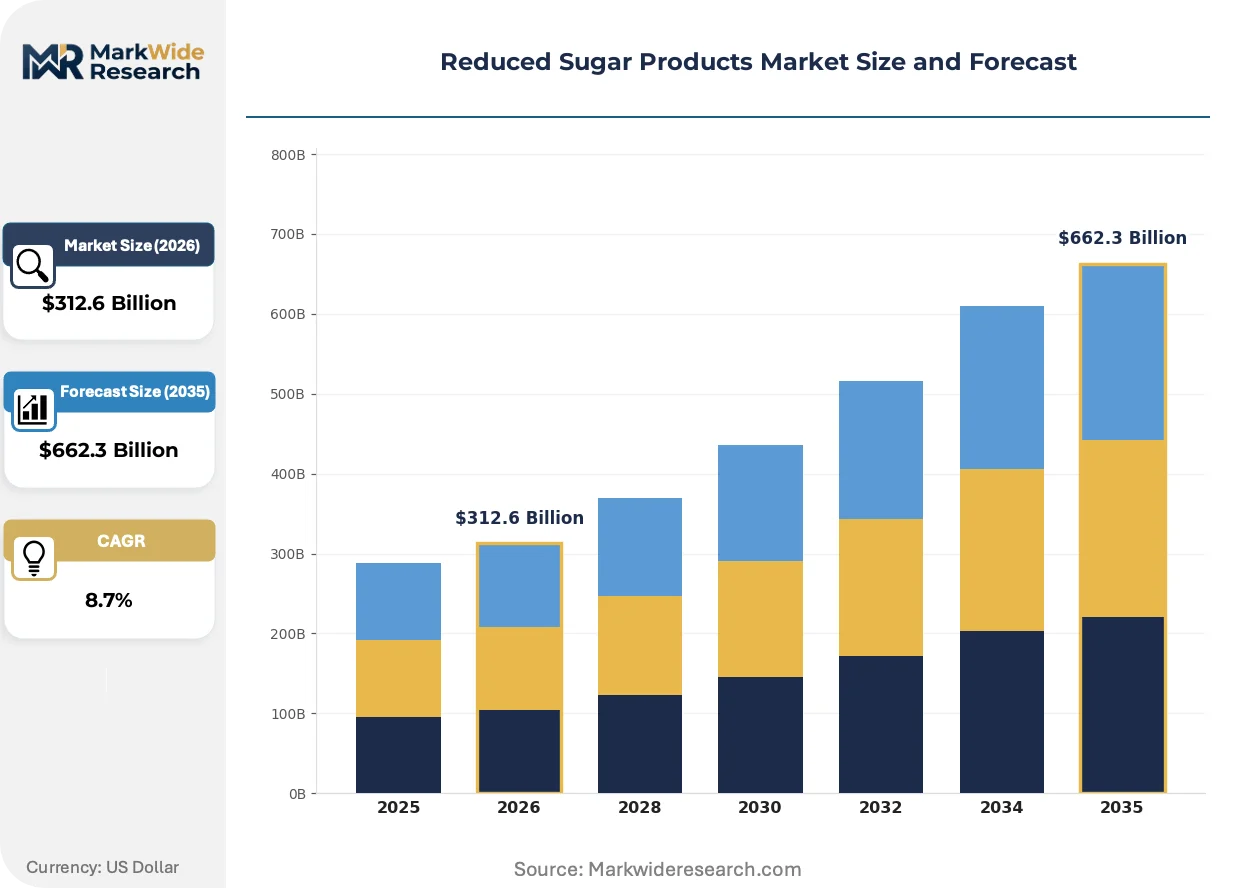
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Beverages, Dairy Products, Confectionery End User: Health-Conscious Consumers, Children, Athletes, Diabetes Patients Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Formulation: Natural Sweeteners, Artificial Sweeteners, Sugar Substitutes, Organic Ingredients |
| Companies Covered | Mondelez International, Danone, Coca-Cola Company, Monster Beverage Corporation, Kraft Heinz, PepsiCo, Unilever, Suntory Holdings Limited, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Sugar Products Market Strategic Shifts
Natural sweetener supply chains are digitizing procurement forecasting while enzymatic modification techniques unlock sensory parity with sucrose, compressing the performance gap that once limited category expansion.
Enzymatically modified steviol glycosides are consolidating competitive positioning in premium beverage segments. Mid-tier soda and functional drink manufacturers are adopting these next-generation extracts at accelerating rates to avoid the metallic finish of first-generation Reb A formulations. The technology is consolidating R&D budgets around bioconversion platforms and marginalizing legacy solvent-extraction capacity.
REACH-compliant novel-sweetener dossiers are reshaping European market-access economics. EFSA toxicological data requirements now demand multi-generational rodent studies and human glycemic-response trials, elevating capital barriers for new entrants. Confectionery segments face the steepest compliance burdens as chocolate applications trigger additional cocoa-interaction assessments.
Sport-nutrition procurement is fragmenting away from mass-market retail toward specialized e-commerce platforms and gym-channel direct distribution. Reduced-sugar protein bars and ready-to-drink shakes are bypassing traditional grocery slotting fees through influencer-curated subscription models. This channel rotation is most visible in United States metropolitan markets where boutique fitness chains operate captive retail footprints.
Reduced Sugar Products Market Segmentation
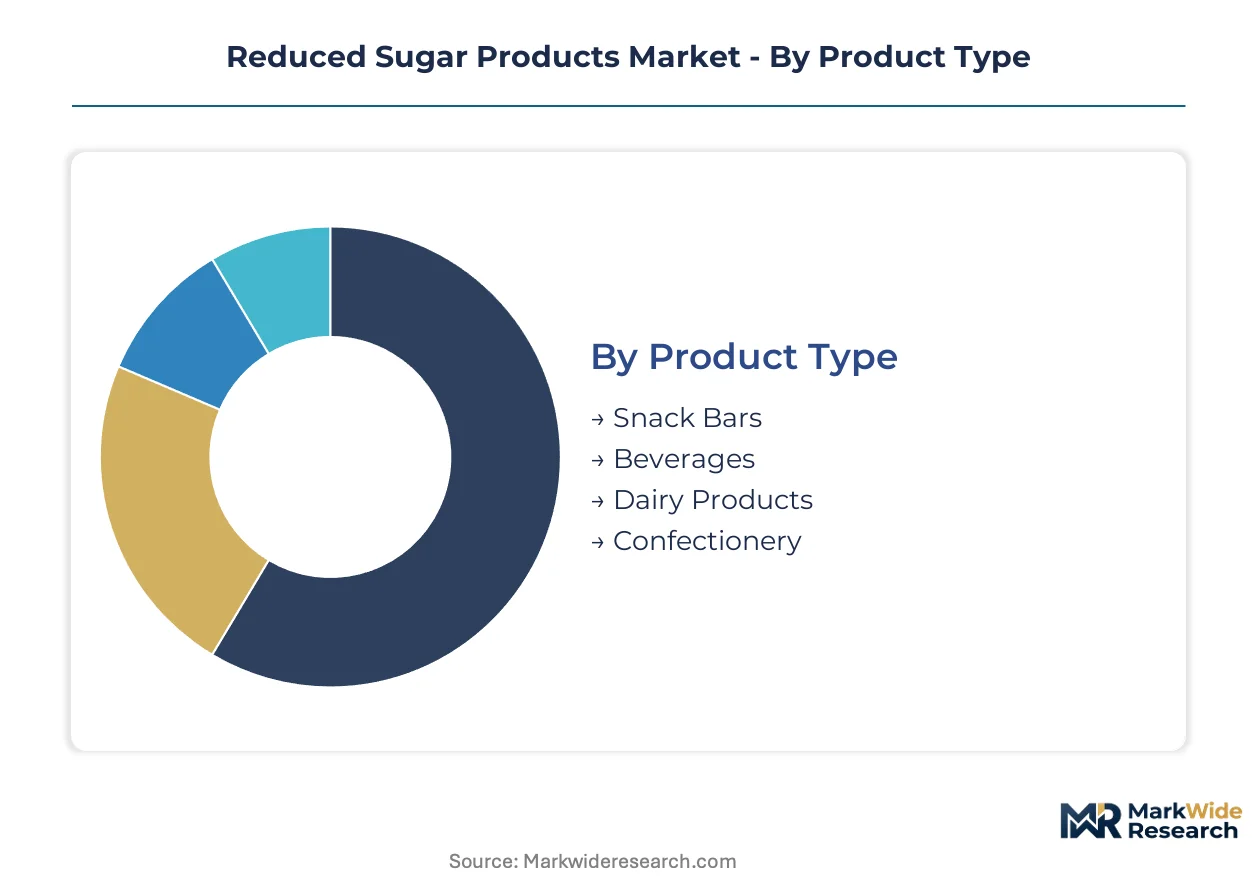
Segmentation in reduced sugar products determines procurement channel access and reformulation investment priorities. Manufacturers align R&D budgets and supply chain configurations to the distinct technical requirements and price sensitivities of each category.
Product Type:
Supply concentration in natural sweetener extraction favors beverage and dairy manufacturers with captive bioconversion capacity, while snack bar and confectionery players face tighter margin pools from volatile monk-fruit and stevia-leaf sourcing.
- Beverages:Liquid formulations rely on high-intensity sweetener blends—stevia glycosides, monk-fruit extracts, and rare sugars—to achieve sensory parity with sucrose while meeting glycemic-response targets. Demand concentrates in the United States where municipal sugar taxes in Philadelphia, Seattle, and San Francisco have compressed reformulation timelines to under 18 months.
- Dairy Products:Protein-fortified yogurts and flavored milks deploy enzymatically modified sweeteners to mask bitter protein notes, creating dual-claim positioning for athlete and metabolic-health segments. Greek yogurt manufacturers in New York and California anchor volume procurement through direct-to-gym distribution partnerships.
- Snack Bars:Polyol-bound formulations face gastrointestinal tolerance constraints that limit sugar-replacement ratios to 30-40% in mass-market products.
- Confectionery:Chocolate applications trigger additional EFSA cocoa-interaction assessments in Europe, extending novel-sweetener authorization timelines.
Today's leader: Beverages. Tomorrow's challenger: Dairy Products.
End User:
Cost tier stratification separates premium-priced athlete nutrition from value-positioned children's products, with health-conscious consumers occupying the elastic middle where clean-label certification commands 15-25% price premiums.
- Health-Conscious Consumers:This segment drives clean-label procurement mandates, requiring third-party non-GMO and organic sweetener verifications that extend lead times by 4-6 months. United States metropolitan markets—particularly Los Angeles, New York, and Austin—concentrate demand through independent health-food chains and subscription platforms.
- Athletes:Protein-fortified, reduced-sugar formulations prioritize glycemic control and rapid nutrient absorption, with specialized e-commerce platforms and gym-channel direct distribution displacing traditional grocery slotting. Sport-nutrition procurement fragments fastest in United States boutique fitness chains with captive retail footprints.
- Children:USDA school-meal standards cap sugar content, creating institutional volume commitments for qualified suppliers with reformulation pipelines certified for K-12 procurement.
- Diabetes Patients:Medical-nutrition positioning requires glycemic-response documentation and healthcare practitioner endorsement, limiting accessible distribution to pharmacy and clinical channels.
Health-conscious consumers anchor current revenue. Athletes are climbing the fastest as sport-nutrition channels rotate away from mass retail.
Distribution Channel:
Volume concentration in United States supermarket chains is fragmenting as digital-native brands bypass slotting-fee structures through direct-to-consumer testing of micro-batch reformulations.
- Supermarkets:Retailer shelf-space policies in Kroger, Albertsons, and Ahold Delhaize banners now penalize standard-sugar formulations through reduced facings and end-cap exclusion. Reformulated products must demonstrate velocity thresholds within 90-day trial periods to retain distribution.
- Online Retail:Subscription models enable rapid sensory feedback loops and iterative formulation refinement without retail slotting-fee burdens. Influencer-curated platforms in United States metropolitan markets test novel sweetener blends with 2-4 week replenishment cycles.
- Health Food Stores:Independent chains in Portland, Denver, and Brooklyn concentrate premium positioning for enzymatically modified stevia and rare-sugar formulations.
- Convenience Stores:Impulse-driven purchasing favors single-serve reduced-sugar beverages with front-of-package sugar disclosure compliance.
Supermarkets dominate volume. Online Retail is gaining share fastest through subscription channel expansion.
Formulation:
Margin structure in natural sweetener extraction—enzymatic bioconversion versus legacy solvent-based methods—determines competitive positioning across premium and mid-tier product tiers.
- Natural Sweeteners:Enzymatically modified steviol glycosides consolidate R&D budgets around bioconversion platforms, reducing bitter aftertaste profiles that previously limited beverage applications. PepsiCo and Coca-Cola reformulation pipelines in Georgia and California anchor demand for next-generation Reb M and Reb D extracts.
- Sugar Substitutes:Polyols—erythritol, xylitol, and maltitol—face digestive tolerance thresholds that cap loading in confectionery applications, with consumer gastrointestinal sensitivity triggering product returns above 10g per serving.
- Artificial Sweeteners:Aspartame and sucralose formulations retain cost advantage in value-tier beverages despite clean-label displacement pressure.
- Organic Ingredients:USDA organic certification and non-GMO Project verification extend procurement lead times and elevate input costs 20-35% above conventional alternatives.
Natural Sweeteners command premium positioning. Sugar Substitutes retain volume scale through cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States municipal sugar taxes outpace European regulatory harmonization in reformulation urgency, while Chinese monk-fruit cultivation clusters expose supply chains to climate volatility absent in Brazilian stevia expansion zones.
United States
Philadelphia, Seattle, and San Francisco municipal sugar taxes compress beverage reformulation timelines below 18 months. FDA mandatory added-sugar disclosure panels force CPG manufacturers to accelerate front-of-package claim strategies. Georgia and California anchor PepsiCo and Coca-Cola reformulation pipelines for next-generation Reb M and Reb D stevia extracts.
Germany
Health-conscious consumers in Berlin and Munich drive clean-label procurement mandates through independent bio-supermarket chains. EFSA novel-food authorization timelines of 18-24 months freeze rare-sugar sweetener launches for confectionery applications. Bavaria-based dairy processors lead protein-fortified, reduced-sugar yogurt R&D for athlete nutrition segments.
China
Southern Guangxi and Guizhou provinces concentrate over 80% of global monk-fruit cultivation, exposing reformulators to trade-policy volatility. SAMR national dietary guidelines align with WHO sugar reduction targets, pressuring domestic beverage manufacturers. Yangtze River Delta bioconversion facilities scale enzymatic steviol glycoside production for premium export markets.
Brazil
São Paulo and Minas Gerais stevia cultivation zones diversify natural sweetener supply away from Chinese monk-fruit concentration. ANVISA food additive regulations govern high-intensity sweetener approvals for beverage and dairy applications. Southeast Brazilian processors supply stevia leaf to European confectionery manufacturers facing EFSA compliance burdens.
Japan
Tokyo and Osaka metropolitan markets concentrate demand for rare-sugar formulations targeting diabetes patient segments. PMDA and MHLW jointly regulate functional food claims for glycemic-response positioning. Kanto region dairy cooperatives deploy enzymatically modified sweeteners in protein-fortified yogurts for athlete end users.
Reduced Sugar Products Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures concentrate around captive R&D in natural sweetener extraction and bioconversion platform control. Three archetypes dominate: multinational CPG conglomerates with global snack-bar infrastructure, beverage-centric reformulators with stevia supply chain integration, and dairy specialists with protein-fortification expertise. M&A activity targets enzymatic modification technology licenses, while capacity expansion concentrates in USDA school-meal certified production lines.
Within the multinational conglomerate tier, Mondelez International and Nestlé exemplify divergent strategic anchors. Mondelez leverages global snack-bar manufacturing footprints to sustain reformulation pipelines across European and North American plants. Nestlé occupies a position defined by captive R&D investment in natural sweetener extraction capabilities. PepsiCo sits within the beverage-reformulation specialist archetype, competing through capital diversion toward stevia and monk-fruit blend development.
| Leading Market Players |
|---|
| Mondelez International |
| Danone |
| Coca-Cola Company |
| Monster Beverage Corporation |
| Kraft Heinz |
| PepsiCo |
| Unilever |
| Suntory Holdings Limited |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
Health-conscious consumer procurement through direct-to-consumer platforms and independent health-food chains anchors pricing power toward enzymatically modified stevia and rare-sugar formulations, compressing margins on legacy polyol-dependent tiers.
Pricing Analysis
Capacity additions in Brazilian stevia cultivation zones are reshaping price floors for natural sweetener blends, displacing first-generation Reb A premiums. Three-tier pricing structure across premium enzymatic extracts, standard stevia glycosides, and economy-tier polyols stratifies the market. Cost compression in monk-fruit dependent formulations is intensifying because Chinese supply concentration exposes buyers to trade-policy volatility. Athlete nutrition segments show least price sensitivity due to glycemic-response certification requirements, while value-positioned children's products face acute elasticity from USDA procurement cost caps.
Supply Chain Analysis
Flavor chemist and sensory scientist talent shortages in Georgia and California bioconversion hubs are extending R&D timelines for beverage reformulators. Raw material flows draw from Brazilian stevia leaf, Chinese monk-fruit extract, and Indian erythritol fermentation capacity. Single-source vulnerability in southern Guangxi monk-fruit cultivation clusters exposes reformulation pipelines to climate disruption. Distribution runs through refrigerated tanker networks for liquid extracts and temperature-controlled warehousing for finished beverage consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory harmonization across FDA, EFSA, and WHO frameworks locks in reformulation demand with predictable procurement mandates.
For Market Incumbents: Lock in captive bioconversion capacity through backward integration into enzymatic modification platforms, defending against pure-play natural sweetener specialists. Secure USDA school-meal certification for production lines to capture institutional volume commitments. Prioritize R&D investment in rare-sugar glycemic-response documentation to maintain athlete-segment positioning against emerging protein-fortified dairy entrants. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the lowest barrier to micro-batch testing of novel sweetener blends with rapid sensory feedback loops. Target protein-fortified Greek yogurt white space in United States metropolitan gym-channel distribution, where incumbent dairy players underinvest in athlete-health overlap. Pursue influencer-curated platform partnerships to bypass retail slotting-fee structures that disadvantage small-scale reformulators. For Investors and Strategic Acquirers: Beverage conglomerates with stevia supply chain integration are the most active acquirer in this space, seeking enzymatic modification technology licenses. Long-term viability rests on control of bioconversion platforms rather than brand equity alone. Watch EFSA novel-food authorization timelines for rare-sugar sweeteners as the inflection signal determining European market-access economics for target portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Platform Investment | PepsiCo and Coca-Cola anchor Georgia and California pipelines for next-generation Reb M and Reb D extracts. |
| USDA School-Meal Certification Program | Qualified suppliers secure institutional volume commitments through K-12 procurement pipelines. |
| Direct-to-Consumer Subscription Launch | Digital-native brands bypass Kroger and Albertsons slotting-fee structures with rapid reformulation feedback. |
| Backward Integration into Stevia Cultivation | Brazilian São Paulo and Minas Gerais zones diversify supply away from Chinese monk-fruit concentration. |
| Rare-Sugar EFSA Dossier Submission | Confectionery manufacturers face extended cocoa-interaction assessments for European market access. |
Study Parameters
Coverage spans United States, Germany, China, Brazil, and Japan, with primary inputs from each regional cluster combining interviews with reformulation R&D directors, retail category buyers, regulatory affairs leads, and supply chain planners. Secondary validation draws from FDA GRAS notices, EFSA novel-food opinions, WHO sugar reduction guideline documents, and customs trade data for stevia leaf and monk-fruit extract flows. Bottom-up segment sizing triangulates against top-down macroeconomic anchors.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and formulation technology tier. CAGRs derive from fitted trend extrapolation adjusted for regulatory threshold timing and sweetener approval trajectories. Inputs incorporate municipal sugar tax implementation schedules and enzymatic extraction yield improvement curves.
The model assumes a particular technology adoption path; alternative pathways for rare-sugar bioconversion would alter the outlook. Forecasts reflect assumptions about EFSA authorization timelines, Brazilian stevia cultivation expansion rates, and WHO guideline national adoption velocity. Material deviation in monk-fruit trade policy or FDA added-sugar disclosure enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Xylitol Injection Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Rice Syrup Market
Sweeteners
Galactose Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Sorbitol Market
Sweeteners
Xylose Market
Sweeteners
Sugar Market
Sweeteners
Compressible Sugar Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Icing Sugar Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Australia Allulose Market