
 Molecular Methods Market | 2026-2036
Molecular Methods Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Methods Market Intelligence
Buyer concentration among hospital-affiliated laboratories is pivoting toward a more fragmented landscape as independent reference labs and physician office laboratories expand molecular testing capabilities. QIAGEN leverages its automated sample-to-insight workflows to sustain installed-base loyalty across mid-sized diagnostic networks. Thermo Fisher Scientific Inc. anchors its position through end-to-end reagent and instrument ecosystems that reduce switching costs for high-volume users. Bio-Rad Laboratories Inc. competes in digital PCR niches where absolute quantification commands premium positioning.
Molecular methods encompass nucleic acid-based analytical techniques that detect, amplify, sequence, or hybridize DNA and RNA targets with specificity reaching single-copy sensitivity in some platforms. These methods serve industrial and commercial purposes ranging from pathogen identification in clinical specimens to genotyping in agricultural breeding programs. Polymerase Chain Reaction occupies the largest revenue share due to its entrenched regulatory approvals and workflow familiarity across routine diagnostic settings. Next Generation Sequencing captures the fastest expansion as clinical whole-genome and targeted panel applications displace single-gene assays in oncology and rare disease contexts.
FDA premarket notification pathways and the EU In Vitro Diagnostic Regulation impose escalating analytical and clinical validation requirements that filter market access to well-capitalized platform developers. ISO 15189 accreditation standards for diagnostic laboratories further shape demand by mandating traceable quality management systems that favor integrated instrument-reagent suppliers. Stakeholders must monitor how decentralized point-of-care molecular testing reshapes channel economics between centralized reference laboratories and distributed clinical sites.
Market Dynamics
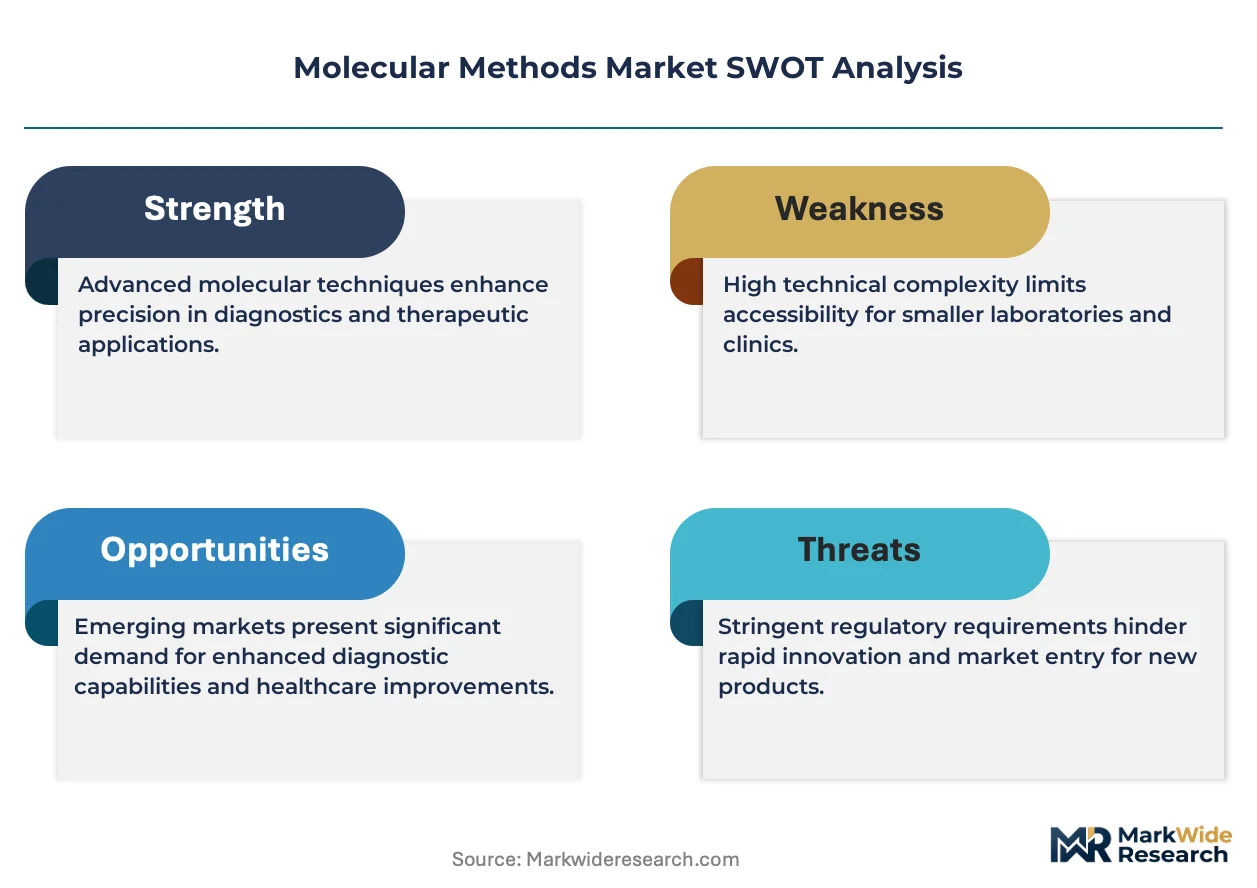
Clinical laboratories face mounting pressure to integrate next-generation sequencing into routine diagnostic workflows as payers demand comprehensive genomic profiling for oncology reimbursement. This technology transition compresses capital cycles and forces mid-sized networks to choose between platform consolidation and outsourced testing partnerships.
Growth Catalysts
- FDA premarket notification pathways:Streamlined 510(k) clearances for nucleic acid-based diagnostics accelerate commercial timelines for multiplex respiratory panels and bloodstream infection assays.
- Infectious disease surveillance infrastructure:Public health laboratories across the United States are expanding molecular testing menus to detect emerging pathogens with pandemic potential.
- EU In Vitro Diagnostic Regulation:MDR compliance mandates drive replacement of legacy immunoassays with CE-IVD marked molecular methods in European hospital laboratories.
Market Restraints
- Reagent supply concentration:Taq polymerase and modified nucleotide production clusters among three contract manufacturers, creating single-source vulnerability for assay developers.
- Capital intensity of sequencing platforms:Illumina and Thermo Fisher instrument ecosystems require $500K-$2M upfront commitments that exclude smaller physician office laboratories.
- Workflow complexity:Bioinformatic analysis pipelines demand specialized computational infrastructure and FTE capacity that community hospitals rarely maintain in-house.
Strategic Opportunities
- Point-of-care molecular testing:CLIA-waived PCR and isothermal amplification devices unlock pharmacy clinic and urgent care channels previously served by centralized reference laboratories.
- Agricultural genotyping services:Seed companies in Brazil and Argentina contract molecular methods for marker-assisted breeding programs targeting drought-resistant crop varieties.
- ISO 15189 accreditation mandates:Diagnostic laboratories pursuing international quality certification favor integrated instrument-reagent suppliers offering traceable calibration and training protocols.
Industry Challenges
- Bioinformatician talent scarcity:Clinical laboratories compete with technology firms for variant interpretation specialists, delaying NGS assay validation timelines.
- Interoperability with LIS infrastructure:Proprietary data formats from sequencing platforms require custom middleware development to integrate with existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Methods Market |
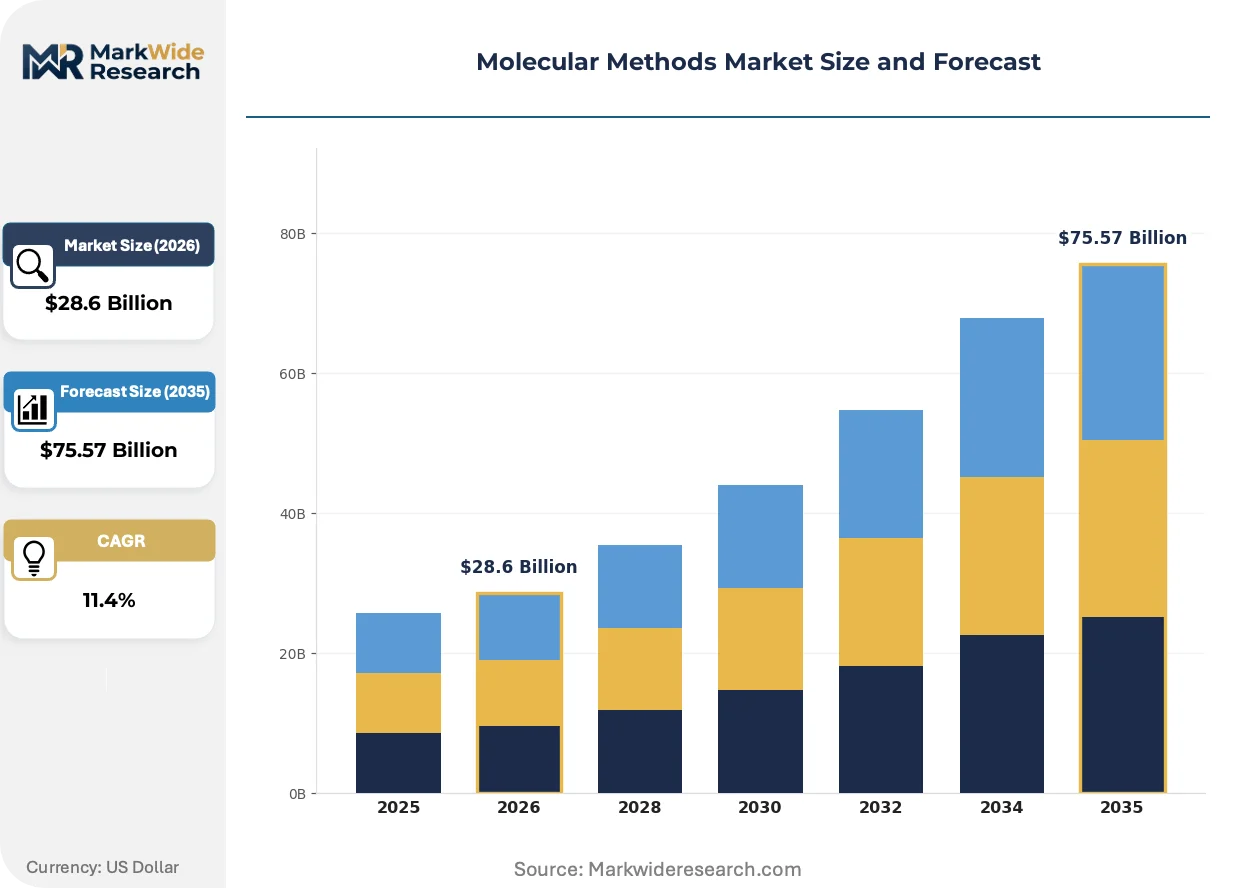
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technique: Polymerase Chain Reaction, Next Generation Sequencing, Microarray, Hybridization, Nucleic Acid Amplification Application: Genetic Testing, Pathogen Detection, Forensic Analysis, Agricultural Biotechnology, Environmental Monitoring End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Forensic Labs, Agricultural Firms Sample Type: Blood, Tissue, Saliva, Soil, Water |
| Companies Covered | QIAGEN, bioMérieux SA, Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., F. Hoffmann-La Roche Ltd, Danaher Corporation, Abbott Laboratories, Hologic Inc., Illumina Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Methods Market Strategic Shifts & Innovations
Digital PCR platforms are fragmenting the quantitative nucleic acid testing landscape as absolute quantification replaces relative fold-change measurements in clinical and industrial applications. This shift demands new calibration standards and proficiency testing frameworks.
CRISPR-based diagnostics is decentralizing infectious disease detection from centralized reference laboratories to distributed clinical sites. Community health centers and pharmacy clinics adopt SHERLOCK and DETECTR platforms for same-day sexually transmitted infection and respiratory pathogen results. This technology is compressing turnaround times from days to hours while reducing specimen transport logistics.
The EU In Vitro Diagnostic Regulation imposes escalating analytical and clinical validation requirements that filter market access to well-capitalized platform developers. Device manufacturers must maintain technical documentation and post-market surveillance systems that smaller assay developers cannot sustain. Oncology companion diagnostics and prenatal screening panels face the steepest compliance burdens, prompting consolidation among notified body review capacities.
Subscription reagent purchasing models are displacing transactional instrument sales in high-volume molecular testing operations. Academic medical centers and integrated delivery networks negotiate multi-year consumable commitments that bundle instruments, maintenance, and assay menus at per-test pricing. This transformation is most advanced in the United States, where laboratory benefit managers and group purchasing organizations consolidate procurement leverage across hospital networks.
Molecular Methods Market Segmentation
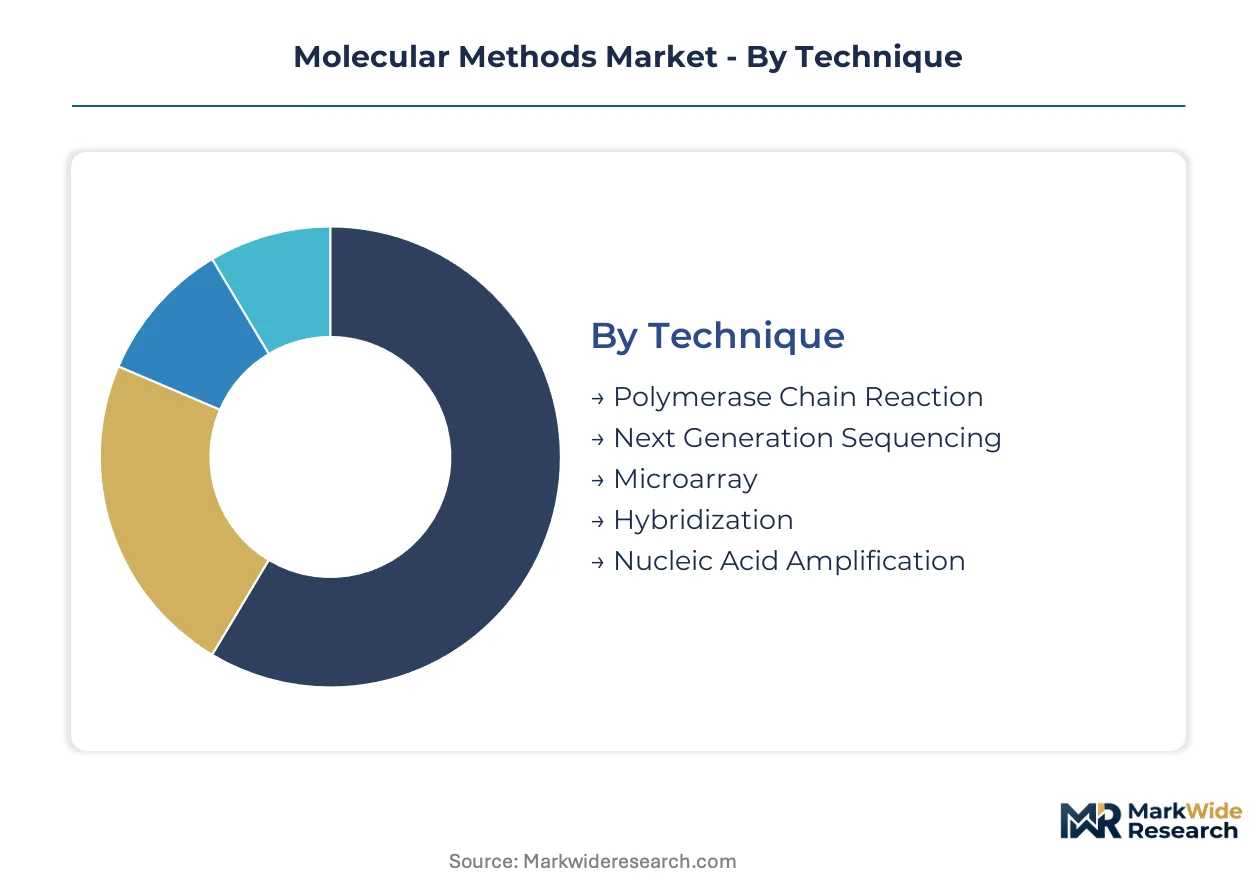
Molecular methods fragment across multiple technical and commercial dimensions that determine procurement patterns, validation requirements, and margin structures. Understanding these segment boundaries clarifies where capital deployment concentrates and which customer configurations sustain platform economics.
Technique:
Capital intensity varies sharply across amplification and detection platforms, with sequencing ecosystems demanding the heaviest upfront instrumentation commitments.
- Polymerase Chain Reaction:Thermal cycling amplification of DNA targets using Taq polymerase and fluorescent probe detection. Hospital-affiliated laboratories in the United States anchor procurement volumes for infectious disease panels and oncology companion diagnostics, driven by entrenched regulatory clearances and workflow familiarity.
- Next Generation Sequencing:Massively parallel sequencing-by-synthesis or semiconductor detection generating millions of reads per run. Academic medical centers and cancer centers in the United States absorb the steepest capital commitments for whole-genome and targeted oncology applications, pressured by payer demands for comprehensive genomic profiling.
- Microarray:Solid-phase hybridization of labeled nucleic acids to spotted probe sets for genotyping and expression profiling.
- Hybridization:Solution-phase or membrane-based probe-target binding for specific sequence detection without enzymatic amplification.
- Nucleic Acid Amplification:Isothermal methods including LAMP and NASBA enabling point-of-care deployment without thermal cycling infrastructure.
Polymerase Chain Reaction absorbs the bulk of installed capacity; Next Generation Sequencing is expanding most quickly.
Application:
Regulatory burden and reimbursement density separate clinical applications from industrial and forensic segments, shaping customer investment horizons.
- Genetic Testing:Germline and somatic variant detection for inherited disease risk, pharmacogenomics, and carrier screening. Reference laboratories in the United States concentrate demand for expanded carrier panels and prenatal cell-free DNA screening, navigating FDA premarket notification and state laboratory licensing requirements.
- Pathogen Detection:Qualitative and quantitative identification of viral, bacterial, and fungal agents in clinical specimens. Public health laboratories across the United States expand multiplex respiratory and bloodstream infection menus, intensifying infectious disease surveillance infrastructure.
- Forensic Analysis:STR profiling and mitochondrial sequencing for human identification in criminal casework and disaster victim identification.
- Agricultural Biotechnology:Marker-assisted breeding, GMO detection, and pathogen screening in seed and livestock production.
- Environmental Monitoring:Microbial community profiling and pathogen surveillance in water, soil, and air matrices.
Genetic Testing commands the highest reimbursement density; Pathogen Detection is climbing the fastest on pandemic preparedness investments.
End User:
Customer scale and technical sophistication determine whether integrated platform ecosystems or modular reagent kits capture procurement decisions.
- Diagnostic Laboratories:High-throughput clinical testing operations requiring ISO 15189 accreditation and traceable quality management. Mid-sized networks in the United States face compressed capital cycles as they choose between NGS platform consolidation and outsourced testing partnerships.
- Research Institutes:Academic and government laboratories pursuing discovery applications with flexible funding and publication-driven validation timelines.
- Pharmaceutical Companies:Drug developers employing molecular methods for biomarker discovery, patient stratification, and manufacturing quality control.
- Forensic Labs:Government and private facilities processing criminal evidence under chain-of-custody protocols and accreditation standards.
- Agricultural Firms:Seed companies and livestock breeders contracting genotyping services for trait selection and pedigree verification.
Diagnostic Laboratories dominate instrument placements; Research Institutes show the steepest expansion trajectory for novel platform evaluation.
Sample Type:
Collection logistics and nucleic acid stability requirements shape whether centralized processing or distributed point-of-care deployment prevails.
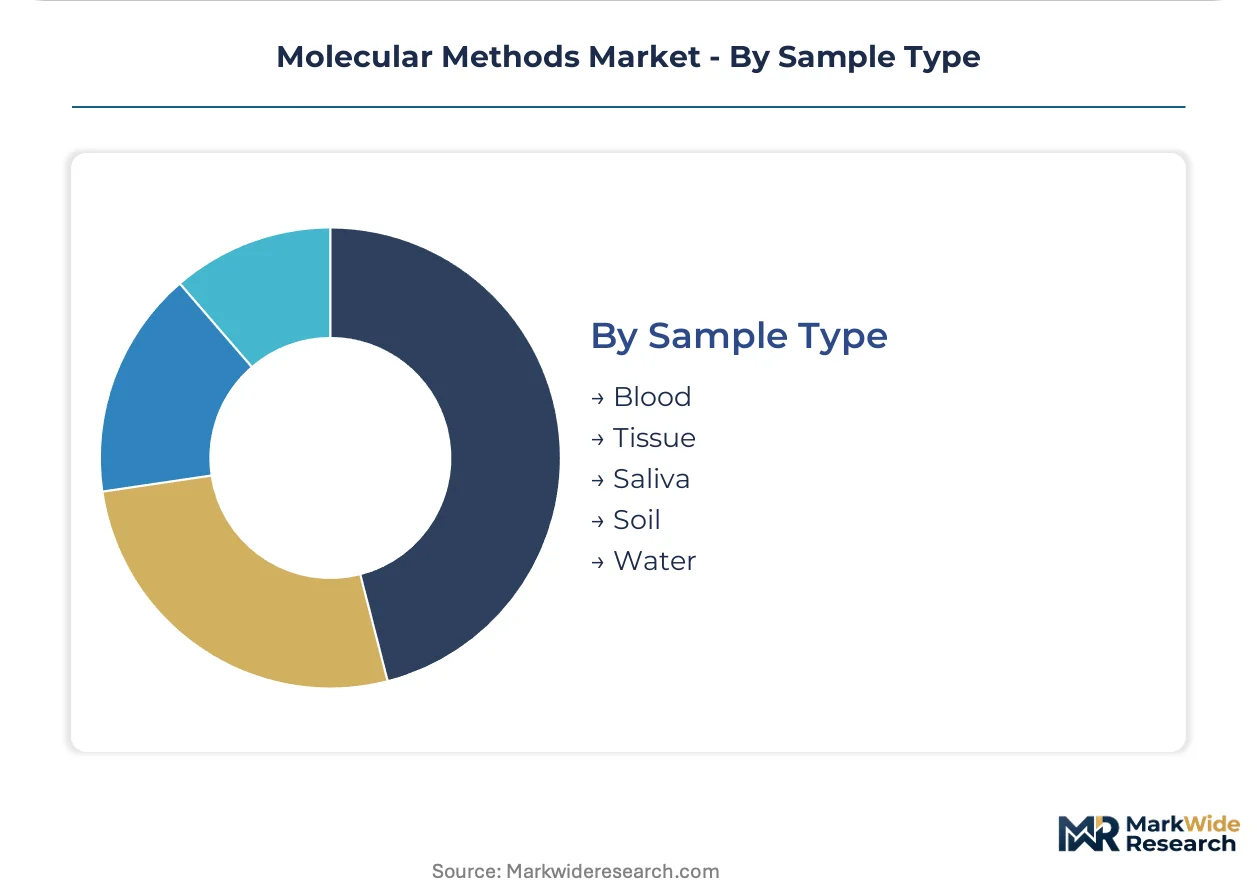
- Blood:Plasma, serum, and buffy coat preparations yielding high-quality DNA and RNA for clinical diagnostics. Hospital laboratories in the United States standardize on automated extraction workflows for liquid biopsy and infectious disease applications, minimizing preanalytical variability.
- Tissue:Formalin-fixed paraffin-embedded and fresh-frozen specimens requiring specialized extraction protocols for oncology testing.
- Saliva:Non-invasive collection enabling direct-to-consumer genetic testing and large-scale population screening programs.
- Soil:Complex matrices demanding inhibitor removal for agricultural and environmental microbiome analysis.
- Water:Low-biomass samples requiring concentration methods for pathogen surveillance in drinking water and recreational monitoring.
Blood samples sustain the majority of commercial assay revenue; Saliva is gaining share fastest through direct-to-consumer channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taq polymerase and modified nucleotide production clusters anchor supply-side geography in the United States, Germany, and China, while demand concentrates where reference laboratories and academic medical centers scale procurement.
United States
Hospital-affiliated laboratories and independent reference labs anchor molecular testing volume expansion. FDA premarket notification pathways for nucleic acid-based diagnostics accelerate commercial timelines for multiplex respiratory panels. The Boston-Cambridge corridor and San Diego biotech clusters concentrate platform development and clinical validation partnerships.
Germany
EU In Vitro Diagnostic Regulation compliance investments drive replacement of legacy immunoassays with CE-IVD marked molecular methods. EMA and notified body review capacities concentrate in Munich and Frankfurt, shaping regulatory service ecosystems. The Rhine-Main region hosts diagnostic manufacturers pursuing MDR technical documentation and post-market surveillance systems.
China
NMPA clearance pathways for nucleic acid-based diagnostics are streamlining as domestic manufacturers scale sequencing and PCR platform production. The Yangtze River Delta and Pearl River Delta clusters concentrate reagent manufacturing and instrument assembly operations. Shanghai and Shenzhen anchor clinical validation partnerships between domestic developers and tertiary hospital laboratories.
Japan
PMDA regulatory frameworks for companion diagnostics and prenatal screening panels impose steep analytical validation requirements. METI industrial policy supports genomic medicine infrastructure investments in Kanto and Kansai regions. Tokyo and Osaka academic medical centers absorb capital commitments for whole-genome and targeted oncology sequencing applications.
United Kingdom
NHS genomic medicine service expansion drives centralized procurement of next-generation sequencing platforms for rare disease and cancer applications. MHRA post-Brexit regulatory autonomy is reshaping conformity assessment pathways for molecular diagnostics. The Cambridge-London corridor concentrates platform development and clinical research organization partnerships.
Molecular Methods Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue point-of-care and decentralized testing modalities. The vendor base stratifies across integrated instrument-reagent ecosystems, modular assay developers, and specialty quantification platforms. Three archetypes dominate: end-to-end workflow suppliers, niche amplification technology specialists, and bioinformatic analysis service providers. Competitive moves concentrate on multi-year consumable subscription models and CLIA-waived device regulatory clearances.
Within the integrated ecosystem tier, Thermo Fisher Scientific Inc. and QIAGEN exemplify archetypes that bundle instruments, maintenance, and assay menus at per-test pricing. Bio-Rad Laboratories Inc. occupies a position among quantification specialists where absolute sensitivity commands premium positioning. These three anchors represent how scale-driven consolidation, automated workflow loyalty, and digital PCR specialization respectively capture procurement decisions across diagnostic laboratory networks.
| Leading Market Players |
|---|
| QIAGEN |
| bioMérieux SA |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Abbott Laboratories |
| Hologic Inc. |
| Illumina Inc. |
| Others |
Cost & Logistics Intelligence
Subscription reagent purchasing models among academic medical centers and integrated delivery networks are compressing per-test margins and forcing suppliers to restructure service bundling to retain multi-year consumable commitments. This procurement shift concentrates pricing power with buyers who negotiate bundled instrument, maintenance, and assay menu contracts.
Pricing Analysis
Service-bundling differentiation separates integrated instrument-reagent ecosystems from unbundled reagent-only suppliers, with warranty coverage and technical training increasingly included in premium-tier contracts. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15189 accreditation support, FDA clearance tier, and automation integration depth. Pricing pressure stems from CLIA-waived point-of-care devices commoditizing routine infectious disease panels. Physician office laboratories exhibit highest price sensitivity due to capital constraints, while cancer centers absorb premium positioning for comprehensive genomic profiling.
Supply Chain Analysis
Dual-sourcing qualification mandates from diagnostic laboratory networks are fragmenting Taq polymerase procurement across United States, Germany, and China contract manufacturers to mitigate single-source vulnerability. Modified nucleotides, fluorescent probes, and thermal cycling instrumentation draw from concentrated chemical synthesis clusters in the Yangtze River Delta and Rhine-Main region. Tariff exposure on Chinese-sourced oligonucleotides threatens cost structures for assay developers lacking alternative qualified suppliers. Distribution runs through integrated delivery network group purchasing organizations and laboratory benefit managers consolidating procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over modified nucleotide supply and bioinformatic analysis pipelines determines margin sustainability. Players are pursuing backward integration into reagent manufacturing to escape polymerase supply concentration.
For Market Incumbents: Anchor installed-base loyalty through automated sample-to-insight workflow upgrades that increase switching costs for mid-sized diagnostic networks. Defend against CRISPR-based diagnostic entrants by accelerating CLIA-waived PCR device clearances for pharmacy clinic channels. Prioritize captive supply of Taq polymerase through contract manufacturer equity stakes or in-house fermentation capacity. For New Entrants and Emerging Players: The premium-economy price-point gap in point-of-care molecular testing creates white-space opportunity for isothermal amplification platforms targeting urgent care and community health centers. Penetrate pharmacy clinic channels previously served by centralized reference laboratories through same-day sexually transmitted infection and respiratory pathogen assays. Pursue go-to-market partnerships with laboratory benefit managers seeking to diversify supplier bases beyond entrenched PCR ecosystem vendors. For Investors and Strategic Acquirers: The window for entry favors digital PCR platform specialists and CRISPR diagnostic developers with regulatory validation partnerships. Long-term viability hinges on consolidation of bioinformatic analysis capabilities as NGS adoption compresses variant interpretation margins. Watch FDA premarket notification clearance timelines for multiplex respiratory panels as inflection indicator for platform commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Device Clearance | Unlocks pharmacy clinic and urgent care distribution channels beyond hospital laboratories. |
| Backward Integration into Reagent Manufacturing | Reduces Taq polymerase single-source vulnerability for high-volume assay developers. |
| Bioinformatic Platform Acquisition | Addresses talent scarcity in variant interpretation for NGS clinical validation timelines. |
| Multi-Year Consumable Subscription Model | Secures per-test pricing commitments from integrated delivery network group purchasing organizations. |
| EU MDR Technical Documentation Investment | Enables CE-IVD marked molecular method placement in European hospital laboratory compliance replacements. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body review capacities, and nucleic acid diagnostic reimbursement code valuations anchored the trend analysis, supplemented by interviews with diagnostic laboratory directors, biomedical engineers, group purchasing organization contract managers, and regulatory affairs specialists at platform developers. Secondary validation drew from FDA premarket notification databases, EMA companion diagnostic guidance documents, CMS clinical laboratory fee schedule updates, and ISO 15189 accreditation body reports. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down molecular testing procedure volume projections.
Input-output matrices mapped amplification technique, application, end-user scale, and sample type segmentation dimensions across the projection horizon. CAGRs derived from logistic adoption curves for NGS platform displacement of single-gene assays and infectious disease surveillance infrastructure buildout. Forecast inputs incorporated payer coverage policy shifts for comprehensive genomic profiling and public health laboratory capital appropriation cycles.
Underlying measurement precision varies by segment; Polymerase Chain Reaction and Pathogen Detection carry tighter precision than emerging CRISPR diagnostic and Agricultural Biotechnology categories due to established procedure reporting systems. Forecasts reflect documented assumptions regarding FDA premarket notification pathway efficiency and EU MDR notified body capacity expansion. Deviation in CLIA-waived device clearance velocity or Taq polymerase supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Monoclonal Antibody Custom Service Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market