
 Cell Line Development Services Market | 2026-2036
Cell Line Development Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Line Development Services Market Insights
CRISPR-Cas9 integration into mammalian cell engineering is reconfiguring how contract providers design stable production lines for complex biologics. Lonza Group leverages its integrated manufacturing footprint across Switzerland and North America to anchor high-value stable cell line programs for commercial-stage clients. WuXi Biologics competes on speed, sustaining rapid turnaround timelines through its China-based discovery and development campuses. Thermo Fisher Scientific controls instrument-to-service bundling, extending proprietary platform technologies into recurring cell line characterization contracts.
Cell line development services encompass the creation, optimization, and qualification of mammalian or microbial host systems expressing recombinant proteins, monoclonal antibodies, or viral vectors, typically requiring transfection efficiencies above 70 percent and specific productivity thresholds exceeding 20 picograms per cell per day for commercial viability. Stable cell line development commands the largest revenue share due to multi-year commercial supply agreements and regulatory filing requirements, while gene editing services represent the fastest-expanding category as sponsors seek targeted knock-in and knock-out modifications for next-generation modalities. CRISPR-Cas9 technology dominates current platform adoption, though TALEN retains niche positioning for applications demanding reduced off-target liability profiles.
FDA biologics license application standards and EMA good manufacturing practice guidelines for cell substrates shape validation requirements and documentation burdens across service providers. ISO 9001 quality management systems and ICH Q5D guidelines on cell substrate derivation further constrain market entry for smaller laboratories lacking dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving gene therapy-specific guidance from multiple agencies, as vector-producing cell line qualification protocols diverge from traditional protein expression paradigms and demand specialized analytical capabilities.
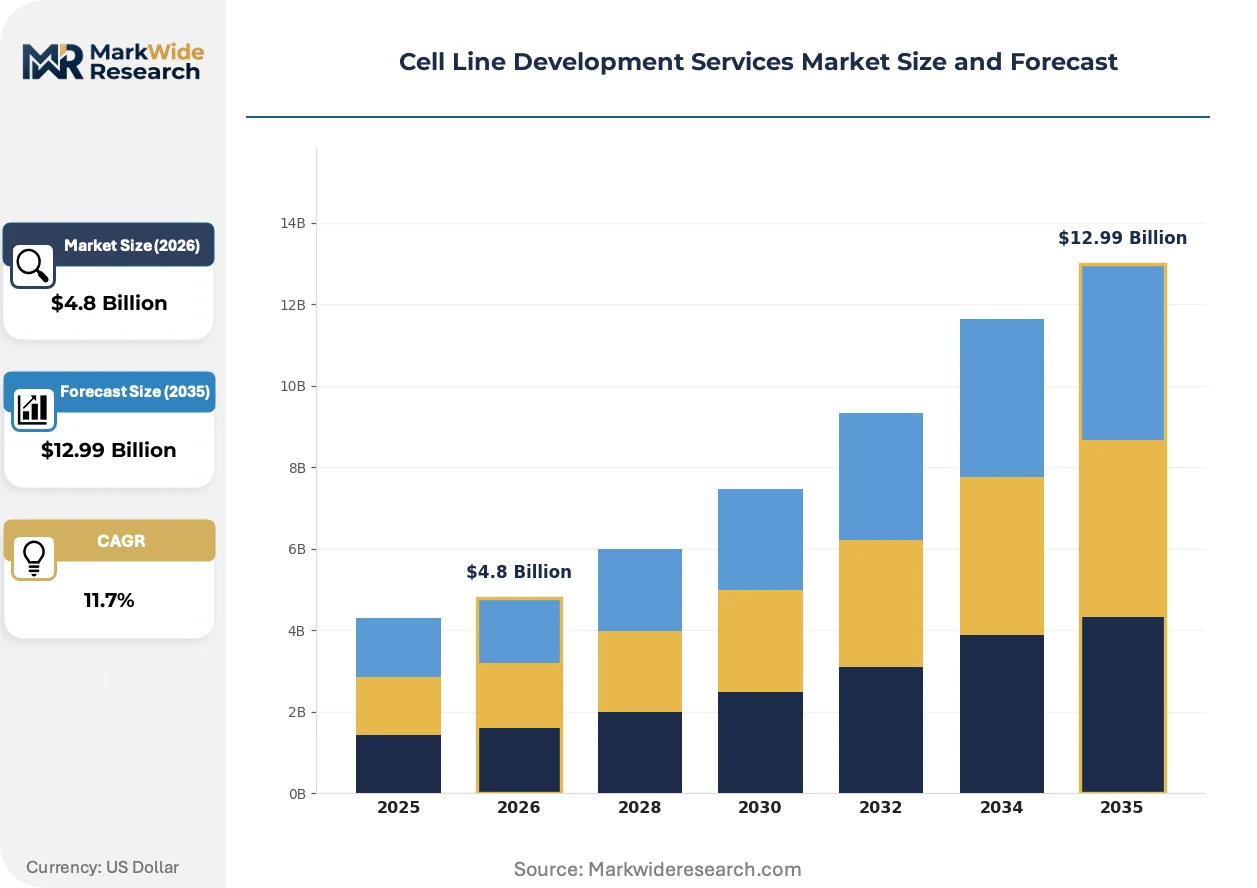
Market Dynamics
CRISPR-Cas9 integration into mammalian cell engineering is compressing development timelines from months to weeks, forcing contract providers to restructure service architectures around rapid gene-editing workflows rather than traditional selection-based methodologies.
Growth Catalysts
- EMA good manufacturing practice guidelines for cell substrates:Regulatory harmonization across European markets reduces duplicate qualification studies, accelerating cross-border commercialization timelines for biologics developers.
- Monoclonal antibody production outsourcing:Biopharmaceutical sponsors are divesting internal stable cell line capabilities to focus on clinical development, concentrating demand with specialized contract manufacturing organizations.
- Boston and San Diego biotech cluster density:Geographic concentration of venture-backed drug developers in these hubs sustains premium pricing for high-touch cell line engineering services.
Market Restraints
- Fetal bovine serum price volatility:Mammalian cell culture media costs fluctuate with agricultural commodity cycles, squeezing margins on fixed-price development contracts.
- Chinese CDMO capacity concentration:Heavy reliance on WuXi Biologics and similar providers for rapid-turnaround discovery services creates geopolitical supply risk exposure.
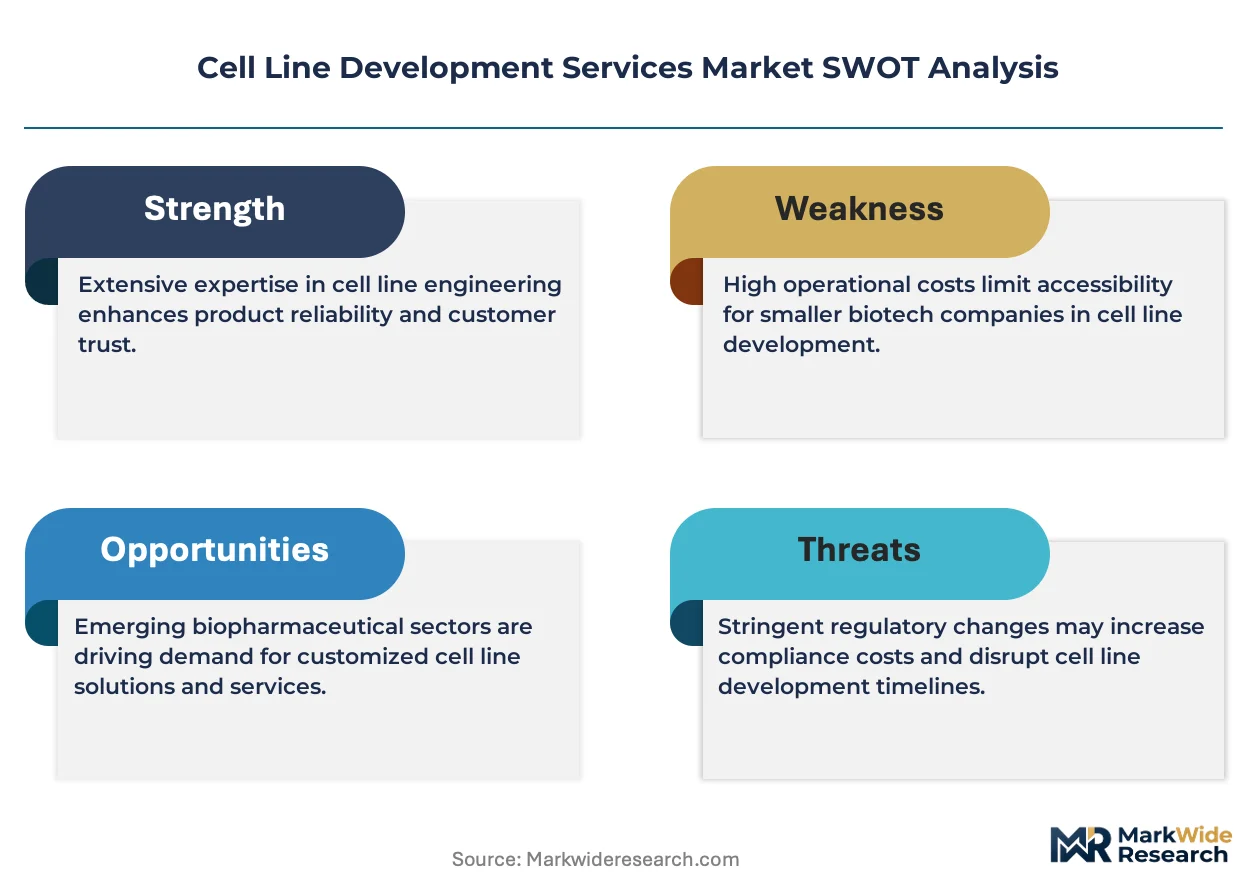
- Off-target CRISPR editing liability:Regulatory agencies demand extensive characterization data for gene-edited cell substrates, extending documentation burdens beyond traditional random integration methods.
Strategic Opportunities
- India's PLI scheme for biopharmaceutical manufacturing:Production-linked incentives attract contract development investment to underpenetrated South Asian markets with lower operational costs.
- Allogeneic cell therapy vector production:Viral vector-producing cell lines for CAR-T and stem cell therapies represent nascent demand with limited qualified supplier bases.
- ISO 9001 and ICH Q5D convergence:Unified quality frameworks enable single-audit qualification for multi-jurisdictional supply, reducing client onboarding friction.
Industry Challenges
- Gene editing specialist scarcity:CRISPR protocol optimization requires rare combinations of molecular biology and regulatory expertise, inflating compensation costs.
- GMP suite capex requirements:Dedicated containment facilities for viral vector-producing cell lines demand capital investments exceeding standard protein expression infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Line Development Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Stable Cell Line Development, Transient Cell Line Development, Gene Editing Services, Cell Line Characterization Application: Monoclonal Antibody Production, Recombinant Protein Manufacturing, Vaccine Development, Gene Therapy Research End User: Biopharmaceutical Companies, Contract Research Organizations, Academic Institutions, Biotechnology Firms Technology: CRISPR-Cas9, Zinc Finger Nucleases, TALEN, RNA Interference |
| Companies Covered | Lonza Group, WuXi Biologics, Thermo Fisher Scientific, Sartorius AG, Samsung Biologics, Merck KGaA, Charles River Laboratories, Danaher, Selexis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Line Development Services Market Trends and Innovations
Service providers are reconfiguring platform architectures around three intersecting forces: automated cell handling systems, evolving gene therapy regulatory frameworks, and compressed sponsor decision cycles that reward speed over customization depth.
Automated clone selection and single-cell dispensing systems are rendering obsolete manual limiting dilution methods that previously dominated stable cell line generation. Mid-sized biotech sponsors now mandate sub-12-week timelines from transfection to master cell bank, forcing providers to integrate high-content imaging and artificial intelligence-driven productivity prediction into standard workflows. This compression is eliminating price premiums for boutique manual services while rewarding capital-intensive platform standardization.
FDA gene therapy-specific guidance documents are diverging vector-producing cell line qualification protocols from traditional protein expression paradigms. The agency's enhanced expectations for replication-competent virus testing and extended cell substrate stability data are extending analytical development phases. Sponsors targeting the US market must now budget specialized virology capabilities that exceed standard cell line characterization requirements.
Sponsor procurement patterns are fragmenting across multiple specialized providers rather than consolidating with full-service partners. Large pharmaceutical developers now segment early gene editing, stable line generation, and GMP banking across distinct vendors with platform-specific expertise. This unbundling is most pronounced in the United States, where venture-backed biotechs prioritize milestone-based payment structures and rapid vendor switching over long-term partnership commitments.
Cell Line Development Services Market Segmentation
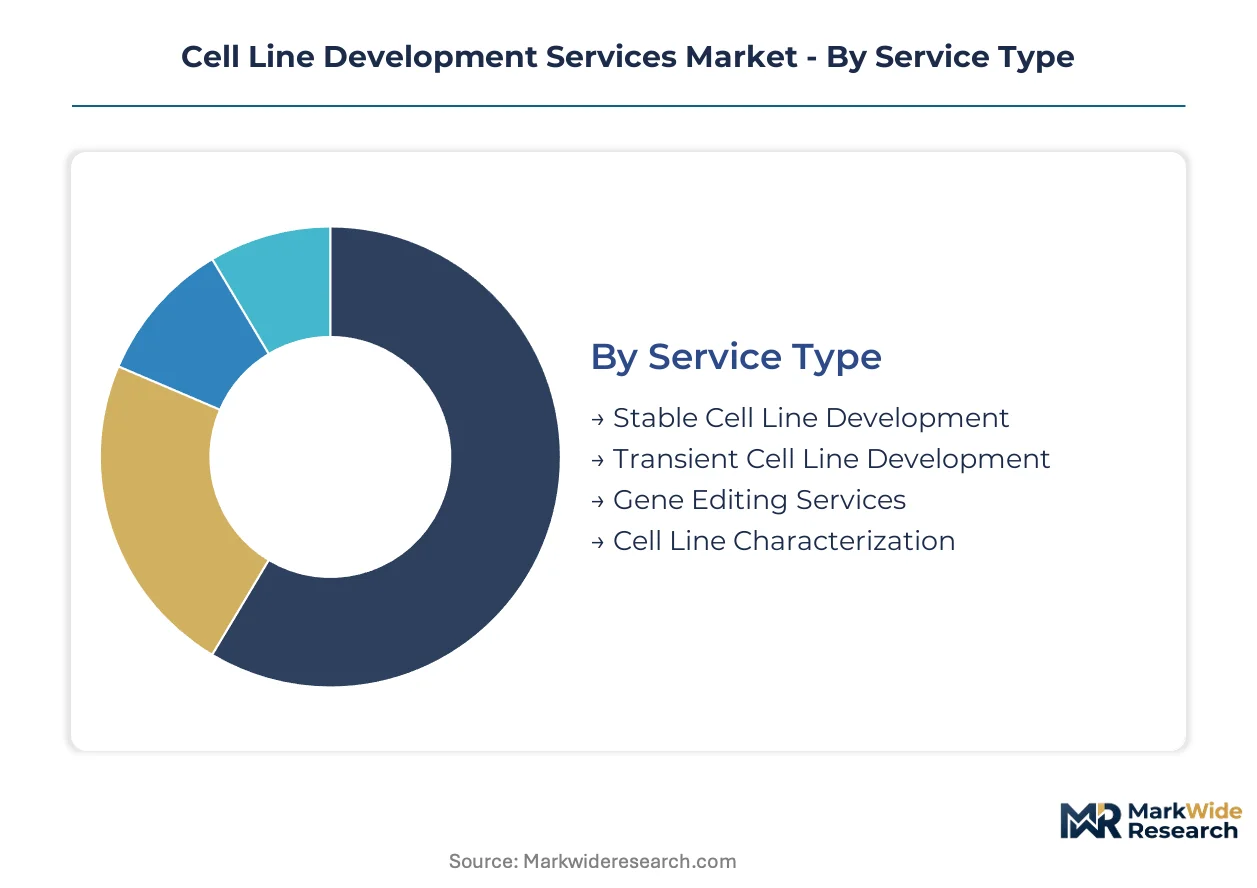
Service architectures in cell line development fragment across technical methodologies, therapeutic targets, and client sophistication levels. Procurement patterns diverge sharply between venture-backed biotechs seeking speed and large pharmaceutical developers demanding regulatory-ready documentation packages.
Service Type:
After-sales service intensity peaks with stable cell line programs, where multi-year commercial supply agreements demand continuous technical support and regulatory filing assistance.
- Stable Cell Line Development:Generation of permanently transfected host systems expressing recombinant proteins or monoclonal antibodies at commercial-scale productivity thresholds. Demand concentrates with FDA-tracked biologics sponsors in Boston and San Diego clusters, driven by multi-year master cell bank supply agreements and BLA documentation requirements.
- Gene Editing Services:Targeted knock-in, knock-out, and precision modification protocols using engineered nuclease platforms. CRISPR-Cas9 workflows are expanding most quickly in Cambridge and Research Triangle Park facilities, propelled by compressed timelines for next-generation modality development.
- Transient Cell Line Development:Short-duration expression systems for rapid protein production without permanent genomic integration.
- Cell Line Characterization:Analytical validation including identity testing, stability assessment, and adventitious agent screening.
Stable cell line development holds the largest share; momentum sits with gene editing services.
Application:
Cost tier stratification separates blockbuster-scale monoclonal antibody programs from exploratory gene therapy vector production with limited qualified supplier bases.
- Monoclonal Antibody Production:High-titer mammalian expression systems for therapeutic antibody candidates requiring specific productivity above 20 picograms per cell per day. Transfection efficiency mandates exceed 70 percent for commercial viability, with demand anchored by FDA biologics license pathway requirements.
- Gene Therapy Research:Viral vector-producing cell line qualification for CAR-T and stem cell therapy applications. Replication-competent virus testing demands are climbing fastest in United States-based facilities, shaped by divergent FDA guidance from traditional protein expression paradigms.
- Recombinant Protein Manufacturing:Industrial-scale expression of therapeutic enzymes, cytokines, and growth factors.
- Vaccine Development:Cell substrate qualification for viral vaccine production using qualified master cell banks.
Monoclonal antibody production commands premium pricing; gene therapy research shows the steepest expansion trajectory.
End User:
Customer type determines contract structure complexity, with biopharmaceutical companies demanding integrated manufacturing footprints and academic institutions prioritizing milestone-based payment flexibility.
- Biopharmaceutical Companies:Sponsors divesting internal stable cell line capabilities to focus on clinical development. Concentrated demand in United States venture-backed hubs sustains premium pricing for high-touch engineering services with dedicated regulatory affairs support.
- Contract Research Organizations:Intermediary procurement agents managing segmented vendor relationships across gene editing, stable line generation, and GMP banking.
- Academic Institutions:Research-scale projects with limited budgets and exploratory therapeutic targets.
- Biotechnology Firms:Mid-sized developers seeking rapid turnaround timelines through specialized platform providers.
Biopharmaceutical companies dominate revenue contribution; biotechnology firms are gaining share fastest.
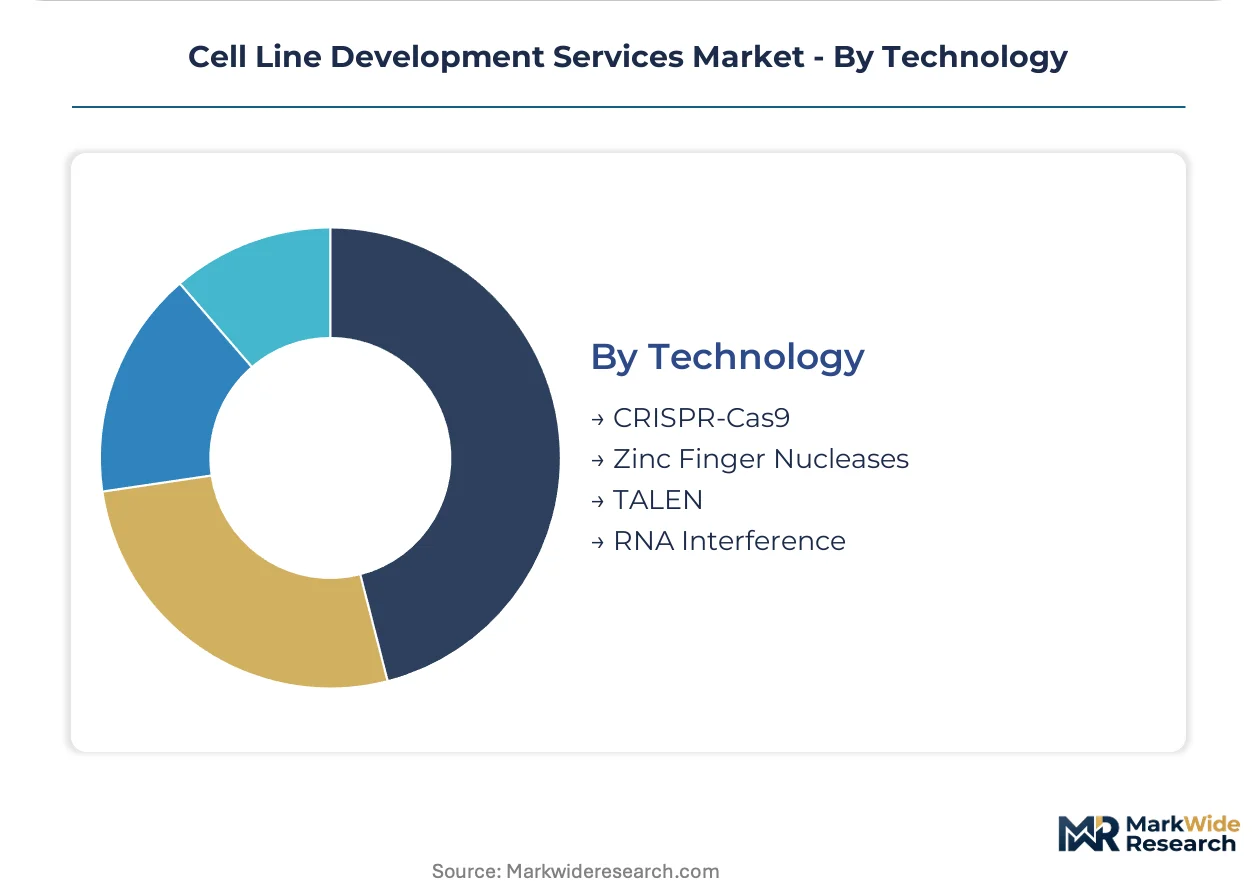
Technology:
Platform maturity creates divergent risk profiles, with established CRISPR workflows competing against TALEN's reduced off-target liability positioning for regulatory-sensitive applications.
- CRISPR-Cas9:Dominant gene editing platform compressing mammalian cell engineering timelines from months to weeks. Adoption concentrates in commercial-stage programs across Switzerland and North American manufacturing footprints, driven by protocol standardization and reagent cost reduction.
- TALEN:Transcription activator-like effector nucleases retaining niche positioning for applications demanding minimized off-target editing events. Regulatory agencies in the United States and Europe demand extensive characterization data, extending documentation burdens for gene-edited cell substrates.
- Zinc Finger Nucleases:First-generation programmable nuclease platform with established intellectual property landscapes.
- RNA Interference:Transient knockdown methodologies for exploratory target validation without permanent genomic modification.
CRISPR-Cas9 holds the largest share; TALEN maintains specialized positioning for liability-sensitive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in cell line development services tilt toward net service exports from Switzerland and the United States, while China and India absorb inbound contract manufacturing demand. Regulatory divergence between FDA and EMA pathways creates friction for sponsors seeking multi-jurisdictional filings.
United States
FDA biologics license application standards and dense venture capital availability concentrate premium service demand in Boston and San Diego clusters. The agency's gene therapy-specific guidance for vector-producing cell lines extends analytical development phases beyond traditional protein expression timelines. Cambridge and Research Triangle Park facilities now mandate sub-12-week turnaround timelines from transfection to master cell bank.
Switzerland
Swissmedic harmonization with EMA good manufacturing practice guidelines reduces duplicate qualification studies for European commercialization. Lonza Group anchors high-value stable cell line programs through integrated manufacturing footprints across Basel and North American satellite operations. The country's pharmaceutical heritage sustains premium pricing for regulatory-ready documentation packages.
China
WuXi Biologics competes on speed through discovery and development campuses in Shanghai and Wuxi, though geopolitical supply risk exposure concerns some sponsors. NMPA alignment with ICH Q5D guidelines accelerates domestic biologics development while dual carbon goals pressure energy-intensive GMP facility operations. Yangtze River Delta concentration of CDMO capacity creates vendor consolidation vulnerabilities.
Germany
Merck KGaA and Sartorius AG leverage precision engineering heritage in chromatography and single-use systems adjacent to cell line services. EMA regulatory affairs infrastructure in Frankfurt and Munich supports complex BLA documentation for European market entry. Bavaria's biotech corridor connects academic research institutions with commercial-scale manufacturing partners.
India
PLI scheme production-linked incentives attract contract development investment to underpenetrated South Asian markets with lower operational costs. CDSCO alignment with WHO prequalification standards opens access to emerging market biologics procurement. Hyderabad and Bengaluru clusters build viral vector-producing capabilities for CAR-T therapy export contracts.
Cell Line Development Services Market Competitive Landscape
On the supply side, the industry is consolidating around platform-standardized service architectures that reward capital intensity over boutique customization. Three strategic archetypes dominate: integrated manufacturing conglomerates with end-to-end biologics capabilities, speed-focused Asian CDMOs competing on compressed timelines, and instrument-to-service bundlers leveraging proprietary platform technologies. M&A activity concentrates on gene editing specialist acquisitions and GMP facility capacity expansion in viral vector production.
Among integrated Swiss-American conglomerates, Lonza Group exemplifies the premium-tier stable cell line developer with multi-continent manufacturing footprints. WuXi Biologics occupies a position within the rapid-turnaround archetype, sustaining competitive pressure through China-based operational scale. Thermo Fisher Scientific represents the instrument-to-service bundler model, extending proprietary platform technologies into recurring characterization contracts. These three anchors illustrate how geographic specialization and capability depth stratify competitive positioning across contract manufacturing segments.
| Leading Market Players |
|---|
| Lonza Group |
| WuXi Biologics |
| Thermo Fisher Scientific |
| Sartorius AG |
| Samsung Biologics |
| Merck KGaA |
| Charles River Laboratories |
| Danaher |
| Selexis SA |
| Others |
Pricing and Supply Chain Analysis
Fetal bovine serum price volatility determines both margin compression in fixed-price development contracts and the geographic reconfiguration of mammalian cell culture operations toward lower-cost South Asian markets. Biopharmaceutical sponsors in Boston and San Diego clusters absorb premium pricing for rapid-turnaround services while procurement teams diversify media sourcing to mitigate agricultural commodity cycle exposure.
Pricing Analysis
Biopharmaceutical companies anchor project-based pricing structures that stratify across GMP certification tiers, master cell bank complexity, and regulatory filing support depth. Price differentiation hinges on FDA biologics license pathway documentation packages and after-sales technical support intensity. Cost compression in standard transient expression services is intensifying because automated clone selection platforms eliminate manual service premiums. Academic institutions exhibit highest price sensitivity, while commercial-stage sponsors prioritize speed over unit economics.
Supply Chain Analysis
Upstream fetal bovine serum sourcing draws from Australia, New Zealand, and South American agricultural markets, with specialty media formulations resting on German and Swiss precision chemical suppliers. CRISPR reagent manufacturing concentrates in United States and Chinese production facilities. Single-source vulnerability in Chinese CDMO capacity creates geopolitical risk exposure for rapid-turnaround discovery services. Distribution runs through direct contractual relationships between sponsors and specialized contract manufacturing organizations, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell line development services represent a service-attach opportunity where recurring cell line characterization contracts and multi-year master cell bank supply agreements expand faster than one-time transfection projects. Regulatory filing assistance and continuous technical support layers now command margin premiums exceeding initial engineering fees.
For Market Incumbents: Entrench platform-standardized workflows by integrating automated clone selection systems that compress timelines below 12 weeks, defending against speed-focused Asian CDMOs. Acquire gene editing specialist capabilities to fill CRISPR protocol optimization talent gaps. Backward integration into proprietary media formulations mitigates fetal bovine serum cost volatility. For New Entrants and Emerging Players: Viral vector-producing cell line qualification for CAR-T therapy applications in India and Southeast Asia represents the most penetrable entry point, given limited qualified supplier bases and PLI scheme production-linked incentives. Target mid-sized biotechnology firms in Research Triangle Park seeking milestone-based payment flexibility rather than long-term partnership commitments. Lead with GMP facility investment in lower-operational-cost geographies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturing conglomerates with end-to-end biologics capabilities over boutique manual service providers. Long-term viability rests on capital-intensive platform standardization rather than customization depth. Acquisition targets should demonstrate regulatory-ready documentation infrastructure and multi-continent manufacturing footprints. Monitor FDA gene therapy-specific guidance divergence from protein expression paradigms as inflection indicator for specialized virology capability valuations.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Capacity Expansion | Dedicated containment infrastructure for viral vector-producing cell lines exceeds standard protein expression capital requirements. |
| Gene Editing Specialist Acquisition | CRISPR protocol optimization talent scarcity inflates compensation costs and constrains service scalability. |
| Regulatory Affairs Infrastructure Investment | FDA biologics license application standards and EMA good manufacturing practice guidelines shape documentation burdens. |
| Automated Clone Selection Platform Deployment | High-content imaging and artificial intelligence-driven productivity prediction render manual limiting dilution methods obsolete. |
| Multi-Continent Manufacturing Footprint Establishment | Swissmedic harmonization with EMA guidelines and FDA pathway requirements demand dual-jurisdictional qualification capabilities. |
Research Methodology
Desk research of FDA biologics license application filings, EMA good manufacturing practice guideline documents, and ClinicalTrials.gov cell line derivation protocols preceded structured interviews with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and gene therapy vector production specialists. Secondary validation drew from SEC 10-K disclosures of publicly traded CDMOs, ISO 9001 certification databases, and ICH Q5D guideline implementation reports. Bottom-up service revenue modeling triangulated against top-down biopharmaceutical outsourcing spend estimates.
Assumptions held fixed include regulatory framework stability across FDA and EMA jurisdictions, CRISPR-Cas9 platform dominance over alternative nuclease technologies, and continued biopharmaceutical sponsor divestment of internal stable cell line capabilities. The analytical framework segmented revenue across service type, application, end user, and technology platform dimensions across the analysis window. CAGRs were derived from weighted regression of historical outsourcing penetration rates and projected biologics pipeline expansion. Forecast inputs incorporated transfection efficiency thresholds, specific productivity benchmarks, and master cell bank generation timelines.
Practitioners should monitor NMPA regulatory alignment shifts, geopolitical supply risk exposure in Chinese CDMO capacity, and evolving FDA gene therapy guidance divergence for early signals requiring forecast revision. Cross-checking against CDSCO and WHO prequalification standard adoption rates in emerging markets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Global Reporter Gene Assay Market