
 Canada Insulin Drugs and Delivery Devices Market | 2026-2036
Canada Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Insulin Drugs and Delivery Devices Market Outlook
The capability gap between pump-focused hardware investments and conventional drug portfolios is rotating competitive capital across the Canadian insulin landscape. Novo Nordisk leverages its integrated drug-device ecosystem to sustain premium positioning in long-acting formulations. Medtronic anchors its presence through continuous glucose monitor and pump bundling, while Sanofi competes on basal insulin analog scale and hospital contract breadth.
Canada Insulin Drugs and Delivery Devices encompass biologically active peptide formulations for glycemic control and mechanical or electronic systems for subcutaneous administration, with modern pumps delivering basal rates as precise as 0.025 units per hour and most analogs requiring recombinant DNA production in microbial or mammalian cell cultures. Long-acting insulin and insulin pens together occupy the mature volume core, where provincial tendering compresses margins but locks in formulary placement. Continuous glucose monitors represent the fastest-growing delivery device category, propelled by expanded reimbursement under Ontario and British Columbia public programs.
Health Canada, the Patented Medicine Prices Review Board, and provincial public drug plans collectively govern market access, pricing ceilings, and reimbursement eligibility for insulin therapies and delivery hardware across Canada. The PMPRB's revised pricing guidelines force manufacturers to benchmark against lower-cost European biosimilars, accelerating generic substitution in provincial formularies. Stakeholders must monitor the pace of provincial CGM reimbursement harmonization and the resulting shift in device procurement from hospital channels to direct home-care distribution.
Market Dynamics
Health Canada's biosimilar interchangeability guidelines are compressing brand insulin margins while accelerating provincial formulary turnover, forcing manufacturers to rebalance R&D portfolios toward delivery device ecosystems.
Growth Catalysts
- Provincial CGM Reimbursement:Ontario and British Columbia public drug plans now cover continuous glucose monitors for Type 1 and insulin-dependent Type 2 patients, expanding the addressable patient pool beyond private insurance holders.
- Aging Demographics:Canadians over 65 now represent the fastest-growing diabetes cohort, with home care preference driving demand for pen injectors and patch pumps over hospital-administered vial-and-syringe protocols.
- Biologics Manufacturing Scale:Recombinant DNA production capacity at mammalian cell culture facilities in Quebec and Ontario is expanding, reducing import dependency for long-acting analogs.
Market Restraints
- PMPRB Pricing Benchmarks:The Patented Medicine Prices Review Board's revised guidelines force Canadian insulin prices toward median OECD levels, eroding margin buffers for novel formulations.
- Single-Source API Concentration:Active pharmaceutical ingredient supply for recombinant human insulin concentrates among three global fermentation facilities, creating vulnerability to contamination or geopolitical disruption.
- Refrigeration Infrastructure Gaps:Cold chain requirements for unopened insulin vials limit distribution reach into remote northern communities lacking consistent 2-8°C storage.
Strategic Opportunities
- Atlantic Canada Penetration:Newfoundland and Labrador, Nova Scotia, and New Brunswick maintain below-national CGM adoption rates, presenting whitespace for device manufacturers with province-specific reimbursement advocacy.
- Pump-Pen Convergence:Smart pen systems integrating dose logging, glucose data, and clinician connectivity are capturing patients between conventional injection and full pump therapy.
- Indigenous Health Partnerships:Federal Non-Insured Health Benefits program expansion creates a direct procurement channel bypassing provincial formulary fragmentation for First Nations and Inuit patients.
Industry Challenges
- Specialized Bioprocess Engineering Talent:Mammalian cell culture scale-up expertise remains concentrated among legacy biologics manufacturers, constraining new entrant production capacity.
- Health Canada Device Licensing Timelines:Software-as-medical-device classifications for closed-loop algorithms extend review cycles 12-18 months beyond hardware-only submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Insulin Drugs and Delivery Devices Market |
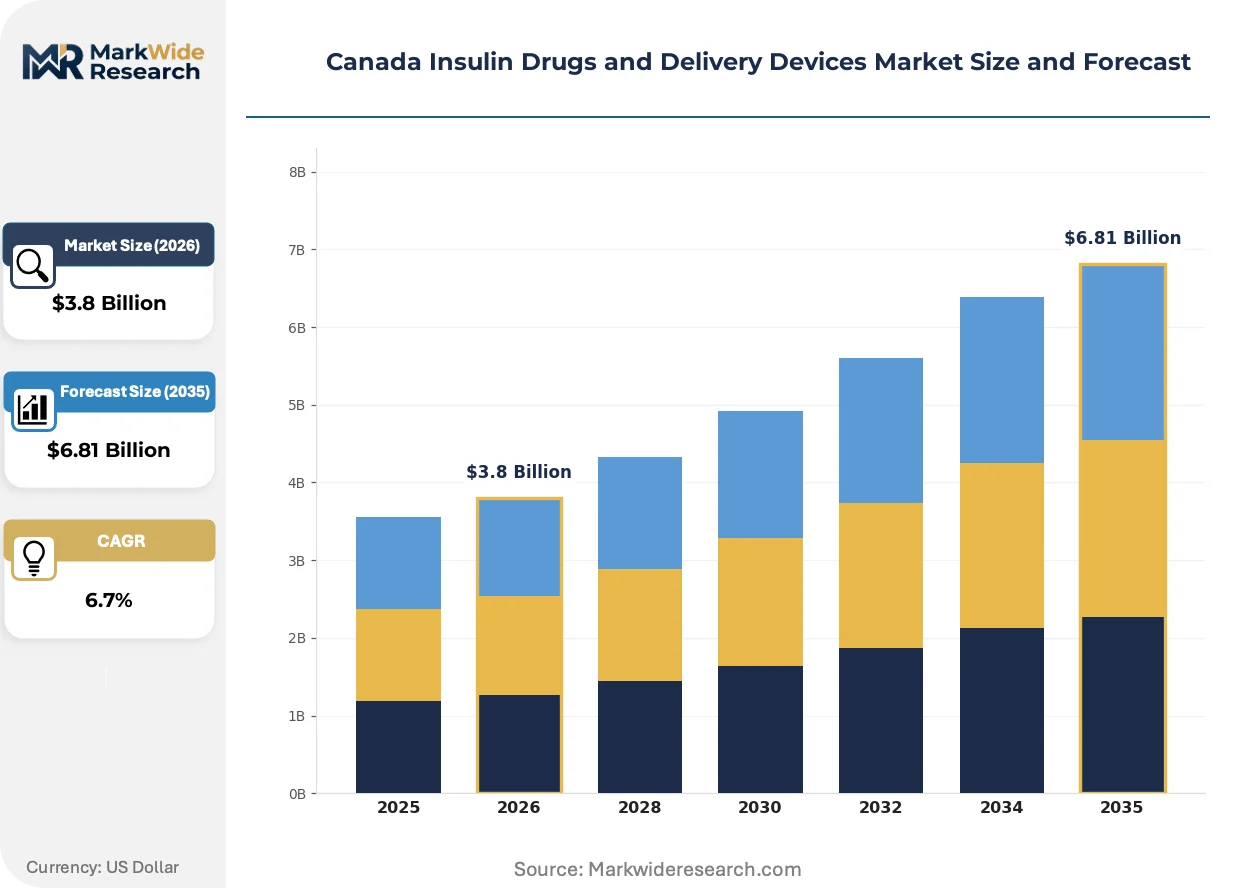
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Insulin Pumps Delivery Device: Insulin Pens, Syringes, Jet Injectors, Continuous Glucose Monitors End User: Hospitals, Clinics, Home Care, Retail Pharmacies Application: Diabetes Management, Emergency Treatment, Pediatric Care, Elderly Care |
| Companies Covered | Medtronic, Ypsomed, Novo Nordisk, Julphar, Biocon, Sanofi, Becton Dickinson, Roche, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Insulin Drugs and Delivery Devices Market Strategic Shifts
Device miniaturization and algorithm-driven dosing are converging to displace conventional injection protocols, while provincial procurement centralization is rewriting how manufacturers access patient populations.
Patch pump technology is miniaturizing basal-bolus delivery into adhesive-mounted devices under 25 grams. Adolescents and young adults with Type 1 diabetes are adopting these systems at twice the rate of conventional tubed pumps. This form factor compression is enabling direct-to-consumer channels and reducing pharmacy intermediation.
Health Canada's 2023 biosimilar interchangeability framework now permits automatic substitution at pharmacy level without prescriber consultation for designated insulin products. Provincial formularies in Quebec and Ontario are accelerating biosimilar tender awards, compressing originator volume retention. Manufacturers with vertically integrated device portfolios are responding by bundling delivery hardware with long-acting analog contracts.
Home care channels are displacing hospital-based diabetes education and device initiation. Community pharmacy networks in Alberta and Manitoba now deliver CGM training, pump setup, and remote monitoring support previously concentrated in endocrinology clinics. This channel migration is most advanced in urban centers with established pharmacy-led chronic disease management programs.
Canada Insulin Drugs and Delivery Devices Market Segmentation
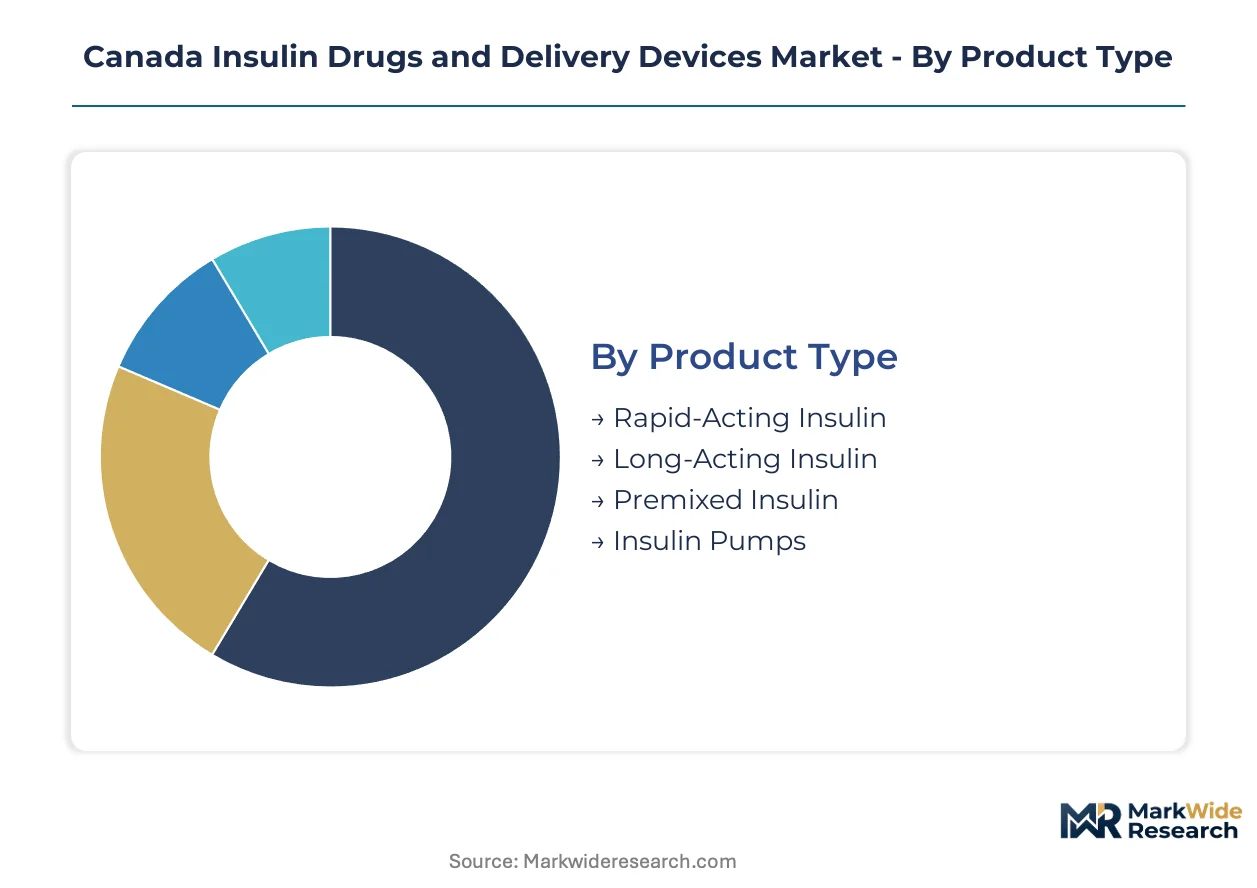
Canada's insulin market segments along therapeutic mechanism, administration technology, care setting, and patient population. Provincial formulary structures and reimbursement tiers create distinct margin pools across each dimension, with device-integrated therapies commanding premium positioning against commodity analogs.
Product Type:
Margin concentration pools in long-acting formulations and pump-integrated delivery systems, where patent protection and device bundling sustain pricing power against biosimilar erosion.
- Rapid-Acting Insulin:Lispro, aspart, and glulisine analogs formulated for 15-minute onset and 3-5 hour duration. Demand concentrates in Ontario and Quebec Type 1 diabetes populations where postprandial glucose control drives formulary placement, constrained by PMPRB pricing benchmarks that compress novel formulation premiums.
- Long-Acting Insulin:Glargine and degludec formulations engineered for 24-hour basal coverage with reduced hypoglycemia risk. Ontario's aging Type 2 cohort drives volume concentration, with provincial tendering locking in multi-year contracts that trade margin for formulary exclusivity.
- Premixed Insulin:Fixed-ratio basal-bolus combinations serving patients with limited self-monitoring capacity, prevalent in rural Manitoba and Saskatchewan where endocrinology access is sparse.
- Insulin Pumps:Electronic delivery systems with programmable basal rates and bolus calculators, capturing pediatric and young adult Type 1 patients in British Columbia and Alberta where private insurance penetration is highest.
The dominant share belongs to Long-Acting Insulin, while Insulin Pumps are gaining share fastest through expanded provincial reimbursement.
Delivery Device:
Device selection correlates with patient dexterity, reimbursement tier, and clinical supervision intensity, with smart systems capturing patients migrating from conventional injection.
- Insulin Pens:Disposable and reusable cartridge systems with dose dial features, dominating Quebec and Ontario home care channels where elderly Type 2 patients prefer simplified administration over vial-and-syringe protocols.
- Syringes:Conventional U-100 and U-40 calibrated devices, concentrated in hospital and long-term care settings where nursing staff administer doses, facing volume erosion from pen adoption.
- Jet Injectors:Needle-free pressure delivery systems for needle-phobic patients, niche positioning in pediatric endocrinology clinics with limited provincial coverage.
- Continuous Glucose Monitors:Factory-calibrated sensors with real-time glucose transmission, expanding most quickly in British Columbia and Ontario where public reimbursement now covers insulin-dependent Type 2 patients previously excluded from private coverage.
Insulin Pens retain volume leadership, though Continuous Glucose Monitors show the steepest expansion trajectory as provincial programs harmonize coverage.
End User:
Care setting determines procurement channel, with hospital contracts emphasizing volume scale and home care channels prioritizing patient training and remote monitoring infrastructure.
- Hospitals:Acute care settings managing diabetic ketoacidosis, perioperative glycemic control, and pregnancy complications, procuring through provincial group purchasing organizations with formulary compliance mandates.
- Clinics:Endocrinology and primary care practices in Toronto, Montreal, and Vancouver performing device initiation and dose titration, transitioning toward remote monitoring models.
- Home Care:Community-based administration for aging patients with mobility limitations, fastest-growing channel in Atlantic Canada where hospital-at-home programs expand.
- Retail Pharmacies:Dispensing points for pen and vial prescriptions, increasingly delivering CGM training and pump setup services in Alberta's pharmacy-led chronic disease networks.
Retail Pharmacies capture the dominant patient touchpoint volume, while Home Care is expanding most quickly through provincial aging-in-place initiatives.
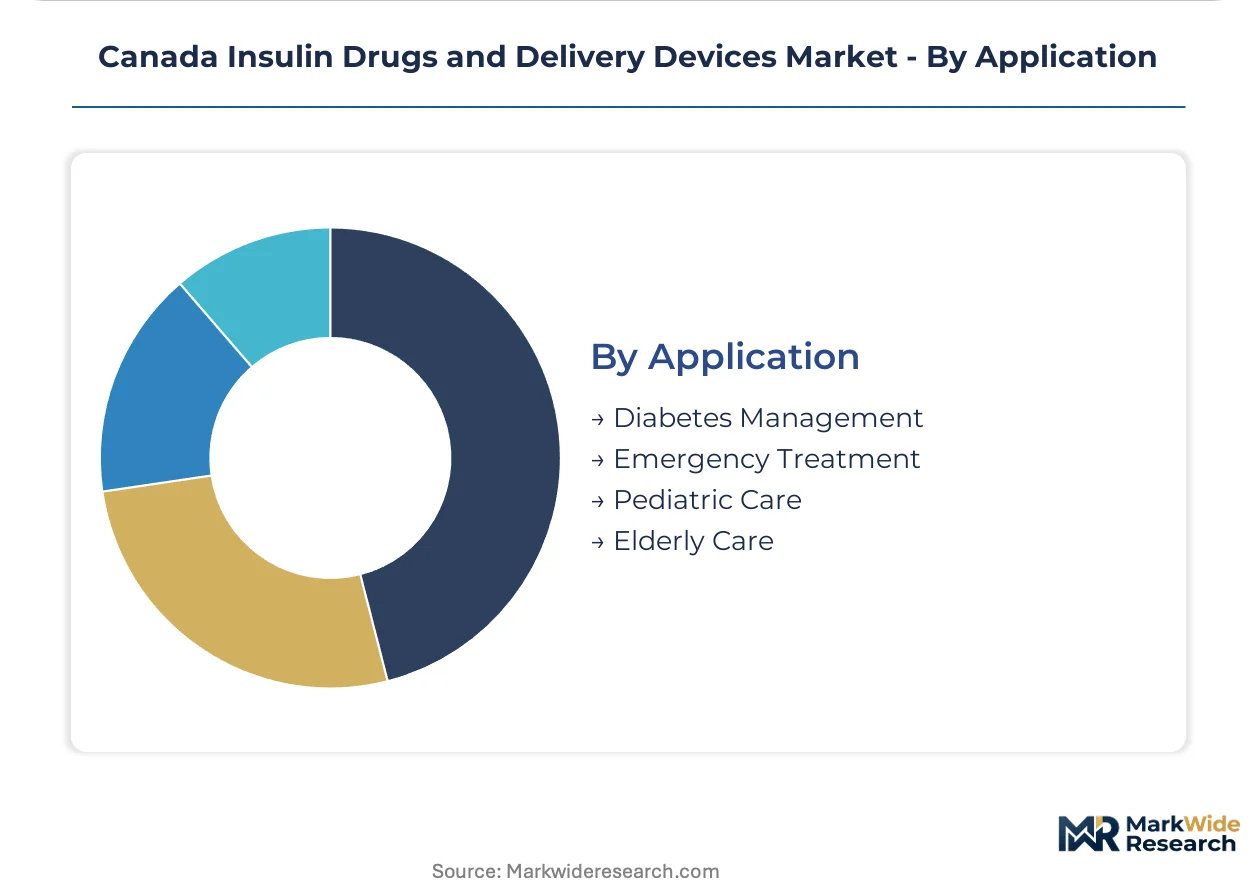
Application:
Clinical use case segments by acuity, patient age, and comorbidity profile, with pediatric and elderly applications driving device innovation requirements.
- Diabetes Management:Chronic glycemic control across Type 1 and Type 2 populations, the foundational application occupying the majority of insulin volume and device deployment.
- Emergency Treatment:Hypoglycemia reversal with glucagon formulations and hyperglycemic crisis management in emergency departments, concentrated in urban trauma centers.
- Pediatric Care:Type 1 diabetes management in patients under 18, driving demand for patch pumps and automated insulin delivery systems with parental monitoring features.
- Elderly Care:Simplified regimens for patients with cognitive or functional limitations, prevalent in long-term care facilities across Ontario and Quebec with high staff-to-patient ratios.
Diabetes Management holds the dominant application share, while Elderly Care is climbing the fastest as demographic aging accelerates demand for simplified delivery systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's insulin market runs a structural trade deficit in finished drug products, offset by device manufacturing exports concentrated in Ontario and Quebec. Provincial procurement centralization shapes regional demand patterns more than raw population distribution.
Ontario
Toronto's endocrinology density drives pump and CGM adoption rates above national averages. Health Ontario's expanded public coverage for continuous glucose monitors since 2022 has shifted device procurement toward home care channels. The Mississauga-Brampton corridor hosts distribution centers serving the province's aging Type 2 population.
Quebec
Montreal's biologics manufacturing base supplies recombinant insulin analogs across Eastern Canada. The province's formulary tendering system locks in multi-year contracts that trade margin for volume security. Laval's medical device cluster produces pen injector components for North American distribution.
Alberta
Calgary and Edmonton's pharmacy-led chronic disease networks deliver CGM training and pump setup services previously concentrated in clinics. Private insurance penetration here exceeds national averages, sustaining premium device pricing. The province's hospital-at-home expansion redirects insulin delivery from acute care to community settings.
British Columbia
Vancouver's technology corridor attracts digital health startups integrating glucose sensors with mobile platforms. PharmaCare's 2023 reimbursement expansion for insulin-dependent Type 2 patients doubled the addressable CGM pool. Victoria's aging population drives demand for simplified pen systems over vial-and-syringe protocols.
Atlantic Canada
Newfoundland and Labrador's below-national CGM adoption rates present whitespace for device manufacturers with province-specific advocacy. The federal Non-Insured Health Benefits program creates a direct procurement channel for First Nations patients bypassing provincial fragmentation. Halifax's diabetes education centers remain the primary device initiation points in the region.
Canada Insulin Drugs and Delivery Devices Market Competitive Environment
Concentration sits with integrated drug-device ecosystems and specialized pump manufacturers competing against commodity analog producers. The market structure tiers into three strategic archetypes: vertically integrated biologics-device combinations, standalone delivery hardware specialists, and biosimilar-focused pure-play drug manufacturers. Competitive moves center on provincial formulary bundling contracts and reimbursement advocacy for sensor-augmented pump systems.
Within the integrated ecosystem tier, Novo Nordisk and Medtronic exemplify contrasting approaches to patient lock-in through hardware-software combinations. Sanofi occupies a position bridging basal insulin scale with emerging device partnerships. Among standalone pump specialists, Ypsomed represents the miniaturization trajectory displacing conventional tubed systems. These three anchors illustrate how Canadian provincial procurement rewards either full-stack integration or focused hardware innovation, with limited middle ground for undifferentiated analog producers.
| Leading Market Players |
|---|
| Medtronic |
| Ypsomed |
| Novo Nordisk |
| Julphar |
| Biocon |
| Sanofi |
| Becton Dickinson |
| Roche |
| Eli Lilly |
| Others |
Value Chain & Pricing Dynamics
Ninety-day cold-chain inventory buffers at Ontario distribution hubs concentrate pricing power among manufacturers with captive mammalian cell culture capacity, while provincial tendering systems compress margins for originator analogs lacking device bundling. This inventory-leadtime structure forces biosimilar producers to absorb logistics costs to secure formulary placement against integrated competitors.
Pricing Analysis
The customization-premium spread between pump-integrated therapy bundles and standard pen formulations now exceeds the gap between originator and biosimilar analogs alone. Contract-based long-term offtake agreements dominate, with provincial formularies trading multi-year volume commitments for price ceilings. Price differentiation rests on Health Canada interchangeability designation and CGM compatibility certification. Cost compression in basal insulin tenders is intensifying because PMPRB benchmarks force parity with European biosimilars. Hospital procurement committees show highest price sensitivity; pediatric endocrinology clinics demonstrate lowest sensitivity due to outcome-based reimbursement for automated delivery systems.
Supply Chain Analysis
Inventory-leadtime observations reveal 45-60 day fermentation cycle dependencies for recombinant insulin APIs concentrated in Denmark, Germany, and the United States. Active pharmaceutical ingredient supply draws from microbial and mammalian cell culture facilities with single-source vulnerability for certain long-acting analog strains. Cold chain logistics for temperature-sensitive finished goods creates tariff-exposed distribution chokepoints at customs clearance points. Distribution runs through provincial pharmaceutical wholesalers with direct-to-pharmacy penetration expanding in Alberta and British Columbia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's biosimilar interchangeability framework constitutes a regulatory inflection accelerating device-differentiation strategies across the insulin landscape. This disruption rewards manufacturers with integrated hardware-software ecosystems over pure-play drug portfolios.
For Market Incumbents: Fortify formulary position by bundling CGM-enabled pump systems with long-acting analog contracts in Ontario and Quebec. Deepen backward integration into sensor manufacturing to offset PMPRB pricing compression on drug margins. Prioritize Health Canada software-as-medical-device licensing for closed-loop algorithms to extend competitive moats beyond commodity biosimilar substitution.
For New Entrants and Emerging Players: Lead with patch pump miniaturization targeting Atlantic Canada provinces where CGM penetration lags national benchmarks. Exploit the federal Non-Insured Health Benefits procurement channel for First Nations patients bypassing provincial tender fragmentation. Position smart pen systems with dose-logging connectivity as bridge products for Type 2 patients between conventional injection and full pump therapy.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharma parents divesting non-core diabetes device portfolios amid biosimilar margin erosion. Five-to-ten year viability favors manufacturers with captive biologics production and software companion development capabilities. Monitor provincial CGM reimbursement harmonization velocity as the inflection signal for home-care channel migration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Software-as-Medical-Device Licensing | Accelerates closed-loop insulin delivery approval timelines against hardware-only competitors. |
| Provincial Formulary Bundling Contracts | Locks multi-year volume commitments for integrated drug-device ecosystems in Ontario and Quebec. |
| CGM Reimbursement Advocacy | Expands addressable patient pool beyond private insurance in British Columbia and Atlantic provinces. |
| Backward Integration into Sensor Manufacturing | Captures margin from glucose monitoring hardware previously sourced from third-party suppliers. |
| Indigenous Health Partnership Development | Creates direct federal procurement channel bypassing provincial formulary fragmentation for First Nations patients. |
Study Parameters
Desk research of Health Canada regulatory filings, provincial formulary databases, and PMPRB pricing disclosure records preceded structured interviews with endocrinology clinic directors, hospital procurement managers, provincial drug plan administrators, and CGM distribution specialists. Primary fieldwork with device training pharmacists and diabetes educator networks in Alberta and British Columbia validated secondary estimates of home-care channel migration velocity. Bottom-up patient population modeling triangulated against top-down manufacturer shipment data.
Variance decomposition across therapeutic mechanism, delivery technology, care setting, and patient age cohort shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by provincial reimbursement expansion schedules and biosimilar interchangeability adoption curves. Modeled inputs incorporated Health Canada approval pathway timelines and PMPRB pricing benchmark revisions.
The analysis sits within stated boundaries; outcomes outside sustained provincial CGM reimbursement expansion or prolonged Health Canada software review cycles would require recalibration. Forecasts reflect documented assumptions regarding biosimilar formulary penetration and cold chain infrastructure investment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Human Insulin Market