
 Prenatal Genetic Testing Market | 2026-2036
Prenatal Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal Genetic Testing Market Intelligence
Cell-free DNA analysis is pivoting from research-grade protocols to clinical-grade workflows, compressing per-test costs while preserving sensitivity thresholds. Illumina Inc. leverages its sequencing instrument installed base to dominate reagent pull-through economics. Thermo Fisher Scientific anchors its position through integrated sample-to-answer platforms that reduce laboratory turnaround times. Natera Inc. specializes in proprietary bioinformatics pipelines that differentiate its NIPT offerings from commodity sequencing services.
Prenatal genetic testing encompasses laboratory and imaging modalities that assess fetal chromosomal, genetic, and structural conditions during gestation, typically employing next-generation sequencing of cell-free fetal DNA in maternal plasma or invasive tissue sampling with karyotyping. The primary purpose centers on enabling informed reproductive decision-making and guiding prenatal clinical management. Non-invasive prenatal testing leads the test type category due to superior safety profiles and expanding gestational-age windows, while digital PCR represents the fastest-growing technology segment as laboratories seek lower-cost alternatives to comprehensive sequencing for targeted aneuploidy detection. Diagnostic laboratories capture the largest end-user margin pool because of their capital-intensive infrastructure and high-throughput operational scale.
The FDA regulates prenatal screening devices as in vitro diagnostics, requiring analytical and clinical validation submissions that shape product development timelines and market entry pathways. CMS reimbursement determinations and state-level Medicaid coverage policies directly influence patient access and laboratory revenue stability across the United States. EMA's In Vitro Diagnostic Regulation imposes stricter performance and post-market surveillance standards in Europe, elevating compliance costs for manufacturers serving that geography. Stakeholders must monitor evolving payer evidence requirements for expanded NIPT indications beyond common aneuploidies.
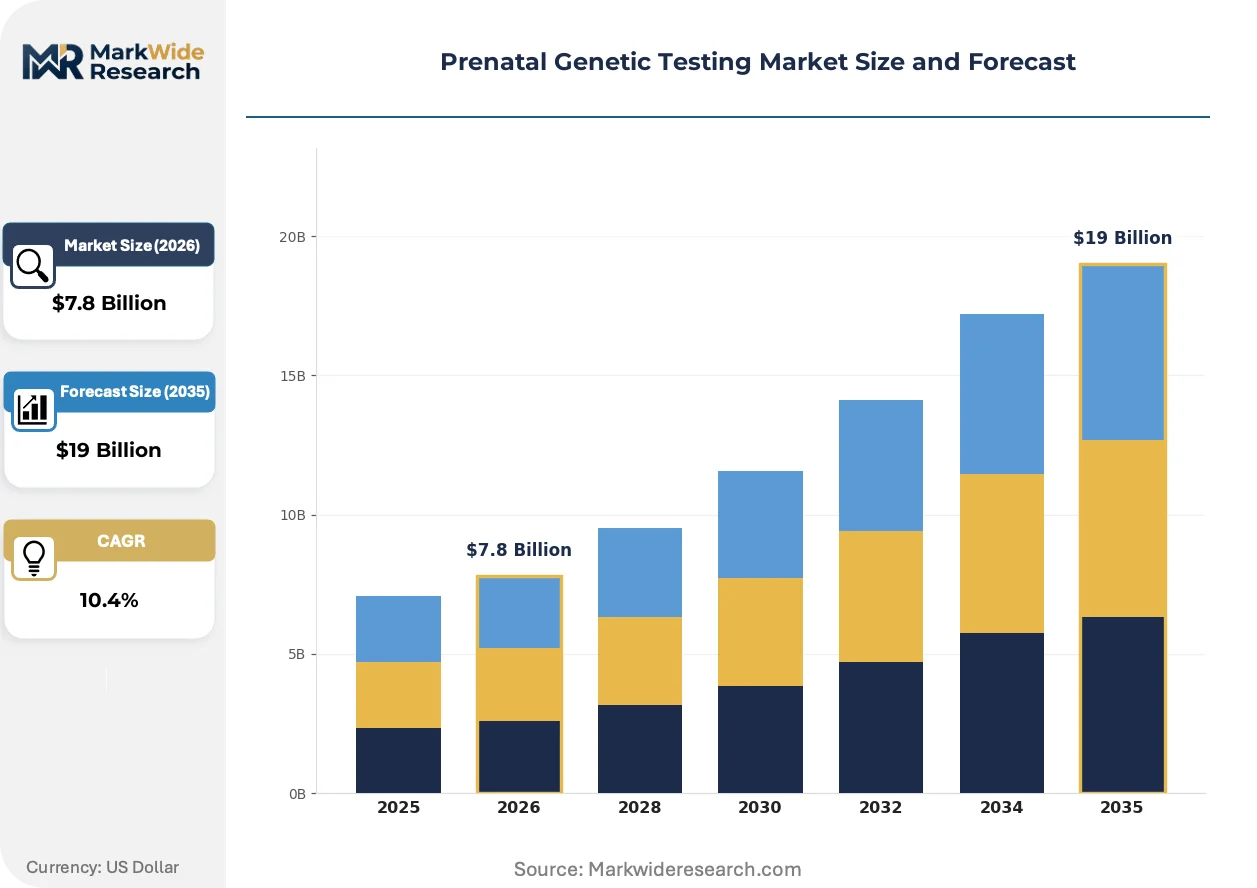
Market Dynamics
Cell-free DNA sequencing economics are compressing per-test costs below reimbursement thresholds, triggering a volume shift from high-complexity academic medical centers toward mid-tier fertility networks that previously outsourced testing.
Growth Catalysts
- CMS NIPT Reimbursement Expansion:Medicare coverage determinations for non-invasive prenatal testing in average-risk pregnancies are unlocking patient access across United States fertility clinics and obstetric practices previously constrained by out-of-pocket cost barriers.
- Digital PCR Platform Diffusion:Laboratories in China and Germany are deploying droplet digital PCR systems for targeted aneuploidy screening, reducing capital requirements versus comprehensive next-generation sequencing while maintaining clinical sensitivity.
- Maternal Serum Screening Integration:First-trimester combined screening protocols are embedding genetic risk stratification into standard prenatal workflows, creating downstream demand for confirmatory diagnostic testing.
Market Restraints
- Reagent Supply Concentration:Sequencing consumables for cell-free DNA analysis depend on a limited vendor base concentrated in California and Massachusetts, exposing laboratories to allocation risk during demand surges.
- EMA Post-Market Surveillance Burden:Europe's In Vitro Diagnostic Regulation imposes ongoing performance monitoring obligations that extend compliance timelines and elevate documentation costs for NIPT manufacturers.
- Invasive Procedure Substitution Limits:Amniocentesis and chorionic villus sampling retain diagnostic authority for mosaicism detection and single-gene disorder confirmation, constraining complete displacement by non-invasive methods.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Sickle cell disease carrier screening programs in Nigeria and Ghana present entry points for expanded NIPT panels targeting hemoglobinopathies with high regional prevalence.
- Microdeletion Panel Expansion:22q11.2 deletion syndrome detection represents an emerging reimbursable indication beyond common aneuploidies, with United States commercial payers gradually extending coverage.
- At-Home Sample Collection:Direct-to-consumer blood draw networks are bypassing traditional clinic-based phlebotomy, compressing patient friction and capturing gestational-age-sensitive windows.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant interpretation pipelines require computational biologists trained in both obstetric clinical context and statistical false-positive management, a hybrid skill set concentrated at academic centers.
- Multicenter Validation Complexity:Analytical validation studies spanning diverse gestational ages and maternal body mass index strata demand coordinated specimen collection across three or more clinical sites, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal Genetic Testing Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $19 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Non-Invasive Prenatal Testing, Chorionic Villus Sampling, Amniocentesis, Maternal Serum Screening, Ultrasound Screening Technology: Next-Generation Sequencing, Microarray, Polymerase Chain Reaction, Fluorescence In Situ Hybridization, Digital PCR Indication: Chromosomal Abnormalities, Single Gene Disorders, Neural Tube Defects, Sex Chromosome Aneuploidies, Multifactorial Disorders End User: Genetic Counseling Centers, Diagnostic Laboratories, Fertility Clinics, Specialty Hospitals, Academic Research Institutions |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., Natera Inc., Laboratory Corporation of America Holdings, F. Hoffmann-La Roche Ltd, Eurofins Scientific, BGI Genomics, Myriad Genetics Inc., QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal Genetic Testing Market Strategic Shifts & Innovations
Workflow automation and algorithmic variant classification are converging to reduce human interpretation burden, while regulatory frameworks on both sides of the Atlantic are tightening evidence requirements for expanded screening claims.
Library preparation chemistry is modularizing into pre-validated, automation-compatible cartridge formats. Mid-volume hospital laboratories in Texas and Bavaria are adopting these plug-and-play consumables to eliminate protocol development overhead. This standardization is compressing technical training requirements and enabling same-day sample-to-sequence turnaround that previously required overnight batching.
REACH-compliant reagent documentation is mandating granular substance-level disclosure for European IVD manufacturers. Supply chain audits now trace oligonucleotide synthesis inputs through contract research organizations to original nucleotide suppliers. Germany-based NIPT developers are responding by qualifying alternative synthesis partners in Switzerland to maintain CE marking continuity.
Fertility clinic procurement directors are consolidating vendor relationships through exclusive testing agreements that bundle NIPT with carrier screening and preimplantation genetic testing. United States multi-site reproductive medicine groups are displacing à-la-carte laboratory selection with single-source contracts that capture volume discounts and standardized reporting formats. This concentration is most visible in Florida and California, where private equity-backed clinic rollups command sufficient case volume to negotiate preferred pricing tiers.
Prenatal Genetic Testing Market Segmentation
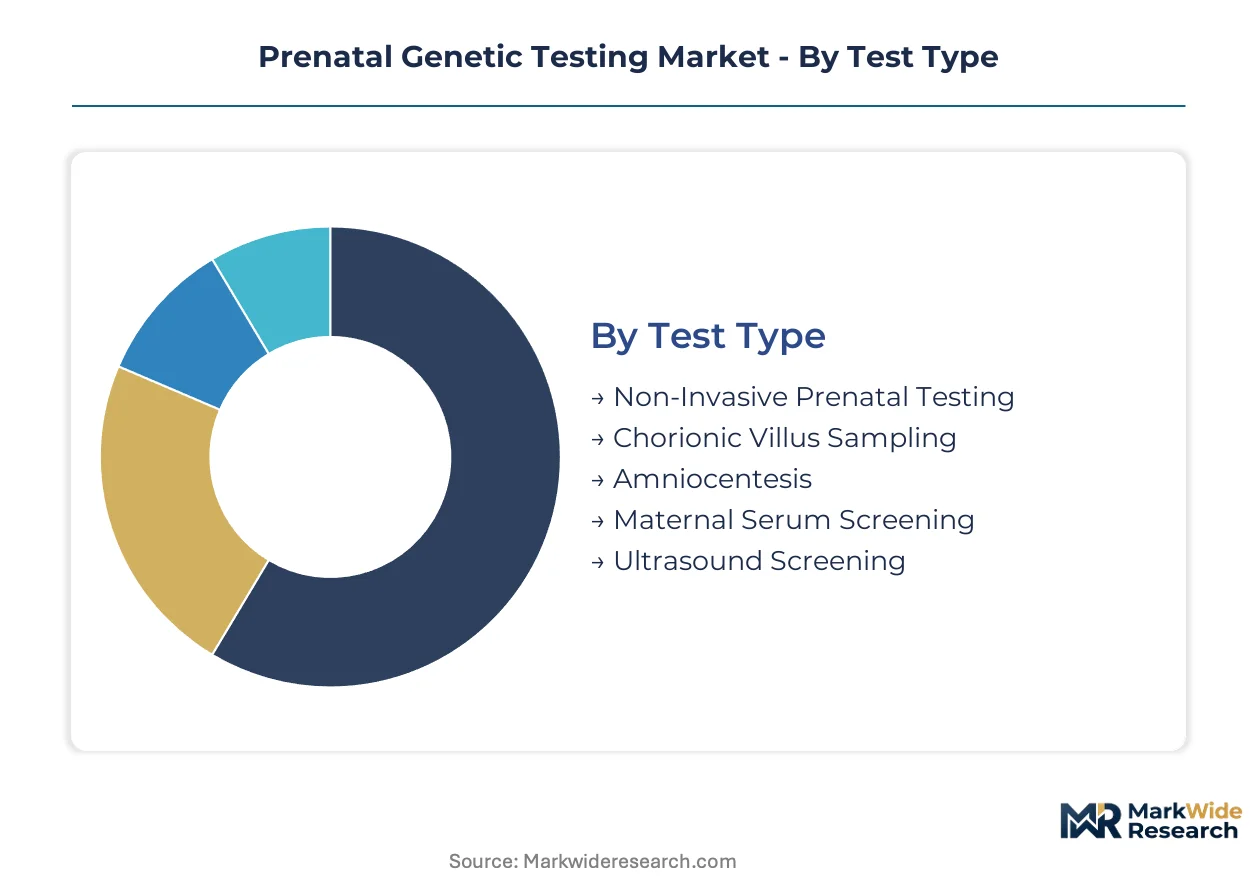
Prenatal genetic testing segments diverge sharply in regulatory burden and capital intensity. Test type determines FDA pathway complexity, while technology choice shapes laboratory infrastructure requirements and reimbursement eligibility.
Test Type:
FDA 510(k) clearance and CMS coverage determinations cluster heavily on safety profiles, with invasive procedures facing stricter adverse event reporting mandates than screening modalities.
- Non-Invasive Prenatal Testing:Cell-free fetal DNA analysis from maternal plasma eliminates miscarriage risk associated with invasive sampling. Demand concentrates in United States fertility networks and Chinese municipal hospitals where CMS and provincial reimbursement policies now cover average-risk pregnancies. Superior safety profiles and expanding gestational-age windows are displacing first-trimester serum screening.
- Amniocentesis:Second-trimester amniotic fluid aspiration with karyotyping retains diagnostic authority for mosaicism detection and single-gene confirmation. Specialty hospitals in Germany and academic centers in Massachusetts maintain procedure volume for complex cases where NIPT returns indeterminate results. Invasive procedure substitution limits constrain complete displacement by non-invasive methods.
- Chorionic Villus Sampling:First-trimester placental tissue biopsy enables earlier diagnostic timelines than amniocentesis.
- Maternal Serum Screening:Biochemical marker analysis from maternal blood samples serves as a risk stratification entry point.
- Ultrasound Screening:Structural anomaly detection via sonography operates without molecular diagnostic regulatory pathways.
Leading the category by volume: Non-Invasive Prenatal Testing. Growing fastest: Non-Invasive Prenatal Testing.
Technology:
Capital requirements and reagent economics stratify adoption, with comprehensive sequencing platforms demanding seven-figure instrument investments versus sub-six-figure digital PCR deployments.
- Digital PCR:Droplet-based absolute quantification of fetal DNA fractions delivers targeted aneuploidy detection at reduced capital burden. Laboratories in China and Germany are deploying these systems to bypass comprehensive sequencing infrastructure costs while maintaining clinical sensitivity for common trisomies. Lower reagent consumption and simplified bioinformatics are accelerating mid-tier fertility network adoption.
- Next-Generation Sequencing:Massively parallel sequencing of cell-free DNA enables genome-wide aneuploidy and microdeletion detection. Diagnostic laboratories in California and Massachusetts dominate installed base concentration, leveraging reagent pull-through economics and high-throughput operational scale. Library preparation automation is compressing per-test costs below reimbursement thresholds.
- Polymerase Chain Reaction:Targeted amplification of specific loci serves confirmatory testing applications.
- Microarray:Comparative genomic hybridization enables submicroscopic copy number variant detection.
- Fluorescence In Situ Hybridization:Chromosomal probe hybridization retains niche utility for rapid aneuploidy confirmation.
Next-Generation Sequencing commands the largest revenue pool. Digital PCR exhibits the steepest expansion trajectory among mid-volume laboratories.
Indication:
Reimbursement authorization and clinical utility evidence requirements vary by condition prevalence and therapeutic intervention availability.
- Chromosomal Abnormalities:Trisomy 21, 18, and 13 detection constitutes the foundational NIPT indication with established payer coverage. United States commercial insurers and CMS have standardized reimbursement for this indication, creating predictable revenue streams for diagnostic laboratories. Screening protocol integration into first-trimester workflows sustains volume concentration.
- Single Gene Disorders:Cystic fibrosis, sickle cell disease, and spinal muscular atrophy carrier screening require distinct analytical validation frameworks. Academic research institutions in Massachusetts and specialty hospitals in Germany are driving panel expansion, though reimbursement remains fragmented across United States state Medicaid programs. Microdeletion panel expansion for 22q11.2 deletion syndrome represents an emerging reimbursable indication.
- Neural Tube Defects:Open spina bifida and anencephaly detection relies on maternal serum alpha-fetoprotein measurement.
- Sex Chromosome Aneuploidies:Turner syndrome and Klinefelter syndrome screening faces variable payer coverage policies.
- Multifactorial Disorders:Polygenic risk scoring for conditions like congenital heart disease remains investigational.
Chromosomal Abnormalities screening generates the highest procedure volume. Single Gene Disorders panels are climbing the fastest as expanded carrier screening penetrates fertility clinics.
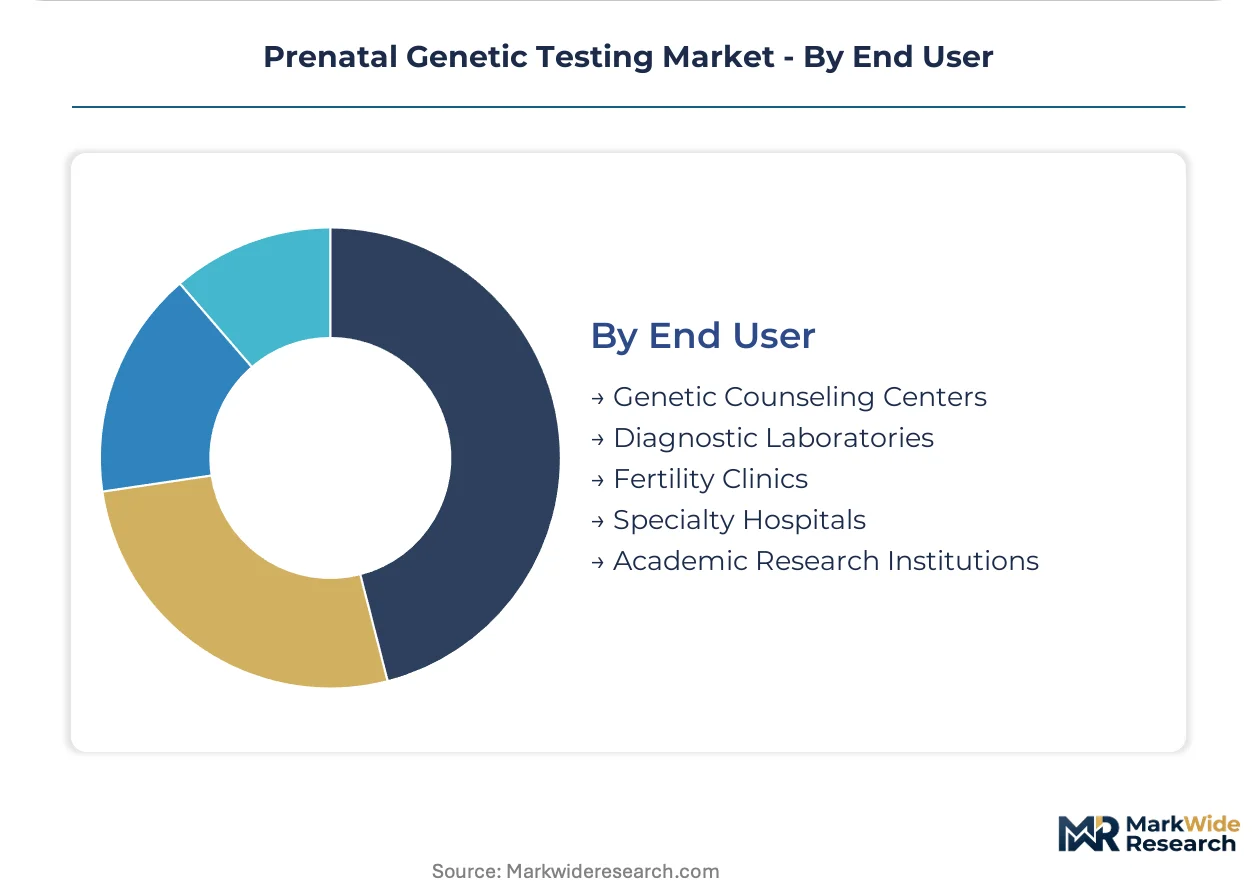
End User:
Procurement sophistication and test menu breadth requirements segment the customer base across institutional capabilities.
- Diagnostic Laboratories:High-throughput facilities with CAP/CLIA certification and dedicated molecular genetics divisions capture the largest margin pool. Fertility clinic procurement directors are consolidating vendor relationships through exclusive testing agreements that bundle NIPT with carrier screening. Capital-intensive infrastructure and automated workflow integration defend position against mid-tier entrants.
- Fertility Clinics:Reproductive medicine practices prioritize rapid turnaround and integrated genetic counseling workflows. United States multi-site groups in Florida and California are displacing à-la-carte laboratory selection with single-source contracts. Direct-to-consumer blood draw networks are bypassing traditional clinic-based phlebotomy to compress patient friction.
- Genetic Counseling Centers:Patient education and risk communication facilities without in-house testing infrastructure.
- Specialty Hospitals:Maternal-fetal medicine units with invasive procedure capabilities.
- Academic Research Institutions:Validation studies and expanded indication development sites.
Diagnostic Laboratories lead by revenue concentration. Fertility Clinics are gaining share fastest through vertical integration of genetic services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology special economic zones in California, Massachusetts, and Jiangsu Province concentrate sequencing infrastructure and reagent manufacturing, attracting laboratory networks and fertility clinic chains through tax abatements and expedited regulatory pathways.
United States
Fertility clinic rollups in Florida and California are consolidating vendor relationships through exclusive NIPT contracts. CMS reimbursement expansion for average-risk pregnancies under 2024 coverage determinations is unlocking access across mid-tier obstetric practices. The San Francisco Bay Area anchors reagent manufacturing concentration, with sequencing consumables flowing to diagnostic laboratories nationwide.
China
Municipal hospitals in Beijing and Shanghai are deploying droplet digital PCR systems for targeted aneuploidy screening at reduced capital burden. NMPA regulatory harmonization with international IVD standards is compressing product registration timelines for domestic manufacturers. The Suzhou Industrial Park clusters sequencing instrument assembly and oligonucleotide synthesis capacity serving Asia-Pacific laboratory networks.
Germany
Specialty hospitals in Bavaria and North Rhine-Westphalia maintain invasive procedure volume for mosaicism detection where NIPT returns indeterminate results. EMA's In Vitro Diagnostic Regulation imposes REACH-compliant reagent documentation mandates that extend compliance timelines. The Munich biotech corridor hosts bioinformatics development centers refining variant interpretation pipelines for European market requirements.
United Kingdom
NHS England's genomic medicine service is integrating cell-free DNA screening into standardized prenatal care pathways. MHRA post-Brexit regulatory autonomy is diverging from EMA timelines on expanded NIPT indication approvals. The Cambridge-London corridor concentrates academic research institutions driving multicenter validation studies for microdeletion panel expansion.
Switzerland
Precision medicine hubs in Basel and Zurich are qualifying alternative oligonucleotide synthesis partners to maintain CE marking continuity under REACH substance disclosure mandates. Swissmedic's streamlined IVD authorization processes are attracting manufacturers seeking faster European market entry than EMA centralized pathways permit. The country's diagnostic laboratory networks serve as reference sites for alpine region fertility clinics.
Prenatal Genetic Testing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with sequencing platform providers capturing reagent pull-through economics while independent laboratories compete on turnaround time and genetic counseling integration. The vendor base concentrates around three strategic archetypes: integrated life science conglomerates with instrument-installed bases, pure-play NIPT developers with proprietary bioinformatics, and diversified diagnostic service networks with captive patient volume. Consolidation is accelerating through fertility clinic chain acquisitions and exclusive testing agreements that bundle screening menus.
Within the sequencing infrastructure tier, Illumina Inc. and Thermo Fisher Scientific Inc. anchor the reagent and instrument supply layer that downstream laboratories depend upon. Natera Inc. exemplifies the specialized bioinformatics archetype, occupying a position differentiated from commodity sequencing services through proprietary analytical pipelines. These three entities collectively represent the vertical span from sample processing hardware to clinical report generation that defines competitive positioning in cell-free DNA-based screening.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| Natera Inc. |
| Laboratory Corporation of America Holdings |
| F. Hoffmann-La Roche Ltd |
| Eurofins Scientific |
| BGI Genomics |
| Myriad Genetics Inc. |
| QIAGEN N.V. |
| Others |
Cost & Logistics Intelligence
Fertility clinic procurement directors in Florida and California command pricing leverage through exclusive testing agreements that bundle NIPT with carrier screening, compressing margins for standalone laboratory vendors. This buyer concentration enforces three-tier pricing stratification across premium, standard, and economy service levels differentiated by turnaround time and genetic counseling integration.
Pricing Analysis
Short lead-time premiums apply to same-day sample processing contracts with fertility networks, while extended batch-scheduled workflows attract spot-rate discounts. Pricing stratifies across premium, standard, and economy tiers based on bioinformatics depth and reporting speed. Cost compression in the economy tier is intensifying because digital PCR platforms reduce reagent overhead. Mid-tier fertility clinics exhibit highest price sensitivity; academic medical centers with captive volume show lowest.
Supply Chain Analysis
Reverse-logistics flows for expired reagent cartridges and instrument refurbishment cycles concentrate servicing capacity in California and Massachusetts. Oligonucleotide synthesis draws from contract research organizations in Switzerland and original nucleotide suppliers in Germany. Single-source vulnerability persists for sequencing consumables anchored in the San Francisco Bay Area. Distribution runs through diagnostic laboratory networks with CAP/CLIA certification serving fertility clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from CMS reimbursement standardization is forcing sub-scale bioinformatics developers toward acquisition or exit, rewarding integrated platform providers with captive instrument installed bases.
For Market Incumbents: Hedge against digital PCR substitution by qualifying alternative synthesis partners in Switzerland to maintain CE marking continuity under REACH mandates. Deepen reagent pull-through economics through library preparation automation that compresses per-test costs below reimbursement thresholds. Anchor position against mid-tier fertility network entrants by bundling NIPT with preimplantation genetic testing under exclusive contracts. For New Entrants and Emerging Players: The premium-economy price-point gap in microdeletion panel expansion creates white-space entry at mid-tier fertility clinics previously excluded by comprehensive sequencing infrastructure costs. Target droplet digital PCR deployment in Chinese municipal hospitals and German Bavarian networks where capital constraints favor targeted aneuploidy screening. Penetrate through at-home sample collection networks that bypass traditional clinic-based phlebotomy friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play NIPT developers with proprietary bioinformatics pipelines but sub-scale commercial operations in Massachusetts and California. Five-to-ten-year viability hinges on expanded indication reimbursement beyond common aneuploidies. Monitor CMS coverage determinations for 22q11.2 deletion syndrome as inflection signal for microdeletion panel market formation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA's In Vitro Diagnostic Regulation imposes REACH-compliant documentation extending compliance timelines for European market entry. |
| Reimbursement Strategy | CMS coverage expansion for average-risk pregnancies unlocks patient access across United States mid-tier obstetric practices. |
| Hospital System Partnership | Exclusive testing agreements with fertility clinic rollups in Florida capture volume discounts and standardized reporting formats. |
| Software Companion Development | Algorithmic variant classification reduces human interpretation burden and accelerates same-day sample-to-sequence turnaround. |
| Backward Integration | Qualifying alternative oligonucleotide synthesis partners in Switzerland maintains CE marking continuity under substance disclosure mandates. |
Research Approach
Multi-period observation of CMS reimbursement determinations, NMPA registration timelines, and EMA post-market surveillance obligations anchored the trend analysis, supplemented by interviews with laboratory operations directors, fertility clinic procurement managers, genetic counselors, and bioinformatics pipeline developers. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, CMS Medicare coverage databases, and CAP/CLIA certification records. Bottom-up test volume modeling and top-down market sizing triangulated revenue estimates across the analysis window.
Input-output matrices mapped cell-free DNA sequencing economics, digital PCR platform diffusion rates, and maternal serum screening integration patterns across test type, technology, indication, and end-user segments. CAGRs were derived from regression analysis of historical procedure volumes and reimbursement trajectory assumptions. Forecast inputs incorporated fertility clinic rollup activity in Florida and California, NMPA regulatory harmonization progress in China, and EMA compliance cost escalation in Germany.
Inputs from CMS coverage determinations and NMPA product registrations were available through the study window; gaps in real-time EMA post-market surveillance cost data introduce uncertainty bands around European market entry timelines. Practitioners should monitor expanded NIPT indication reimbursement decisions and digital PCR platform adoption curves in China for early signals of technology substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Testing Service Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
APO E Gene Test Kit Market
Genomics
Alagille Syndrome Market
Genomics
Antisense Oligonucleotides Market
Genomics
Genomics and Transcriptomics Market
Genomics
North America Whole Exome Sequencing Market
Genomics
SNP Genotyping Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
DNA Sequencing Market
Genomics
Europe Epigenetics Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Genetic Testing Panels Market
Genomics
North America Microarray Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Molecular Biomarkers for Cancer Detection Market