
 Monoclonal Antibody Custom Service Market | 2026-2036
Monoclonal Antibody Custom Service Market Size, Share, and Industry Trends Forecast 2026-2036
Monoclonal Antibody Custom Service Market Outlook
The monoclonal antibody custom service sector is pivoting on a widening split between premium, GMP-compliant therapeutic-grade production and commodity research-grade antibody supply. Thermo Fisher Scientific Inc. leverages its integrated instrument-to-service platform to dominate high-value therapeutic workflows. GenScript anchors its competitive position through specialized clone development capabilities in Asia-Pacific markets. Abnova Corporation differentiates via extensive recombinant protein libraries that accelerate client discovery timelines.
Monoclonal antibody custom services encompass contract-based design, expression, purification, and validation of antigen-specific immunoglobulins produced through hybridoma or recombinant technologies, typically requiring 8–16 weeks from immunization to clone selection depending on complexity and species source. Pharmaceutical companies and biotech firms represent the dominant end-user category, with therapeutic use applications commanding premium pricing due to stringent quality and documentation requirements. Clone development and protein production services lead current revenue pools, while assay development segments exhibit faster expansion as companion diagnostic demands intensify alongside therapeutic pipelines.
FDA, EMA, and ISO 13485 frameworks collectively govern monoclonal antibody service validation, with FDA's evolving biosimilar guidance and EMA's MDR-aligned quality standards directly shaping client qualification criteria and facility audit frequency. China's NMPA has accelerated local Good Manufacturing Practice harmonization, altering offshore delivery mode competitiveness for Western clients. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where compliance investments will reshape contract manufacturing organization selection criteria.
Market Dynamics
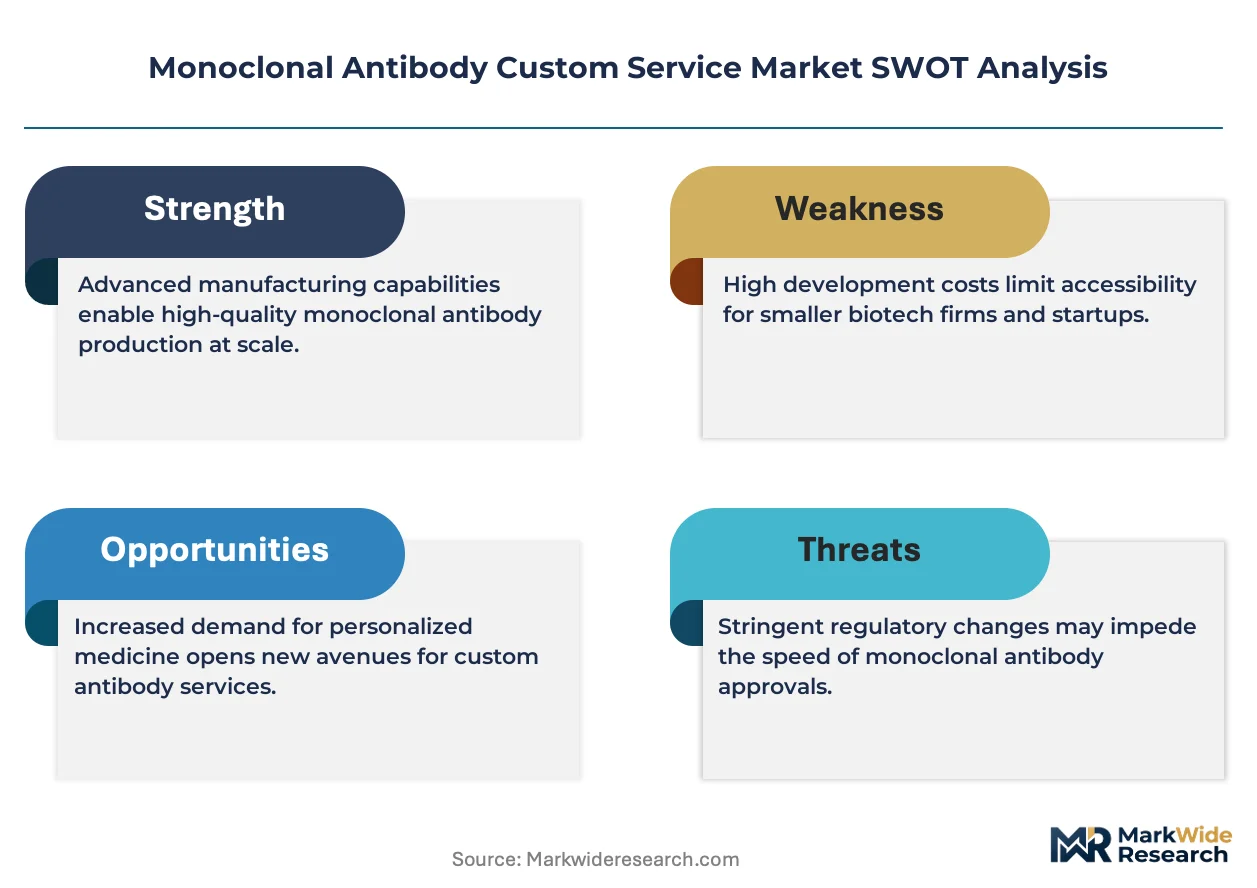
Precision medicine pipelines are fragmenting antibody demand into smaller-batch, higher-complexity production runs that strain legacy manufacturing footprints and reward flexible bioreactor configurations.
Growth Catalysts
- Companion diagnostic mandates:FDA's expanding guidance on co-developed therapeutics and diagnostics pushes sponsors to secure integrated antibody supply chains for simultaneous approval pathways.
- China NMPA GMP harmonization:Accelerated alignment with international manufacturing standards enables domestic Chinese CMOs to capture Western biopharma outsourcing previously directed to North American facilities.
- Single-use bioreactor adoption:Disposable manufacturing technologies reduce cross-contamination risk and facility turnaround time for multi-product antibody campaigns.
Market Restraints
- Fetal bovine serum price volatility:Hybridoma production remains dependent on serum inputs subject to supply disruptions from bovine disease outbreaks and export restrictions.
- Plasmid DNA supply concentration:Transient expression systems rely on plasmid manufacturing concentrated among a limited set of specialized suppliers, creating bottleneck risk for recombinant antibody campaigns.
- EMA MDR documentation burden:Medical Device Regulation-aligned quality standards for diagnostic-grade antibodies extend validation timelines and inflate compliance costs for European-market service providers.
Strategic Opportunities
- Cell and gene therapy convergence:Viral vector manufacturing expertise overlaps with antibody production capabilities, enabling CMOs to capture adjacent biologics workflows from the same sponsor relationships.
- ISO 13485 certification gaps in Southeast Asia:Malaysia and Singapore host underdeveloped diagnostic-grade antibody manufacturing capacity relative to their clinical trial growth, creating first-mover positioning for certified entrants.
- AI-guided epitope prediction:Machine learning platforms for immunogen design compress discovery timelines and reduce immunization failures, differentiating service providers who integrate computational biology with wet-lab validation.
Industry Challenges
- Cell line development specialist scarcity:Experienced molecular biologists capable of stable CHO and HEK293 engineering command premium compensation and constrain facility expansion timelines.
- Multi-attribute method validation:FDA's advancing expectations for comprehensive product characterization create analytical development bottlenecks that delay IND-enabling packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoclonal Antibody Custom Service Market |
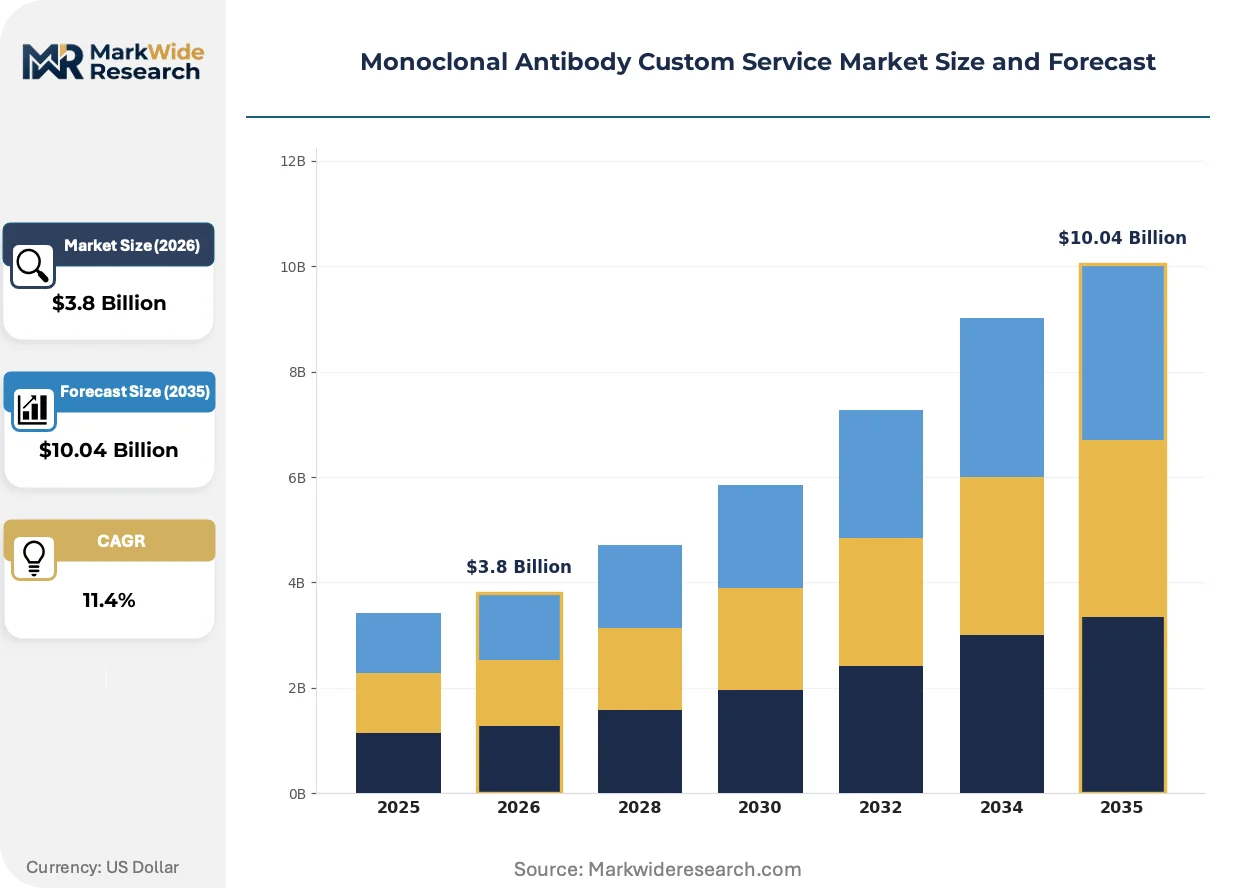
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clone Development, Protein Production, Assay Development, Characterization End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Academic Entities Application: Therapeutic Use, Diagnostic Development, Research Studies, Drug Discovery Delivery Mode: Onshore Services, Offshore Services, Hybrid Services, Consultancy |
| Companies Covered | Thermo Fisher Scientific Inc., GenScript, Bio-Rad Laboratories, Inc., Abnova Corporation, ProteoGenix, Sino Biological Inc., Bio-Techne, Creative Diagnostics, Abcam plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoclonal Antibody Custom Service Market Strategic Shifts
Workflow automation and modular facility design are compressing the traditional 16-week antibody production cycle while fragmenting demand into project-based engagements rather than long-term supply agreements.
Single-use perfusion bioreactor systems are expanding into fed-batch dominated therapeutic antibody manufacturing. Mid-sized biotech sponsors now specify perfusion for Phase II campaigns requiring rapid scale-up flexibility. This technology is expanding into clinical-stage production by enabling 5-10x cell density improvements without stainless-steel infrastructure commitments.
EMA's evolving biosimilar immunogenicity guidance is tightening analytical comparability requirements for reference antibody characterization. Contract laboratories must now demonstrate extended sub-visible particle monitoring and forced degradation studies beyond originator filing standards. European CMOs are responding by consolidating analytical development and QC functions under unified data integrity frameworks.
Biopharma procurement teams are unbundling discovery-grade antibody supply from downstream GMP manufacturing, creating separate vendor relationships for research use versus IND-enabling material. This bifurcation pressures integrated service providers to defend margin on commodity clone development while capturing premium on regulatory-compliant production. The United States exhibits the most pronounced vendor fragmentation, with sponsors maintaining 3-4 active antibody service relationships across development stages.
Monoclonal Antibody Custom Service Market Segmentation
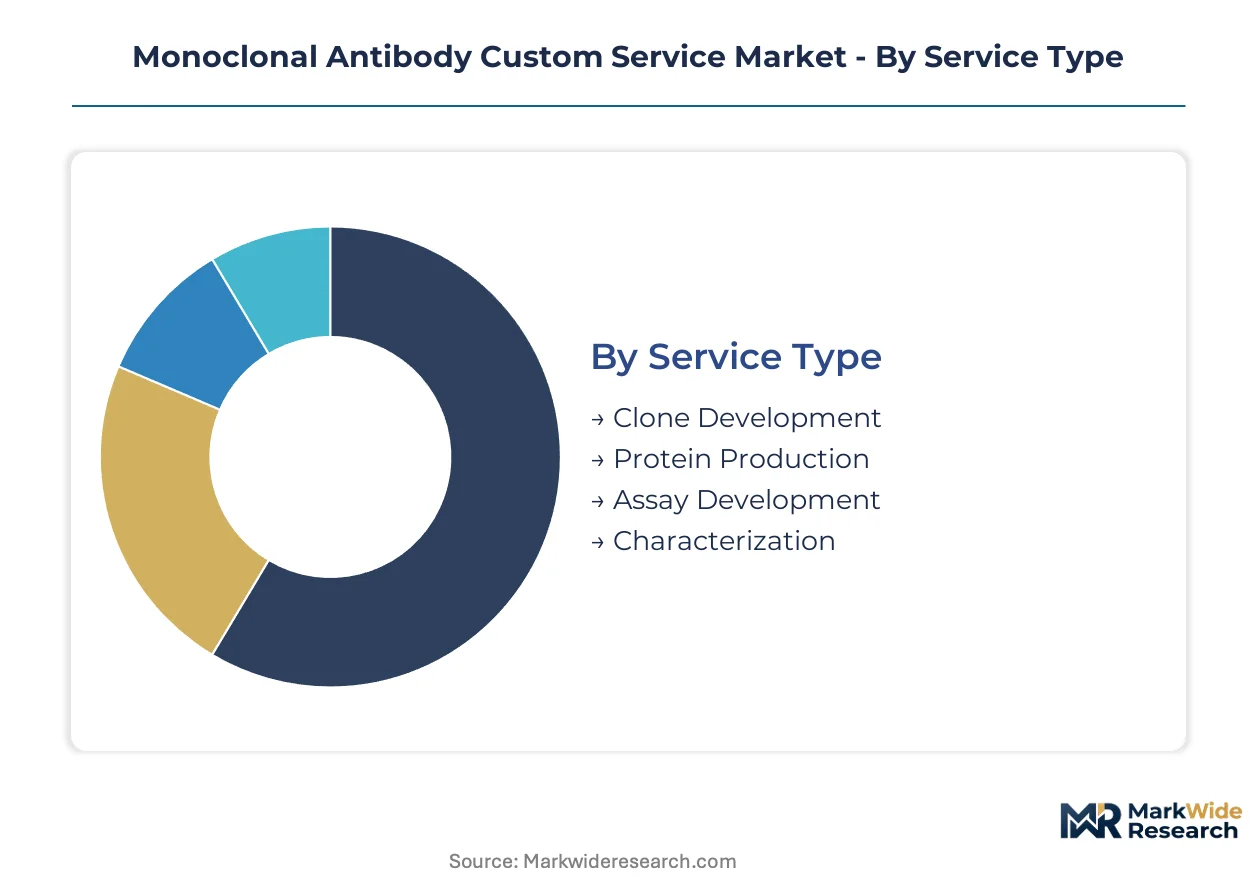
Monoclonal antibody custom services fragment across four critical dimensions that reshape vendor selection criteria. Service type determines technical capability requirements, while end-user category dictates compliance intensity and pricing tolerance.
Service Type:
Buyers prioritize technical depth and timeline predictability when selecting service tiers.
- Clone Development:Hybridoma and recombinant antibody generation through immunization, fusion, and screening protocols. Pharmaceutical sponsors in the United States commission clone development most intensively for IND-enabling campaigns where clonality documentation faces FDA scrutiny.
- Protein Production:Transient and stable expression systems yielding milligram-to-gram quantities in CHO, HEK293, or microbial hosts. Biotech firms concentrate demand in Germany and Massachusetts where GMP-adjacent infrastructure supports rapid scale-up for Phase I material.
- Assay Development:Binding kinetics, specificity confirmation, and functional validation workflows.
- Characterization:Structural analysis, glycan profiling, and stability assessment for regulatory filings.
Protein production leads on scale; assay development leads on momentum.
End User:
Customer type governs procurement sophistication and contract structure preferences.
- Pharmaceutical Companies:Large sponsors demand integrated service portfolios spanning discovery through GMP manufacturing with unified quality systems and audit-ready documentation. These buyers concentrate spending in the United States and Switzerland where proximity to regulatory expertise reduces submission risk.
- Biotech Firms:Mid-cap developers favor modular engagements with milestone-based payments and rapid turnaround for competitive financing timelines. Chinese biotechs increasingly source from domestic CMOs following NMPA GMP harmonization.
- Research Institutions:Non-profit and government laboratories purchasing research-grade antibodies with flexible specifications.
- Academic Entities:University groups prioritizing cost efficiency and publication-grade validation over regulatory documentation.
Pharmaceutical companies anchor revenue concentration; biotech firms drive expansion velocity.
Application:
End-use purpose determines certification requirements and pricing stratification.
- Therapeutic Use:GMP-compliant antibody production for clinical administration with extensive viral safety testing, endotoxin control, and batch release protocols. FDA and EMA filings command premium pricing due to validation burden and liability exposure.
- Diagnostic Development:IVD-grade antibodies requiring ISO 13485 certification and lot-to-lot consistency for companion diagnostic co-development. EMA MDR alignment has tightened European requirements beyond prior CE-marking standards.
- Research Studies:Non-GMP material for preclinical mechanistic work and tool antibody generation.
- Drug Discovery:High-throughput screening reagents and target validation antibodies with accelerated turnaround.
Therapeutic use commands margin dominance; diagnostic development exhibits the steepest expansion trajectory.
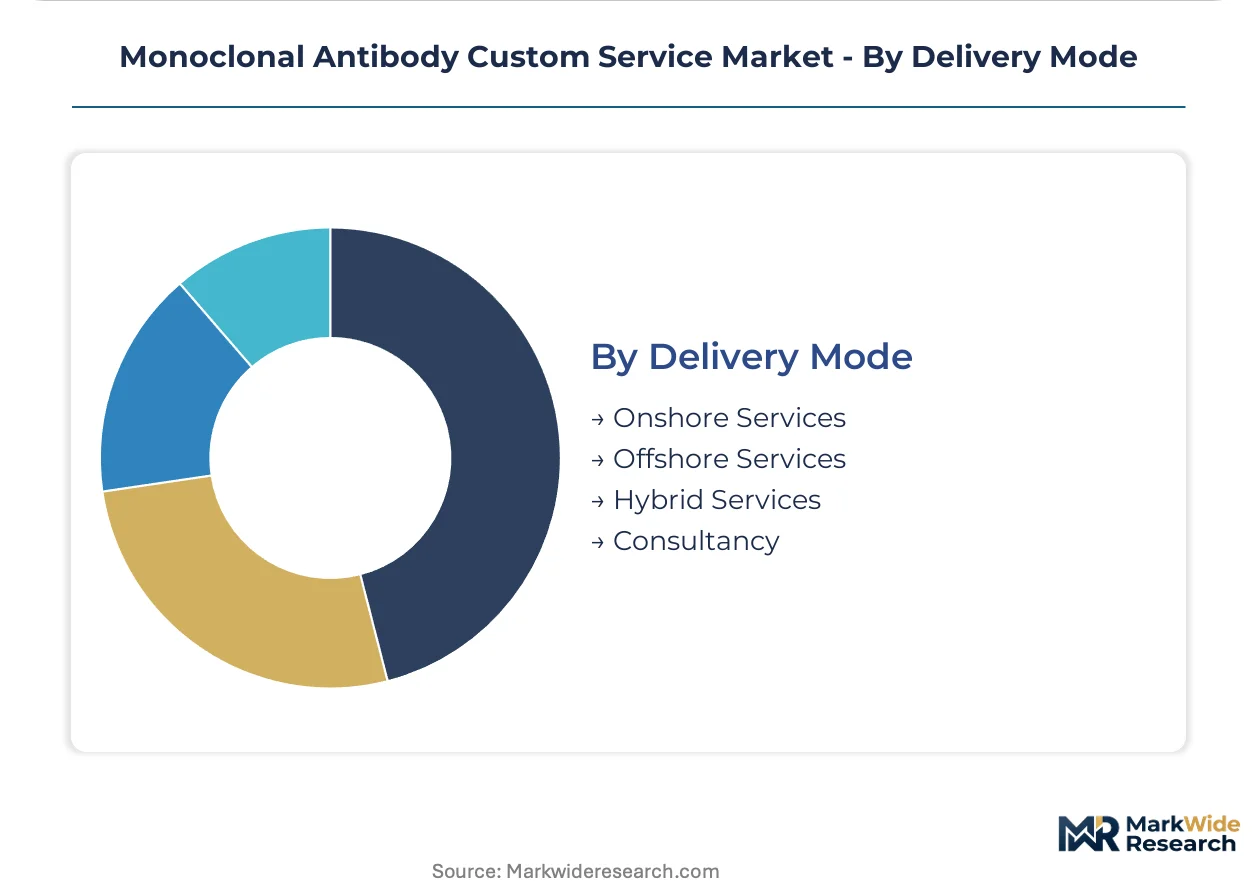
Delivery Mode:
Geographic sourcing strategy reflects risk tolerance and regulatory proximity needs.
- Onshore Services:Domestic manufacturing eliminating cross-border logistics and enabling rapid sponsor oversight. United States-based sponsors maintain onshore relationships for IND-critical material where FDA pre-approval inspection access matters.
- Offshore Services:International outsourcing capturing cost advantages and specialized capabilities, particularly in China where NMPA-certified facilities now compete for Western biopharma contracts.
- Hybrid Services:Split workflows with discovery offshore and GMP manufacturing onshore to balance cost and compliance.
- Consultancy:Advisory engagements for regulatory strategy, vendor qualification, and technology transfer planning.
Onshore services retain preference for therapeutic-grade campaigns; hybrid models gain share fastest among cost-constrained mid-cap sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level molecular biologists and cell line engineers concentrate in three distinct geographic clusters that anchor monoclonal antibody service capacity. The United States, Germany, and China host the densest talent pools, with each jurisdiction developing specialized regulatory frameworks that reshape outsourcing decisions.
United States
FDA's biosimilar guidance and IND scrutiny drive pharmaceutical sponsors toward domestic CMO relationships for critical-path material. The Greater Boston and San Francisco Bay Area biotech corridors sustain the highest density of hybridoma specialists and transient expression facilities. Massachusetts-based sponsors increasingly split workflows between discovery-grade offshore supply and GMP onshore manufacturing to balance speed with compliance.
Germany
EMA's MDR-aligned quality standards and evolving immunogenicity guidance tighten documentation requirements for diagnostic-grade antibody production. The Munich and Heidelberg biotech clusters concentrate HEK293 and CHO stable line development expertise. Bavarian facilities are consolidating analytical development and QC functions under unified data integrity frameworks to meet heightened European regulatory expectations.
China
NMPA's accelerated GMP harmonization with international standards enables domestic CMOs to capture Western biopharma contracts previously directed to North American facilities. The Yangtze River Delta and Beijing-Tianjin-Hebei corridors anchor recombinant protein production scale. Shanghai-based service providers are expanding perfusion bioreactor capacity to meet mid-cap biotech demand for rapid Phase II scale-up flexibility.
Switzerland
Swissmedic's alignment with FDA and EMA standards positions Basel and Zurich facilities as premium-tier destinations for integrated discovery-to-GMP workflows. The country's concentrated pharmaceutical R&D ecosystem sustains specialized clone development capabilities for therapeutic antibody programs. Swiss CMOs are capturing sponsor relationships seeking unified quality systems across preclinical and clinical material supply.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's post-Brexit divergence from EMA procedures creates qualification complexity for pan-European sponsors. The Cambridge and Oxford biotech clusters maintain strong hybridoma and recombinant antibody engineering talent. UK-based service providers are navigating regulatory uncertainty by securing dual FDA-EMA audit readiness for export-oriented production.
Monoclonal Antibody Custom Service Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the monoclonal antibody custom service sector. Integrated instrument-to-service platforms dominate high-value therapeutic workflows, while specialized clone development shops capture discovery-stage engagements. Three archetypes define competitive positioning: diversified life science conglomerates with end-to-end platforms, regional specialists with deep technical capabilities in specific expression systems, and recombinant protein library operators accelerating client discovery timelines. Capacity expansion and AI-guided epitope prediction integration represent the dominant competitive moves reshaping vendor differentiation.
Among diversified life science platforms, Thermo Fisher Scientific Inc. anchors the integrated instrument-to-service tier, while GenScript occupies a specialized position in Asia-Pacific clone development. Abnova Corporation exemplifies the recombinant protein library archetype. These three entities represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| GenScript |
| Bio-Rad Laboratories, Inc. |
| Abnova Corporation |
| ProteoGenix |
| Sino Biological Inc. |
| Bio-Techne |
| Creative Diagnostics |
| Abcam plc |
| Others |
Value Chain & Pricing Dynamics
FDA's companion diagnostic mandates are forcing pharmaceutical sponsors to unbundle discovery-grade antibody supply from GMP manufacturing, compelling contract manufacturers to reconfigure service tiers and compress margins on commodity clone development while defending premium pricing on regulatory-compliant production.
Pricing Analysis
The bundled-versus-unbundled service split now defines pricing architecture across the monoclonal antibody custom service sector. Project-based transactional pricing dominates, with three-tier pricing structure across premium, standard, and economy levels: therapeutic-grade GMP production commands top-tier rates due to FDA and EMA validation burdens, diagnostic-grade ISO 13485-certified supply occupies mid-tier positioning, and research-grade material competes on cost. Cost compression in research-grade segments is intensifying because biotech procurement teams now maintain multiple vendor relationships and pit specialized clone developers against one another. Academic entities and early-stage biotech firms exhibit highest price sensitivity, while large pharmaceutical companies prioritize unified quality systems and audit-ready documentation over unit cost.
Supply Chain Analysis
Reverse-logistics flows remain minimal in monoclonal antibody services given biological material stability constraints, though failed clone batches trigger rapid remake protocols that strain transient expression capacity. Supply concentrates in the United States, China, and Germany where clustered biotech hubs sustain dense outsourcing ecosystems. Production draws from fetal bovine serum inputs subject to bovine disease outbreak disruptions, plasmid DNA manufacturing concentrated among limited specialized suppliers, and single-use bioreactor consumables. Single-source vulnerability in plasmid supply creates bottleneck risk for recombinant antibody campaigns. Distribution runs through direct sponsor-CMO relationships with minimal intermediary involvement, though hybrid models now split discovery offshore and GMP manufacturing onshore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The monoclonal antibody custom service market functions as a stable compounder, with precision medicine pipelines fragmenting antibody demand into smaller-batch, higher-complexity production runs that sustain pricing power for flexible manufacturers.
For Market Incumbents: Acquire AI-guided epitope prediction platforms to compress client discovery timelines and differentiate from commodity clone shops. Cell line development specialist scarcity threatens facility expansion timelines; secure talent through acquisition of boutique CHO and HEK293 engineering teams in Greater Boston and San Francisco Bay Area corridors. Pursue backward integration into plasmid DNA manufacturing to eliminate supply bottlenecks and capture margin from recombinant antibody workflows. For New Entrants and Emerging Players: Enter via ISO 13485 certification gaps in Southeast Asia, where Malaysia and Singapore host underdeveloped diagnostic-grade antibody manufacturing capacity relative to clinical trial growth. Target assay development segments exhibiting fastest expansion as companion diagnostic demands intensify alongside therapeutic pipelines. Position as rapid-turnaround specialists for mid-cap biotech sponsors in China following NMPA GMP harmonization, leveraging domestic cost advantages for Western biotech contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing deep technical capabilities in perfusion bioreactor systems and stable cell line engineering. Long-term viability hinges on convergence with cell and gene therapy manufacturing workflows where viral vector expertise overlaps antibody production capabilities. Monitor NMPA audit readiness certifications among Chinese CMOs as inflection indicator for offshore competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Guided Epitope Prediction Integration | Machine learning platforms compress immunization timelines and reduce clone failure rates for sponsors. |
| Perfusion Bioreactor Capacity Expansion | Disposable systems enable 5-10x cell density improvements without stainless-steel infrastructure commitments. |
| ISO 13485 Certification Investment | Diagnostic-grade antibody production meets tightened EMA MDR-aligned quality standards for IVD supply. |
| Plasmid DNA Manufacturing Backward Integration | In-house production eliminates supply concentration risk for transient expression systems. |
| Cell and Gene Therapy Convergence | Viral vector expertise captures adjacent biologics workflows from existing sponsor relationships. |
Study Parameters
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CMO procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and NMPA GMP certification databases; plus customs and trade flow analysis — were reconciled through bottom-up service-type segmentation and top-down regional demand aggregation.
Historical capacity utilization and sponsor outsourcing patterns were cross-referenced against expert panel input on regulatory timeline expectations and technology adoption curves across the analysis window. Segmentation dimensions modeled include service type, end-user category, application purpose, and delivery mode geography, with CAGRs derived from slope-intercept fitting to normalized spending trajectories. Forecast inputs incorporated single-use bioreactor adoption rates and NMPA harmonization progress against EMA MDR documentation burden impacts.
Inputs from EMA and FDA pre-approval inspection records were available through the study window; gaps in real-time sponsor CMO selection criteria introduce uncertainty bands around offshore delivery mode share projections. Forecasts reflect assumptions on regulatory convergence timelines and technology transfer efficiency. Practitioners should monitor NMPA international audit recognition agreements and perfusion bioreactor yield improvement disclosures for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Global Qpcr Reagents Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
Spain Specialty Enzymes Market