
 DNA and RNA Sample Preparation Market | 2026-2036
DNA and RNA Sample Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
DNA and RNA Sample Preparation Market Analysis
North American reagent manufacturers is restructuring supply chains to secure polymerase and magnetic bead inputs amid volatile raw material sourcing. Thermo Fisher Scientific leverages its integrated consumables-instrument ecosystem to lock in multi-year hospital contracts. QIAGEN N.V. anchors its position through proprietary silica-membrane chemistry optimized for low-yield forensic specimens. Agilent Technologies Inc. differentiates via microfluidic automation that compresses library prep turnaround times for clinical labs.
DNA and RNA sample preparation encompasses the extraction, purification, quantification, and library construction of nucleic acids from biological matrices, typically requiring 260/280 absorbance ratios above 1.8 for downstream sequencing or PCR compatibility. The process serves as the quality-determining gateway for molecular diagnostics, genomics research, and forensic identification workflows. Reagents and kits capture the dominant revenue share due to recurring consumable demand tied to instrument installed bases, while automated pipetting systems represent the fastest-expanding technology segment as laboratories confront technician staffing constraints. Clinical diagnostics applications command premium pricing relative to research laboratory volumes, reflecting stringent regulatory validation requirements and patient-sample liability exposure.
The FDA oversees laboratory-developed test validation standards that directly shape sample prep protocol documentation and traceability requirements for U.S. clinical operators. The EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management frameworks impose design-control and post-market surveillance obligations on European manufacturers seeking CE-marked entry. WHO prequalification pathways for nucleic acid testing in low-resource settings are expanding addressable demand for stabilized, ambient-temperature sample collection chemistries. Stakeholders must monitor how evolving regulatory divergence between U.S. and European validation standards fragments product development roadmaps and complicates global kit registration strategies.
Market Dynamics
Clinical laboratories face acute technician shortages while diagnostic test volumes surge, forcing automation investments that compress manual nucleic acid extraction workflows. This labor-capacity mismatch is restructuring procurement priorities across hospital molecular diagnostics programs.
Growth Catalysts
- ISO 13485 quality mandates:European manufacturers pursuing CE-marked IVD entry must document rigorous design controls, elevating demand for validated sample prep kits with traceable supply chains.
- Forensic specimen backlogs:Cold case DNA testing initiatives in the United States and United Kingdom are accelerating throughput requirements for low-yield extraction chemistries.
- Magnetic bead automation:Robotic liquid handlers are displacing manual spin-column protocols in high-throughput clinical labs, driving recurring consumable attachment to installed instrument bases.
Market Restraints
- Polymerase input volatility:Reagent manufacturers face erratic sourcing of recombinant enzymes from concentrated Asian fermentation suppliers, compressing gross margins on extraction kits.
- FDA LDT enforcement uncertainty:Evolving laboratory-developed test guidance creates compliance timeline risk for hospital labs validating in-house sample prep protocols.
- Silica membrane substitution limits:Forensic and ancient DNA applications lack viable alternatives to proprietary silica chemistry, locking buyers into single-source dependencies.
Strategic Opportunities
- WHO prequalification pathways:Ambient-temperature stabilization chemistries for nucleic acid transport are expanding addressable demand in sub-Saharan African and Southeast Asian public health programs.
- Microfluidic-NGS convergence:Integrated library prep automation is collapsing turnaround times for tumor profiling panels, opening clinical oncology contract testing markets.
- Point-of-care decentralization:Miniaturized extraction devices are penetrating physician office laboratories and urgent care networks, bypassing centralized hospital lab channels.
Industry Challenges
- Cross-trained technician scarcity:Molecular diagnostics programs struggle to recruit personnel proficient in both wet-lab nucleic acid handling and automated instrument troubleshooting.
- Legacy LIS integration friction:New automated extraction platforms require costly middleware development to interface with entrenched laboratory information systems in academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA and RNA Sample Preparation Market |
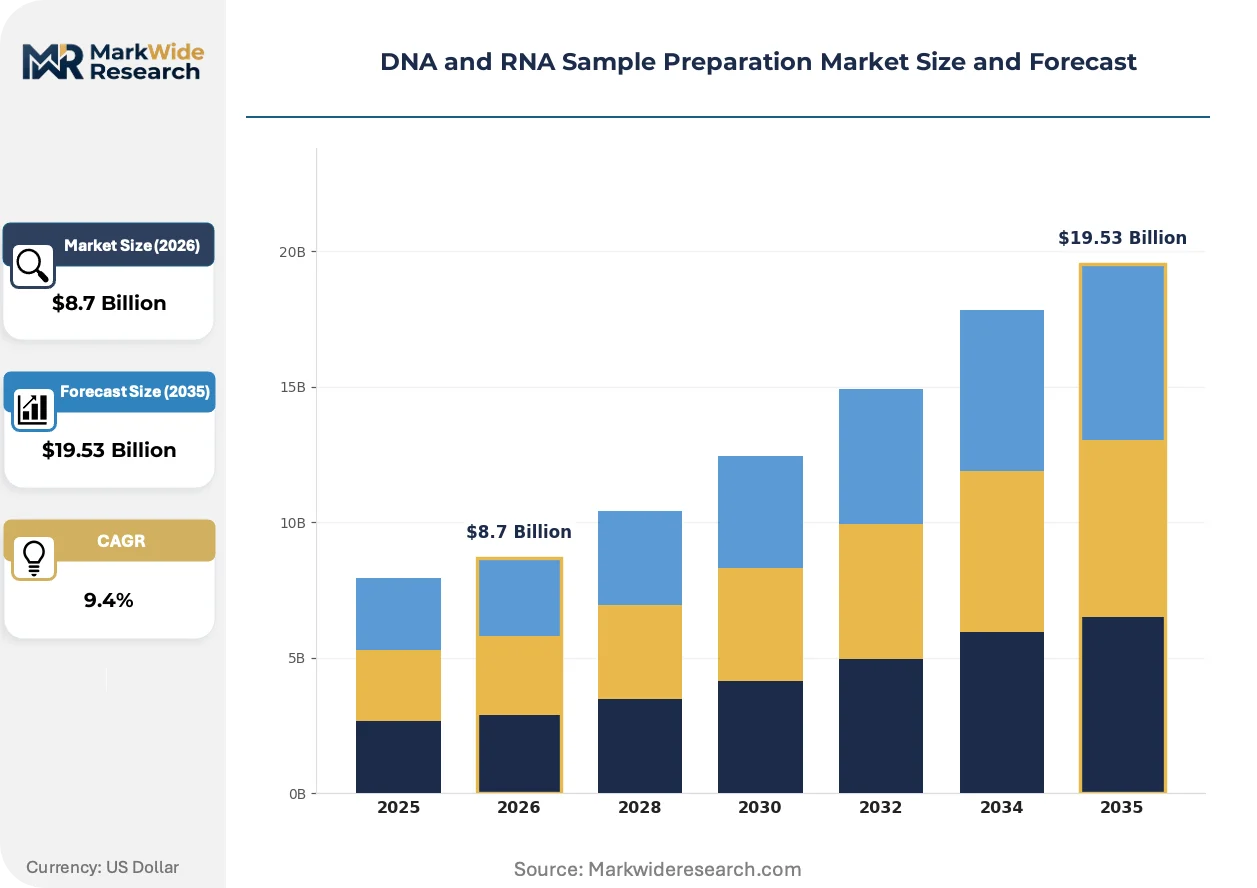
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Consumables Technology: Polymerase Chain Reaction, RNA Extraction, Automated Pipetting, Magnetics Application: Clinical Diagnostics, Research Laboratories, Genetic Testing, Forensics End User: Academic Institutes, Hospitals, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific Inc., QIAGEN N.V., Agilent Technologies Inc., Bio-Rad Laboratories Inc., Illumina Inc., F. Hoffmann-La Roche Ltd., Promega Corporation, Beckman Coulter Life Sciences, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA and RNA Sample Preparation Market Emerging Trajectories
Sample preparation workflows are converging with upstream collection and downstream analysis stages, eliminating discrete handoff points that historically introduced contamination risk and processing delays. This integration is compressing total diagnostic turnaround times while demanding new instrument form factors.
Automated nucleic acid extraction platforms are unifying lysis, binding, washing, and elution steps into sealed cartridge consumables. Hospital clinical laboratories are adopting these closed systems at accelerating replacement cycles for open-platform liquid handlers. The technology is unifying quality control documentation by embedding RFID-tracked reagent lots and automated 260/280 ratio logging directly into instrument software, reducing manual transcription errors that plague regulatory audits.
The FDA's evolving LDT enforcement posture is tightening validation documentation requirements for sample handling protocols in U.S. clinical operators. Manufacturers must now submit extensive analytical performance data linking extraction efficiency to downstream diagnostic accuracy. High-complexity molecular diagnostics laboratories serving oncology and infectious disease testing are most affected, responding by consolidating vendor relationships to reduce qualification burden.
Hospital procurement committees are consolidating reagent purchasing through multi-year sole-source agreements tied to instrument placement. Group purchasing organizations and integrated delivery networks are displacing decentralized laboratory purchasing autonomy, particularly in the United States where health system consolidation has concentrated buying power. Academic medical centers with captive biobanking operations exhibit the strongest resistance, maintaining parallel research-grade procurement channels separate from clinical diagnostic supply chains.
DNA and RNA Sample Preparation Market Segmentation
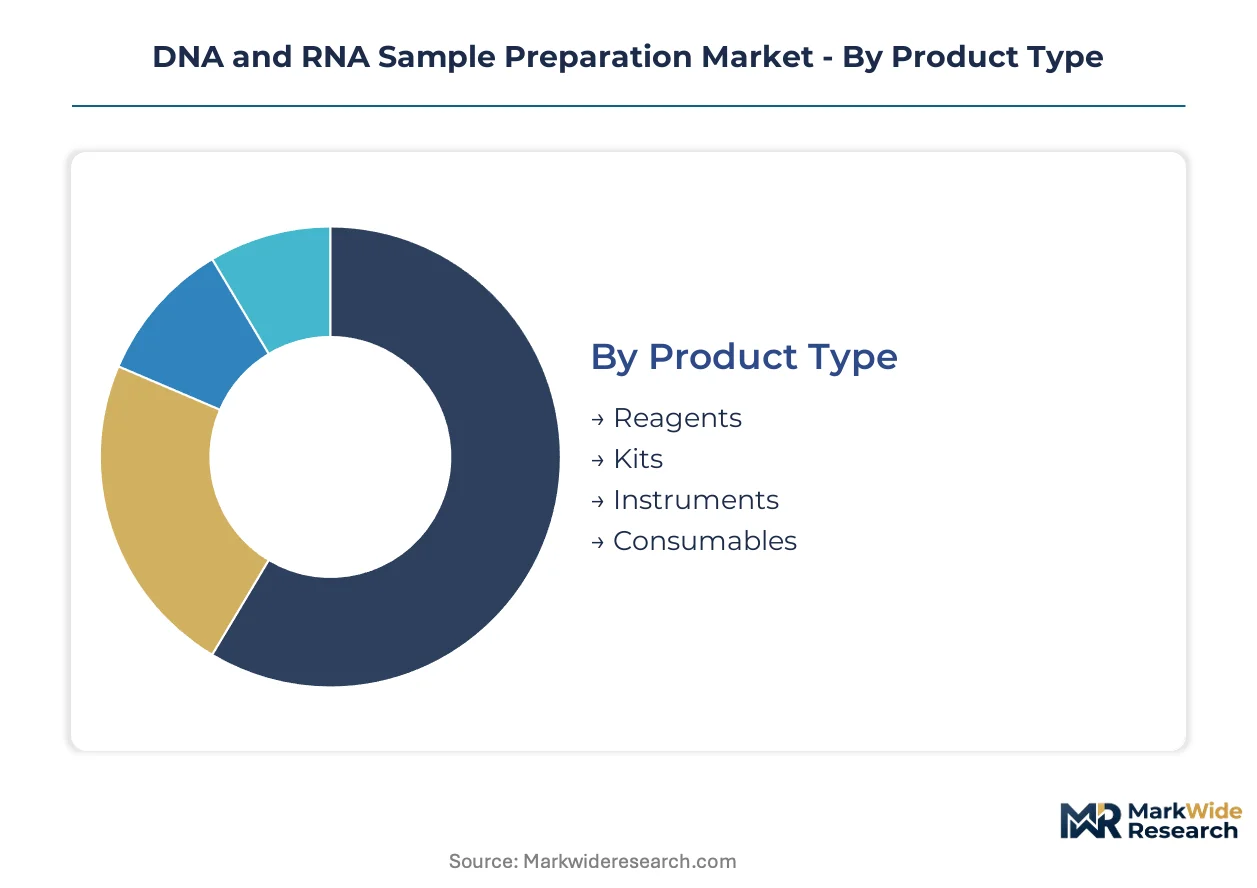
Segmentation in DNA and RNA sample preparation reveals divergent margin profiles and automation readiness across product architectures. Procurement patterns split sharply between high-throughput clinical installations and flexible research configurations. Understanding these divides shapes vendor pricing strategies and R&D allocation priorities.
Product Type:
Reagent and kit volumes dominate procurement spend, yet instrument placements lock in long-term consumable attachment rates across hospital networks.
- Reagents:Enzyme formulations, buffers, and lysis solutions constitute the recurring revenue foundation for extraction chemistry suppliers. Hospital molecular diagnostics programs in the United States consume polymerase and magnetic bead formulations at accelerating rates as automated platforms expand installed bases.
- Kits:Pre-formulated extraction chemistries bundle silica membranes, spin columns, or magnetic bead suspensions with validated protocols. Academic medical centers prioritize kit standardization to satisfy FDA laboratory-developed test documentation requirements for downstream diagnostic accuracy.
- Instruments:Robotic liquid handlers and closed-system extractors command capital budgets with 5-7 year replacement cycles. Biotechnology firms invest in modular open-platform architectures that accommodate protocol customization for novel sample matrices.
- Consumables:Cartridge-based elution tubes, collection plates, and RFID-tracked reagent packs embed quality control documentation directly into instrument software. Pharmaceutical companies driving high-throughput screening operations source these in bulk to minimize per-sample handling costs.
Mature deployment sits with Reagents. Newer deployment is concentrated in Instruments as labor shortages force automation retrofits.
Technology:
Automation-ready modalities command procurement premiums, while legacy chemistries retain entrenched positions in specialized applications.
- Polymerase Chain Reaction:Thermal cycling-dependent amplification remains the workhorse for targeted nucleic acid detection in infectious disease panels. Clinical diagnostics laboratories in Germany and France deploy PCR-integrated sample prep workflows for regulatory-compliant pathogen identification.
- RNA Extraction:Stabilized collection chemistries and ribonuclease-free handling protocols protect labile transcripts for gene expression analysis. Oncology-focused contract testing facilities prioritize RNA integrity metrics above DNA yield for fusion transcript detection.
- Automated Pipetting:Robotic liquid handlers displace manual multichannel pipetting in high-throughput screening environments. Biotechnology firms confronting technician recruitment constraints are expanding these installations fastest.
- Magnetics:Paramagnetic bead separation enables walk-away automation with minimal centrifugation requirements. Hospital labs with space constraints favor magnetic platforms over vacuum-manifold spin column alternatives.
Established workflows center on Polymerase Chain Reaction. Automated Pipetting is climbing the fastest as staffing gaps widen.
Application:
Regulatory validation intensity determines pricing power, with patient-sample liability driving premium tiers.
- Clinical Diagnostics:FDA and EMA oversight mandates extensive analytical performance documentation linking extraction efficiency to diagnostic accuracy. United Kingdom hospital trusts consolidate vendor relationships to reduce qualification burden for infectious disease and oncology testing.
- Research Laboratories:Flexible protocols accommodate experimental matrices without regulatory submission requirements. Academic institutes in Japan and Australia maintain parallel procurement channels separate from clinical supply chains to preserve protocol autonomy.
- Genetic Testing:Direct-to-consumer and carrier screening applications demand high-throughput compatibility with diverse sample types. Commercial laboratories in the United States scale automated extraction to match surging hereditary cancer panel volumes.
- Forensics:Low-yield ancient DNA and degraded crime scene specimens require proprietary silica-membrane chemistries with documented contamination controls. Cold case initiatives in the United Kingdom and United States are accelerating throughput requirements for this segment.
Clinical Diagnostics commands the steepest premium tier. Research Laboratories offer volume scale with lower compliance overhead.
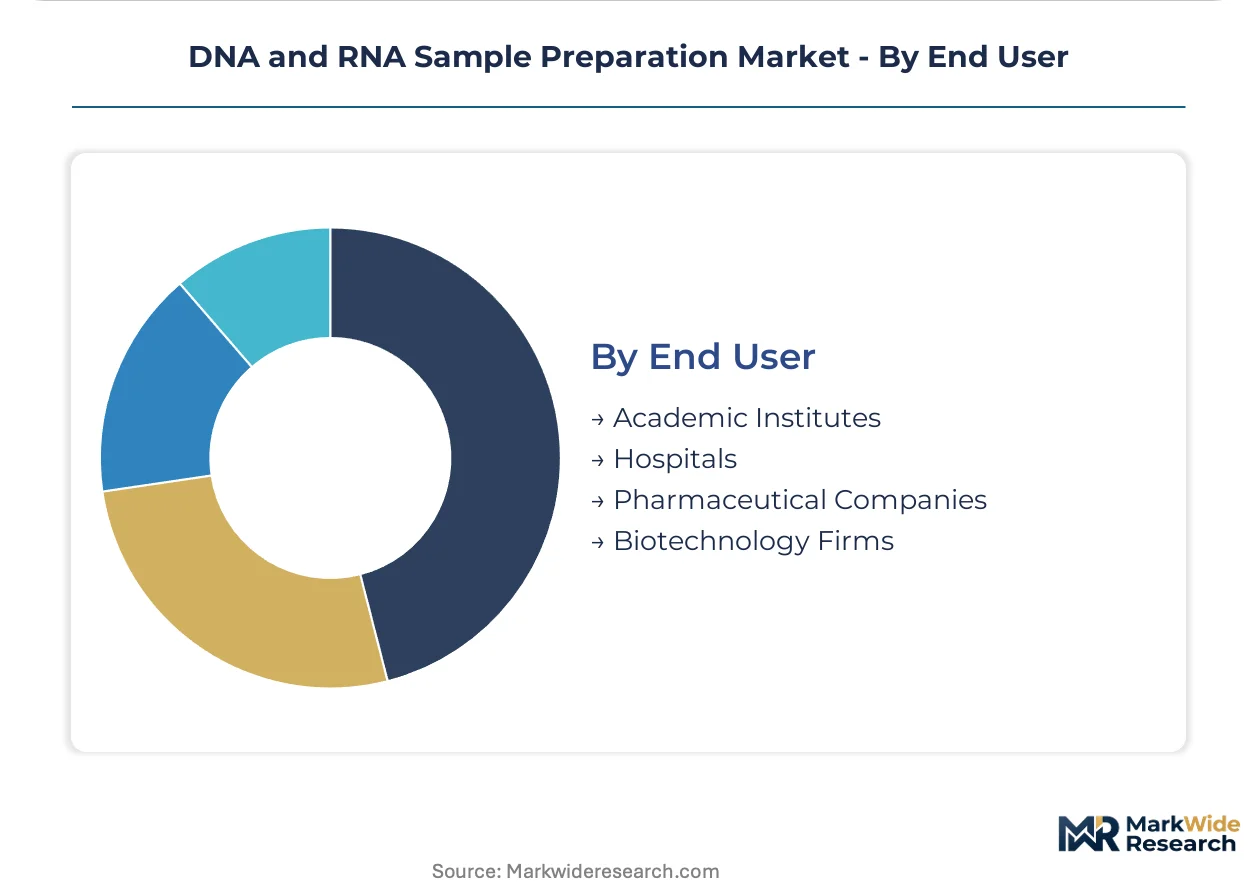
End User:
Procurement centralization varies sharply, with integrated delivery networks displacing decentralized laboratory autonomy in some channels.
- Academic Institutes:Dual-track purchasing maintains research-grade flexibility alongside clinical collaboration requirements. Biobanking operations at major United States academic medical centers resist sole-source agreements to preserve specimen processing protocol diversity.
- Hospitals:Group purchasing organizations concentrate reagent buying power across consolidated health systems. Molecular diagnostics programs in France and Germany face tightening EMA In Vitro Diagnostic Regulation compliance timelines for sample prep validation.
- Pharmaceutical Companies:High-throughput screening and companion diagnostic development drive demand for automated extraction scalability. Quality management systems must satisfy FDA and EMA design-control obligations simultaneously.
- Biotechnology Firms:Agile R&D operations prioritize modular instrument platforms with rapid protocol reconfiguration capabilities. Cell and gene therapy developers require nucleic acid extraction compatible with novel vector characterization workflows.
Hospital procurement exhibits the strongest consolidation pressure. Biotechnology Firms retain the most decentralized purchasing autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant enzyme fermentation capacity clusters in South Korean and Chinese bioprocessing hubs, creating input dependencies for extraction kit manufacturers worldwide. Magnetic bead raw material supply chains trace to Japanese and German specialty chemical producers, while instrument assembly concentrates in United States and German precision manufacturing zones.
United States
Hospital-based molecular diagnostics programs and academic medical centers drive instrument and reagent procurement at scale. The FDA's evolving guidance on laboratory-developed tests tightens quality benchmarks for sample handling protocols, forcing validation documentation upgrades. The Boston-Cambridge biotech corridor anchors demand for automated nucleic acid extraction workflows serving clinical oncology testing.
Germany
Clinical diagnostics laboratories accelerate adoption of automated extraction platforms amid technician staffing constraints. The EMA's In Vitro Diagnostic Regulation imposes design-control and post-market surveillance obligations on manufacturers seeking CE-marked entry. The Rhine-Main region around Frankfurt hosts concentrated pharmaceutical quality control operations demanding high-throughput sample prep scalability.
China
Domestic bioprocessing infrastructure expands recombinant polymerase and magnetic bead production to reduce import dependency. The NMPA strengthens nucleic acid testing quality standards for domestic IVD registration, elevating documentation requirements. The Yangtze River Delta biotech manufacturing zone attracts automated extraction platform assembly investments from multinational suppliers.
Japan
Precision instrument manufacturers supply robotic liquid handling systems to Asia-Pacific clinical laboratories confronting labor shortages. The PMDA maintains stringent analytical performance validation standards for nucleic acid-based diagnostics entering the market. The Kansai region around Osaka hosts specialized magnetic bead chemistry producers serving forensic and research applications.
United Kingdom
Cold case DNA testing initiatives accelerate throughput requirements for low-yield extraction chemistries in forensic laboratories. The UK Medicines and Healthcare products Regulatory Agency aligns with EMA IVD frameworks while maintaining national competency standards. London-based academic medical centers resist sole-source procurement agreements to preserve biobanking protocol flexibility.
DNA and RNA Sample Preparation Market Vendor Landscape
Global majors compete with regional champions across integrated consumables-instrument ecosystems and specialized chemistry portfolios. The vendor base stratifies into three tiers: diversified life science conglomerates with captive reagent supply, mid-scale automation specialists with modular platform architectures, and niche chemistry providers focused on forensic or ancient DNA applications. Dominant competitive moves include multi-year sole-source hospital contracts tied to instrument placement and proprietary silica-membrane chemistry lock-ins for low-yield specimen workflows.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and QIAGEN N.V. exemplify the integrated ecosystem archetype, while Agilent Technologies Inc. occupies a position emphasizing microfluidic automation differentiation. These three entities anchor the premium tier through recurring consumable attachment to installed instrument bases, with each representing distinct strategic positioning around chemistry intellectual property, automation hardware, or workflow integration depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Agilent Technologies Inc. |
| Bio-Rad Laboratories Inc. |
| Illumina Inc. |
| F. Hoffmann-La Roche Ltd. |
| Promega Corporation |
| Beckman Coulter Life Sciences |
| PerkinElmer Inc. |
| Others |
Supply Flow & Price Mechanics
Hospital group purchasing organizations and integrated delivery networks concentrate procurement authority across United States health systems, anchoring contract-based long-term offtake agreements that bundle instrument placement with recurring reagent commitments. This buyer consolidation shifts pricing power toward vendors with captive consumable ecosystems and multi-year service warranties.
Pricing Analysis
Service bundling separates premium-tier offerings from unbundled economy alternatives, with validated protocol documentation and FDA-compliant quality control embedded in higher tiers. Price differentiation hinges on ISO 13485 certification grade and geographic delivery cost to academic medical centers versus centralized hospital networks. Cost compression in economy reagent tiers is intensifying because polymerase input volatility squeezes manufacturer margins. Biotechnology firms exhibit highest price sensitivity due to discretionary R&D budgets, while clinical diagnostics laboratories accept premium pricing to mitigate patient-sample liability exposure.
Supply Chain Analysis
Recombinant polymerase supply rests on South Korean and Chinese bioprocessing fermentation capacity, while magnetic bead raw materials draw from Japanese and German specialty chemical producers. Instrument assembly centers on United States and German precision manufacturing zones, with cartridge consumables sourced from Malaysian and Mexican contract manufacturers. Single-source vulnerability concentrates in silica-membrane chemistry for forensic applications, where proprietary formulations lack substitution alternatives. Distribution runs through direct hospital contracts and group purchasing organization channels, bypassing traditional laboratory distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over recombinant enzyme fermentation capacity and magnetic bead chemistry determines long-term margin sustainability. Players pursuing backward integration into raw material supply secure procurement priority during input shortages.
For Market Incumbents: Deploy multi-year sole-source hospital contracts tied to automated platform placement to lock in consumable attachment rates against modular open-platform substitutes. Deepen in-house production of magnetic bead formulations to reduce dependency on Asian fermentation suppliers facing erratic output. Consolidate vendor qualification documentation for FDA laboratory-developed test compliance to raise switching costs for hospital molecular diagnostics programs.
For New Entrants and Emerging Players: Launch via point-of-care miniaturized extraction devices targeting physician office laboratories and urgent care networks bypassing entrenched hospital procurement channels. Penetrate sub-Saharan African and Southeast Asian public health programs through WHO prequalification pathways for ambient-temperature stabilization chemistries. Position against legacy spin-column workflows by emphasizing walk-away automation compatibility with space-constrained clinical laboratories.
For Investors and Strategic Acquirers: The window for entry favors niche chemistry providers with proprietary silica-membrane intellectual property for low-yield forensic and ancient DNA applications. Long-term viability centers on recurring consumable revenue models rather than capital-intensive instrument placements with extended replacement cycles. Watch FDA enforcement posture on laboratory-developed test validation timelines as the critical inflection signal for hospital lab capital commitment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Hospital System Partnership | Locks in reagent volume commitments through integrated consumables-instrument ecosystems across United States academic medical centers. |
| Backward Integration into Polymerase Production | Captive recombinant enzyme fermentation capacity insulates gross margins from volatile Asian supplier pricing. |
| WHO Prequalification Pathway Investment | Ambient-temperature chemistry validation opens addressable demand in sub-Saharan African public health infrastructure. |
| Microfluidic-NGS Platform Integration | Collapsing library prep turnaround times penetrates clinical oncology contract testing markets with premium pricing. |
| Forensic Silica-Membrane Patent Expansion | Proprietary low-yield extraction chemistry maintains single-source dependency for cold case DNA testing initiatives. |
Methodological Framework
Independent corroboration across hospital laboratory directors, molecular diagnostics procurement managers, and reagent manufacturer product strategists underwrites the qualitative findings in this study. Primary interviews with FDA regulatory affairs specialists, EMA compliance officers, and academic biobanking operations heads captured validation protocol documentation requirements. Secondary validation drew from FDA laboratory-developed test guidance releases, EMA In Vitro Diagnostic Regulation implementation timelines, WHO prequalification pathway documentation, and ISO 13485 certification databases. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down health system procurement budget allocations.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory and mix-shift effects. Segmentation dimensions modeled include product architecture, automation technology readiness, regulatory validation intensity, and end-user procurement centralization. CAGRs were derived from installed base expansion curves, replacement cycle compression, and consumable attachment rate assumptions. Forecast inputs incorporated technician staffing constraint projections and evolving FDA enforcement posture on laboratory-developed test documentation.
Polymerase supply disruption, FDA LDT guidance revision, and hospital consolidation acceleration are the dominant revision risks to the forecast framework. Forecasts reflect documented assumptions regarding automation adoption curves and regulatory timeline stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Biobank Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market