
 Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market | 2026-2036
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market Intelligence
Distribution channels for specialized PCR reagents and consumables is narrowing as integrated systems gain favor, a shift benefiting large-scale manufacturers. Thermo Fisher Scientific leverages its extensive global sales network to secure large contracts. Bio-Rad Laboratories differentiates through its focus on dPCR technology and associated assays. QIAGEN competes by offering sample-to-insight workflows that bundle instrumentation with tailored reagent kits.
Digital PCR and real-time PCR are molecular biology techniques for amplifying and quantifying nucleic acid sequences. These methods utilize fluorescent probes, such as TaqMan Probes, to monitor amplification in real-time or partition samples for absolute counting. The primary purpose is sensitive detection and measurement of DNA or RNA for research and diagnostics. PCR Reagents and Consumables constitute the largest recurring revenue segment, while demand from diagnostic laboratories for pathogen detection is accelerating instrument sales.
Regulatory oversight from bodies like the US FDA, requirements for CE marking in Europe, and approvals by China's NMPA are critical for market access. These agencies mandate stringent validation for instruments and assays intended for clinical diagnostic use. The choice between higher-throughput qPCR and the precision of dPCR for specific applications will define future investment strategies for end-users.
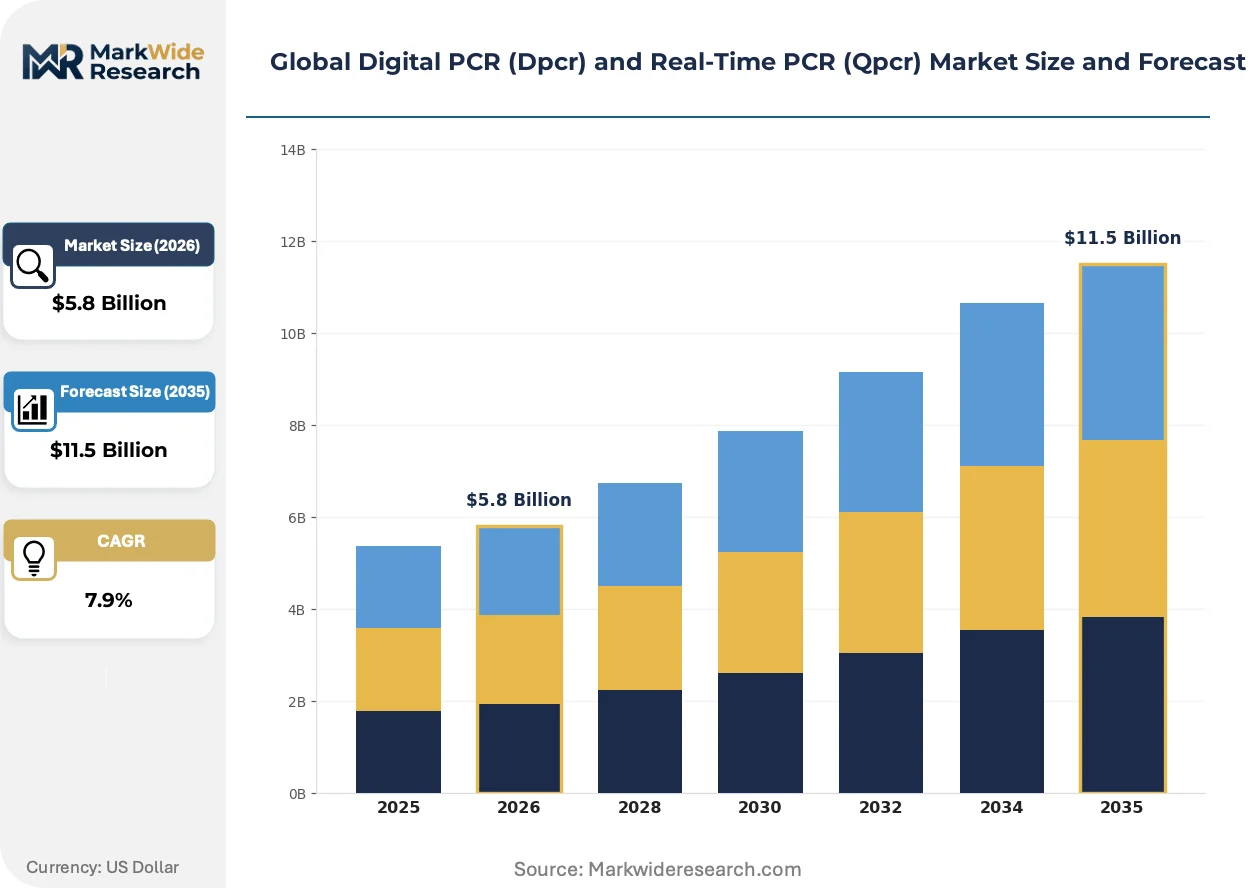
Market Dynamics
The central force shaping the market is the convergence of microfluidics with PCR instrumentation, enabling higher throughput and sensitivity. This shift is driven by demand from clinical diagnostics for rapid, precise pathogen and biomarker quantification for personalized medicine.
Growth Catalysts
- Oncology Research:Demand for liquid biopsy and rare mutation detection applications in cancer research and diagnostics accelerates the adoption of high-precision dPCR systems for their absolute quantification capabilities.
- Public Health Initiatives:Government-funded programs in countries like the United States and China for pandemic preparedness and infectious disease surveillance are expanding the installed base of molecular diagnostic instruments in public laboratories.
- Microfluidics Integration:The incorporation of microfluidics technology enhances sample partitioning in dPCR and optimizes reaction volumes in qPCR, improving assay sensitivity and enabling higher throughput for complex analyses.
Market Restraints
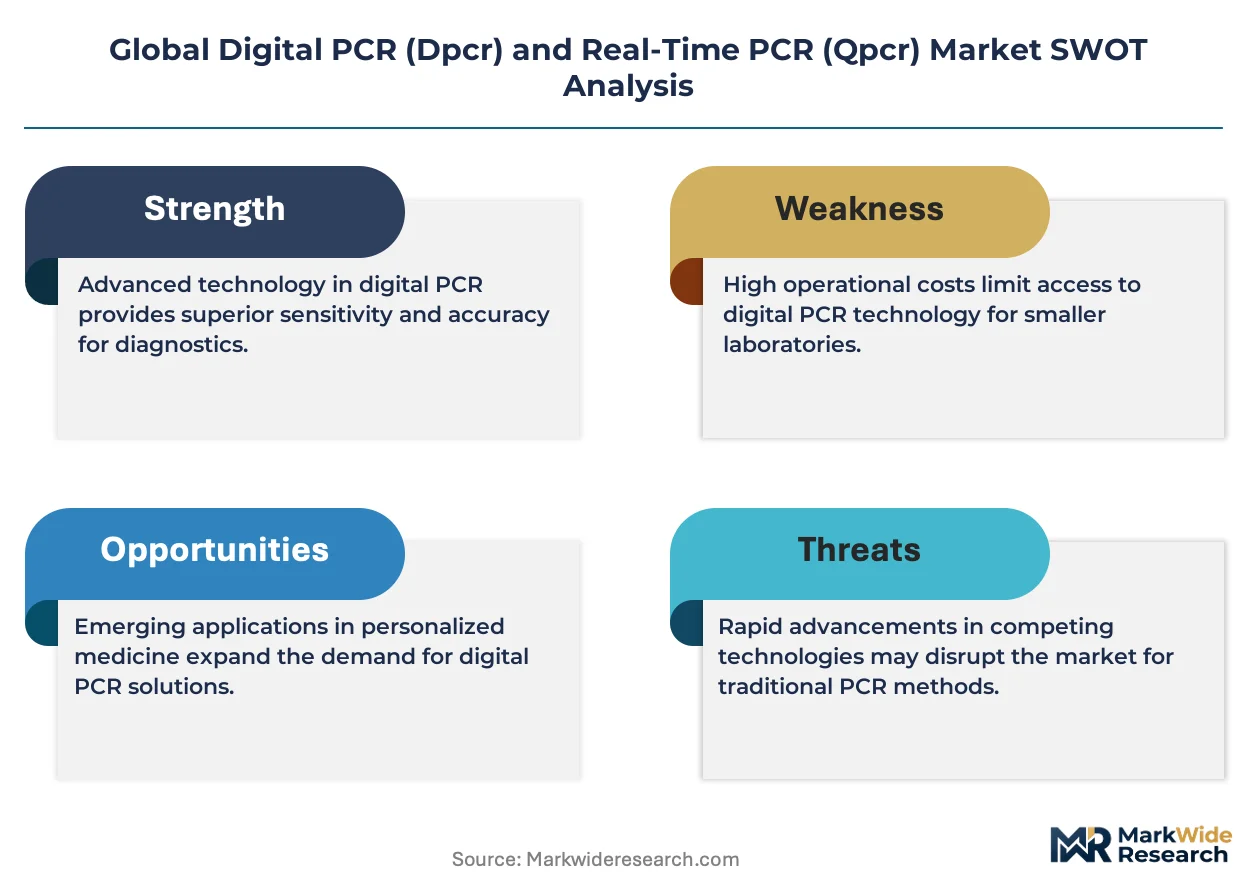
- High Capital Outlay:The significant initial investment required for high-end dPCR and qPCR instrumentation limits adoption by smaller research laboratories and clinics with constrained capital equipment budgets.
- Multiplexing Limitations:While dPCR offers superior precision, its capacity for multiplexing, or analyzing numerous targets in one reaction, remains technically constrained compared to the capabilities of many real-time PCR platforms.
- Stringent Validation Requirements:The rigorous clinical validation processes mandated by regulatory bodies such as the FDA and EMA, along with China's NMPA, create extended and costly development timelines for new diagnostic assays.
Strategic Opportunities
- Food and Environmental Testing:Applying PCR technology for pathogen detection in food supply chains and for monitoring microbial contaminants in water represents a significant, underpenetrated market segment beyond clinical diagnostics.
- Point-of-Care Platforms:Developing portable, rapid, and user-friendly PCR systems for decentralized testing in clinics, physician offices, or field settings addresses a critical need in regions with limited laboratory infrastructure.
- NGS Workflow Integration:There is a clear opportunity to position dPCR as an essential validation tool to confirm findings from Next-Generation Sequencing (NGS) and to precisely quantify sequencing libraries before a run.
Industry Challenges
- Bioinformatics Skill Gap:A shortage of technicians and scientists with the advanced bioinformatics skills needed to analyze and interpret the large, complex datasets generated by high-throughput PCR systems hampers effective data utilization.
- Cross-Platform Standardization:A lack of standardization in instrumentation, reagents, and data analysis protocols across different manufacturers leads to variability in results, complicating inter-laboratory study comparisons and the establishment of universal diagnostic standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital PCR Systems, Real-Time PCR Instruments, PCR Reagents, PCR Consumables Technology: Microfluidics, Emulsion PCR, SYBR Green, TaqMan Probes, Molecular Beacon, Others Application: Gene Expression Analysis, Pathogen Detection, Mutation Testing, Copy Number Variation, Biomarker Discovery End User: Biotechnology Firms, Pharmaceutical Companies, Academic Research, Diagnostic Laboratories, Forensic Agencies |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., F. Hoffmann-La Roche Ltd, QIAGEN N.V., Danaher Corporation, Agilent Technologies Inc., Abbott Laboratories, Takara Bio Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market Strategic Shifts & Innovations
Automation and workflow integration are reshaping the PCR market, moving it from standalone instruments to complete sample-to-insight systems. This evolution prioritizes reproducibility and data traceability for clinical and research applications, reducing hands-on time and potential for error.
Miniaturization and Microfluidics
Microfluidics technology partitions samples into thousands of nanoliter droplets for digital PCR analysis. Clinical laboratories are rapidly adopting this for applications requiring absolute quantification, such as liquid biopsy. This technology is digitizing nucleic acid counting, converting the analog signal of qPCR into a binary measurement that enhances precision.
Stricter Regulatory Scrutiny
The European Union's In Vitro Diagnostic Regulation (IVDR) imposes stricter requirements for clinical evidence and post-market surveillance. This regulation elevates the burden of proof for assay manufacturers, demanding rigorous performance validation. Diagnostic laboratories now prioritize CE-IVDR marked systems and kits to ensure compliance, affecting procurement across the EU.
Consolidated Procurement Models
A shift towards bundled procurement of instruments, reagents, and software is gaining prominence. This trend favors large manufacturers offering integrated "sample-to-insight" workflows, challenging smaller, specialized reagent suppliers. This consolidation of purchasing is most visible within large hospital networks in the United States and public health laboratories in China.
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market Segmentation
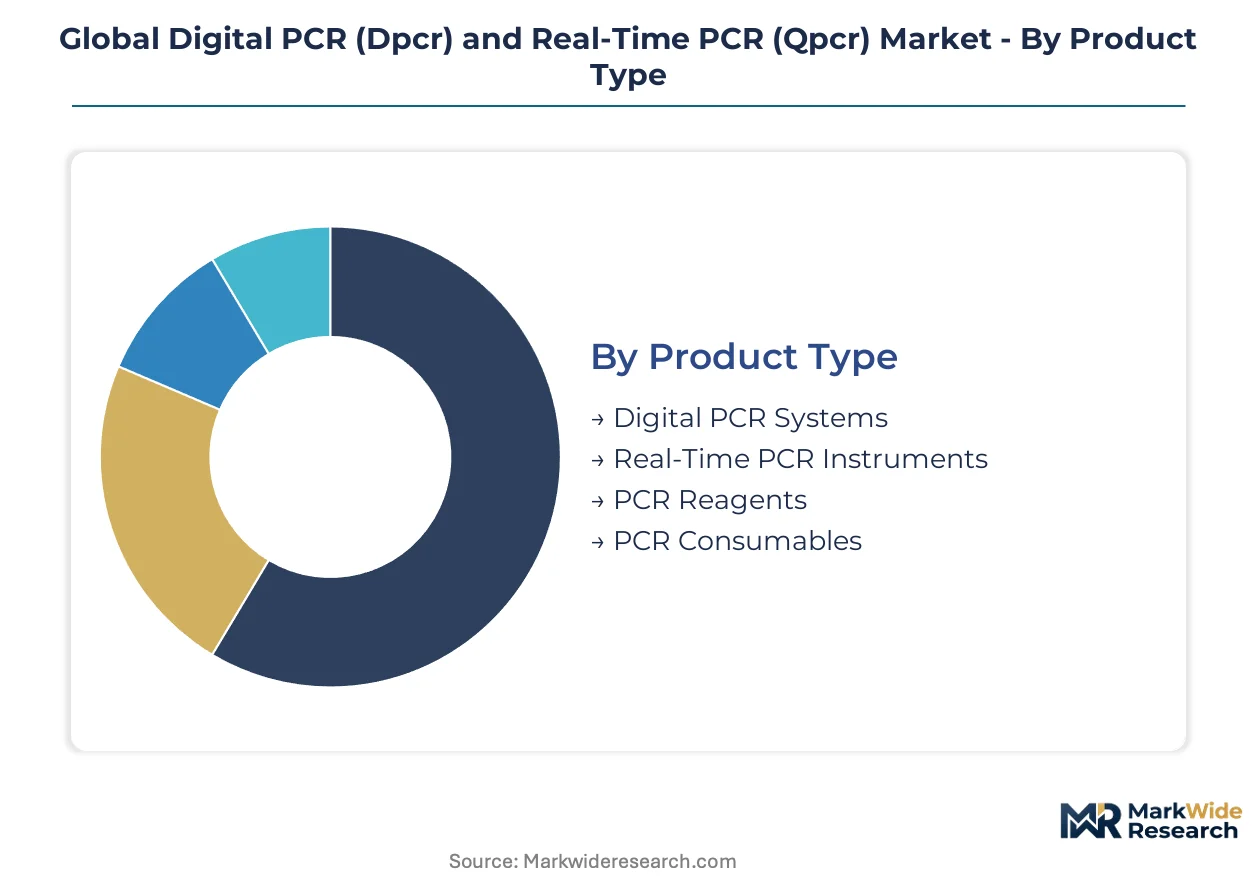
The Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market segments illuminate distinct technological advancements and end-user demands. Understanding these divisions helps identify areas of concentrated revenue and emerging opportunities across diverse applications. This granular view assists stakeholders in aligning product development with specific market needs.
Product Type:
The product type segment spans mature and emerging offerings, reflecting the evolution from established real-time PCR to advanced digital PCR solutions. Recurring revenue streams from reagents and consumables underpin market stability, while instrument sales drive initial capital expenditure.
- PCR Reagents:These include enzymes, buffers, dNTPs, and fluorescent probes essential for PCR amplification and detection. Demand concentrates in diagnostic laboratories and research institutions due to continuous assay execution, representing the largest recurring revenue segment.
- Real-Time PCR Instruments:These systems enable the simultaneous amplification and quantification of nucleic acids using fluorescent signals. Diagnostic laboratories in countries like China and the United States drive significant instrument sales, fueled by public health initiatives for pathogen detection.
- Digital PCR Systems:These instruments partition samples into thousands of reactions for absolute quantification of nucleic acids. Oncology research groups in Europe utilize these for highly sensitive liquid biopsy applications.
- PCR Consumables:This category includes reaction plates, tubes, sealing films, and tips necessary for sample preparation and reaction execution. Clinical laboratories require high volumes for routine diagnostic workflows.
PCR Reagents handles the majority of throughput; Digital PCR Systems is the fastest mover on share.
Technology:
Technological innovation within the PCR market focuses on enhancing sensitivity, throughput, and multiplexing capabilities for complex biological analyses. The integration of microfluidics is a key differentiator, improving precision and reducing sample volumes.
- TaqMan Probes:These dual-labeled oligonucleotide probes bind to target DNA sequences, releasing a fluorescent signal upon cleavage by Taq polymerase. This technology is widely adopted in diagnostic assays for pathogen detection due to its specificity and reliability.
- Microfluidics:This technology manipulates small fluid volumes, enabling precise sample partitioning for dPCR and optimized reaction conditions for qPCR. Clinical diagnostics leverage microfluidics for higher throughput and enhanced assay sensitivity in personalized medicine.
- Emulsion PCR:This method encapsulates individual DNA molecules in water-in-oil emulsion droplets for amplification. Next-Generation Sequencing (NGS) library preparation frequently employs emulsion PCR for clonal amplification.
- SYBR Green:A fluorescent dye that binds to double-stranded DNA, SYBR Green offers a cost-effective method for real-time PCR quantification. Academic research laboratories often use SYBR Green for gene expression studies.
- Molecular Beacon:These hairpin-shaped oligonucleotide probes fluoresce only when hybridized to a complementary target sequence. Forensic agencies apply molecular beacons for highly specific DNA detection in evidence analysis.
- Others:This segment includes less common or proprietary PCR chemistries and detection methods. Specialized research applications may utilize these alternative technologies for unique experimental requirements.
TaqMan Probes maintain a significant installed base; Microfluidics integration exhibits the steepest expansion trajectory.
Application:
The diverse applications of PCR technology span clinical diagnostics, research, and specialized testing, each with unique requirements for precision and throughput. Public health and oncology research represent areas of intense demand and rapid technological integration.
- Pathogen Detection:This application focuses on identifying and quantifying infectious agents like viruses and bacteria in clinical samples. Diagnostic laboratories globally rely on PCR for rapid and accurate diagnosis of diseases, particularly in pandemic preparedness.
- Mutation Testing:This involves detecting specific genetic alterations associated with diseases, especially cancer. Oncology research and clinical diagnostics utilize dPCR for highly sensitive detection of rare mutations in liquid biopsy samples.
- Gene Expression Analysis:This application measures the activity of genes by quantifying mRNA levels. Biotechnology firms use gene expression analysis for drug discovery and development, assessing therapeutic efficacy.
- Copy Number Variation:This refers to variations in the number of copies of a particular gene or DNA segment. Genetic research laboratories investigate copy number variations for insights into disease susceptibility.
- Biomarker Discovery:This application seeks to identify novel biological indicators for disease diagnosis, prognosis, or therapeutic response. Pharmaceutical companies employ PCR in early-stage research to validate potential biomarkers.
Pathogen Detection applications generate substantial revenue; Mutation Testing is experiencing significant growth due to advancements in liquid biopsy.
End User:
The end-user landscape for PCR technologies is segmented by institutional type, reflecting varying scales of operation, regulatory environments, and research priorities. Diagnostic laboratories and biotechnology firms are primary drivers of instrument and reagent demand.
- Diagnostic Laboratories:These facilities perform routine clinical testing for disease diagnosis and monitoring. Demand from these laboratories, especially in the United States and Germany, accelerates instrument sales for high-throughput pathogen detection.
- Biotechnology Firms:These companies engage in research and development of new biological products and technologies. Biotechnology firms use PCR extensively for gene cloning, expression analysis, and quality control in biopharmaceutical production.
- Pharmaceutical Companies:These organizations develop and manufacture drugs and therapies. Pharmaceutical companies utilize PCR for drug target validation, preclinical testing, and pharmacogenomics studies.
- Academic Research:Universities and research institutions conduct fundamental scientific investigations. Academic researchers employ PCR for a wide range of molecular biology experiments, often focusing on novel applications.
- Forensic Agencies:These government bodies apply scientific methods to legal investigations. Forensic agencies use PCR for DNA profiling in criminal cases and paternity testing.
Diagnostic Laboratories drive consistent instrument and reagent sales; Biotechnology Firms are expanding their adoption for novel therapeutic development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded public health initiatives significantly influence the global Digital PCR and Real-Time PCR market. These programs drive the expansion of molecular diagnostic capabilities across diverse regions. Such strategic investments bolster the installed base of instruments in public laboratories.
United States
The US FDA mandates stringent validation for clinical diagnostic assays, shaping market entry for PCR technologies. Demand for pathogen detection from diagnostic laboratories drives instrument sales. Biotech clusters in Boston and the San Francisco Bay Area actively develop advanced molecular diagnostic solutions.
China
Public health initiatives in China are expanding the installed base of molecular diagnostic instruments. The NMPA requires rigorous approvals for clinical diagnostic use, impacting market access. Major cities like Shanghai and Beijing are centers for significant public health investment and R&D.
Germany
Diagnostic laboratories in Germany accelerate instrument sales for high-throughput pathogen detection. The EU IVDR imposes stricter requirements for clinical evidence, influencing procurement decisions. Life science hubs in Munich and Heidelberg are focusing on oncology research applications.
Japan
Advanced research applications and diagnostics drive demand in Japan's PCR market. The PMDA ensures stringent regulatory oversight for new instruments and assays. Tokyo and Kyoto's research institutions are at the forefront of novel PCR technology development.
India
Growing public health initiatives in India increase demand for molecular diagnostic instruments. The CDSCO regulates the approval of diagnostic kits and systems, ensuring quality standards. Biotechnology parks in Bangalore and Hyderabad are expanding their molecular diagnostic capabilities.
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market Key Industry Players
On the supply side, the industry is moderately consolidated, characterized by a mix of large, integrated solution providers and specialized innovators. This structure benefits manufacturers capable of offering complete sample-to-insight systems. Major players leverage extensive global sales networks to secure large contracts, while others differentiate through a focused technology approach. Key competitive moves include offering bundled workflows, strategic portfolio diversification, and expanding geographic reach to meet diverse market demands.
Within the integrated solution provider archetype, Thermo Fisher Scientific Inc. leverages its extensive global sales network to secure large contracts across various diagnostic and research settings. Bio-Rad Laboratories Inc. represents a specialized dPCR innovator, differentiating through its dedicated focus on digital PCR technology and associated assays for high-precision applications. QIAGEN N.V. exemplifies a workflow-focused solution provider, competing by offering comprehensive sample-to-insight workflows that bundle instrumentation with tailored reagent kits, streamlining processes for end-users. These companies collectively anchor significant market segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| F. Hoffmann-La Roche Ltd |
| QIAGEN N.V. |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Abbott Laboratories |
| Takara Bio Inc. |
| Merck KGaA |
Cost & Logistics Intelligence
Air freight corridors for temperature-sensitive reagents introduce specific cost dynamics, shaping supply concentration and influencing downstream price differentiation for PCR products. The specialized logistics required for these sensitive biological materials contribute to the overall cost structure of the market.
Pricing Analysis
Certification level (FDA/CE/NMPA-grade) creates the primary spread in PCR product pricing. The dominant pricing structure combines contract-based long-term agreements for instrumentation with per-unit transactional sales for reagents and consumables. Brand reputation and after-sales service also differentiate prices significantly. Pricing softness stems from consolidated procurement models adopted by large hospital networks. Smaller research laboratories and clinics with constrained capital budgets exhibit the highest price sensitivity for new instrument purchases.
Supply Chain Analysis
Export control regimes for advanced biotechnology components increasingly limit flows, impacting the PCR market's supply chain. Supply concentration centers in the United States, Germany, and China for specialized components and finished goods. The industry relies on critical inputs such as high-purity enzymes, fluorescent probes, and microfluidic chips. Geopolitical tensions affecting specialized component availability represent a significant structural risk. Direct sales channels for major manufacturers and specialized distributors handle downstream product delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is at a platform-economics inflection, driven by the shift towards integrated "sample-to-insight" ecosystems that bundle instruments, reagents, and software for streamlined workflows.
For Market Incumbents:
Harden existing market positions by integrating advanced microfluidics technology into next-generation dPCR and qPCR systems, mitigating the threat from specialized dPCR innovators. Consolidate global distribution networks to secure large contracts, leveraging extensive sales infrastructure. Invest proactively in assay development for emerging applications like liquid biopsy, addressing stricter regulatory scrutiny from bodies such as the EU IVDR. Control key reagent and consumable supply chains to ensure consistent quality and availability.
For New Entrants and Emerging Players:
Pursue underpenetrated market segments such as food and environmental testing, where demand for pathogen detection is growing beyond clinical diagnostics. Develop point-of-care platforms that offer rapid, user-friendly PCR systems for decentralized testing in clinics or field settings. Target smaller research laboratories and clinics with cost-effective, modular solutions that address high capital outlay constraints. A strong go-to-market angle involves offering flexible, subscription-based models for instrument access and reagent supply.
For Investors and Strategic Acquirers:
Carve-out targets emerge from larger life science conglomerates seeking to divest non-core PCR assets, offering opportunities for focused investment. The long-term viability of this market, spanning a 5-10 year window, is anchored in the continuous demand from personalized medicine and public health initiatives. Acquisition targets should prioritize specialized dPCR innovators and firms with proprietary microfluidics technology. An inflection signal to watch is the accelerated adoption of integrated PCR systems in emerging economies like China and India.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling instruments, reagents, and software streamlines workflows for diagnostic laboratories, enhancing efficiency. |
| Regulatory Approval Pathway | Securing CE-IVDR marking is critical for market access in Europe, impacting procurement decisions for diagnostic systems. |
| Manufacturing Scale-Up | Increasing production capacity for microfluidic components supports the growing demand for dPCR systems in oncology research. |
| Strategic Partnership | Collaborating with bioinformatics firms addresses the skill gap in analyzing complex datasets from high-throughput PCR systems. |
| Geographic Expansion | Establishing a stronger presence in China leverages public health initiatives and expanding molecular diagnostic capabilities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by rigorous secondary research. Stakeholders included diagnostic laboratory directors, oncology researchers, biotechnology firm R&D leads, and regulatory affairs specialists. Secondary data sources encompassed FDA and NMPA regulatory filings, scientific publications from PubMed, company annual reports, and industry association data. This approach facilitated a robust bottom-up and top-down triangulation of market insights.
The analytical framework calibrated market sizing and forecasting across the analysis window, segmenting by product type, technology, application, end user, and regulatory compliance level. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected future demand, considering the impact of technological advancements. Key industry-specific forecast inputs included public health spending on infectious disease surveillance and R&D investment in oncology diagnostics.
Macroeconomic conditions sit as an overlay; deviation in global healthcare expenditure or biotechnology R&D funding would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Material shifts in public health policy or diagnostic technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Serine Protease Market
Biotechnology Services
Global Qpcr Reagents Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Biobank Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Global Bioprocess Validation Market