
 Europe Agricultural Biologicals Market | 2026-2036
Europe Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Biologicals Market Insights
EU-registered biocontrol product tiers are bifurcating the competitive landscape as growers demand validated efficacy data alongside organic certification. BASF SE leverages its formulation science heritage to sustain premium positioning in biostimulant concentrates. Koppert Biological Systems anchors its dominance through specialized predator mite production networks serving Dutch glasshouse operators. Novozymes A/S differentiates via enzyme-based biostimulant platforms that occupy the technical frontier of nitrogen mineralization enhancement.
Agricultural biologicals comprise living organisms, derived metabolites, and natural substances formulated for crop protection, nutrition, and soil conditioning, typically requiring cold-chain distribution and defined colony-forming unit thresholds to maintain viability. Their primary commercial purpose is to reduce synthetic chemical residues in food supply chains while maintaining yield parity through modes of action including antibiosis, mycoparasitism, and induced systemic resistance. Biopesticides and biostimulants lead current revenue generation, with biofertilizers representing the fastest-expanding margin pool as fixation and solubilization technologies mature. Crop protection applications retain the largest share of deployed volume, though seed treatment formats are gaining structural share as coating technologies improve microbial survival rates during germination stress.
The EU Green Deal and REACH framework shape product registration pathways, while EFSA establishes residue and toxicology benchmarks that determine market access timelines for novel biological active substances. National regulators in France and Spain enforce additional efficacy verification protocols that extend commercialization lead times but strengthen farmer confidence in labeled performance claims. Stakeholders must monitor the EU AI Act's emerging classification criteria for precision agriculture platforms that pair biological inputs with sensor-driven application timing.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing synthetic pesticide substitution timelines that compress biological product development cycles while elevating registration standards across member states.
Growth Catalysts
- Farm to Fork pesticide reduction targets:The EU Green Deal mandates 50% synthetic chemical reduction by 2030, creating immediate pull for biocontrol alternatives in Mediterranean horticulture clusters.
- Spanish greenhouse biological adoption:Almeria's 30,000 hectares of intensive vegetable production under plastic are converting to integrated pest management protocols that specify predator mite releases.
- Microbial seed coating advances:Polymer encapsulation technologies now protect rhizobia and mycorrhizal inoculants through germination stress periods, expanding treatment addressable market.
Market Restraints
- EFSA registration timelines:Novel active substance evaluations for biocontrol agents extend 24-36 months, delaying commercialization and freezing R&D capital in regulatory queues.
- Cold-chain distribution costs:Live microbial products require 2-8°C logistics infrastructure that concentrates supply capability in Netherlands and Germany, limiting peripheral market access.
- Live microbial shelf stability:Colony-forming unit degradation during transport and storage creates efficacy variability that undermines grower confidence in performance claims.
Strategic Opportunities
- Poland and Romania arable conversion:Eastern European cereal and oilseed producers remain underpenetrated by biologicals, presenting first-mover expansion territory for nitrogen-fixing seed treatments.
- EU AI Act precision agriculture pairing:Emerging classification criteria for sensor-driven biological application timing will reward platforms integrating microbial inputs with drone-mounted multispectral imaging.
- Biostimulant-biofertilizer convergence:Formulations combining humic acid carriers with phosphate-solubilizing bacteria address multiple plant physiological targets in single applications.
Industry Challenges
- Microbial formulation expertise scarcity:Industrial microbiologists capable of scaling axenic fermentation to commercial volumes command premium compensation that strains mid-tier manufacturer payroll structures.
- Organic certification compliance timelines:EU 2018/848 regulation updates require revised input verification protocols that extend product re-certification cycles and inflate audit expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Biologicals Market |
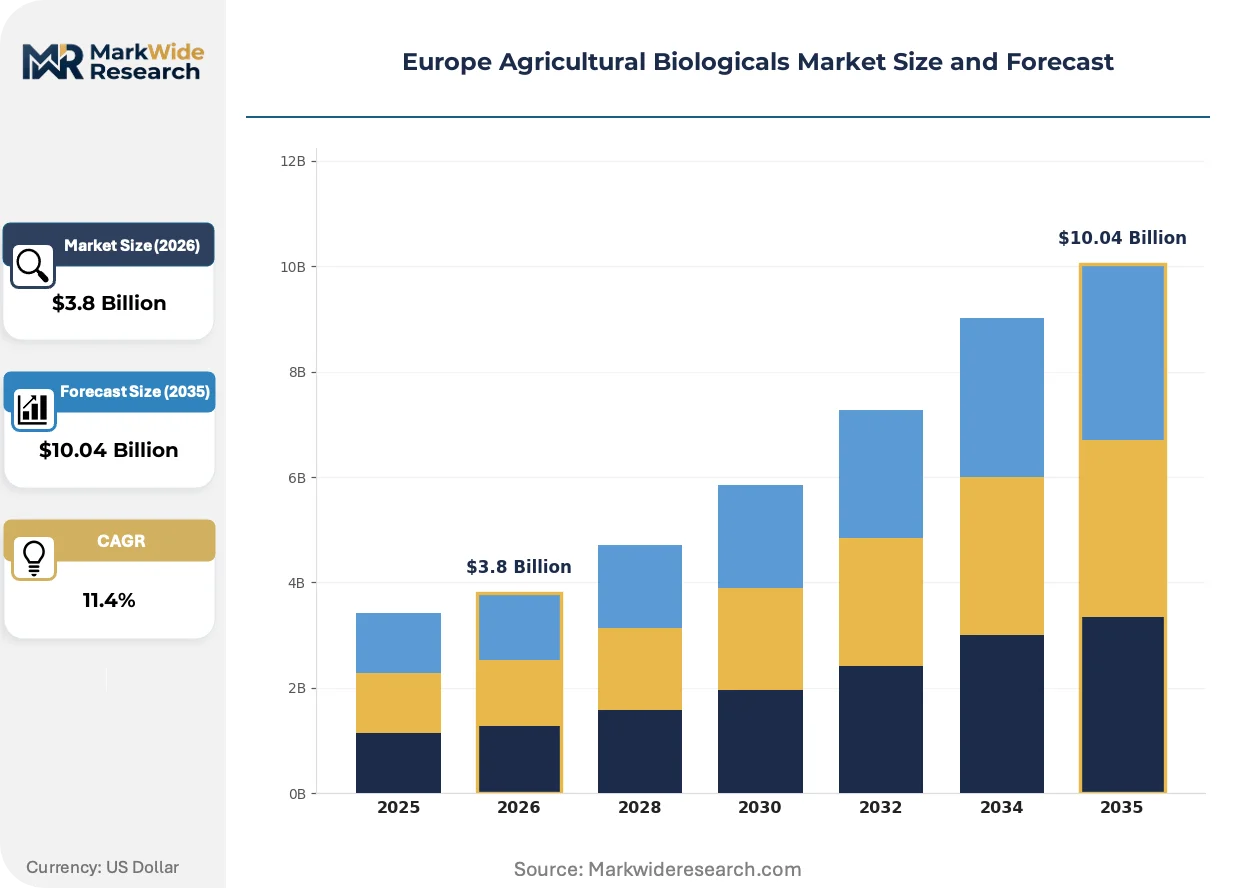
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopesticides, Biofungicides, Biofertilizers, Biostimulants Application: Crop Protection, Soil Health, Crop Nutrition, Seed Treatment End Use Industry: Cereals, Fruits, Vegetables, Oilseeds Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Koppert Biological Systems, Novozymes A/S, UPL Limited, Biolchim S.p.A., Agronutrition SAS, Symborg Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Biologicals Market Trends and Innovations
Biological input formats are converging with digital agriculture infrastructure, creating integrated systems where microbial efficacy depends on precision application timing rather than standalone product performance.
Microbial consortia engineering is miniaturizing. Researchers at Wageningen University and Research are developing synthetic communities of 3-5 compatible bacterial strains that colonize crop rhizospheres more aggressively than single-species inoculants. Dutch glasshouse tomato growers are piloting these engineered consortia in substrate-based systems. The technology is miniaturizing production bioreactor requirements from industrial-scale stainless steel tanks to modular 1,000-liter disposable bag systems that reduce capital intensity for regional manufacturers.
REACH framework amendments for microbial active substances are tightening data requirements on environmental fate and non-target organism impacts. ECHA guidance documents now mandate extended soil persistence studies for novel biocontrol bacteria. French national regulators enforce additional field efficacy trials under ANSM protocols that extend commercialization lead times but strengthen farmer confidence in labeled performance claims. Spanish authorities align with these standards while maintaining accelerated review tracks for products addressing listed quarantine pests.
Specialty crop buyers are consolidating procurement authority through cooperative purchasing organizations that negotiate biological input supply contracts on behalf of member growers. Italian fruit and vegetable cooperatives in Emilia-Romagna now aggregate demand across 15,000 hectares for centralized biocontrol sourcing. These purchasing bodies are displacing traditional distributor relationships and demanding outcome-based performance guarantees rather than product-centric transactions. France's cooperative network demonstrates similar concentration, with InVivo Group subsidiaries controlling biological input selection for member farms.
Europe Agricultural Biologicals Market Segmentation
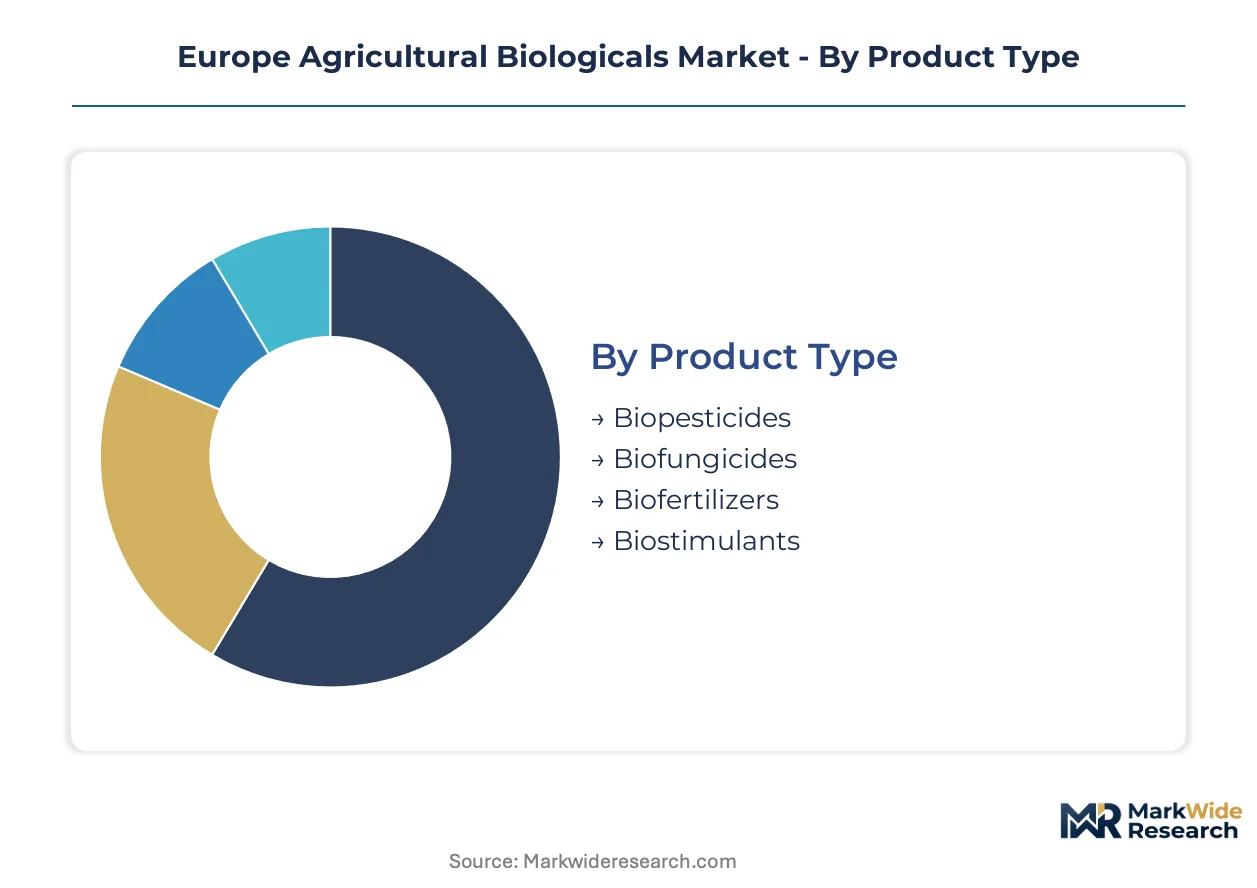
Biological input purchasing in Europe fragments across product formats, application methods, and crop-specific protocols. Segmentation reveals where substitution economics favor biocontrol over synthetic chemistry and which distribution pathways concentrate procurement power.
Product Type:
Biopesticides face the steepest substitution pressure as EU Green Deal timelines force synthetic chemical displacement in Mediterranean horticulture clusters.
- Biopesticides:These biocontrol agents derived from living organisms or natural compounds target specific pest populations through modes including antibiosis and mycoparasitism. Almeria's greenhouse vegetable operators now specify predator mite releases as standard protocol, driven by supermarket residue requirements that exclude synthetic alternatives.
- Biostimulants:Formulations containing humic acids, seaweed extracts, and microbial metabolites enhance nutrient uptake efficiency without direct fertilization. Dutch glasshouse tomato growers in Westland cluster deploy these concentrates through drip irrigation systems to maintain yield parity during synthetic fertilizer reduction transitions.
- Biofertilizers:Nitrogen-fixing rhizobia and phosphate-solubilizing bacteria inoculants reduce synthetic fertilizer dependency in Eastern European cereal production.
- Biofungicides:Trichoderma and Bacillus-based formulations suppress soil-borne pathogens through competitive exclusion and induced systemic resistance mechanisms.
Biopesticides retain volume leadership; biostimulants hold the steepest expansion curve.
Application:
Application format selection tracks cold-chain infrastructure density, with live microbial viability requirements concentrating certain formats in Netherlands and Germany.
- Crop Protection:Foliar sprays and soil drenches deploying entomopathogenic fungi and baculoviruses defend against lepidopteran pests and aphid vectors. French vineyard operators in Bordeaux region integrate these applications into powdery mildew management programs under ANSM efficacy verification protocols.
- Seed Treatment:Polymer-encapsulated microbial inoculants protect rhizobia through germination stress periods, expanding addressable market for regional manufacturers using modular 1,000-liter disposable bag bioreactor systems.
- Soil Health:Mycorrhizal inoculants and compost teas restore microbial community diversity in intensive arable rotations.
- Crop Nutrition:Foliar-applied microbial consortia enhance nitrogen mineralization rates in substrate-based cultivation systems.
Crop protection commands current deployment share; seed treatment formats gain structural share as coating technologies mature.
End Use Industry:
Crop value per hectare determines biological input economics, with high-value horticulture outpacing arable adoption rates.
- Vegetables:Intensive greenhouse production under plastic in Spain's Almeria province and Italy's Po Valley generates concentrated demand for integrated pest management protocols. Italian cooperatives in Emilia-Romagna aggregate procurement across 15,000 hectares for centralized biocontrol sourcing.
- Fruits:Orchard and vineyard applications in France and Italy emphasize residue-free certification for export market access. French cooperative networks through InVivo Group subsidiaries control biological input selection for member farms.
- Cereals:Large-scale arable rotations in Poland and Romania remain underpenetrated, presenting expansion territory for nitrogen-fixing seed treatments.
- Oilseeds:Rapeseed and sunflower producers deploy biocontrol against pollen beetle and sclerotinia stem rot pressures.
Vegetables anchor biological adoption intensity; cereals present the widest penetration gap.
Distribution Channel:
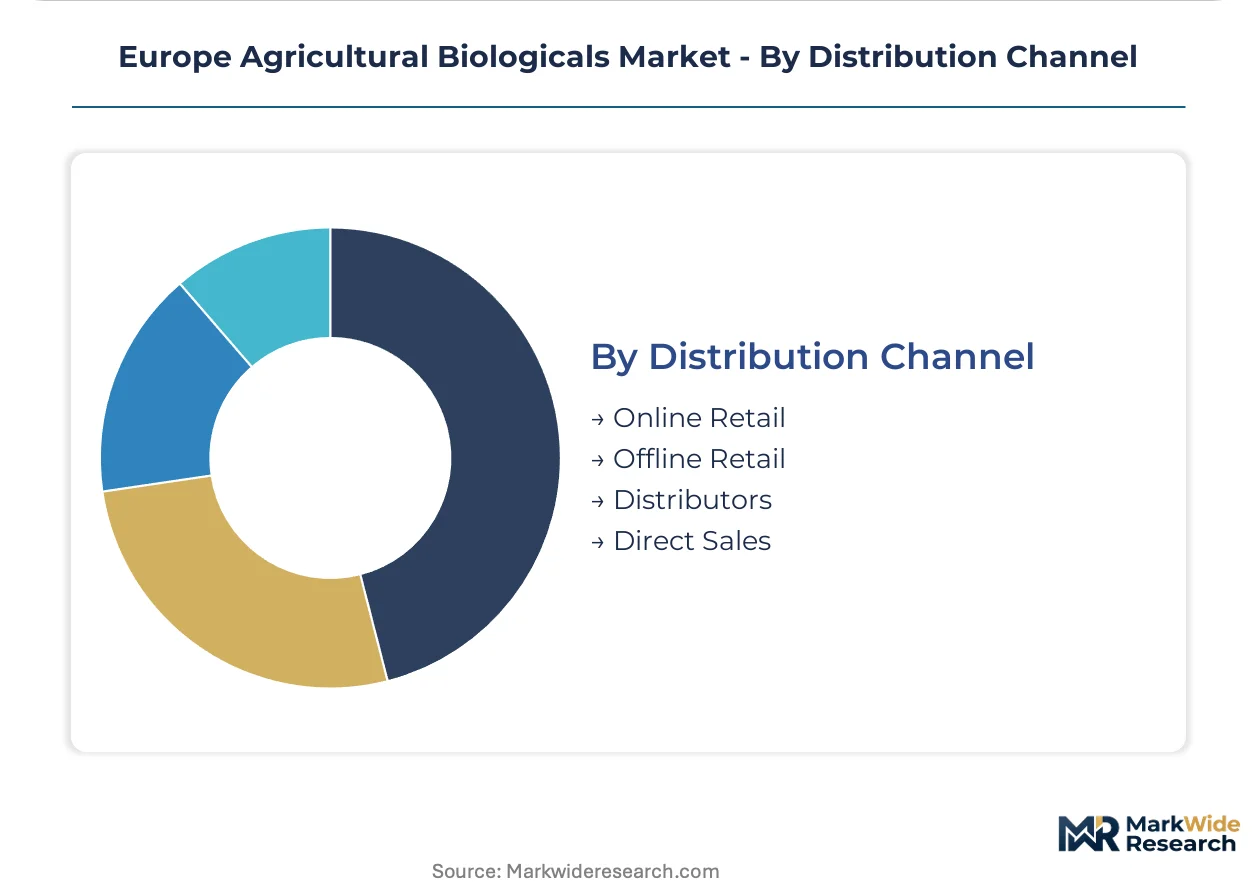
Channel selection reflects grower scale and technical support requirements, with cooperative purchasing displacing traditional distributor relationships.
- Distributors:Regional agrochemical distributors maintain biological input portfolios alongside synthetic chemistry, offering technical advisory services for transition protocols. These intermediaries face margin compression as cooperative purchasing bodies consolidate procurement authority.
- Direct Sales:Large-scale greenhouse operators and cooperative networks negotiate supply contracts directly with manufacturers, demanding outcome-based performance guarantees rather than product-centric transactions.
- Offline Retail:Farm supply stores and agricultural cooperatives serve smaller-scale producers with standardized product ranges.
- Online Retail:E-commerce platforms emerge for specialty biostimulant concentrates and small-volume biocontrol products.
Distributors retain transaction volume leadership; direct sales channels expand most quickly among large-scale operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biological input trade flows across Europe concentrate in Mediterranean export corridors serving Northern European retail markets, with Dutch logistics hubs mediating cold-chain distribution for live microbial products. Import dependency for specialized biocontrol agents runs highest in Eastern European cereal zones lacking domestic fermentation capacity.
Spain
Almeria's 30,000 hectares of intensive greenhouse vegetable production under plastic anchors biological adoption intensity. ANSM-aligned efficacy protocols govern biocontrol product registration, extending commercialization timelines while strengthening grower confidence. The Andalusian horticulture cluster converts rapidly to integrated pest management specifications that mandate predator mite releases for residue-free supermarket supply contracts.
Netherlands
Specialized predator mite production networks serve Dutch glasshouse operators across the Westland cluster. The country's national agricultural regulator enforces strict colony-forming unit thresholds for live microbial viability. Wageningen University and Research drives synthetic community engineering for substrate-based tomato cultivation, miniaturizing bioreactor requirements for regional manufacturers.
France
Bordeaux vineyard operators integrate entomopathogenic fungi into powdery mildew management under ANSM field efficacy verification protocols. InVivo Group cooperative subsidiaries control biological input selection for member farms across the national network. The EU Green Deal's Farm to Fork pesticide reduction targets accelerate substitution timelines in high-value export-oriented viticulture.
Italy
Emilia-Romagna fruit and vegetable cooperatives aggregate procurement across 15,000 hectares for centralized biocontrol sourcing. EU 2018/848 organic certification updates require revised input verification protocols that extend re-certification cycles. The Po Valley intensive horticulture belt generates concentrated demand for biostimulant concentrates deployed through drip irrigation systems.
Poland
Eastern European cereal and oilseed producers remain underpenetrated by biologicals, presenting first-mover expansion territory for nitrogen-fixing seed treatments. EFSA registration timelines for novel active substances extend 24-36 months, delaying commercialization. Large-scale arable rotations in the country's agricultural heartland lack cold-chain infrastructure density for live microbial distribution.
Europe Agricultural Biologicals Market Competitive Landscape
Concentration sits with diversified agrochemical conglomerates leveraging formulation science heritage to sustain premium positioning in biostimulant concentrates. The vendor base spans three tiers: global integrated players with seed-to-shelf portfolios, specialized biological producers with captive fermentation assets, and regional distributors consolidating procurement authority through cooperative purchasing organizations. Dominant competitive moves include M&A targeting microbial strain libraries and strategic partnerships pairing biological inputs with precision agriculture platforms.
Within the specialized biological tier, Koppert Biological Systems and Novozymes A/S exemplify divergent archetypes. Koppert anchors dominance through dedicated predator mite production networks serving protected cultivation systems. Novozymes occupies a position at the technical frontier of enzyme-based biostimulant platforms. BASF SE represents the integrated conglomerate archetype, leveraging formulation capabilities developed across synthetic and biological portfolios. These three entities illustrate how competitive positioning fragments across production technology specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Koppert Biological Systems |
| Novozymes A/S |
| UPL Limited |
| Biolchim S.p.A. |
| Agronutrition SAS |
| Symborg Inc. |
| Others |
Pricing and Supply Chain Analysis
EU 2018/848 organic certification protocols gate both supplier qualification and price differentiation simultaneously, mandating third-party audit trails that inflate production costs while enabling premium positioning for verified biological inputs. Supermarket residue requirements in Northern European retail chains further stratify procurement tiers, concentrating pricing power with growers who can document cold-chain integrity from fermentation to field application.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade markups for EU-registered biocontrol agents with validated efficacy data under EFSA protocols, while standard tiers serve conventional greenhouse operators with unverified biostimulant concentrates. Price differentiation hinges on organic certification tier and volume scale, with cooperative purchasing bodies extracting steep discounts through aggregated offtake. Pricing pressure stems from EFSA registration timelines that freeze R&D capital in regulatory queues, compressing margins for mid-tier manufacturers. Small-scale arable producers in Eastern Europe exhibit highest price sensitivity, whereas Dutch glasshouse operators in the Westland cluster prioritize performance guarantees over unit cost.
Supply Chain Analysis
Cold-chain infrastructure chokepoints in live microbial distribution concentrate supply capability in the Netherlands and Germany, limiting peripheral market access for Almeria greenhouse operators and Polish cereal producers. Axenic fermentation capacity draws from specialized production networks in the Netherlands, France, and Spain, with polymer encapsulation inputs for seed coating technologies sourced from German chemical suppliers. Single-source vulnerability runs through Dutch predator mite production networks serving protected cultivation systems. Distribution runs through cooperative purchasing organizations that displace traditional agrochemical distributors, with InVivo Group subsidiaries and Italian Emilia-Romagna cooperatives consolidating procurement authority across member farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Agricultural Biologicals Market functions as a regulatory entrenchment story, where EFSA registration requirements and EU 2018/848 certification protocols create switching costs that cement incumbent positions while raising barriers for unvalidated alternatives.
For Market Incumbents: Secure captive fermentation capacity through backward integration into axenic production infrastructure, particularly in the Netherlands where specialized microbiologist talent concentrates. Extend commercialization lead times into competitive advantage by accelerating ANSM-aligned field efficacy trials that strengthen grower confidence. The threat of modular 1,000-liter disposable bag bioreactor systems enabling regional manufacturer entry demands preemptive capacity addition in Spain and Italy. Certification investment in EU 2018/848 organic input verification protocols remains the critical lever for margin defense. For New Entrants and Emerging Players: Lead with nitrogen-fixing seed treatments targeting underpenetrated Polish and Romanian arable rotations, where large-scale cereal producers lack cold-chain infrastructure for live microbial alternatives. The most penetrable segment sits with Eastern European oilseed growers seeking synthetic fertilizer displacement under EU Green Deal timelines. A go-to-market angle pairing phosphate-solubilizing bacteria with drone-mounted multispectral imaging addresses precision agriculture demand emerging under EU AI Act classification criteria. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microbial consortia engineering, where Wageningen University research miniaturizes production bioreactor requirements from industrial-scale tanks to modular systems. Long-term viability in the biological input space rests on acquisition targets possessing captive strain libraries and established registration dossiers with EFSA. The signal to watch is consolidation velocity among Italian and French cooperative purchasing bodies, as centralized procurement authority reshapes downstream channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Strain Library Acquisition | Captive biodiversity assets accelerate EFSA registration pathways for novel biocontrol agents. |
| Precision Agriculture Platform Partnership | Drone-mounted multispectral imaging integration meets EU AI Act criteria for sensor-driven application timing. |
| Cold-Chain Infrastructure Expansion | Peripheral market access in Poland and Romania unlocks Eastern European cereal penetration. |
| Cooperative Procurement Consolidation | Direct supply contracts with InVivo Group and Emilia-Romagna cooperatives displace distributor intermediaries. |
| Modular Bioreactor Deployment | 1,000-liter disposable bag systems reduce capital intensity for regional manufacturers competing with Dutch incumbents. |
Research Methodology
Initial hypotheses were tested against primary input from biocontrol product managers, greenhouse operations directors at Almeria and Westland clusters, EFSA regulatory affairs specialists, and cooperative procurement officers at InVivo Group subsidiaries, then refined through secondary validation. Bottom-up and top-down triangulation combined interview insights with EFSA active substance registration databases, EU customs trade data for biological input flows, ANSM field trial disclosure records, and REACH framework amendment tracking documents.
Variance decomposition across the projection horizon isolates drivers by product type, application format, crop-specific protocol, and distribution channel concentration. Segmentation dimensions modeled include biocontrol agent category, live versus derived metabolite formulation, protected versus open-field cultivation system, and cooperative versus distributor procurement pathway. CAGRs were synthesized from adoption curve analysis in Mediterranean horticulture clusters and penetration rate projections in Eastern European arable zones, with nitrogen mineralization enhancement technologies and polymer encapsulation survival rates as key forecast inputs.
Forecasts assume regulatory continuity in EFSA evaluation protocols and EU 2018/848 organic certification regimes; material policy shifts in Farm to Fork pesticide reduction targets or REACH microbial active substance amendments would require re-modeling. Practitioners should keep alternative scenarios live as EU AI Act precision agriculture classification criteria and Eastern European cold-chain infrastructure buildouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Brazil Agricultural Biologicals Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market