
 Global Computational Biology Market | 2026-2036
Global Computational Biology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computational Biology Market Foresight
GPU-accelerated silicon is pivoting computational biology away from CPU-dependent architectures, slashing time-to-insight for molecular dynamics simulations. Thermo Fisher Scientific leverages integrated instrument-software workflows to dominate high-throughput sequencing analytics. Illumina sustains technology leadership in genomic data generation, anchoring downstream computational demand. Schrödinger specializes in physics-based molecular modeling, differentiating through proprietary force-field algorithms.
Computational biology applies mathematical modeling, statistical methods, and algorithmic analysis to interpret complex biological datasets, typically processing petabyte-scale genomic, proteomic, and metabolomic information through parallelized machine-learning pipelines. Its primary commercial purpose is accelerating therapeutic target identification and reducing preclinical failure rates in pharmaceutical development. Structural modeling software and systems biology platforms capture concentrated margin pools as pharmaceutical companies demand mechanistic insights beyond correlative pattern detection. Cloud-based solutions represent the fastest-expanding deployment mode as elastic compute resources eliminate capital-intensive cluster procurement for biotech startups.
FDA validation requirements for computational drug-discovery tools shape product development roadmaps, while EMA's evolving guidance on AI-enabled biomarker qualification creates compliance complexity for European market entry. China's NMPA and national GB standards for bioinformatics software security impose localization mandates on foreign platform vendors. Stakeholders must monitor divergence between FDA, EMA, and NMPA evidentiary standards for in-silico trial submissions as regulatory fragmentation threatens to segment the addressable market by jurisdiction.
Market Dynamics
GPU-accelerated molecular simulation architectures are compressing preclinical timelines from months to days, forcing pharmaceutical R&D procurement to abandon CPU-centric compute clusters. Cloud-native bioinformatics pipelines now dominate capital planning discussions at biotech firms.
Growth Catalysts
- Precision Therapeutics Mandate:FDA's 2023 guidance on in-silico clinical trial validation validates computational models as evidentiary substitutes for animal studies, accelerating regulatory acceptance of simulation-based submissions.
- Genomic Data Proliferation:CRISPR-edited cell line generation has created petabyte-scale functional genomics datasets that demand algorithmic interpretation beyond manual curation capacity.
- Elastic Cloud Infrastructure:Amazon Web Services and Google Cloud Platform have built HIPAA-compliant bioinformatics environments that eliminate on-premises cluster procurement for emerging biotech startups.
Market Restraints
- Specialized Talent Scarcity:The intersection of computational physics and molecular biology requires hybrid PhD-level expertise concentrated at MIT, Stanford, and ETH Zurich, constraining workforce scaling.
- Data Sovereignty Fragmentation:China's GB/T 35273 personal information security standard and GDPR's health data provisions create jurisdictional silos that prevent cross-border genomic dataset federation.
- Force-Field Licensing Costs:Proprietary molecular mechanics parameter sets from academic institutions impose per-simulation royalties that accumulate rapidly at pharmaceutical scale.
Strategic Opportunities
- Underpenetrated Oncology Biomarker Space:Liquid biopsy circulating tumor DNA analysis in India remains below 5% penetration, creating first-mover advantage for cloud-deployed variant calling pipelines.
- AI-Drug Discovery Convergence:Deep learning architectures trained on AlphaFold structural predictions enable de novo protein design applications previously inaccessible to small-molecule specialists.
- Japan's PMDA Computational Validation Pathway:METI's 2024 initiative to recognize foreign in-silico trial data opens streamlined market entry for validated simulation platforms.
Industry Challenges
- Cross-Disciplinary Recruitment Friction:Bioinformatics teams struggle to retain machine learning engineers who command 40% salary premiums in technology sector alternatives.
- Legacy LIMS Integration Complexity:Pharmaceutical quality systems built on 1990s-era laboratory information management architectures resist API-based connectivity with modern cloud analytics environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computational Biology Market |
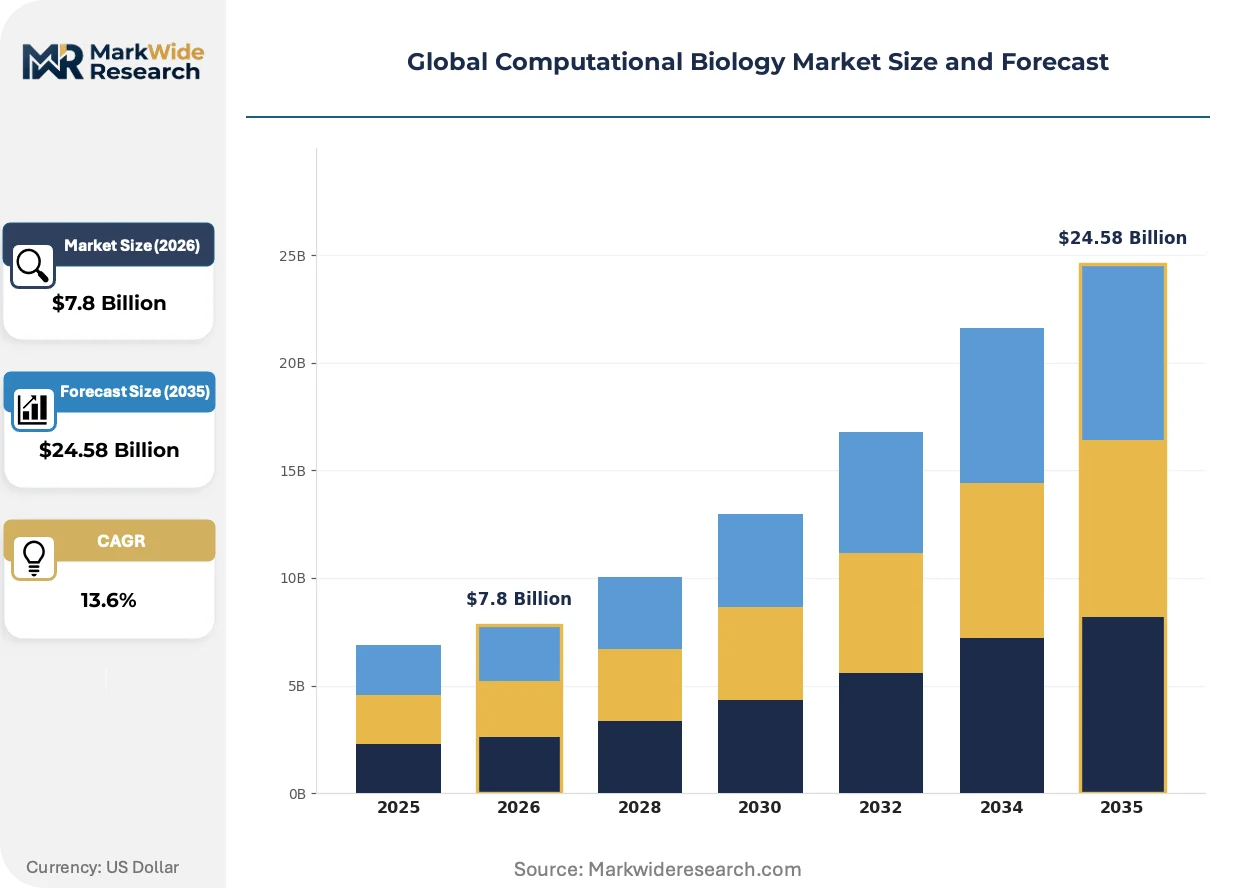
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequence Analysis Tools, Structural Modeling Software, Systems Biology Platforms, Genomic Data Analytics, Proteomics Software Application: Drug Discovery, Biomarker Identification, Personalized Medicine, Disease Modeling, Agricultural Biotechnology End User: Pharmaceutical Companies, Academic Institutions, Biotech Startups, Research Laboratories, Government Agencies Deployment: Cloud-Based Solutions, On-Premises Platforms, Hybrid Deployment, Software-as-a-Service, High-Performance Computing Clusters |
| Companies Covered | Thermo Fisher Scientific, Illumina, QIAGEN, Dassault Systèmes, Certara, Genedata AG, Schrödinger, DNAnexus, Compugen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computational Biology Market Shifts & Advancements
Quantum-classical hybrid algorithms are entering early commercial deployment for protein folding problems, while federated learning architectures address data-sharing constraints. These developments are compressing the gap between raw genomic output and actionable therapeutic hypothesis.
Neuromorphic computing chips designed for spiking neural networks are rewriting energy efficiency standards for molecular dynamics simulations. Sanofi and Roche have piloted IBM's NorthP architecture for all-atom membrane protein modeling, cutting kilowatt-hour costs by orders of magnitude versus GPU farms. This efficiency gain is rewriting total cost of ownership calculations for sustained simulation campaigns.
EMA's 2024 qualification opinion on AI-enabled biomarker discovery establishes evidentiary requirements for machine learning models in regulatory submissions. The framework mandates algorithmic transparency and locked training datasets, forcing computational biology vendors to rearchitect black-box architectures into interpretable pipelines. European pharmaceutical sponsors now face 18-24 month qualification timelines that lag FDA's more permissive model-informed drug development pathway.
Biotech procurement teams are unbundling software licenses from sequencing instrument contracts, reversing Illumina's decade-long integrated pricing strategy. Third-party analysis platforms from specialized vendors now win standalone evaluations based on multi-omics integration capabilities rather than hardware bundling. This behavioral shift concentrates most visibly in Cambridge, Massachusetts and South San Francisco, where venture-backed startups prioritize interoperability over single-vendor ecosystems.
Global Computational Biology Market Segmentation
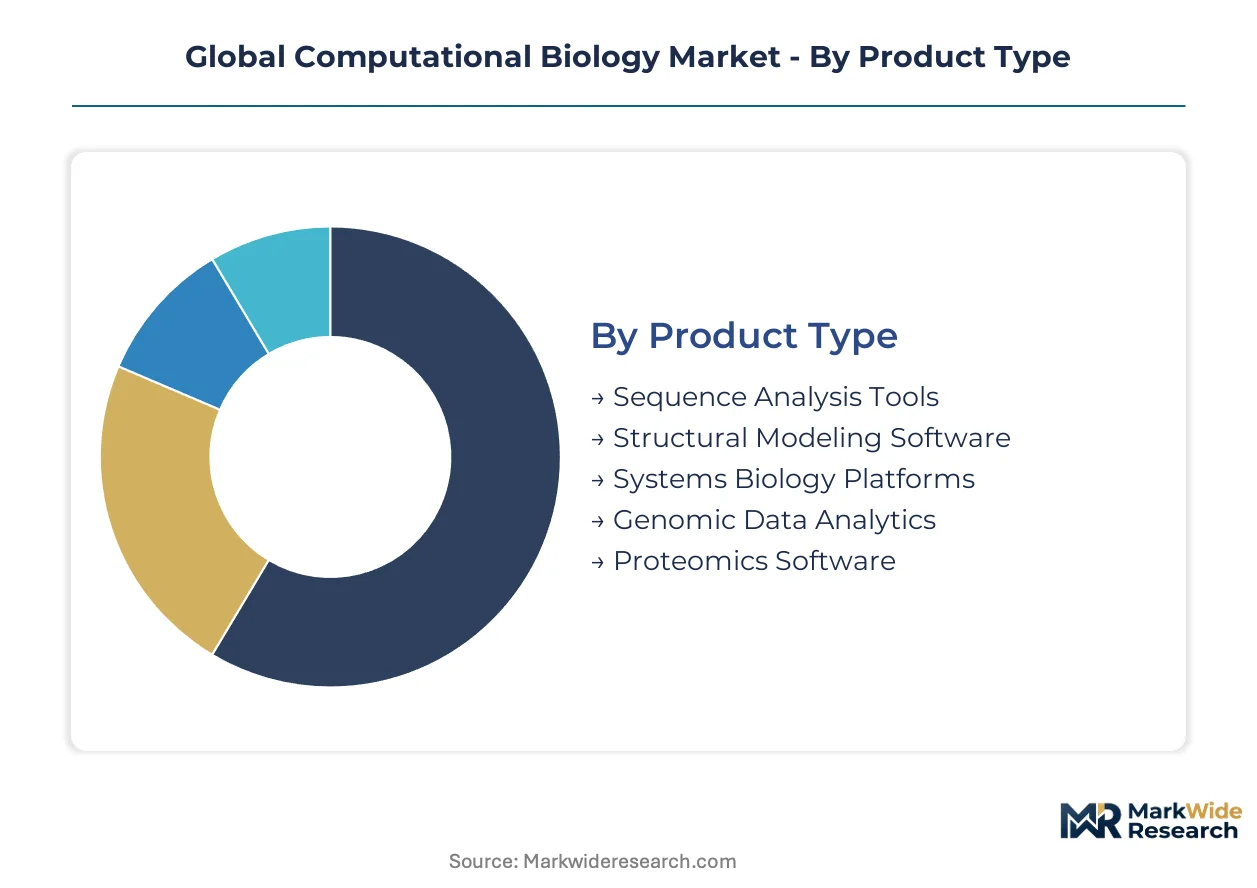
Computational biology vendors architect product roadmaps around distinct capability layers. Each segmentation axis reveals divergent margin structures and procurement patterns across pharmaceutical, academic, and government buyers.
Product Type:
Technical sophistication varies sharply across functional modules, with physics-based engines commanding premium licensing against statistical toolkits.
- Sequence Analysis Tools:Algorithms for genome assembly, variant calling, and phylogenetic reconstruction process raw sequencing output into annotated datasets. Demand clusters at Broad Institute, BGI Genomics, and Wellcome Sanger Institute where petabyte-scale population genomics projects require distributed computing architectures.
- Structural Modeling Software:Physics-based molecular mechanics and quantum chemistry simulations predict protein-ligand binding affinities and conformational dynamics. Roche, Novartis, and Sanofi procurement teams prioritize these platforms for lead optimization campaigns where mechanistic accuracy reduces late-stage attrition.
- Systems Biology Platforms:Integrative modeling environments connect multi-omics datasets through network inference and kinetic simulation.
- Genomic Data Analytics:Population-scale GWAS pipelines and polygenic risk score calculators.
- Proteomics Software:Mass spectrometry data processing for protein quantification and post-translational modification mapping.
Mature deployment sits with Sequence Analysis Tools. Newer deployment is concentrated in Structural Modeling Software.
Application:
Commercial value accrues unevenly across therapeutic development stages, with target-to-hit phases absorbing disproportionate software spend.
- Drug Discovery:Virtual screening, de novo molecular design, and ADMET prediction compress discovery timelines. Pfizer, AstraZeneca, and Merck & Co. have established dedicated computational chemistry units with annual platform budgets exceeding instrument procurement allocations.
- Biomarker Identification:Machine learning classifiers trained on multi-omics signatures stratify patient populations for precision trial design. Foundation Medicine and Tempus have built proprietary pipelines that pharmaceutical partners license for companion diagnostic co-development.
- Personalized Medicine:Clinical decision support algorithms match oncogenic variants to approved therapies.
- Disease Modeling:In-silico patient cohorts and organoid simulation for mechanism elucidation.
- Agricultural Biotechnology:Crop trait prediction and gene editing target selection.
Revenue concentration favors Drug Discovery. Steepest expansion trajectory appears in Biomarker Identification.
End User:
Procurement authority and evaluation criteria diverge fundamentally between profit-driven pharmaceutical sponsors and grant-funded academic centers.
- Pharmaceutical Companies:Enterprise licensing agreements with vendor-managed infrastructure and dedicated support tiers. Johnson & Johnson, Takeda, and Boehringer Ingelheim negotiate multi-year contracts bundling software, compute credits, and professional services.
- Academic Institutions:Grant-funded, open-source-preferred procurement with heavy reliance on NIH, Wellcome Trust, and European Research Council infrastructure allocations. MIT, Stanford, and ETH Zurich maintain internal high-performance computing clusters with customized bioinformatics pipelines.
- Biotech Startups:Cloud-first, consumption-based pricing with minimal capital commitment.
- Research Laboratories:CRO and CDMO facilities offering computational services to sponsor companies.
- Government Agencies:National health institutes and defense biodefense programs.
Contract value peaks with Pharmaceutical Companies. User growth is climbing the fastest among Biotech Startups.
Deployment:
Infrastructure economics and data sovereignty requirements shape architectural choices across regulated and exploratory research environments.
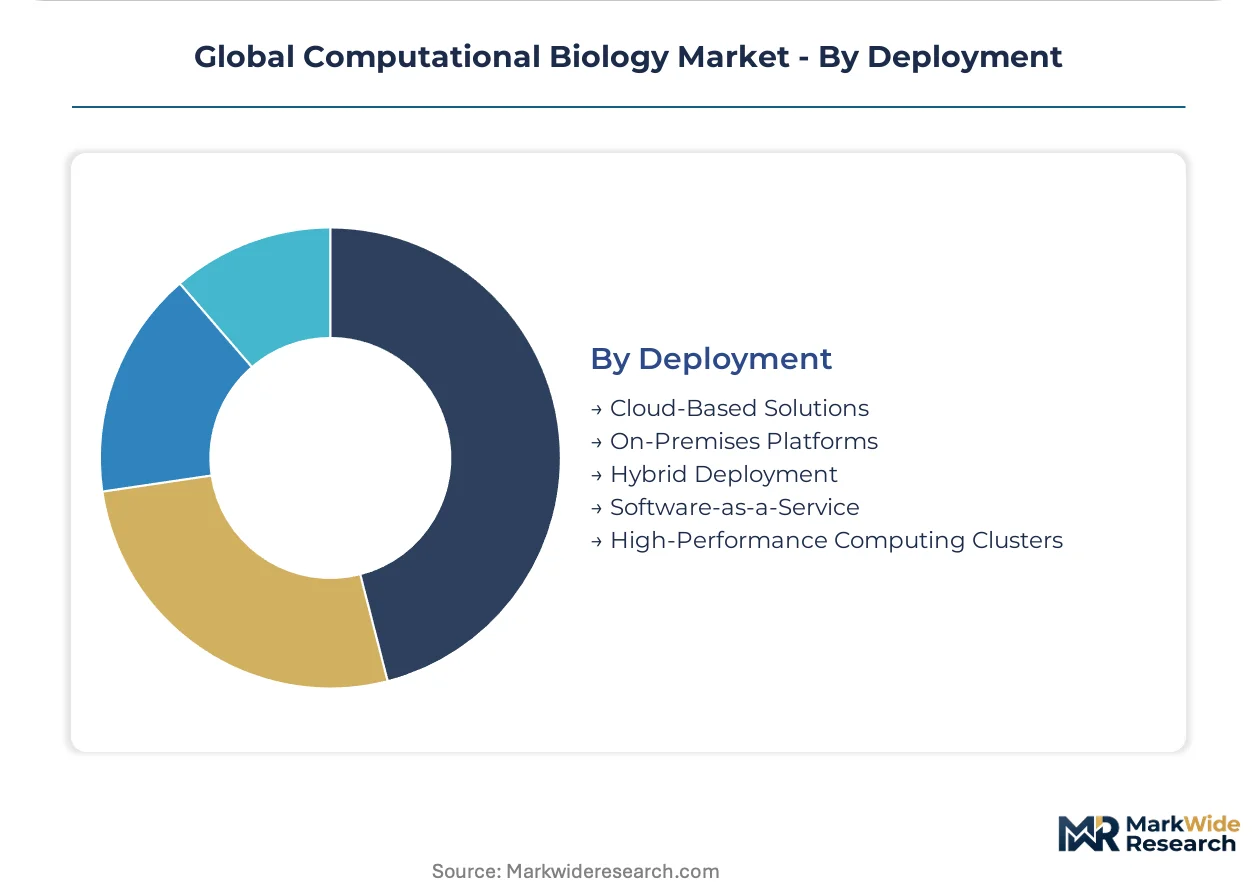
- Cloud-Based Solutions:Elastic compute provisioning through AWS, Google Cloud, and Azure with HIPAA and GDPR-compliant environments. Recursion Pharmaceuticals and Insitro have built entirely cloud-native discovery stacks eliminating on-premises capital expenditure.
- On-Premises Platforms:Air-gapped clusters for classified biodefense research and proprietary dataset protection. Lawrence Livermore National Laboratory and Porton Down maintain sovereign infrastructure for pathogen genomics.
- Hybrid Deployment:Sensitive primary analysis on-premises with anonymized secondary analysis in cloud.
- Software-as-a-Service:Browser-accessible platforms with subscription metering.
- High-Performance Computing Clusters:Dedicated GPU and neuromorphic silicon arrays for sustained simulation campaigns.
Legacy dominance persists with On-Premises Platforms. Capability investment is concentrating in Cloud-Based Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement authority concentrates in the United States, Germany, and China as national health agencies deepen bioinformatics infrastructure investment. Cloud-based deployment architectures displace legacy on-premises installations across research hubs in these markets.
United States
FDA's 2023 guidance on in-silico clinical trial validation accelerates regulatory acceptance of simulation-based submissions. NIH infrastructure allocations sustain academic cluster procurement at MIT, Stanford, and Broad Institute. Greater Boston and South San Francisco biotech clusters drive cloud-native platform adoption among venture-backed startups.
Germany
EMA qualification opinions on AI-enabled biomarker discovery create compliance complexity for simulation platform vendors. The country's pharmaceutical regulator mandates algorithmic transparency and locked training datasets for machine learning submissions. Heidelberg and Munich research centers maintain hybrid deployment architectures balancing data sovereignty with elastic compute needs.
China
NMPA and national GB standards for bioinformatics software security impose localization mandates on foreign platform vendors. The country's dual carbon goals accelerate neuromorphic computing pilot programs for energy-efficient molecular dynamics. Beijing-Tianjing-Hebei and Yangtze River Delta clusters concentrate domestic sequencing analytics demand.
Japan
METI's 2024 initiative to recognize foreign in-silico trial data opens streamlined market entry for validated simulation platforms. PMDA computational validation pathways attract pharmaceutical sponsors seeking regulatory efficiency. Kanto and Kansai pharmaceutical corridors deepen integration with cloud-based discovery stacks.
United Kingdom
Wellcome Trust infrastructure allocations sustain open-source-preferred procurement at Sanger Institute and Crick Institute. GDPR health data provisions constrain cross-border genomic dataset federation with European partners. London-Oxford-Cambridge golden triangle concentrates structural modeling software demand for lead optimization campaigns.
Global Computational Biology Market Competitive Landscape
Strategic partnerships dominate the current landscape as specialized vendors seek compute infrastructure and distribution scale. The vendor base organizes around three tiers: integrated instrument-software conglomerates, pure-play simulation specialists, and cloud-native platform operators. Physics-based molecular mechanics vendors command premium licensing against statistical toolkits. Portfolio diversification and technology licensing represent the dominant competitive vectors as firms expand from single-capability modules to integrated discovery environments.
Within the integrated instrumentation tier, Thermo Fisher Scientific leverages consolidated instrument-software workflows to anchor high-throughput sequencing analytics demand. Illumina sustains technology leadership in genomic data generation, anchoring downstream computational demand through hardware-software bundling. Schrödinger occupies a specialist position in physics-based molecular modeling, differentiating through proprietary force-field algorithm licensing. These three exemplify divergent archetypes: Thermo Fisher represents vertical integration across the analytical stack, Illumina exemplifies hardware-coupled software distribution, and Schrödinger anchors the pure-play simulation segment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| QIAGEN |
| Dassault Systèmes |
| Certara |
| Genedata AG |
| Schrödinger |
| DNAnexus |
| Compugen |
| Others |
Supply & Pricing Matrix
GPU silicon costs cascade through computational biology pricing tiers, with NVIDIA A100 and H100 procurement expenses concentrating in cloud provider data centers before surfacing as per-simulation metering rates for pharmaceutical buyers. Elastic compute provisioning absorbs upstream hardware volatility into consumption-based SaaS contracts, while on-premises deployments bear capital expenditure exposure directly.
Pricing Analysis
Volume concentrates in sequence analysis tools where per-sample processing fees compress toward commodity levels, while margins concentrate in structural modeling software where physics-based force-field licensing commands premium tiers. Price differentiation separates validated FDA submission-grade platforms from exploratory research tiers, with algorithmic transparency requirements under EMA guidance adding compliance premiums for European market entry. Pricing pressure stems from cloud-native entrants undercutting legacy perpetual license models with usage-based alternatives. Biotech startups exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize mechanistic accuracy over unit cost in lead optimization campaigns.
Supply Chain Analysis
Specialized GPU manufacturing rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity in Taiwan and South Korea, with advanced packaging dependencies drawing from ASE Group and Amkor facilities. Proprietary molecular mechanics parameter sets source from academic institutions including University of California and ETH Zurich, while cloud infrastructure feeds from AWS, Google Cloud, and Azure data center networks. Single-source vulnerability concentrates in leading-edge semiconductor lithography equipment. Distribution runs through direct enterprise sales for pharmaceutical accounts and self-service marketplaces for emerging biotech users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational biology vendor consolidation is accelerating as regulatory qualification costs for FDA and EMA submission-grade platforms force subscale specialists toward strategic exits. Capital intensity for GPU cluster provisioning and compliance infrastructure creates winner-take-most dynamics favoring integrated platform operators.
For Market Incumbents: Anchor defensive positioning through exclusive force-field licensing agreements with academic institutions, locking proprietary molecular mechanics parameters that emerging competitors cannot replicate without royalty burdens. Pursue backward integration into neuromorphic computing hardware partnerships with IBM or Intel, securing preferential access to energy-efficient simulation architectures before cost advantages diffuse. Cloud-native entrants threaten traditional perpetual license revenue streams through consumption-based alternatives.
For New Entrants and Emerging Players: Enter via liquid biopsy variant calling pipelines in India, where oncology biomarker penetration sits below five percent and cloud-deployed solutions face minimal incumbent saturation. Target agricultural biotechnology applications in Brazil and Southeast Asia, where gene editing target selection demand outpaces specialized vendor supply. Pursue API-first integration strategies that unbundle from sequencing instrument contracts, capturing procurement attention at venture-backed startups in Cambridge and South San Francisco.
For Investors and Strategic Acquirers: PMDA computational validation pathway recognition for foreign in-silico trial data is the leading indicator that Japanese market entry barriers are compressing for validated simulation platforms. Five-to-ten year viability favors pure-play physics-based modeling specialists with proprietary algorithm portfolios over statistical toolkit vendors facing commoditization. Acquisition targets should demonstrate locked training datasets compliant with EMA algorithmic transparency mandates and established pharmaceutical sponsor relationships with multi-year contract visibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Force-Field Licensing Agreement | Proprietary molecular mechanics parameters from ETH Zurich or UC Berkeley lock competitive differentiation for pharmaceutical-scale simulations. |
| Neuromorphic Computing Partnership | IBM NorthP or Intel Loihi integration cuts kilowatt-hour costs for sustained membrane protein modeling campaigns at Sanofi-scale deployments. |
| API-First Platform Architecture | Interoperability with legacy LIMS systems addresses pharmaceutical quality system integration friction blocking cloud adoption. |
| FDA Submission-Grade Validation | In-silico clinical trial model qualification under FDA 2023 guidance enables evidentiary substitution for animal studies in IND packages. |
| EMA Algorithmic Transparency Compliance | Locked training datasets and interpretable pipeline architectures satisfy EMA 2024 qualification opinions for AI-enabled biomarker discovery. |
Research Methodology
Document review covered FDA guidance documents, EMA qualification opinions, NMPA GB standards, and ClinicalTrials.gov computational trial registrations, complemented by interviews with drug development executives, bioinformatics platform engineers, regulatory affairs leads at pharmaceutical sponsors, and cloud procurement officers at venture-backed biotech firms. Secondary validation drew from NIH infrastructure allocation reports, hyperscaler healthcare vertical disclosures, and SEC 10-K filings for publicly traded instrument-software conglomerates. Bottom-up triangulation across deployment mode, application segment, and end-user archetype reconciled with top-down market sizing from pharmaceutical R&D software budget proxies.
Segment-level outputs across product type, application, end user, and deployment architecture fed into analytical framework projections over the analysis window. CAGRs derived from elasticity modeling of pharmaceutical R&D spend allocation shifts toward in-silico methods, cloud infrastructure cost curves, and regulatory acceptance velocity for simulation-based submissions. Industry-specific inputs included GPU price-performance trajectories, force-field licensing royalty schedules, and EMA qualification timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios where FDA, EMA, and NMPA evidentiary standards diverge sharply. Forecasts reflect assumptions around cloud adoption velocity, neuromorphic computing commercialization timelines, and cross-border genomic data federation policy evolution. A small set of named triggers warrants ongoing watch: PMDA pathway expansion, China GB standard enforcement intensity, and pharmaceutical sponsor unbundling behavior from instrument-software contracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
Bioinformatics Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
China Computational Biology Market
Bioinformatics
South Korea Computational Biology Market