
 Research Antibodies and Reagents Market | 2026-2036
Research Antibodies and Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Research Antibodies and Reagents Market Intelligence
PhD-level protein chemist availability is bifurcating the competitive landscape between premium custom reagent houses and commoditized catalog suppliers. Thermo Fisher Scientific leverages its end-to-end workflow integration to sustain dominant positions in proteomics and flow cytometry reagent bundles. Danaher Corporation anchors its growth through analytical instrument-reagent consumable pairing across life science research platforms. Abcam plc differentiates via recombinant antibody validation rigor and digital distribution channels that compete with traditional field sales models.
Research antibodies and reagents comprise purified immunoglobulins, peptide antigens, and conjugated detection molecules manufactured through hybridoma culture, recombinant expression, or synthetic chemistry, typically characterized by specificity metrics, clone identity, and lot-to-lot consistency parameters that determine reproducibility in quantitative biological assays. These materials serve as binding and detection tools in target identification, biomarker quantification, and therapeutic mechanism studies across pharmaceutical and academic research workflows. Monoclonal antibodies command the largest product type value pool due to their defined specificity and renewable supply, while recombinant antibodies represent the fastest-growing category as validation standards tighten and animal-origin-free sourcing requirements spread. Drug discovery applications absorb the greatest reagent volume, though flow cytometry panels and immunohistochemistry-grade antibodies concentrate margin pools through technical complexity and customization requirements.
FDA bioanalytical guidance, EMA ICH Q2(R1) method validation standards, and ISO 13485 quality management frameworks collectively elevate reagent documentation, traceability, and performance verification burdens for suppliers seeking regulated market access. These compliance requirements favor incumbent manufacturers with dedicated regulatory affairs infrastructure and quality systems over smaller catalog distributors. Stakeholders must monitor evolving specificity disclosure mandates and cross-border reference standard harmonization initiatives that will reshape competitive qualification thresholds.
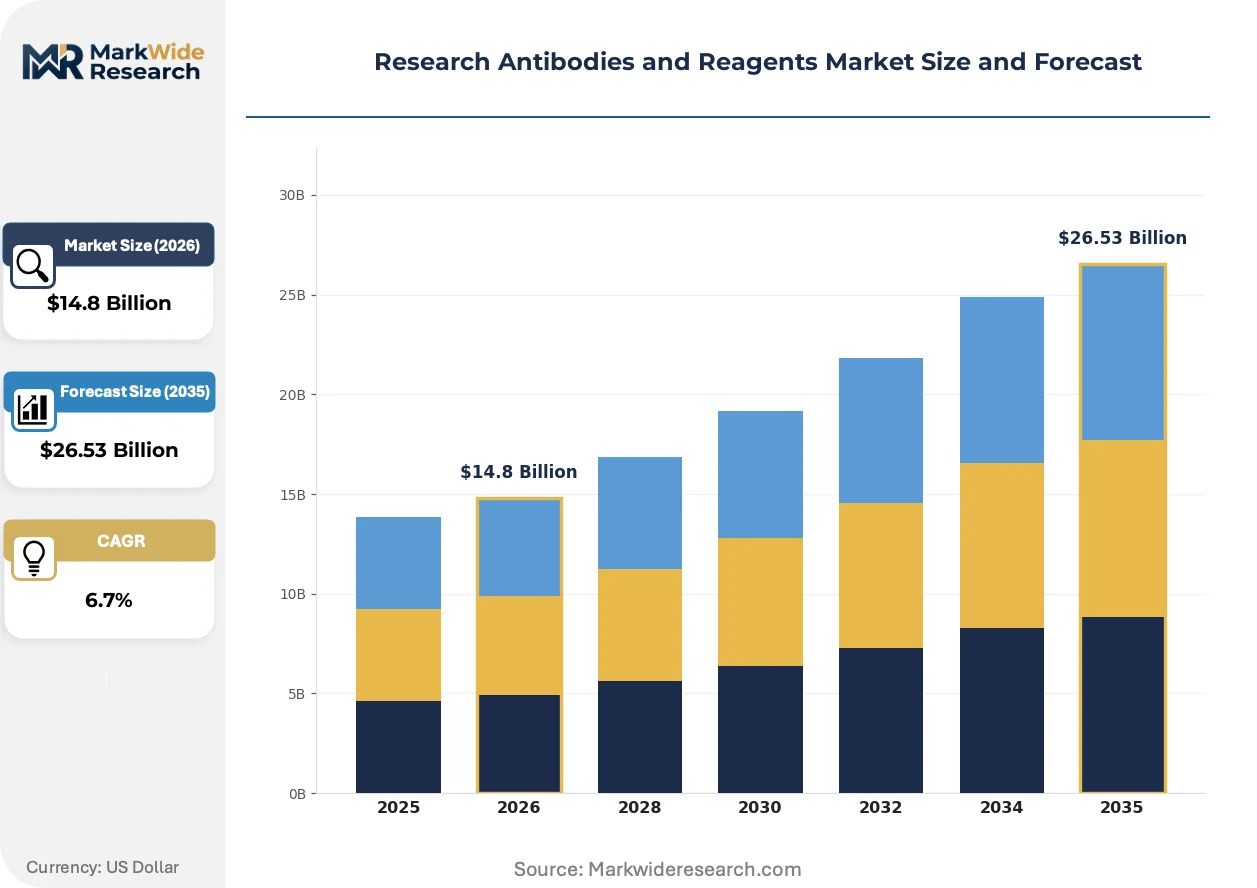
Market Dynamics
Recombinant antibody production is supplanting hybridoma-derived supply chains as validation standards tighten and pharmaceutical sponsors demand animal-origin-free documentation for IND-enabling studies.
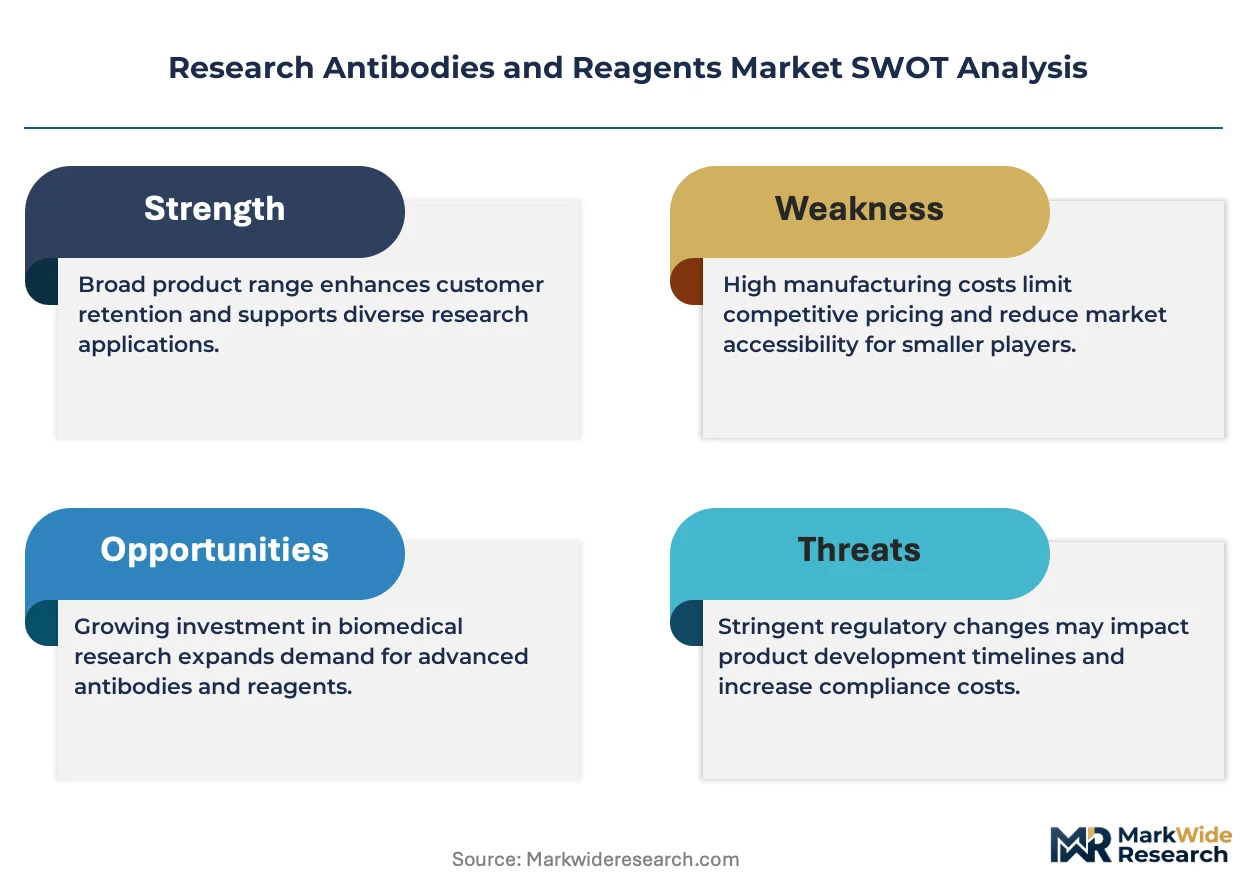
Growth Catalysts
- NIH funding cycles:Sustained federal research appropriations in the United States drive high-volume purchasing from academic medical centers and national laboratories.
- ICH Q2(R1) method validation standards:European regulatory harmonization elevates reagent qualification documentation requirements, favoring suppliers with dedicated quality infrastructure.
- Flow cytometry panel expansion:Multiplex biomarker quantification in immuno-oncology trials consumes specialized conjugated antibodies at accelerating rates.
Market Restraints
- Fetal bovine serum price volatility:Hybridoma culture media costs fluctuate with agricultural commodity markets and trade policy uncertainty.
- Chinese recombinant protein supply concentration:Contract manufacturing for antigen production clusters in Shanghai and Suzhou industrial zones, creating single-source vulnerability.
- Lot-to-lot reproducibility failures:Polyclonal antibody heterogeneity generates assay drift that invalidates longitudinal biomarker studies.
Strategic Opportunities
- India biotech corridor expansion:Hyderabad and Bengaluru research clusters remain underpenetrated by validated reagent distributors with local technical support.
- ISO 13485 certification:Diagnostic-grade antibody qualification opens regulated IVD companion diagnostic co-development pathways.
- Digital distribution platforms:Direct-to-laboratory e-commerce with searchable validation data is compressing traditional field sales cycles.
Industry Challenges
- PhD-level protein chemist scarcity:Custom reagent development houses compete for limited talent pools against pharmaceutical biologics divisions.
- Cross-reactivity litigation exposure:Antibody specificity failures in clinical biomarker assays generate product liability and reputational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Research Antibodies and Reagents Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Secondary Antibodies, Recombinant Antibodies, Peptides, Antibody Conjugates Application: Drug Discovery, Proteomics, Flow Cytometry, Immunohistochemistry, ELISA, Western Blotting End User: Biotechnology Firms, Pharmaceutical Companies, Academic Institutes, Research Laboratories, Contract Research Organizations Form: Liquid, Lyophilized, Powder, Ready-to-Use, Custom Formulations |
| Companies Covered | Bio-Rad Laboratories Inc., Santa Cruz Biotechnology Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche AG, Danaher Corporation, Merck KGaA, Cell Signaling Technology Inc., Becton Dickinson and Company, Abcam plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Research Antibodies and Reagents Market Strategic Shifts & Innovations
Validation rigor and digital procurement infrastructure are compressing traditional supply relationships while elevating technical performance thresholds across antibody sourcing decisions.
Rabbit monoclonal antibody technology is supplanting mouse-derived alternatives in phospho-specific and post-translational modification detection applications. Pharmaceutical translational medicine groups now specify rabbit clones for biomarker assay development. This shift is compressing market share for legacy murine hybridoma catalogs while rewarding suppliers with proprietary rabbit B-cell cloning platforms.
EMA's updated MDR guidance on in vitro diagnostic device performance evaluation extends traceability requirements to research-use-only antibodies destined for clinical trial assays. European CROs now demand extended stability data and manufacturing change notification protocols previously reserved for GMP materials. Reagent houses serving EU-sponsored oncology studies are restructuring quality systems to accommodate this documentation burden.
Consolidated buying through group purchasing organizations is fragmenting individual laboratory autonomy in antibody selection. Academic medical centers in Boston and San Francisco now mandate centralized procurement with pre-negotiated validation standards, displacing principal investigator-driven catalog diversity. This pattern concentrates volume with vendors offering enterprise-wide data management portals and lot-matching services.
Research Antibodies and Reagents Market Segmentation
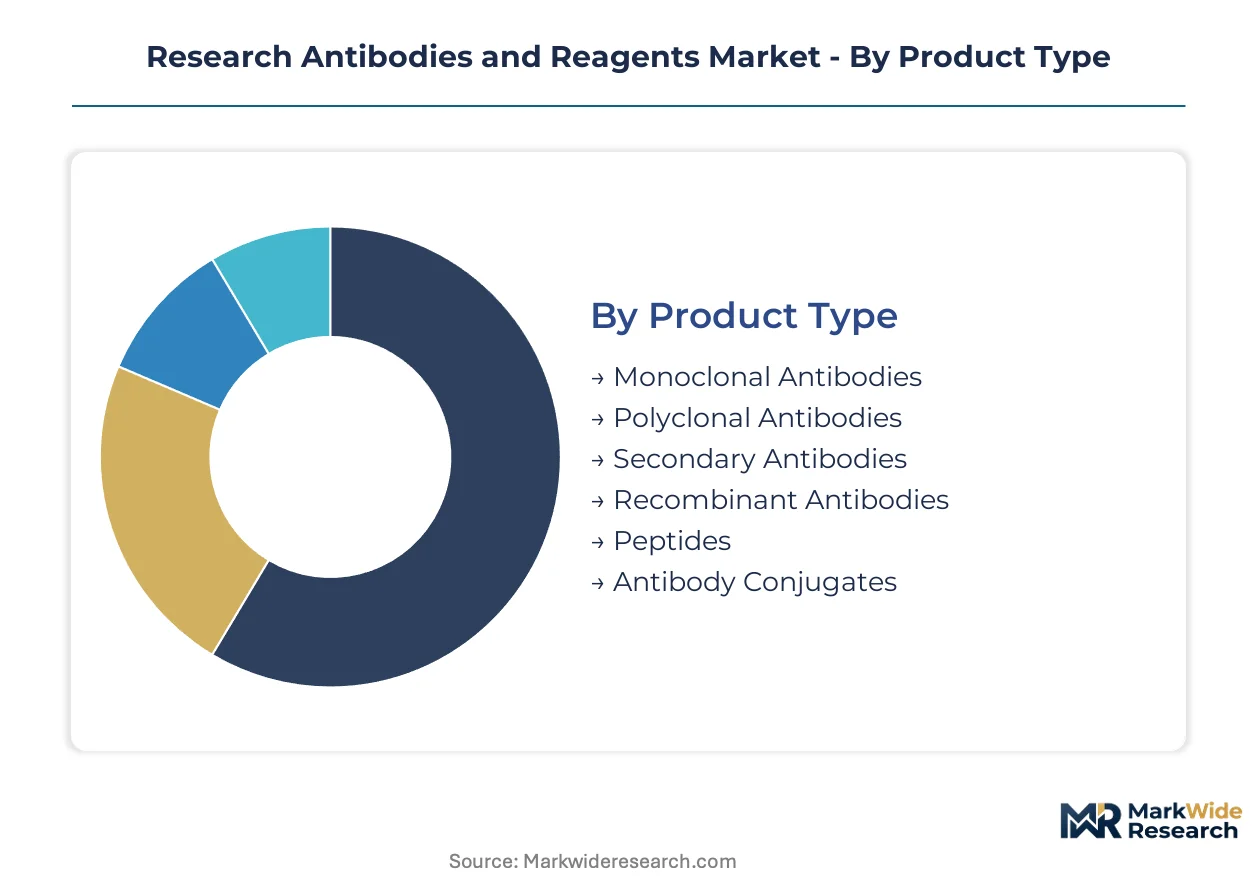
Antibody sourcing decisions fragment across technical specifications, regulatory compliance tiers, and workflow integration requirements. Each segmentation dimension carries distinct margin profiles and vendor qualification thresholds that reshape procurement patterns.
Product Type:
Margin pools concentrate in recombinant antibody production and specialized conjugation chemistry where validation documentation commands premium pricing.
- Monoclonal Antibodies:Defined specificity through single-clone hybridoma or recombinant production yields renewable supply chains with lot-to-lot consistency. Pharmaceutical translational medicine groups in Boston and San Francisco specify these for IND-enabling biomarker assays where regulatory scrutiny is highest.
- Recombinant Antibodies:Animal-origin-free expression systems in Chinese hamster ovary or HEK293 platforms satisfy pharmaceutical sponsor documentation requirements for clinical trial materials. EMA MDR guidance on traceability is accelerating migration from hybridoma-derived alternatives.
- Polyclonal Antibodies:Heterogeneous immunoglobulin pools from immunized host animals retain cost advantages for screening applications.
- Secondary Antibodies:Detection-conjugated immunoglobulins against primary antibody species enable signal amplification in multiplex assays.
- Peptides:Synthetic antigen sequences support epitope mapping and competitive binding studies.
- Antibody Conjugates:Fluorophore-, enzyme-, or bead-coupled reagents command technical complexity premiums in flow cytometry panels.
Monoclonal antibodies hold installed capacity. Recombinant antibodies are rotating up the share rankings.
Application:
Volume concentration tracks pharmaceutical R&D pipeline density with drug discovery absorbing the greatest reagent tonnage.
- Drug Discovery:Target identification, validation, and mechanism-of-action studies consume antibody libraries at scale. NIH-funded academic medical centers and biotechnology firms in Cambridge and South San Francisco drive high-throughput screening demand.
- Flow Cytometry:Multiplex biomarker quantification in immuno-oncology trials requires specialized conjugated antibodies with precise fluorophore-to-protein ratios. Panel expansion toward 30+ parameters is compressing procurement cycles.
- Proteomics:Mass spectrometry-compatible antibodies and peptide standards enable quantitative protein profiling.
- Immunohistochemistry:Tissue-section-grade antibodies with defined formalin-fixed paraffin-embedded compatibility support diagnostic development.
- ELISA:Plate-based quantification relies on matched antibody pairs with validated sensitivity ranges.
- Western Blotting:Gel electrophoresis detection reagents represent commoditized catalog volumes with price compression.
Drug discovery commands the volume base. Flow cytometry is climbing the fastest on value contribution.
End User:
Procurement autonomy varies sharply with contract research organizations centralizing purchasing through enterprise agreements.
- Pharmaceutical Companies:Internal biologics divisions and translational medicine groups demand GMP-adjacent documentation standards for IND-enabling studies. FDA bioanalytical method validation guidance elevates reagent qualification burdens.
- Contract Research Organizations:Outsourced drug development programs aggregate antibody panel procurement with pre-negotiated validation specifications. IQVIA and Charles River Laboratories operations concentrate purchasing power.
- Biotechnology Firms:Venture-funded discovery shops prioritize speed-to-data over documentation depth in early-stage programs.
- Academic Institutes:NIH funding cycles at Stanford, Harvard, and UCSF sustain high-volume purchasing with principal investigator autonomy.
- Research Laboratories:National laboratory facilities operate under federal procurement regulations with extended vendor qualification timelines.
Pharmaceutical companies anchor the premium tier. Contract research organizations are gaining procurement leverage fastest.
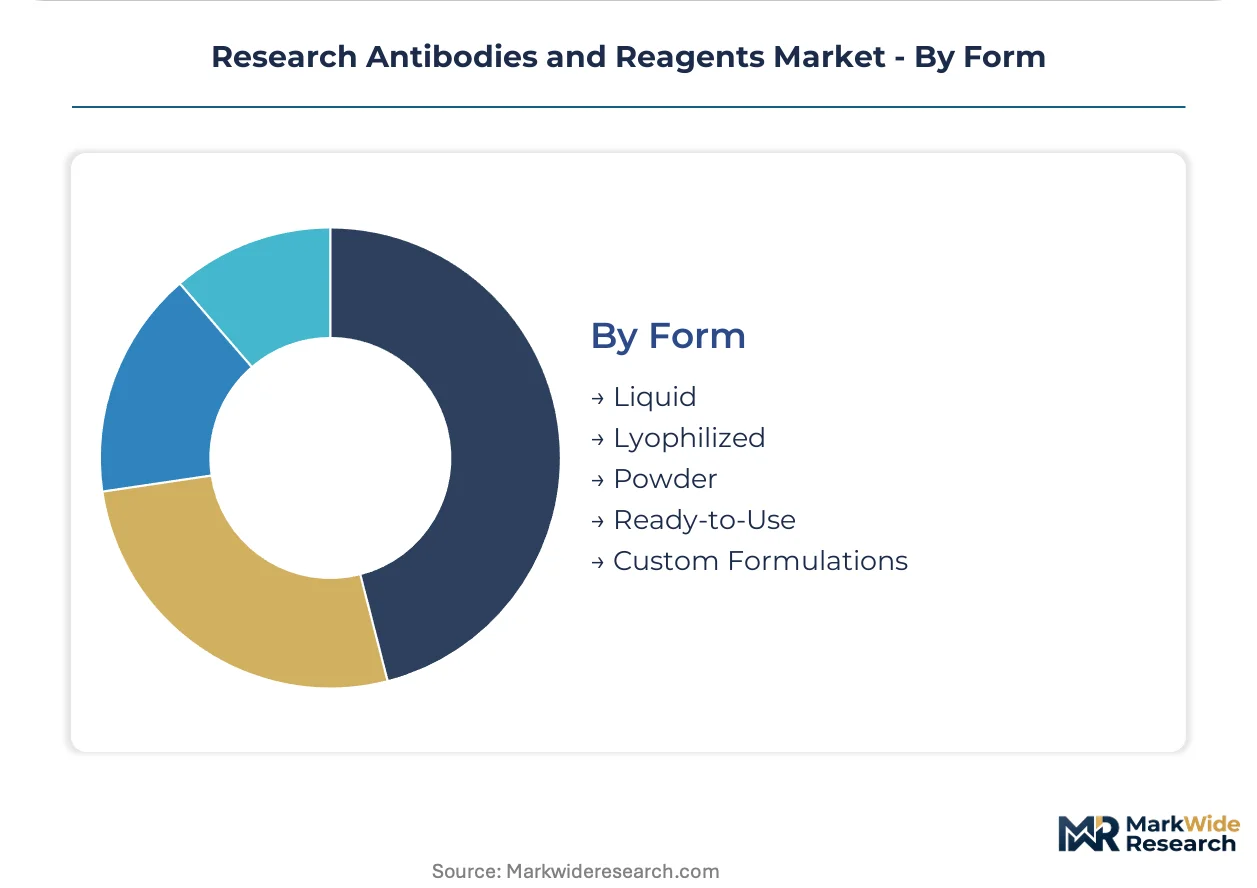
Form:
Supply chain configuration favors liquid formulations for high-throughput automation while lyophilized formats reduce cold-chain burden.
- Liquid:Ready-to-dispense aqueous solutions dominate automated liquid handling workflows in pharmaceutical screening facilities. Cold-chain logistics from manufacturing sites in Shanghai and San Diego maintain stability.
- Lyophilized:Freeze-dried formats extend shelf life for international distribution and field-deployed research.
- Powder:Bulk active immunoglobulin requires end-user reconstitution with defined buffer systems.
- Ready-to-Use:Pre-diluted, pre-conjugated reagents eliminate batch preparation variability in regulated environments.
- Custom Formulations:Client-specified concentrations, buffers, and stabilizers command development service fees.
Liquid formulations dominate throughput-intensive applications. Lyophilized formats are expanding most quickly in distributed research networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA bioanalytical guidance elevates reagent documentation standards in the United States, while EMA MDR traceability mandates reshape European procurement. NIH funding cycles and biotech clustering sustain concentrated demand across North American research corridors.
United States
NIH appropriations exceeding $47 billion annually drive high-volume antibody purchasing from academic medical centers. FDA updated guidance on bioanalytical method validation now requires extended reagent qualification documentation for IND-enabling studies. Biotech clustering around Boston and San Francisco concentrates specialized procurement through consolidated enterprise agreements.
Germany
EMA ICH Q2(R1) harmonization elevates manufacturing change notification protocols for research-use antibodies destined for clinical trials. The country's national pharmaceutical regulator enforces extended stability data requirements previously reserved for GMP materials. Industrial concentration in Munich and Heidelberg research clusters favors suppliers with dedicated quality infrastructure.
China
Contract manufacturing for recombinant protein production clusters in Shanghai and Suzhou industrial zones, creating supply concentration for antigen production. NMPA alignment with international reference standard harmonization initiatives is accelerating local validation capability investment. Beijing-Tianjin-Hebei research corridors are expanding procurement of animal-origin-free expression systems.
United Kingdom
Post-Brexit divergence from EU MDR implementation is creating dual-track documentation requirements for reagent suppliers serving European and domestic markets. Cambridge and Oxford research ecosystems sustain premium-tier antibody demand for translational medicine programs. The Medicines and Healthcare products Regulatory Agency is developing UK-specific performance evaluation frameworks for diagnostic-grade reagents.
India
Hyderabad and Bengaluru biotech corridors remain underpenetrated by validated reagent distributors with local technical support infrastructure. CDSCO alignment with international ISO 13485 certification pathways is opening diagnostic-grade antibody qualification channels. Maharashtra and Karnataka state biotechnology policies are attracting contract research operations with centralized procurement requirements.
Research Antibodies and Reagents Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the research antibodies and reagents market. Consolidated buying through group purchasing organizations is fragmenting individual laboratory autonomy while concentrating volume with vendors offering enterprise-wide data management. Three archetypes dominate: diversified life science conglomerates with workflow integration capabilities, specialized antibody houses with proprietary validation platforms, and catalog distributors competing on digital procurement efficiency. Competitive moves center on recombinant antibody production capacity expansion and ISO 13485 quality system certification for diagnostic-grade market access.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify end-to-end workflow integration strategies that bundle analytical instruments with consumable reagent supply. Abcam plc occupies a distinct position representing the specialized validation-focused archetype, competing through digital distribution channels that displace traditional field sales models. Merck KGaA anchors the European-based diversified supplier segment with historical strength in life science reagent manufacturing.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc. |
| Santa Cruz Biotechnology Inc. |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche AG |
| Danaher Corporation |
| Merck KGaA |
| Cell Signaling Technology Inc. |
| Becton Dickinson and Company |
| Abcam plc |
| Others |
Cost & Logistics Intelligence
Capacity utilization at recombinant antibody production facilities in China and the United States shapes both supply concentration and minimum viable pricing floors for validated reagent tiers. Scale advantages at Shanghai-based contract manufacturing organizations compress unit economics for animal-origin-free expression systems while elevating barriers for smaller hybridoma-dependent suppliers.
Pricing Analysis
Geographic price spreads of 15-40% separate United States biotech corridor procurement from European academic medical center purchasing, reflecting cold-chain logistics premiums and FDA documentation burdens. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth: ISO 13485-certified diagnostic-grade reagents command highest tiers, while catalog polyclonals occupy economy positioning. Price differentiation rests on lot-to-lot consistency guarantees and extended stability data packages. Cost compression in standard-tier monoclonal antibodies is intensifying because Chinese recombinant production capacity expansion floods screening-application segments. Biotechnology firms with venture-funded discovery programs exhibit highest price sensitivity; pharmaceutical translational medicine groups show lowest sensitivity due to IND-enabling assay requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical screening facilities in Boston and San Francisco, while strategic stockpiling of validated antibody lots persists among CROs managing longitudinal biomarker studies. Geographic supply concentration centers on China for recombinant protein antigen production, the United States for hybridoma-derived monoclonals, and Germany for specialized conjugation chemistry. Raw material dependencies encompass fetal bovine serum from agricultural commodity markets, fluorophore dyes from specialized chemical manufacturers, and recombinant expression plasmids from contract foundries. Single-source vulnerability from Shanghai-Suzhou manufacturing clusters creates supply chain risk exposure. Distribution runs through direct-to-laboratory e-commerce platforms compressing traditional field sales cycles alongside consolidated group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in validation documentation and lot-matching subscriptions expand faster than base reagent hardware, with recurring-revenue data management portals capturing enterprise procurement decisions at academic medical centers.
For Market Incumbents: Fortify quality infrastructure investments against EMA MDR traceability mandates and FDA bioanalytical guidance escalation that elevate documentation burdens beyond smaller competitor reach. Deepen backward integration into recombinant expression platforms to secure animal-origin-free supply chains as pharmaceutical sponsors harden sourcing requirements. Consolidate procurement relationships through enterprise data portals that embed validation services into long-term contracts. For New Entrants and Emerging Players: Lead with digital distribution platforms targeting Hyderabad and Bengaluru biotech corridors where validated reagent distributors with local technical support remain underpenetrated. Capture flow cytometry panel customization demand from immuno-oncology CROs seeking rapid turnaround on multiplex biomarker assays. Deploy searchable validation databases with transparent specificity metrics as primary go-to-market differentiation against legacy catalog suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized antibody houses with proprietary rabbit B-cell cloning platforms and ISO 13485 certification pathways. Long-term viability over the next decade favors suppliers with diagnostic-grade qualification infrastructure and pharmaceutical sponsor direct relationships. Acquisition target archetypes include mid-tier recombinant producers with underutilized CHO capacity and digital-native distributors with validated data architectures. The signal to watch is NIH funding cycle appropriation volatility crossing thresholds that trigger academic medical center procurement freezes.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Certification | Opens regulated IVD companion diagnostic co-development pathways with pharmaceutical sponsors. |
| Recombinant Antibody Capacity Expansion | Addresses pharmaceutical demand for animal-origin-free documentation in IND-enabling studies. |
| Digital Distribution Platform Launch | Compresses field sales cycles through searchable validation data and direct-to-laboratory e-commerce. |
| Rabbit Monoclonal Platform Investment | Captures phospho-specific detection demand from translational medicine groups specifying rabbit clones. |
| Enterprise Data Portal Development | Secures consolidated buying relationships with group purchasing organizations fragmenting laboratory autonomy. |
Research Approach
Desk research of regulatory guidance documents, SEC filings from diversified life science conglomerates, and NIH funding appropriation records preceded structured interviews with drug development executives, regulatory affairs leads at reagent manufacturers, academic medical center procurement managers, and CRO biomarker assay specialists. Primary fieldwork combined telephone and video interviews with secondary validation against FDA bioanalytical method validation guidance, EMA MDR implementation documents, and ISO 13485 certification pathway specifications. Bottom-up reagent volume modeling triangulated against top-down market sizing from disclosed contract values and enterprise procurement patterns.
Variance decomposition across product type, application workflow, end-user procurement autonomy, and regional regulatory cluster segmentation shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier contributions, with recombinant antibody production growth rates calibrated against pharmaceutical sponsor sourcing survey data and hybridoma capacity retirement schedules. Forecast inputs incorporated NIH appropriation cycle patterns, EMA MDR enforcement intensity assumptions, and Chinese manufacturing capacity expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained federal research funding levels, stable fetal bovine serum commodity pricing, and continued EMA-FDA regulatory harmonization would require recalibration. Forecasts reflect documented assumptions regarding validation standard tightening velocity and digital procurement adoption curves. Revision becomes warranted when Chinese recombinant protein supply concentration triggers tariff or export restriction thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biobank Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Global Protein Binding Assay Market