
 Transport Protein Assays Kits Market | 2026-2036
Transport Protein Assays Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Protein Assays Kits Market Outlook
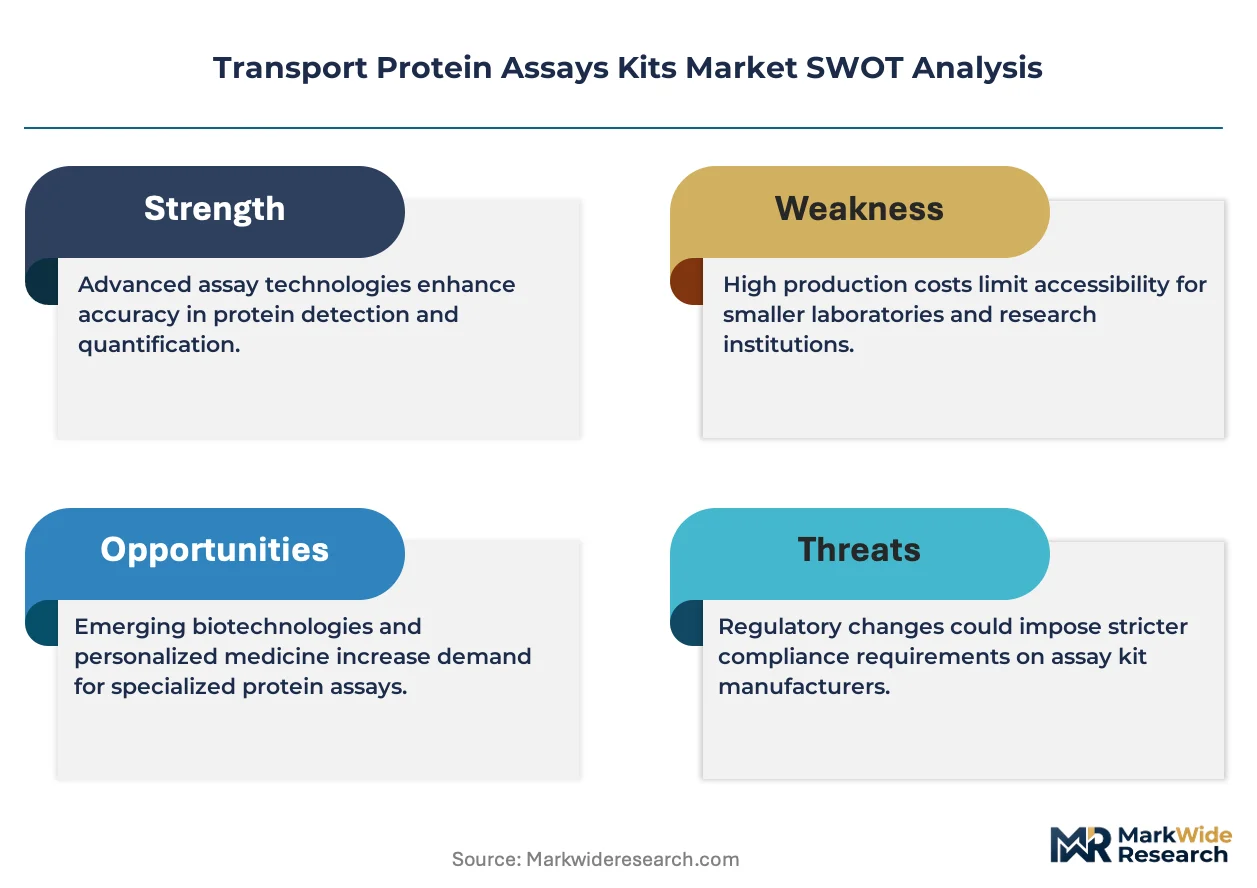
ISO 13485 certification for in vitro diagnostic reagents is unwinding competitive access for kit manufacturers without quality management infrastructure. Thermo Fisher Scientific leverages its captive antibody supply chain to dominate the ELISA and fluorescent assay segments. Merck KGaA anchors European distribution through its life science reagent division, while Bio-Rad Laboratories differentiates via proprietary gel electrophoresis workflows bundled with transport protein detection panels.
Transport protein assays kits are analytical reagent systems engineered to quantify membrane-bound carrier proteins—efflux pumps, uptake transporters, and ion channels—typically employing fluorogenic substrates or labeled antibodies with detection thresholds in the picomolar range, serving drug-drug interaction screening and transporter-mediated toxicity assessment. The fluorescent assays segment leads in revenue density due to multiplexing capability, while lateral flow assays represent the fastest-expanding format for point-of-care transporter phenotyping in clinical labs. Academic research institutions command the largest end-user volume, though pharmaceutical companies capture the premium pricing tier for GLP-compliant kits used in regulatory submission packages.
FDA bioanalytical guidance and EMA's ICH M12 transporter interaction guidelines jointly shape kit performance standards and validation protocols for regulatory submission. The EPA and OSHA frameworks indirectly influence demand through occupational exposure biomonitoring programs that rely on transporter activity readouts. Stakeholders must monitor evolving pharmacogenetic testing reimbursement codes and emerging CRISPR-edited transporter cell line standards that will redefine kit content specifications and competitive differentiation.
Market Dynamics
FDA bioanalytical method validation guidelines and EMA ICH M12 transporter interaction standards are compressing kit performance tolerances while academic institutions and CROs scramble to upgrade detection sensitivity thresholds for regulatory submission packages.
Growth Catalysts
- NIH-funded transporter research expansion:The National Institutes of Health has intensified grant allocations for membrane transporter pharmacology, directly expanding kit procurement volumes at academic medical centers and university laboratories across the United States.
- EMA ICH M12 implementation:The European Medicines Agency's transporter interaction guideline mandates standardized in vitro assays for new drug applications, forcing pharmaceutical sponsors to acquire GLP-compliant kit systems for regulatory submissions.
- Fluorogenic substrate multiplexing:Advances in simultaneous multi-transporter detection are reducing per-assay costs and accelerating high-throughput screening workflows at contract research organizations handling drug-drug interaction studies.
Market Restraints
- Captive antibody supply concentration:Thermo Fisher Scientific's vertical control over high-affinity antibody production creates supply bottlenecks for competing kit manufacturers lacking in-house biologics manufacturing infrastructure.
- ISO 13485 certification barriers:The quality management system requirement for in vitro diagnostic reagents imposes capital-intensive facility upgrades that exclude smaller reagent suppliers from commercializing regulated assay kits.
- CRISPR-edited cell line substitution:Engineered transporter-expressing cell lines with standardized genetic backgrounds are displacing native membrane preparations in some pharmaceutical screening applications, reducing demand for certain kit formats.
Strategic Opportunities
- Point-of-care lateral flow expansion:Clinical laboratories in Germany and France are piloting rapid transporter phenotyping assays for personalized dosing protocols, creating demand for simplified kit formats outside traditional research settings.
- Pharmacogenetic reimbursement tailwinds:Emerging CPT codes for transporter genotype-guided therapy selection in the United States are incentivizing hospital system investment in companion diagnostic assay infrastructure.
- AI-driven assay optimization:Machine learning algorithms trained on kinetic substrate data are converging with automated liquid handling platforms to reduce manual protocol development time for custom transporter panels.
Industry Challenges
- GLP compliance talent scarcity:Kit manufacturers face acute shortages of quality assurance professionals experienced in FDA bioanalytical method validation documentation and audit trail management.
- Cross-platform standardization delays:Absence of universal reference materials for organic anion transporting polypeptide and bile salt export pump assays forces customers to run parallel validation studies, extending sales cycles.
- Reagent stability logistics:Temperature-sensitive fluorogenic substrates require cold-chain distribution infrastructure that strains working capital for mid-scale kit vendors serving dispersed academic accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Protein Assays Kits Market |
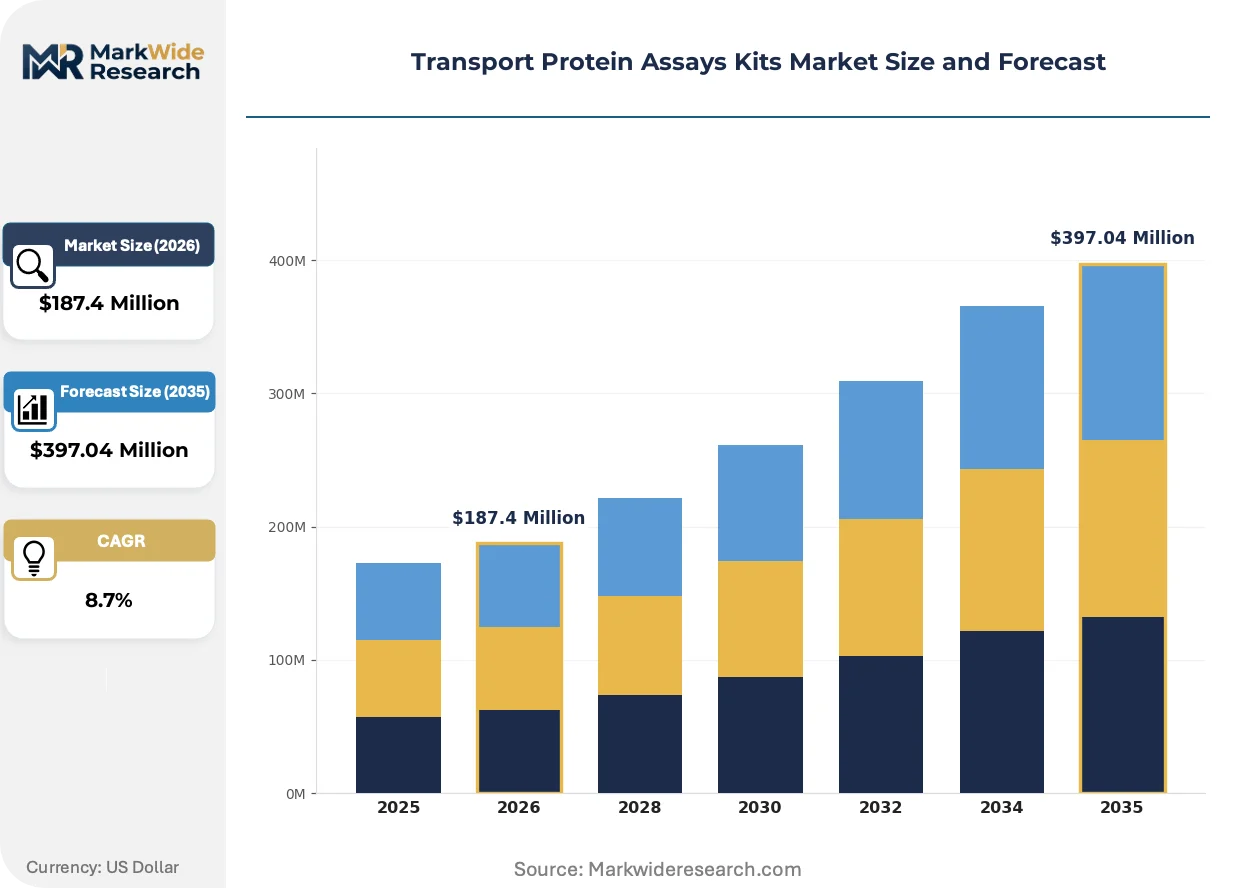
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Western Blotting Kits, Lateral Flow Assays, Fluorescent Assays Application: Drug Development, Diagnostic Research, Clinical Trials, Academic Research Technology: Chromatography, Spectroscopy, Electrophoresis, Microscopy End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Clinical Labs |
| Companies Covered | Thermo Fisher Scientific Inc, Merck KGaA, PerkinElmer Inc, Abcam plc, Bio-Rad Laboratories Inc, Solvo Biotechnology, BioVision Inc, Novus Biologicals Inc, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Protein Assays Kits Market Strategic Shifts
Multiplexed detection architectures and automated liquid handling integration are compressing assay development timelines while regulatory validation requirements harden performance benchmarks across pharmaceutical and clinical laboratory end-uses.
High-content imaging platforms with automated transporter localization analysis are displacing traditional endpoint fluorescence plate readers in drug discovery workflows. Pharmaceutical toxicology departments at Merck KGaA and contract research organizations in Massachusetts are adopting these systems to capture subcellular transporter trafficking dynamics. The shift is compressing demand for single-readout kits while expanding the market for integrated imaging-reagent bundles.
REACH regulation amendments targeting per- and polyfluoroalkyl substances are forcing European kit manufacturers to reformulate fluorogenic substrates and surface coatings. The ECHA restriction proposal affects hydrophobic dye compounds commonly used in lipophilic transporter assays, compelling reformulation investments before 2027 enforcement deadlines. German and Swiss reagent suppliers are accelerating green chemistry partnerships to secure alternative fluorophore supply.
Academic procurement committees are consolidating vendor relationships through multi-year framework agreements rather than transactional purchase orders. University core facilities in North Carolina and California are negotiating bundled pricing across ELISA, fluorescent, and electrophoresis-based transporter detection modalities. This concentration is squeezing smaller kit suppliers dependent on episodic grant-funded purchases while rewarding manufacturers with broad assay format portfolios.
Transport Protein Assays Kits Market Segmentation
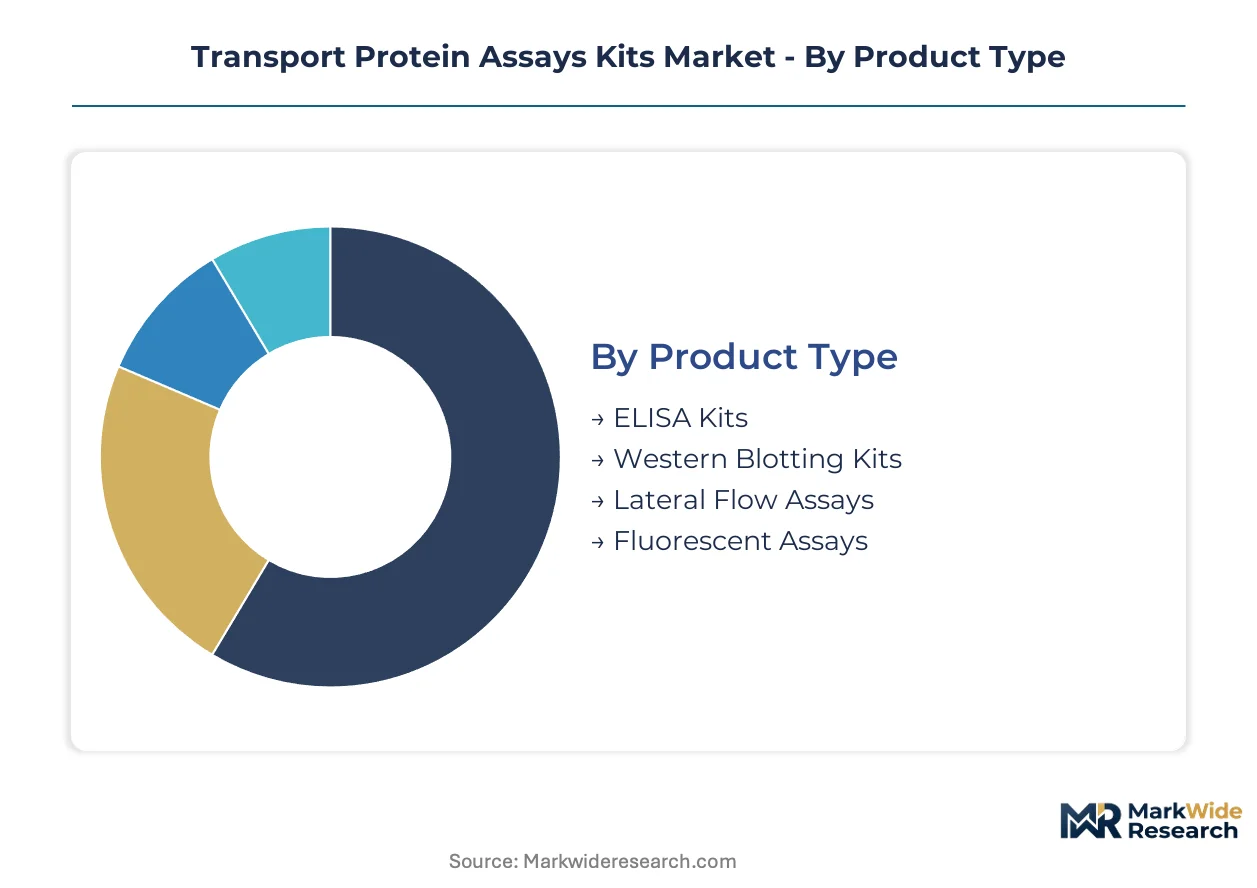
Transport protein assay kits fragment across detection modalities, research applications, and institutional procurement tiers. Each segmentation axis reveals distinct margin architectures and competitive dynamics that shape vendor positioning.
Product Type:
Premium pricing concentrates in multiplex-capable formats with regulatory-grade documentation, while commoditized entry-level kits compete on per-well economics.
- Fluorescent Assays:These systems employ picomolar-sensitivity fluorogenic substrates with simultaneous multi-transporter detection capability. Demand clusters at contract research organizations in Massachusetts and North Carolina handling high-throughput drug-drug interaction screening under FDA bioanalytical guidelines. Multiplexing architecture reduces per-assay reagent consumption while accelerating compound liability assessment timelines.
- ELISA Kits:Enzyme-linked immunosorbent assays deliver standardized quantification through high-affinity antibody binding with colorimetric or chemiluminescent readouts. Pharmaceutical toxicology departments prioritize GLP-compliant ELISA formats for regulatory submission packages, particularly where transporter protein abundance falls within standard dynamic ranges. Thermo Fisher's captive antibody supply chain secures batch-to-batch consistency that competing vendors struggle to match.
- Lateral Flow Assays:Rapid chromatographic test strips enable point-of-care transporter phenotyping without laboratory infrastructure.
- Western Blotting Kits:Gel-based protein separation with immunodetection serves confirmatory studies requiring molecular weight verification.
The dominant share belongs to fluorescent assays, while lateral flow assays are gaining share fastest through clinical laboratory pilots in Germany and France.
Application:
Regulatory submission requirements create tiered demand intensity across research phases, with preclinical safety assessment commanding the steepest kit specifications.
- Drug Development:Transporter-mediated toxicity and drug-drug interaction studies mandate GLP-compliant assay validation with full audit trails. EMA ICH M12 implementation forces sponsors to acquire standardized in vitro transporter interaction data, expanding procurement of validated kit systems for IND-enabling and NDA-supporting studies.
- Academic Research:NIH-funded membrane transporter pharmacology grants drive volume procurement at university core facilities. North Carolina and California institutions negotiate multi-year framework agreements bundling ELISA, fluorescent, and electrophoresis modalities, squeezing smaller vendors dependent on episodic grant cycles.
- Diagnostic Research:Biomarker discovery applications employ transport protein activity as surrogate endpoints for organ function assessment.
- Clinical Trials:Pharmacogenetic stratification protocols require transporter genotype-phenotype correlation assays with documented analytical performance.
Drug development captures the premium pricing tier, while academic research generates the largest unit volumes through distributed procurement networks.
Technology:
Detection modality selection hinges on spatial resolution requirements versus throughput economics, with imaging platforms displacing endpoint readers in discovery workflows.
- Chromatography:High-performance liquid chromatography coupled with mass spectrometry enables absolute quantification of transporter substrate accumulation with structural specificity. Pharmaceutical analytical departments employ LC-MS/MS methods as reference standards for validating simpler immunoassay formats.
- Microscopy:High-content imaging platforms with automated transporter localization analysis capture subcellular trafficking dynamics invisible to population-averaged assays. Merck KGaA toxicology units adopt these integrated imaging-reagent bundles for mechanistic safety studies.
- Spectroscopy:UV-Vis and fluorescence spectrometry provide rapid quantitative readouts for routine screening applications.
- Electrophoresis:Gel-based separation supports protein characterization and antibody specificity verification in quality control workflows.
Microscopy commands the highest per-station revenue, while chromatography maintains the broadest installed base across pharmaceutical quality control laboratories.
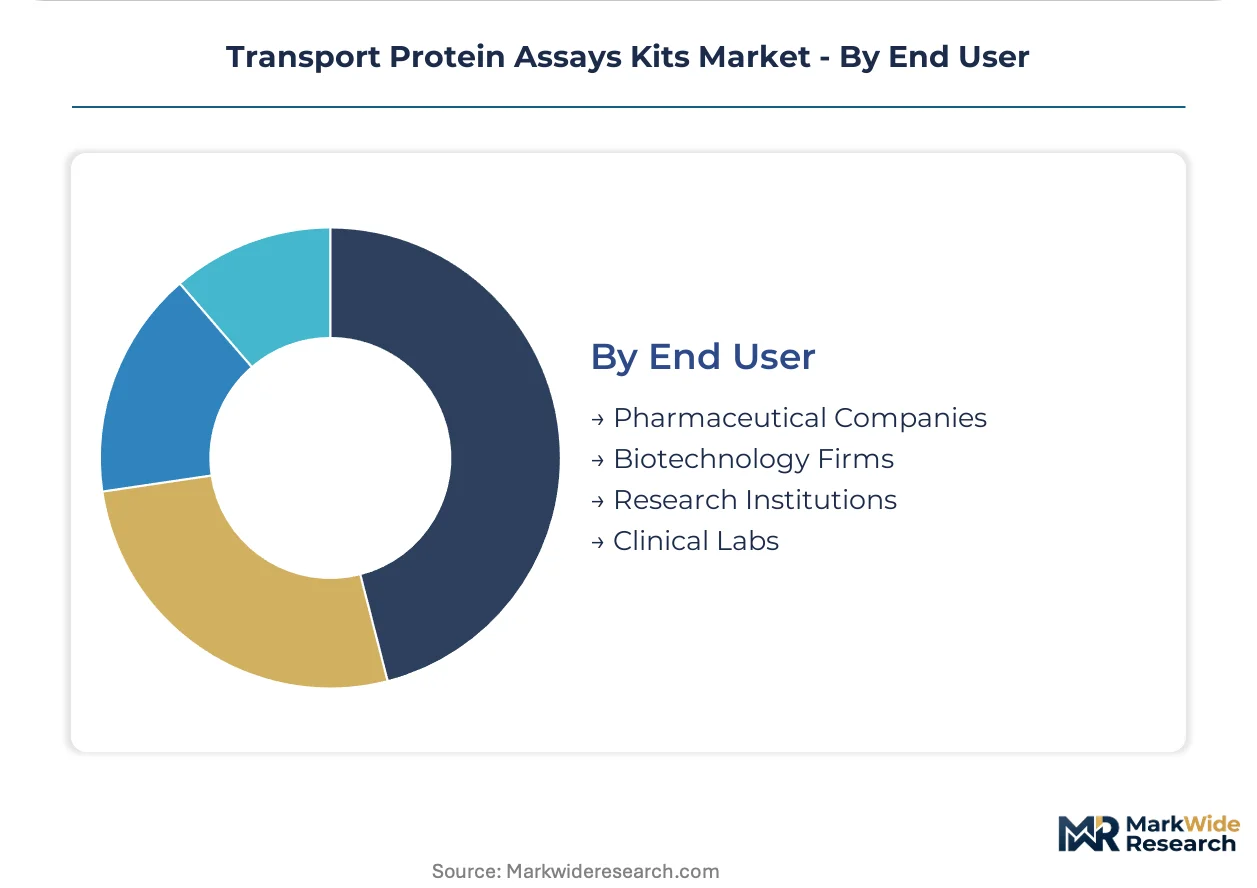
End User:
Procurement sophistication varies sharply by organizational scale, with enterprise buyers enforcing supplier consolidation and smaller accounts prioritizing technical support access.
- Pharmaceutical Companies:Integrated drug developers specify GLP-compliant kits with validated protocols for regulatory submission. FDA bioanalytical method validation guidelines tighten performance benchmarks, forcing quality assurance departments to audit supplier documentation and manufacturing change control procedures.
- Research Institutions:University core facilities and academic medical centers balance cost constraints against multi-format flexibility. Consolidated vendor relationships through framework agreements reward manufacturers with broad assay portfolios spanning detection modalities.
- Biotechnology Firms:Emerging drug developers prioritize rapid assay implementation with minimal protocol optimization.
- Clinical Labs:Hospital system laboratories pilot transporter phenotyping for pharmacogenetic dosing protocols under emerging reimbursement codes.
Pharmaceutical companies dominate the value pool, while clinical labs represent the steepest expansion trajectory as companion diagnostic infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIH grant expansion and EMA regulatory mandates are redistributing kit procurement across concentrated pharmaceutical clusters and academic medical centers in North America and Europe.
United States
NIH-funded membrane transporter pharmacology grants drive procurement volumes at university core facilities. FDA bioanalytical method validation guidelines tighten performance benchmarks for regulatory submission packages. Massachusetts and North Carolina pharmaceutical outsourcing clusters consume GLP-compliant kits for IND-enabling studies.
Germany
EMA ICH M12 implementation forces sponsors to acquire standardized in vitro transporter interaction data. REACH regulation amendments targeting per- and polyfluoroalkyl substances compel reformulation of fluorogenic substrates before 2027 enforcement. Clinical laboratories in Berlin and Munich pilot rapid transporter phenotyping for personalized dosing protocols.
United Kingdom
Academic research institutions negotiate multi-year framework agreements bundling detection modalities across ELISA and fluorescent formats. MHRA alignment with FDA bioanalytical standards elevates kit documentation requirements for pharmaceutical sponsors. The Cambridge-Oxford-London corridor concentrates contract research organization demand for high-throughput screening workflows.
France
Hospital system laboratories adopt point-of-care lateral flow assays for pharmacogenetic stratification under emerging reimbursement frameworks. ANSM pharmacovigilance requirements strengthen quality management expectations for diagnostic reagents. The Paris-Saclay cluster anchors public-private partnerships in transporter-mediated toxicity assessment.
Switzerland
Swissmedic regulatory convergence with EMA ICH M12 elevates validation protocol standards for commercial kit suppliers. Basel-based pharmaceutical toxicology departments integrate high-content imaging platforms with automated transporter localization analysis. Zurich and Geneva academic medical centers consolidate vendor relationships through centralized procurement committees.
Transport Protein Assays Kits Market Competitive Environment
Player mix skews toward diversified life science conglomerates with captive reagent supply chains and specialized assay developers with format-specific expertise. Market structure concentrates around three to five integrated suppliers controlling antibody production and distribution infrastructure alongside mid-scale vendors competing on protocol customization. Strategic archetypes include vertical supply chain owners, multi-format portfolio bundlers, and niche fluorescent substrate specialists. Dominant competitive moves encompass ISO 13485 certification investments to exclude smaller competitors and framework agreement negotiations with university procurement committees.
Among diversified conglomerates, Thermo Fisher Scientific Inc and Danaher Corporation exemplify archetypes built on captive biologics manufacturing and acquisition-driven portfolio breadth. Merck KGaA anchors European distribution positioning through its life science reagent division. Bio-Rad Laboratories Inc occupies a specialist tier differentiated by proprietary workflow integration. These named entities represent the competitive tension between scale-driven supply security and format-specific technical positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Merck KGaA |
| PerkinElmer Inc |
| Abcam plc |
| Bio-Rad Laboratories Inc |
| Solvo Biotechnology |
| BioVision Inc |
| Novus Biologicals Inc |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day antibody production lead times concentrate pricing power with manufacturers holding captive biologics infrastructure, while cold-chain distribution costs for fluorogenic substrates compress margins for mid-scale kit vendors serving dispersed academic accounts across the United States and Germany.
Pricing Analysis
Certification level creates the primary spread between GLP-compliant premium tiers and research-grade economy positioning. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 audit depth, FDA bioanalytical method validation documentation, and batch-to-batch consistency guarantees. Cost compression in the economy tier is intensifying because university procurement committees consolidate vendor relationships through multi-year framework agreements. Academic research institutions exhibit the highest price sensitivity, while pharmaceutical toxicology departments absorb premium pricing for regulatory submission packages.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for antibody raw materials sourced from Chinese biologics contractors. Manufacturing concentration clusters in the United States, Germany, and Switzerland, with captive antibody production resting on hybridoma cell line repositories and recombinant expression systems. Single-source vulnerability permeates high-affinity antibody supply, where Thermo Fisher's vertical control creates bottlenecks for competing kit manufacturers. Distribution runs through life science reagent distributors, direct pharmaceutical procurement channels, and university core facility framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kit manufacturers face acute shortages of quality assurance professionals experienced in FDA bioanalytical method validation documentation, creating a capability gap that separates compliant suppliers from excluded competitors.
For Market Incumbents: Compound defensive positioning through ISO 13485 certification investments that exclude smaller reagent suppliers from regulated assay kit commercialization, while deepening upstream control over fluorogenic substrate formulation to offset REACH regulation amendment impacts on per- and polyfluoroalkyl substance alternatives. CRISPR-edited cell line substitution threatens native membrane preparation demand, requiring bundled imaging-reagent offerings to capture high-content platform adoption at Merck KGaA toxicology units and Massachusetts contract research organizations. For New Entrants and Emerging Players: Differentiate on point-of-care lateral flow assay formats for clinical laboratory pilots in Germany and France, where pharmacogenetic reimbursement tailwinds incentivize hospital system investment in companion diagnostic infrastructure. Target diagnostic research applications with simplified kit architectures that minimize protocol optimization burdens for emerging biotechnology firms lacking in-house assay development expertise. Pursue AI-driven assay optimization partnerships with automated liquid handling platform vendors to reduce manual protocol development time for custom transporter panels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA bioanalytical guidance and EMA ICH M12 transporter interaction standards jointly harden performance benchmarks and validation protocols, erecting durable moats around compliant suppliers. Acquisition targets should display ISO 13485 certification, captive antibody supply relationships, and established framework agreements with university procurement committees in North Carolina and California. Monitor emerging CPT codes for transporter genotype-guided therapy selection as the signal indicating companion diagnostic infrastructure maturation and clinical laboratory demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management infrastructure excludes non-compliant competitors from regulated IVD reagent commercialization under FDA and EMA frameworks. |
| Fluorogenic Substrate Reformulation Partnership | Green chemistry alliances secure alternative fluorophore supply ahead of ECHA REACH enforcement deadlines affecting hydrophobic dye compounds. |
| University Framework Agreement Negotiation | Multi-year bundled pricing across ELISA, fluorescent, and electrophoresis modalities captures consolidated procurement at NIH-funded institutions. |
| High-Content Imaging Platform Integration | Automated transporter localization analysis bundles displace single-readout kits at pharmaceutical toxicology departments in Basel and Massachusetts. |
| Point-of-Care Lateral Flow Expansion | Rapid transporter phenotyping assays address emerging pharmacogenetic reimbursement codes in United States hospital systems and European clinical laboratories. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, university core facility directors, and contract research organization procurement managers and refined through secondary validation against FDA bioanalytical method validation guidelines, EMA ICH M12 transporter interaction documentation, NIH grant allocation databases, and SEC 10-K filings from diversified life science conglomerates. Bottom-up kit volume estimates triangulated with top-down market sizing across detection modalities.
Variance decomposition across product type, application, technology, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro drivers including NIH-funded transporter research expansion and EMA regulatory mandate implementation. Industry-specific inputs incorporated CRISPR-edited cell line adoption curves, pharmacogenetic reimbursement code emergence patterns, and fluorogenic substrate reformulation investment timelines.
Material uncertainties — regulatory guidance revisions, CRISPR cell line substitution acceleration, and REACH enforcement scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions about ISO 13485 certification penetration rates and framework agreement consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Serine Protease Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Biobank Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Cell Characterization Assays Kits Market