
 Marine Polysaccharides Fucoidan Alginate Market | 2026-2036
Marine Polysaccharides Fucoidan Alginate Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Polysaccharides Fucoidan Alginate Market Insights
The EU Green Deal is shifting procurement criteria for marine-derived biomaterials across European pharmaceutical and nutraceutical supply chains. CP Kelco leverages its integrated seaweed supply network to sustain consistent alginate output for food and pharma grades. FMC Corporation anchors North American availability through controlled harvesting partnerships and extraction scale. Gelymar competes in fucoidan specialization, targeting high-purity extracts for dietary supplement formulators.
Marine polysaccharides fucoidan alginate encompasses sulfated polysaccharides extracted from brown seaweed cell walls, with fucoidan containing L-fucose and sulfate ester groups and alginates comprising linear copolymers of mannuronic and guluronic acid residues. These biopolymers function as gelling agents, stabilizers, encapsulation matrices, and bioactive carriers across food, pharma, and cosmetic systems. Sodium alginate dominates volume throughput due to established food and beverage thickening demand, while fucoidan extracts command premium positioning in pharmaceutical and nutraceutical applications where bioactivity justifies higher unit economics. Powder form leads industrial handling efficiency, though capsules and tablets gain traction in direct-to-consumer nutraceutical channels.
FDA oversight of dietary supplement Good Manufacturing Practices shapes fucoidan purity and label claim substantiation for US-bound products. EMA and REACH frameworks in Europe impose extraction solvent restrictions and heavy metal thresholds that filter supplier eligibility. Japan's Ministry of Health, Labour and Welfare maintains distinct pharmaceutical-grade specifications that favor domestic processors with historical compliance records. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and market access delays.
Market Dynamics
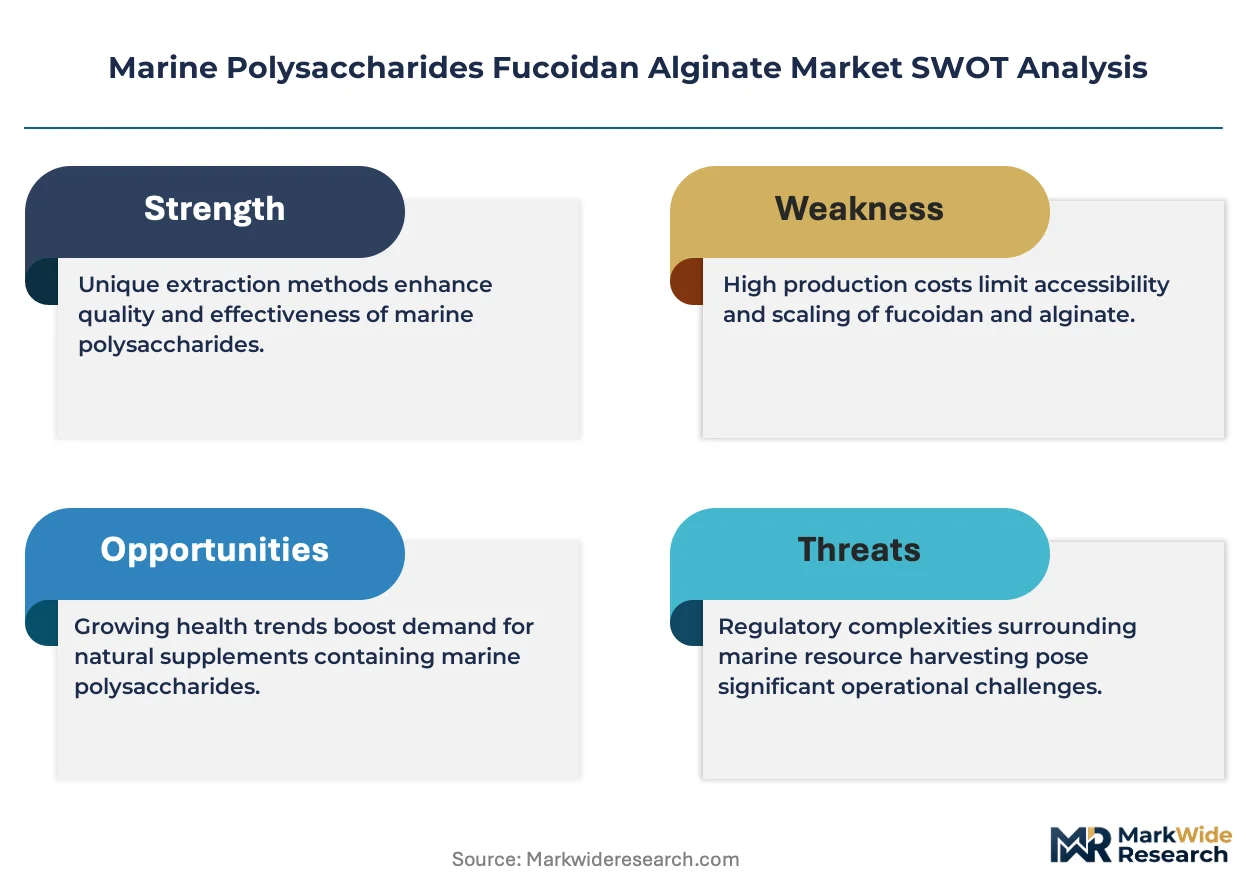
Pharmaceutical-grade extraction capabilities are concentrating among Japanese and European processors with proven compliance under EMA and PMDA frameworks, creating supply gatekeeping that filters new entrants and shapes competitive positioning across nutraceutical and medical device supply chains.
Growth Catalysts
- Immune-modulating supplement demand:Nutraceutical formulators are expanding fucoidan incorporation into functional foods and dietary supplements targeting gut-immune axis applications, with Japan's Ministry of Health, Labour and Welfare providing established approval pathways for bioactive claims.
- REACH compliance tightening:ECHA purity thresholds for pharmaceutical-grade alginate are filtering supplier eligibility and rewarding processors with solvent-recovery capabilities and heavy metal control infrastructure.
- Controlled harvesting partnerships:Sustainable seaweed sourcing agreements between extractors and coastal cultivation operations are securing raw material access for sodium alginate food-grade applications.
Market Restraints
- Brown seaweed biomass volatility:Climate-driven kelp forest degradation and ocean temperature shifts are compressing raw material availability for fucoidan extraction, particularly affecting North Atlantic and North Pacific sourcing zones.
- Extraction solvent restrictions:EMA and REACH frameworks impose chlorinated solvent prohibitions that eliminate conventional processing routes and force capital-intensive equipment upgrades for European processors.
- Synthetic hydrocolloid substitution:Modified cellulose derivatives and microbial polysaccharides are capturing price-sensitive food thickening applications where alginate functional performance is commoditized.
Strategic Opportunities
- Wound care matrix applications:Alginate hydrogel dressings are penetrating post-surgical and chronic wound management protocols, with FDA 510(k) pathways enabling faster commercialization than pharmaceutical drug approvals.
- Encapsulation technology convergence:Fucoidan-alginate coacervation systems are expanding into probiotic and omega-3 delivery formats, combining bioactive carrier functions with controlled-release engineering.
- EU Green Deal procurement criteria:European pharmaceutical and nutraceutical buyers are adopting marine-derived biomaterial sustainability certifications that favor processors with carbon-accounted supply chains and circular extraction methods.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and FDA GMP compliance for fucoidan active pharmaceutical ingredients requires 18-36 month validation cycles that strain working capital and delay revenue recognition.
- Cross-jurisdictional specification divergence:Japan's MHLW maintains distinct sulfate content and molecular weight thresholds that force dual-formulation strategies for global nutraceutical brands.
- Specialized extraction engineering talent:Scarcity of process chemists with brown seaweed polysaccharide fractionation expertise limits capacity expansion at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Polysaccharides Fucoidan Alginate Market |
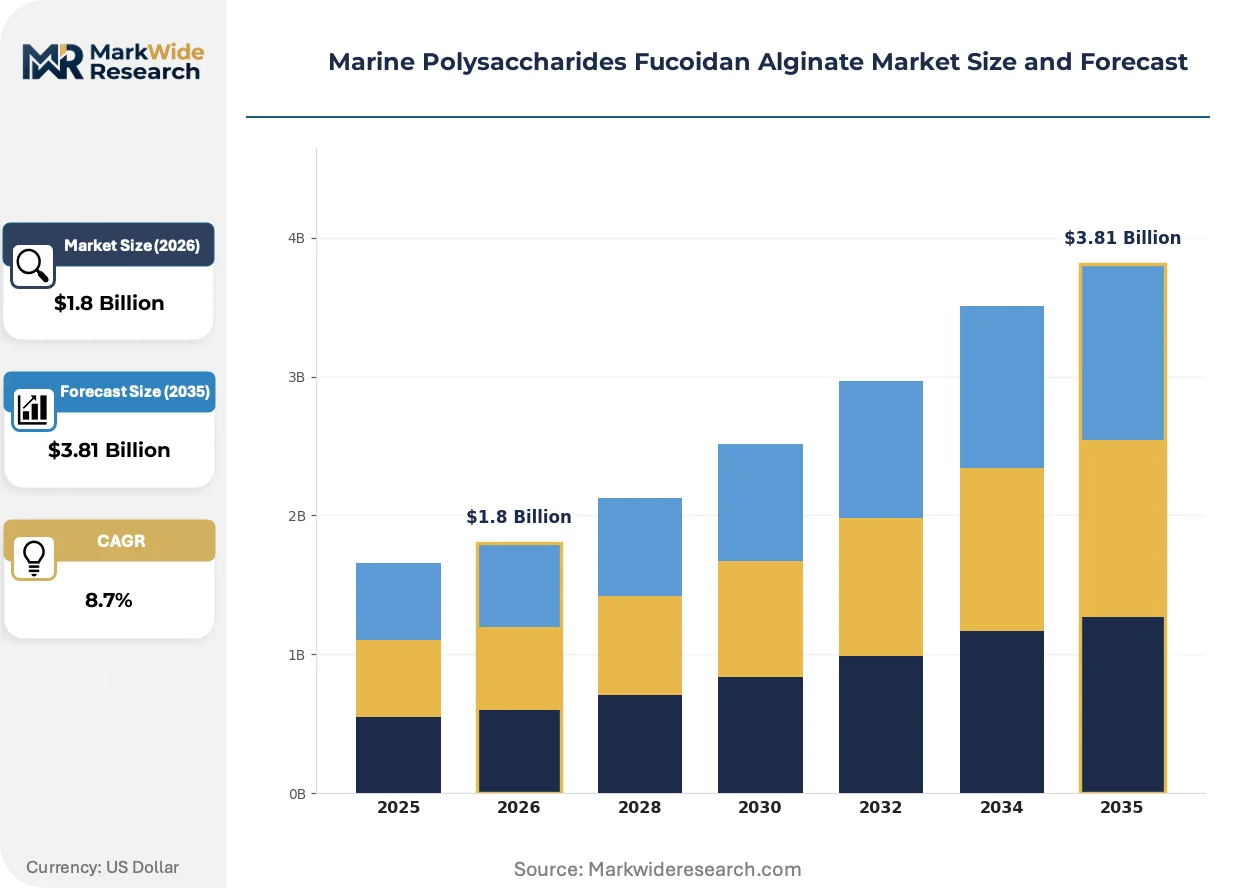
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fucoidan Extracts, Sodium Alginate, Potassium Alginate, Calcium Alginate, Alginate Powders Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Food & Beverages, Agricultural Additives End User: Pharmaceutical Manufacturers, Nutraceutical Producers, Cosmetic Companies, Food Processing Units, Agrochemical Firms Form: Powder, Liquid, Granules, Capsules, Tablets |
| Companies Covered | Cargill, CP Kelco, FMC Corporation, Kerry Group, Algaia, Gelymar, Ceamsa, KIMICA Corporation, Marine Biopolymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Polysaccharides Fucoidan Alginate Market Trends and Innovations
Enzymatic extraction protocols and precision fermentation alternatives are compressing traditional solvent-based processing economics while regulatory frameworks in Europe and Japan accelerate purity standard convergence.
Membrane filtration and chromatographic purification systems are expanding into fucoidan production lines, replacing ethanol precipitation and reducing solvent waste volumes. Pharmaceutical extractors in Japan and Germany are adopting these platforms to meet EMA residual solvent limits without yield sacrifice. This technology is expanding into mid-cap nutraceutical processors seeking premium-grade positioning without full GMP infrastructure investment.
EMA's 2023 update to excipient monographs and ECHA's expanded SVHC candidate list are forcing alginate processors to document supply chain contaminant exposure. European pharmaceutical formulators now require certificates of analysis covering 50+ heavy metal and pesticide parameters. High-purity sodium alginate for implantable devices faces the steepest compliance burden, with contract manufacturers auditing extraction sites directly.
Direct-to-consumer capsule and tablet formats are fragmenting traditional bulk powder distribution for fucoidan supplements. Online nutraceutical retailers in the United States and Japan are bypassing wholesale ingredient channels, sourcing finished extract products with branded bioactivity claims. This channel shift compresses B2B ingredient margins while rewarding extractors with in-house formulation and packaging capabilities.
Marine Polysaccharides Fucoidan Alginate Market Segmentation
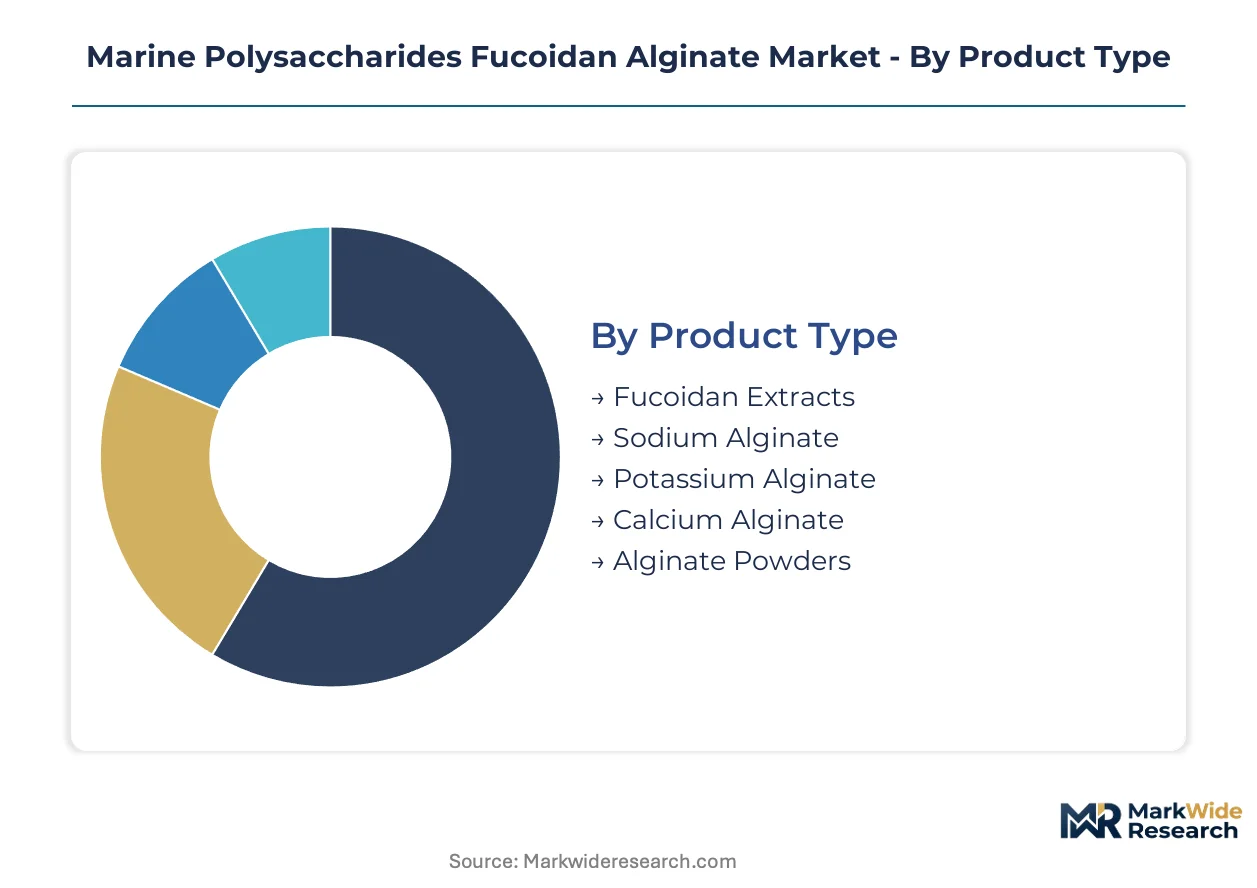
Segmentation in marine polysaccharides reveals how capital deployment, regulatory thresholds, and end-use specifications fragment production economics. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across extraction and formulation tiers.
Product Type:
Capital intensity varies sharply across extraction technologies, with pharmaceutical-grade fractionation requiring solvent recovery systems and chromatographic infrastructure that food-grade processors rarely deploy.
- Sodium Alginate:Linear copolymers of mannuronic and guluronic acid residues dominate food and beverage thickening applications. Demand concentrates in Japan and Germany where processors maintain GMP-certified facilities for dual food-pharma supply. Sodium alginate generates volume throughput but faces margin compression from synthetic hydrocolloid substitution.
- Fucoidan Extracts:Sulfated polysaccharides containing L-fucose and sulfate ester groups command premium positioning in immune-modulating supplements. Japanese nutraceutical formulators source high-purity grades under MHLW approval pathways, while European buyers impose REACH-compliant solvent documentation. Fucoidan extraction demands the steepest upfront investment in membrane filtration and heavy metal control systems.
- Potassium Alginate:Salt variant with modified gelling kinetics for controlled-release pharmaceutical matrices.
- Calcium Alginate:Cross-linked hydrogel precursor for wound dressing and cell encapsulation applications.
- Alginate Powders:Standardized particle-size grades for industrial food processing and agricultural coating systems.
Most installed capacity flows through Sodium Alginate. Expansion is steepest in Fucoidan Extracts.
Application:
Application-tier segmentation tracks how bioactivity substantiation requirements and regulatory gatekeeping fragment customer access and pricing power.
- Pharmaceuticals:Alginate hydrogels and fucoidan active pharmaceutical ingredients require EMA and FDA GMP validation cycles spanning 18-36 months. Japanese PMDA frameworks favor domestic processors with historical compliance records, creating supply concentration for implantable device and wound care matrix applications.
- Dietary Supplements:Direct-to-consumer capsule and tablet formats are bypassing traditional bulk powder channels. US online retailers demand finished extract products with branded bioactivity claims, compressing B2B ingredient margins while rewarding in-house formulation capabilities.
- Cosmetics:Bioactive carrier functions in premium skincare drive sulfate-content specification divergence between Japanese and European formulators.
- Food & Beverages:Sodium alginate thickening demand anchors volume but faces commoditization pressure from modified cellulose derivatives.
- Agricultural Additives:Encapsulation matrices for controlled-release fertilizer coatings.
Revenue concentration sits in Pharmaceuticals. Customer acquisition costs are climbing fastest in Dietary Supplements.
End User:
End-user segmentation exposes how procurement scale and specification stringency filter supplier eligibility across pharmaceutical, nutraceutical, and industrial channels.
- Pharmaceutical Manufacturers:EMA residual solvent limits and heavy metal thresholds require certificates of analysis covering 50+ parameters. European formulators conduct direct extraction site audits for implantable device grades, concentrating supply among German and Japanese processors with proven compliance infrastructure.
- Nutraceutical Producers:Immune-modulating supplement demand is expanding fucoidan incorporation, with Japan's Ministry of Health, Labour and Welfare providing established approval pathways that favor domestic sourcing relationships.
- Cosmetic Companies:Premium skincare formulators specify molecular weight and sulfate content thresholds that vary by target geography.
- Food Processing Units:Price-sensitive thickening applications where alginate functional performance faces synthetic substitution pressure.
- Agrochemical Firms:Controlled-release coating specifications for fertilizer and pesticide delivery systems.
Contract value peaks with Pharmaceutical Manufacturers. Account growth rates are highest among Nutraceutical Producers.
Form:
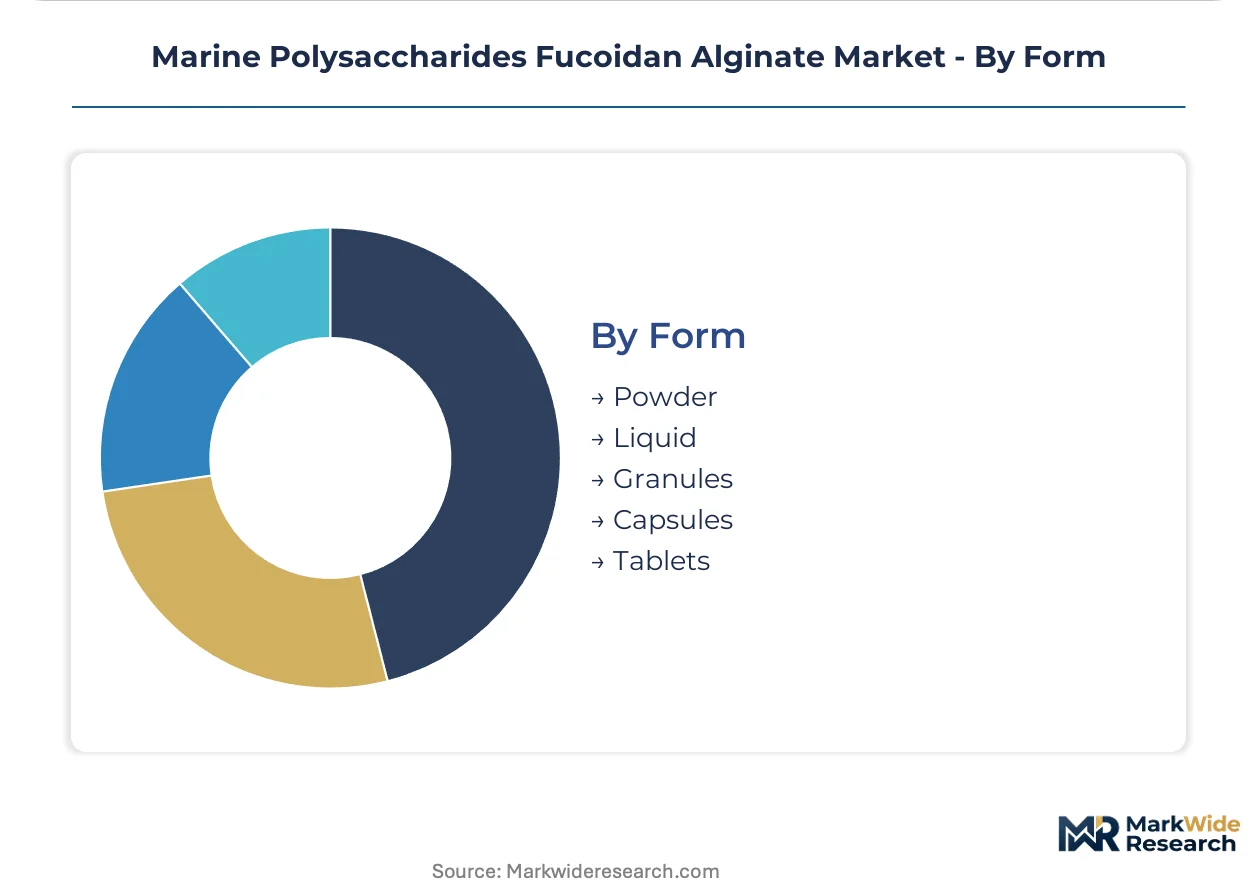
Form-factor segmentation tracks how handling efficiency, dosing precision, and channel economics reshape value capture between bulk ingredient and finished product tiers.
- Powder:Industrial handling efficiency dominates B2B distribution for food, pharma, and cosmetic formulation. Bulk powder throughput sustains alginate margin structures but faces channel compression as direct-to-consumer formats expand.
- Capsules:Direct-to-consumer nutraceutical channels in the United States and Japan are fragmenting traditional wholesale distribution. Online retailers source finished extract products with branded bioactivity claims, rewarding extractors with in-house encapsulation and packaging capabilities.
- Tablets:Compressed dosing formats for standardized fucoidan supplement regimens.
- Liquid:Suspension and solution formats for beverage fortification and topical delivery systems.
- Granules:Intermediate particle-size grades for agricultural coating and controlled-release matrix preparation.
Volume throughput concentrates in Powder. Value per kilogram is expanding most quickly in Capsules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial extraction of marine polysaccharides originated in Japanese coastal processing facilities during the mid-20th century, establishing quality benchmarks that persist in today's pharmaceutical-grade specifications. Contemporary demand patterns reflect both this historical foundation and divergent regulatory frameworks across major consuming markets.
Japan
KIMICA Corporation and domestic processors command advanced extraction capabilities serving immune-modulating supplement demand. Japan's Ministry of Health, Labour and Welfare maintains distinct pharmaceutical-grade specifications that favor established compliance records. Tokyo-Osaka industrial corridors concentrate GMP-certified fractionation infrastructure for both domestic nutraceutical brands and export pharmaceutical contracts.
Germany
EMA residual solvent limits and ECHA REACH frameworks filter supplier eligibility for alginate excipients used in implantable medical devices. German processors deploy membrane filtration and chromatographic purification systems to meet expanded SVHC documentation requirements. Hamburg and Bremerhaven port clusters facilitate seaweed biomass importation for North Rhine-Westphalia extraction facilities.
United States
FDA dietary supplement GMP oversight shapes fucoidan purity thresholds and label claim substantiation for domestic-bound products. FMC Corporation anchors North American availability through controlled harvesting partnerships spanning Pacific and Atlantic coastal zones. California and Massachusetts nutraceutical formulators drive direct-to-consumer capsule and tablet format demand.
China
Domestic alginate production scales through integrated seaweed farming and extraction operations serving food-grade thickening applications. NMPA pharmaceutical excipient registration requirements are tightening for imported marine-derived biomaterials. Qingdao and Dalian coastal processing zones concentrate sodium alginate output for regional food processing and agricultural coating markets.
Marine Polysaccharides Fucoidan Alginate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade extractors commanding pricing multiples over food-grade processors. The competitive terrain organizes around three strategic archetypes: integrated seaweed-to-extraction operators, specialized fucoidan fractionators, and diversified hydrocolloid portfolios. Capacity expansion and backward integration into controlled harvesting partnerships represent the dominant competitive moves as raw material security displaces price competition.
Within the integrated extraction tier, CP Kelco leverages its captive seaweed supply network to sustain consistent alginate output across food and pharmaceutical grades. FMC Corporation exemplifies North American market anchoring through controlled harvesting partnerships and extraction scale. Gelymar occupies a specialist position in fucoidan fractionation, targeting high-purity extract segments where bioactivity substantiation commands premium positioning. These three entities represent distinct strategic postures: supply security, geographic dominance, and product specialization.
| Leading Market Players |
|---|
| Cargill |
| CP Kelco |
| FMC Corporation |
| Kerry Group |
| Algaia |
| Gelymar |
| Ceamsa |
| KIMICA Corporation |
| Marine Biopolymers |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical manufacturers in Japan and Germany anchor procurement volume for pharmaceutical-grade alginate and fucoidan extracts, concentrating purchasing power among buyers with GMP-certified supply requirements and long-term contract preferences. This buyer concentration sustains premium pricing tiers for REACH-compliant and MHLW-approved grades while compressing margins for food-grade sodium alginate facing synthetic hydrocolloid substitution.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-grade levels segments the market by certification intensity and purity thresholds. Price differentiation hinges on EMA residual solvent documentation and heavy metal testing breadth, with pharmaceutical-grade extracts commanding multiples over standard food thickeners. Cost compression in food-grade sodium alginate is intensifying because modified cellulose derivatives capture price-sensitive applications. Nutraceutical capsule formulators show least price sensitivity due to branded bioactivity claim substantiation requirements.
Supply Chain Analysis
Japan's MHLW domestic-content preferences and EU Green Deal procurement criteria are reshaping sourcing toward carbon-accounted supply chains with circular extraction methods. Geographic supply concentration centers on Japan, Germany, and China, with Japanese processors drawing from North Pacific kelp forests and German facilities feeding from North Atlantic biomass. Raw material dependencies rest on brown seaweed availability, solvent recovery infrastructure, and chromatographic purification systems. Single-source vulnerability runs through climate-driven kelp forest degradation in North Atlantic zones. Distribution runs through direct extraction site relationships for pharmaceutical grades and wholesale ingredient channels for food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine polysaccharides market has entered a late-cycle quality phase where immune-modulating supplement demand shifts procurement toward premium fucoidan grades with substantiated bioactivity claims. This specification escalation rewards processors with GMP infrastructure and compliant documentation capabilities.
For Market Incumbents: Hedge against synthetic hydrocolloid substitution in food-grade alginate by deepening backward integration into controlled harvesting partnerships across Pacific and Atlantic coastal zones. Reinforce pharmaceutical-grade positioning through membrane filtration capacity additions in Germany and Japan to capture EMA residual solvent compliance premiums. Channel control through in-house capsule and tablet formulation capabilities defends margin structures against direct-to-consumer channel compression.
For New Entrants and Emerging Players: Mid-scale nutraceutical processors in the United States represent an underserved buyer archetype seeking premium-grade fucoidan without full GMP infrastructure investment. White-space targets include probiotic encapsulation coacervation systems and wound care hydrogel matrix supply to contract manufacturers. The most penetrable entry point runs through enzymatic extraction technology licensing for solvent-free processing routes. A technical partnership positioning with established Japanese extractors accelerates MHLW approval pathway navigation.
For Investors and Strategic Acquirers: Nutraceutical formulators with direct-to-consumer channel capabilities are the most active acquirer in this space, seeking backward integration into extract supply security. The five-to-ten year viability window favors processors with dual food-pharma certification infrastructure and carbon-accounted supply chain documentation. Acquisition targets should display proven EMA and MHLW compliance records with solvent-recovery capabilities. The signal to watch is REACH SVHC list expansion frequency as a proxy for regulatory compliance cost escalation and supplier filtering intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Harvesting | Secures kelp biomass access against climate-driven North Atlantic and North Pacific supply volatility. |
| Membrane Filtration Capacity Expansion | Enables EMA residual solvent compliance without yield sacrifice for pharmaceutical-grade alginate output. |
| Enzymatic Extraction Technology Deployment | Replaces chlorinated solvent routes prohibited under REACH frameworks with lower-waste processing economics. |
| In-House Capsule and Tablet Formulation | Captures direct-to-consumer channel margins bypassing wholesale ingredient distribution compression. |
| EU Green Deal Certification Program | Qualifies processors for European pharmaceutical and nutraceutical sustainability-preferred procurement criteria. |
Research Methodology
Multiple input streams — extraction technology assessments, regulatory filing documentation, and procurement pattern analysis — were reconciled through structured primary interviews with brown seaweed polysaccharide process chemists, pharmaceutical excipient procurement managers, nutraceutical formulation directors, and GMP compliance auditors. Secondary validation drew from EMA excipient monograph updates, ECHA SVHC candidate list revisions, MHLW approval pathway records, and customs trade data for sodium alginate and fucoidan extract flows. Bottom-up volume modeling across extraction capacity and top-down demand segmentation were triangulated to constrain estimate variance.
Data-stream reconciliation anchored forecast construction across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, form factor, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and capacity expansion pipeline tracking. Forecast inputs incorporated kelp forest biomass yield projections and enzymatic extraction technology adoption curves as industry-specific variables.
Underlying measurement precision varies by segment; pharmaceutical-grade extracts with documented GMP compliance carry tighter precision than emerging nutraceutical capsule formats. Forecasts reflect assumptions regarding regulatory framework stability, seaweed biomass availability, and substitution elasticity for synthetic hydrocolloids. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Prokaryotic Expression Systems Market