
 US Genetic Testing Market | 2026-2036
US Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Genetic Testing Market Intelligence
CLIA certification is rotating toward higher-complexity molecular standards, filtering out smaller laboratories that lack the capital for quality-system upgrades. Quest Diagnostics leverages its national specimen-collection network to sustain volume leadership in hereditary cancer panels. Illumina anchors the upstream reagent supply chain through its sequencing-platform installed base. Myriad Genetics specializes in proprietary risk-algorithms that differentiate its oncology offerings from commodity testing services.
Genetic testing encompasses the laboratory analysis of DNA, RNA, chromosomes, proteins, and metabolites to detect heritable or acquired variations, typically requiring nucleic-acid extraction, amplification via PCR or hybridization-based microarray methods, and bioinformatic interpretation against curated variant databases. Its primary commercial purpose spans diagnostic confirmation, therapeutic selection, reproductive risk-assessment, and population-health screening. Pharmacogenomic testing captures expanding margin pools as payers tighten reimbursement for broad panel tests without clinical-actionability evidence. Next-generation sequencing displaces Sanger methods in oncology applications where multi-gene hotspot analysis delivers faster turnaround at lower per-gene cost. Direct-to-consumer companies face structural pressure as FDA and state health departments impose physician-oversight requirements on health-risk reporting.
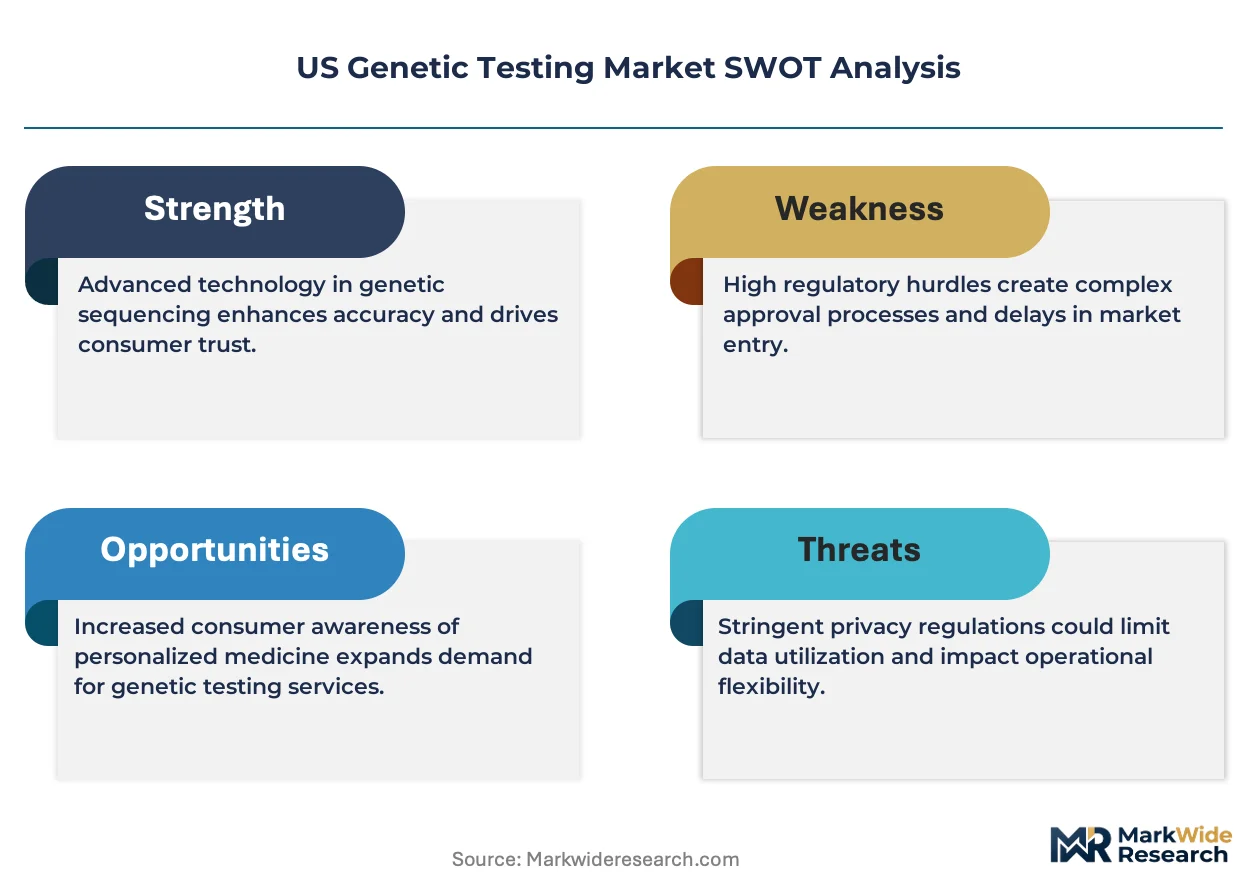
FDA, CMS, and state laboratory licensing boards collectively govern market access through premarket review of novel devices, reimbursement coding for molecular diagnostics, and proficiency-testing mandates under CLIA. These overlapping frameworks create compliance costs that favor scaled operators with dedicated regulatory-affairs functions. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled variant-interpretation tools and CMS national-coverage determinations for liquid-biopsy screening.
Market Dynamics
CLIA certification rotation toward higher-complexity molecular standards is filtering capital-constrained laboratories from the US genetic testing market, concentrating volume among scaled operators with dedicated quality-system infrastructure.
Growth Catalysts
- Oncology Screening Expansion:Hospital systems are integrating hereditary cancer panels into standard-of-care protocols, creating sustained demand for multi-gene hotspot analysis.
- CMS Reimbursement Evolution:National coverage determinations for next-generation sequencing in advanced cancers are expanding patient access to molecular profiling.
- Pharmacogenomic Clinical Integration:Payer pressure for evidence-based prescribing is driving adoption of drug-gene interaction testing in cardiology and psychiatry practices.
Market Restraints
- Reagent Supply Concentration:Upstream dependence on a single sequencing-platform installed base creates vulnerability in consumable pricing and availability.
- FDA Premarket Review Burden:Laboratory-developed test oversight expansion is extending validation timelines and compliance costs for novel assay introductions.
- Sanger Method Residual Demand:Single-gene confirmation testing retains niche applications where NGS turnaround exceeds clinical urgency requirements.
Strategic Opportunities
- Liquid Biopsy Screening:CMS national coverage determination processes for circulating tumor DNA assays represent a pending reimbursement frontier in asymptomatic population screening.
- Artificial Intelligence Variant Interpretation:FDA guidance development on machine-learning-enabled classification tools is creating first-mover advantage for algorithm-validating laboratories.
- Direct-to-Consumer Physician Oversight:State health department mandates for clinician-mediated result delivery are opening B2B partnership channels between testing platforms and telemedicine networks.
Industry Challenges
- Bioinformatician Talent Scarcity:Variant curation and pipeline development functions face recruitment competition from technology and pharmaceutical sectors.
- Proficiency Testing Complexity:CLIA-mandated external quality assessment for rare variant detection strains reference material availability and inter-laboratory comparison infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Genetic Testing Market |
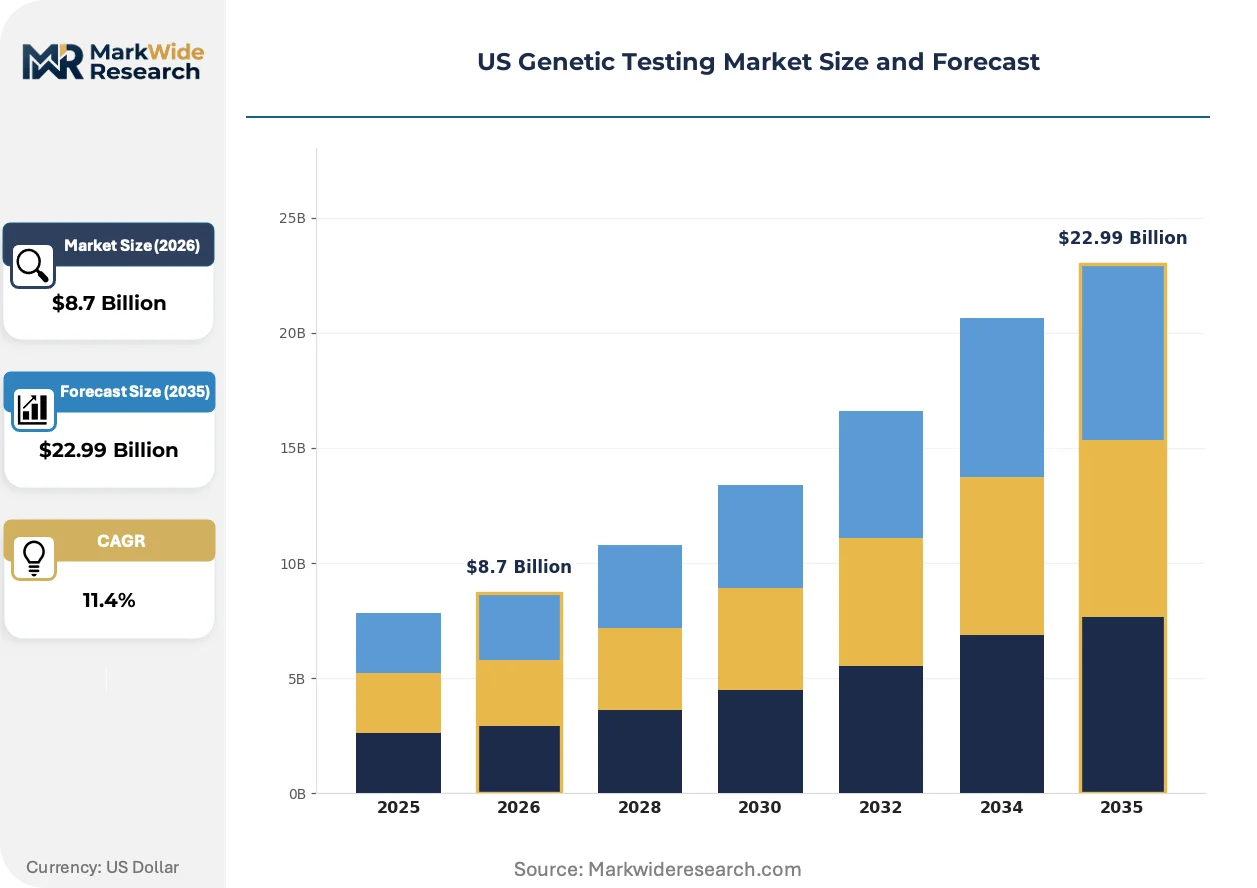
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Diagnostic, Carrier, Prenatal, Pharmacogenomic, Nutrigenomic, Predictive Technology: Next-Generation Sequencing, Microarray, PCR, Sanger Sequencing, CRISPR, Massively Parallel Sequencing Application: Oncology Screening, Rare Disorders, Personalized Medicine, Ancestry Analysis, Prenatal Diagnostics, Reproductive Health End User: Hospitals, Diagnostic Laboratories, Research Institutes, Direct-to-Consumer Companies, Academic Centers, Biotechnology Firms |
| Companies Covered | Quest Diagnostics, Myriad Genetics, Invitae, Ambry Genetics, Illumina, Labcorp, 23andMe, Natera, GeneDx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Genetic Testing Market Strategic Shifts & Innovations
Next-generation sequencing workflows are compressing from centralized reference laboratories toward distributed point-of-care deployment, reshaping capital allocation and technical support models across the US diagnostic landscape.
Point-of-care molecular diagnostic platforms are miniaturizing nucleic-acid extraction, amplification, and detection into cartridge-based systems operable by non-specialist clinical staff. Community oncology practices and urgent care networks are piloting these devices to reduce specimen transport delays. This distributed architecture is miniaturizing the traditional hub-and-spoke laboratory network, fragmenting volume among lower-throughput sites and compressing the addressable market for centralized high-complexity facilities.
FDA draft guidance on artificial-intelligence-enabled variant-interpretation tools is establishing premarket review expectations for machine-learning-based classification algorithms. Laboratories deploying these systems must now document training dataset provenance and performance across ancestry-representative cohorts. Hereditary cancer screening panels are most affected, with several laboratories augmenting internal validation teams to address FDA documentation requirements before formal rule finalization.
Employer-sponsored wellness programs are contracting directly with genetic testing platforms for pharmacogenomic screening, bypassing traditional payer reimbursement pathways. Large self-insured employers in manufacturing and logistics sectors are leading this channel innovation, seeking to reduce adverse drug event costs. Texas and California employer coalitions are most visible in this procurement pattern, negotiating population-level pricing for workforce medication safety programs.
US Genetic Testing Market Segmentation
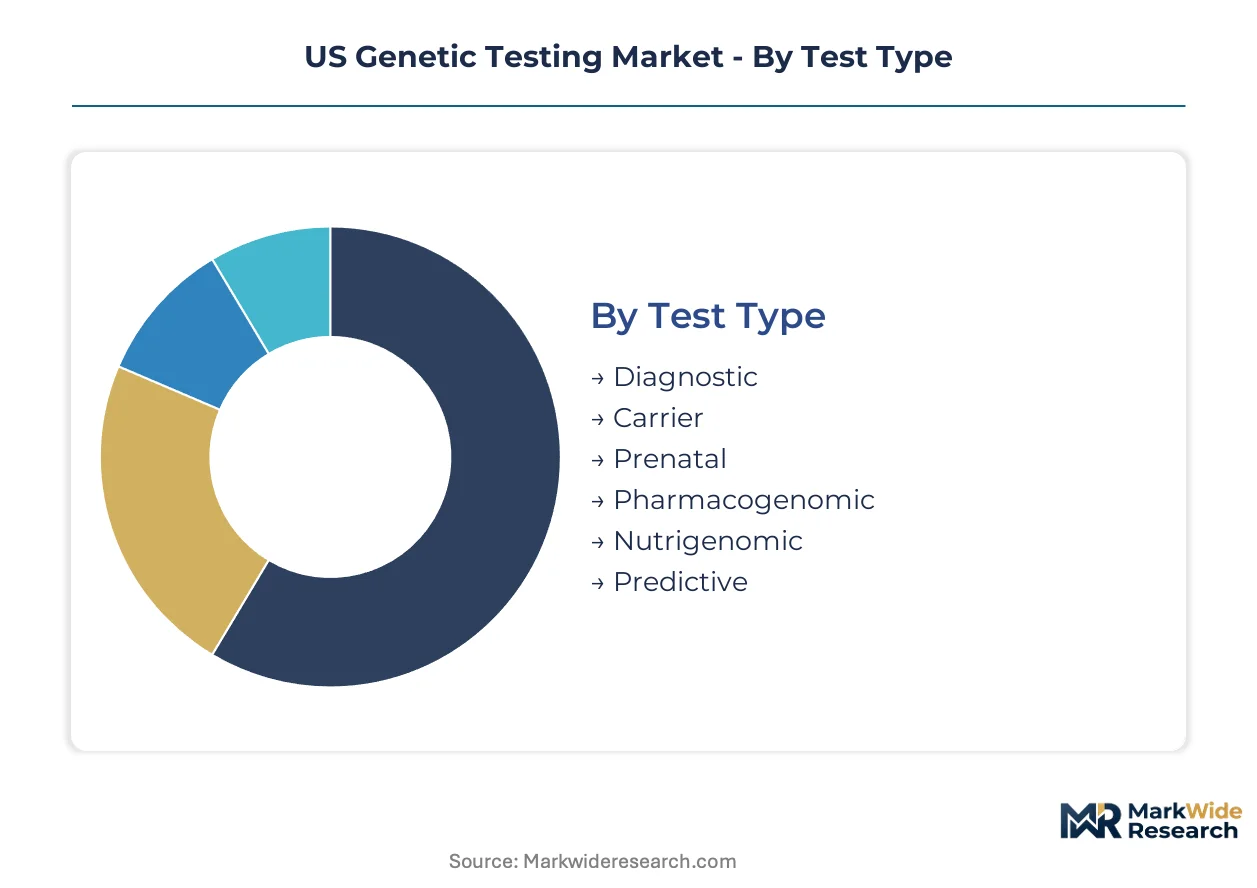
Genetic testing segments fragment along clinical utility and reimbursement pathways, with oncology and pharmacogenomic applications commanding premium pricing while ancestry and direct-to-consumer channels face margin compression from regulatory tightening. Technology choices determine capital intensity and turnaround economics, shaping competitive positioning across hospital systems and reference laboratories.
Test Type:
Margin pools concentrate in diagnostic and pharmacogenomic testing where clinical actionability justifies payer reimbursement at elevated price points.
- Diagnostic:Confirms suspected hereditary conditions through targeted gene analysis, typically following clinical presentation. Hospital oncology departments in California and Massachusetts drive volume as hereditary cancer panels integrate into standard-of-care protocols for breast, colorectal, and prostate malignancies.
- Pharmacogenomic:Analyzes drug-gene interactions to guide therapeutic selection and dosing. Texas employer coalitions and self-insured manufacturing firms are contracting directly for workforce medication safety programs, bypassing traditional CMS reimbursement pathways.
- Carrier:Screens asymptomatic individuals for recessive disorder risk before reproduction. Reproductive endocrinology practices concentrate demand in urban coastal markets.
- Prenatal:Detects fetal chromosomal abnormalities through cell-free DNA analysis. Maternal-fetal medicine specialists in academic medical centers anchor volume.
- Nutrigenomic:Correlates genetic variants with metabolic responses to dietary components. Wellness program administrators and functional medicine practices sustain niche demand.
- Predictive:Estimates disease probability before symptom onset. Direct-to-consumer regulatory constraints are compressing commercial viability as FDA and state health departments impose physician-oversight mandates.
Diagnostic testing holds installed capacity. Pharmacogenomic testing is rotating up the share rankings.
Technology:
Volume distribution tracks platform throughput economics, with next-generation sequencing capturing multi-gene analysis while PCR retains single-target dominance.
- Next-Generation Sequencing:Enables simultaneous analysis of hundreds to thousands of genes through massively parallel readout. Oncology hotspot panels and hereditary cancer screening in hospital systems concentrate demand as per-gene cost collapses below Sanger alternatives.
- PCR:Amplifies targeted DNA segments through thermal cycling for rapid, cost-effective detection. Infectious disease and pharmacogenomic point-of-care applications in community oncology and urgent care networks sustain volume leadership.
- Microarray:Hybridizes nucleic acid samples against fixed probe sets for copy number variation and SNP detection. Prenatal cytogenetics and ancestry applications anchor residual demand.
- Sanger Sequencing:Performs chain-termination analysis for single-gene confirmation. Niche clinical urgency applications where NGS turnaround exceeds therapeutic decision windows retain utility.
- CRISPR:Deploys programmable nucleases for diagnostic signal amplification and detection. Research-stage applications in academic centers are advancing toward clinical validation.
- Massively Parallel Sequencing:Represents high-throughput NGS variants optimized for population-scale screening. Liquid biopsy development programs in biotechnology firms concentrate pilot deployment.
PCR maintains the largest installed base. Next-generation sequencing is climbing the fastest in oncology application share.
Application:
Revenue concentration aligns with reimbursement density, where oncology screening and personalized medicine extract premium pricing from payers and self-funded employers.
- Oncology Screening:Profiles tumor and germline mutations to guide therapeutic selection and surveillance. Hospital systems across California, Massachusetts, and Texas are integrating hereditary panels into standard protocols, with CMS national coverage determinations expanding patient access.
- Personalized Medicine:Matches therapeutic interventions to individual molecular profiles. Cardiology and psychiatry practices are adopting pharmacogenomic protocols under payer pressure for evidence-based prescribing.
- Rare Disorders:Identifies causative variants in Mendelian conditions through exome or genome sequencing. Academic medical centers with specialized genetics services concentrate diagnostic referrals.
- Prenatal Diagnostics:Screens for fetal aneuploidy and microdeletions through maternal blood sampling. Maternal-fetal medicine specialists in metropolitan hospital systems sustain volume.
- Reproductive Health:Supports in vitro fertilization through preimplantation genetic testing. Fertility clinic networks in coastal states anchor commercial demand.
- Ancestry Analysis:Traces geographic origins through population genetics reference panels. Direct-to-consumer regulatory pressure is constraining health-risk reporting and compressing margins.
Oncology screening commands the deepest reimbursement. Personalized medicine is gaining share fastest as clinical integration accelerates.
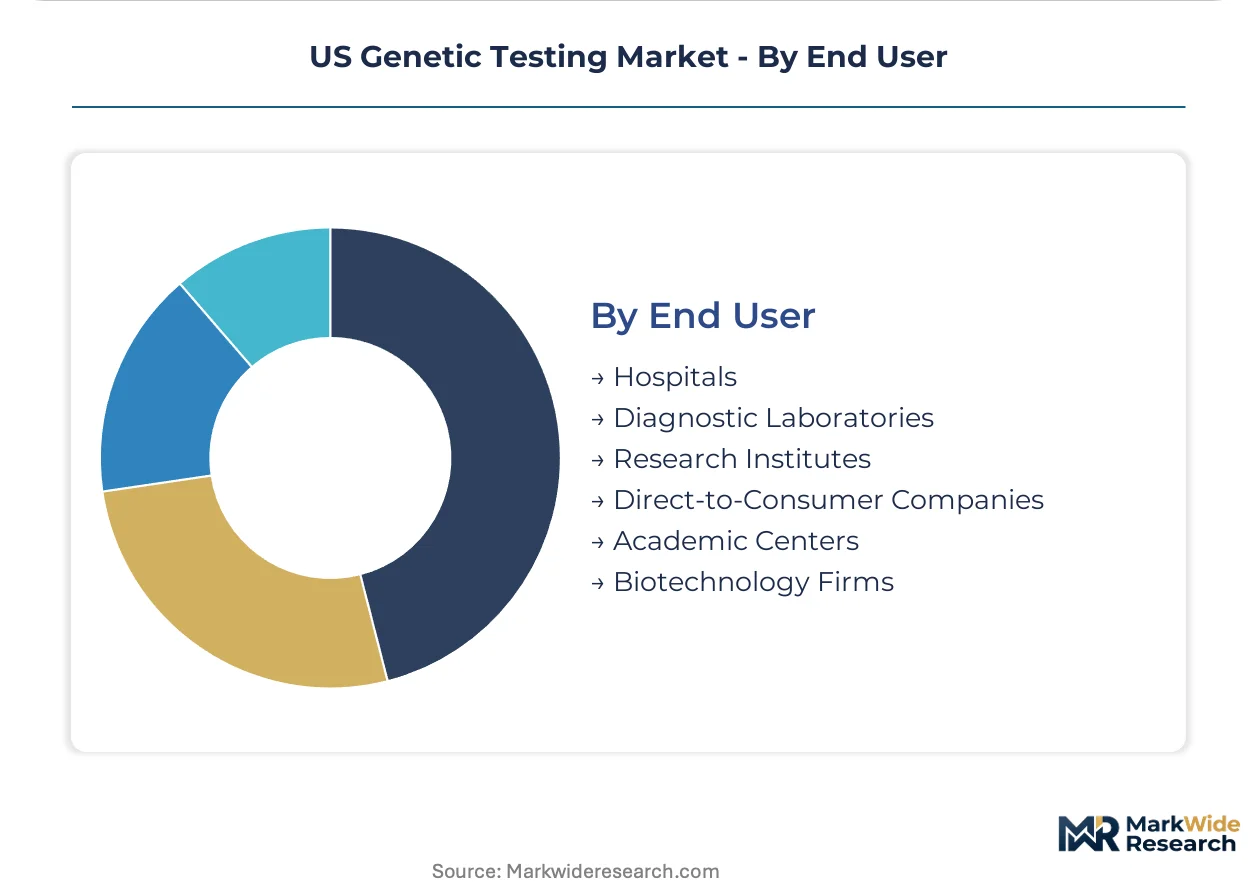
End User:
Procurement authority determines pricing power, with hospital systems and diagnostic laboratories extracting volume discounts while research institutes prioritize technical specifications.
- Hospitals:Integrate genetic testing into clinical workflows for inpatient and outpatient decision support. IDN consolidation in California and Texas is centralizing laboratory procurement and favoring multi-year service contracts with national reference laboratories.
- Diagnostic Laboratories:Process specimens from referring physicians under CLIA certification. Quest Diagnostics and scaled operators are sustaining volume leadership through national collection networks and quality-system infrastructure.
- Research Institutes:Advance biomarker discovery and validation through academic-industry collaboration. NIH-funded centers concentrate demand for novel assay development and prospective cohort studies.
- Direct-to-Consumer Companies:Market genetic testing without clinician intermediation. FDA and state health department oversight mandates are forcing physician-oversight partnerships and elevating compliance costs.
- Academic Centers:Combine clinical service with research and training missions. Hereditary cancer and rare disease programs anchor specialized referral volume.
- Biotechnology Firms:Deploy genetic testing for companion diagnostic development and clinical trial enrollment. Liquid biopsy and AI-enabled variant interpretation pipelines concentrate investment.
Diagnostic laboratories retain the broadest installed capacity. Hospitals are rotating up the share rankings as IDN laboratory consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and self-insured employers concentrate procurement authority in three state-level clusters where laboratory infrastructure and reimbursement density align.
California
Hereditary cancer panel integration into Stanford and UCSF standard-of-care protocols drives hospital laboratory demand. FDA premarket review timelines for novel oncology assays compress competitive windows for local biotechnology firms. The San Francisco-San Jose biotech corridor anchors liquid biopsy development programs and AI-enabled variant interpretation pipelines.
Massachusetts
Academic medical center consolidation around Partners Healthcare and Mass General Brigham centralizes specialized genetics referrals. CMS national coverage determinations for next-generation sequencing expand patient access across Harvard-affiliated hospital networks. The Cambridge-Boston research cluster concentrates rare disease diagnostic volume and companion diagnostic development partnerships.
Texas
Self-insured employer coalitions in manufacturing and logistics sectors contract directly for pharmacogenomic workforce screening. State health department physician-oversight mandates reshape direct-to-consumer distribution channels toward telemedicine partnerships. The Dallas-Houston-Austin diagnostic hub attracts reference laboratory expansion and point-of-care platform pilots.
New York
Integrated delivery network laboratory procurement centralization favors multi-year service contracts with national reference laboratories. CLIA certification rotation toward higher-complexity molecular standards filters capital-constrained local operators. The New York City metropolitan area sustains prenatal diagnostic volume through maternal-fetal medicine specialist concentration.
Illinois
Community oncology practice consolidation into larger health systems compresses specimen transport economics toward distributed point-of-care molecular platforms. Payer pressure for evidence-based prescribing drives pharmacogenomic protocol adoption in cardiology practices. The Chicago-Northwest Indiana corridor anchors Midwest reference laboratory networks serving secondary hospital markets.
US Genetic Testing Market Key Industry Players
Player mix skews toward vertically integrated reference laboratories and specialized molecular diagnostic firms. National specimen-collection networks and quality-system infrastructure create scale advantages that filter smaller CLIA-certified operators. Two strategic archetypes dominate: scaled reference laboratories with broad test menus and specialized firms with proprietary risk algorithms or platform technologies. Competitive moves concentrate on laboratory network consolidation and multi-year integrated delivery network service contracting.
Within the reference laboratory archetype, Quest Diagnostics and Labcorp occupy positions sustained by national collection infrastructure and hospital system procurement relationships. Among specialized molecular diagnostic firms, Myriad Genetics exemplifies the proprietary algorithm-differentiation model in hereditary cancer screening. Illumina anchors the upstream reagent supply chain through sequencing-platform installed base control. These three firms represent distinct competitive positioning vectors: specimen access, clinical interpretation, and technology supply.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Myriad Genetics |
| Invitae |
| Ambry Genetics |
| Illumina |
| Labcorp |
| 23andMe |
| Natera |
| GeneDx |
| Others |
Cost & Logistics Intelligence
Sequencing-platform installed base concentration at Illumina creates asymmetric scale economics that compress per-test reagent costs for high-volume operators while elevating price floors for smaller CLIA-certified laboratories lacking procurement leverage. This supply-side concentration feeds directly into pricing power asymmetry across hospital system contracts and direct-to-consumer channels.
Pricing Analysis
Cost-plus contracts with reagent price indexation to semiconductor and specialty-chemical commodity baskets dominate multi-year agreements between reference laboratories and hospital procurement committees. Pricing stratifies across premium, standard, and economy tiers based on turnaround time guarantees and bioinformatic interpretation depth. Price erosion runs through direct-to-consumer ancestry segments as FDA physician-oversight mandates elevate compliance costs. Self-insured employer pharmacogenomic programs exhibit lowest price sensitivity due to adverse drug event cost-avoidance framing.
Supply Chain Analysis
Just-in-time reagent inventory strategies prevail among centralized reference laboratories, while point-of-care platform operators maintain strategic stockpiles of cartridge consumables to buffer supply disruption. Upstream nucleic-acid extraction chemistries and flow-cell manufacturing concentrate in the United States, Singapore, and Germany. Single-source vulnerability in sequencing-instrument consumables creates exposure to tariff escalation on precision-optical components. Distribution runs through cold-chain logistics networks anchored by national specimen-collection infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioinformatician talent scarcity constrains pipeline development velocity, with recruitment competition from pharmaceutical and technology sectors creating structural bottlenecks for assay-validation throughput.
For Market Incumbents: Compound CLIA quality-system infrastructure advantages through targeted acquisition of regional molecular diagnostic laboratories facing certification-upgrade capital constraints. Defend specimen-access moats by deepening integration with telemedicine networks for direct-to-consumer physician-oversight compliance. Prioritize algorithm-validation investments ahead of FDA artificial-intelligence guidance finalization. For New Entrants and Emerging Players: Lead with liquid biopsy screening development programs targeting CMS national coverage determination windows before incumbent reimbursement lock-in. Employer-sponsored pharmacogenomic wellness programs in Texas and California manufacturing sectors represent the most penetrable white-space channel. Pursue B2B platform licensing rather than clinical-laboratory buildout to bypass collection-network scale requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among proprietary risk-algorithm developers with hereditary cancer panel installed bases. Five-to-ten-year viability hinges on FDA premarket review navigation capabilities and multi-payer contract density. Monitor CMS national coverage determination timelines for circulating tumor DNA assays as inflection indicators for liquid biopsy segment repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Variant Interpretation Validation | FDA guidance compliance creates first-mover advantage for algorithm-documenting laboratories ahead of formal rulemaking. |
| Telemedicine Network Partnership | State physician-oversight mandates force direct-to-consumer channel restructuring toward clinician-mediated result delivery. |
| Liquid Biopsy Reimbursement Strategy | CMS national coverage determination processes represent the decisive regulatory gateway for asymptomatic screening expansion. |
| Employer Direct Contracting Channel | Self-insured manufacturing and logistics coalitions in Texas bypass traditional payer pathways for pharmacogenomic volume. |
| Point-of-Care Platform Deployment | Cartridge-based miniaturization fragments specimen volume toward distributed sites and compresses centralized laboratory economics. |
Research Approach
A standing panel of CLIA laboratory directors, hospital procurement executives, payer medical policy specialists, and bioinformatics pipeline architects provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) and PMA filing databases, CMS national coverage determination records, Clinical Laboratory Fee Schedule updates, and state health department licensing board enforcement actions. Bottom-up test-volume modeling and top-down reimbursement expenditure analysis were cross-triangulated for consistency.
Outputs were stress-tested against external benchmarks including CMS molecular diagnostic spending trends and commercial payer claims data across the projection horizon. Segmentation dimensions encompassed test type, technology platform, clinical application, and end-user procurement authority. CAGRs were derived from logistic adoption-curve fitting to hospital system integration timelines and employer wellness program penetration patterns. Forecast inputs incorporated CLIA certification rotation timelines and FDA artificial-intelligence guidance development trajectories.
Underlying assumptions cover reimbursement stability for multi-gene oncology panels, with deviation risk concentrated in CMS national coverage determination reversals and state laboratory licensing board enforcement intensification. Revision becomes warranted when liquid biopsy screening coverage thresholds cross commercial payer medical-necessity criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Global Gene Expression Market
Genomics
NGS Automation Market
Genomics
Genetic Testing Market
Genomics
Global NGS Sample Preparation Market
Genomics
Gene Sequencing Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Animal Genetics Market
Genomics
Global Optical Genome Mapping Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Reproductive Genetics Market
Genomics
Genetic Material Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Genomics Personalized Health Market
Genomics
DNA Sequencing Market