
 Global Alpha Galactosidase Market | 2026-2036
Global Alpha Galactosidase Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alpha Galactosidase Market Foresight
Recombinant expression platform convergence is narrowing the cost gap between microbial and mammalian cell production systems for therapeutic alpha galactosidase. Novozymes leverages its industrial fermentation infrastructure to supply research-grade enzymes across preclinical pipelines. Protalix Biotherapeutics anchors its position through proprietary plant-cell-based expression technology that sidesteps mammalian cell culture limitations. JCR Pharmaceuticals competes on geographic dominance in Asia-Pacific distribution for enzyme replacement therapies.
Alpha galactosidase is a glycoside hydrolase enzyme (EC 3.2.1.22) that catalyzes the hydrolysis of terminal alpha-galactosyl moieties from glycolipids and glycoproteins, operating optimally at pH 4.5-6.5 and requiring divalent cation cofactors for structural stability; recombinant forms are manufactured via fed-batch fermentation in CHO or plant-cell systems for therapeutic applications, while fungal-derived preparations serve food and feed industries. Powder enzyme formulations dominate industrial procurement due to superior shelf stability and freight economics, though liquid enzymes represent the fastest-growing format in automated food processing lines where dosing precision matters. Capsule formulations capture concentrated margin pools in the nutraceutical channel as consumers self-direct digestive health spending.
FDA orphan drug incentives and EMA's PRIME designation scheme for rare disease therapies shape clinical development economics and market exclusivity timelines for enzyme replacement products. Japan's PMDA Sakigake pathway accelerates review for innovative biologics, compressing commercialization schedules for new entrants. REACH compliance in Europe and evolving GB standards in China impose purity and endotoxin specifications that filter contract manufacturing qualifications. Stakeholders must monitor regulatory convergence on biosimilar substitution rules for long-entrenched enzyme therapies.
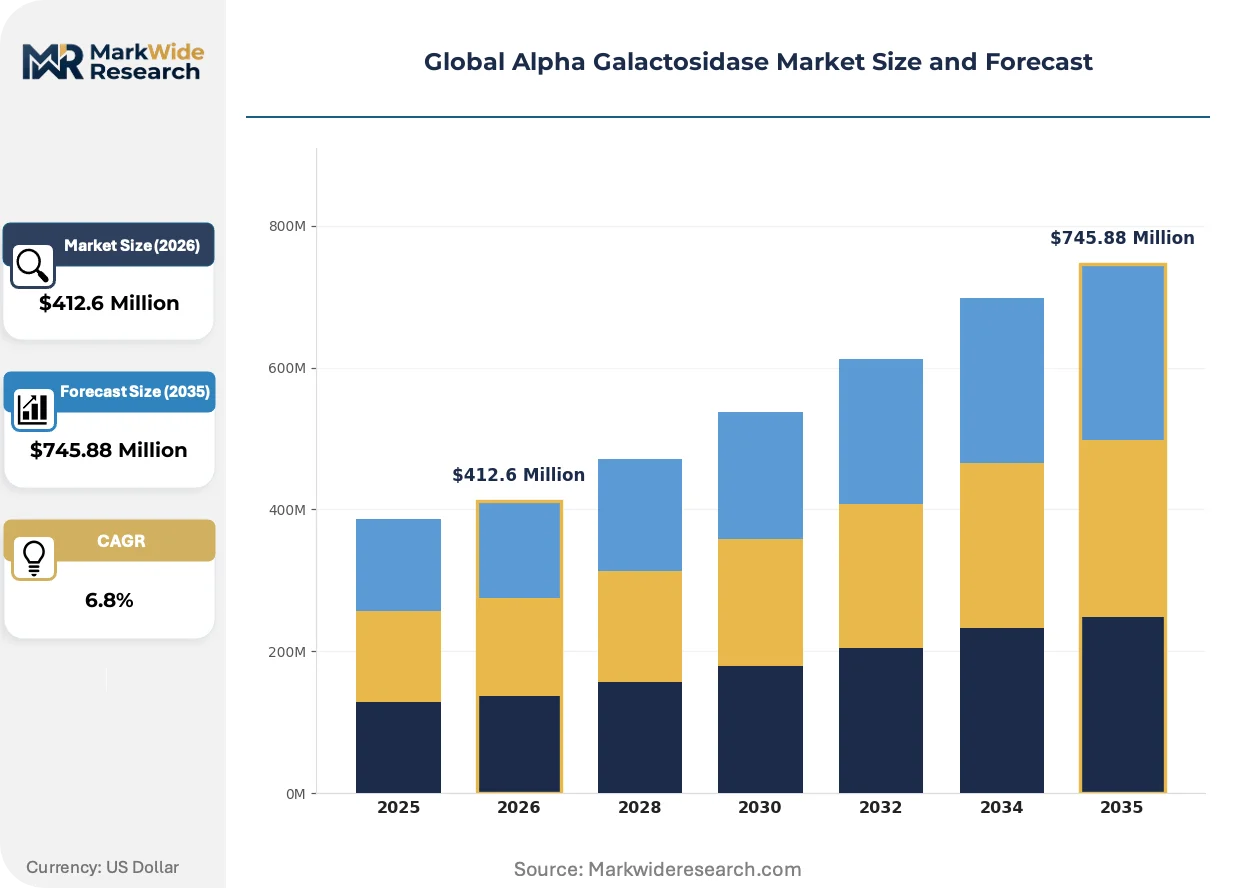
Market Dynamics
FDA's accelerated approval pathways for orphan enzyme drugs are compressing competitive entry timelines while recombinant expression platform convergence narrows production cost differentials between microbial and mammalian cell systems.
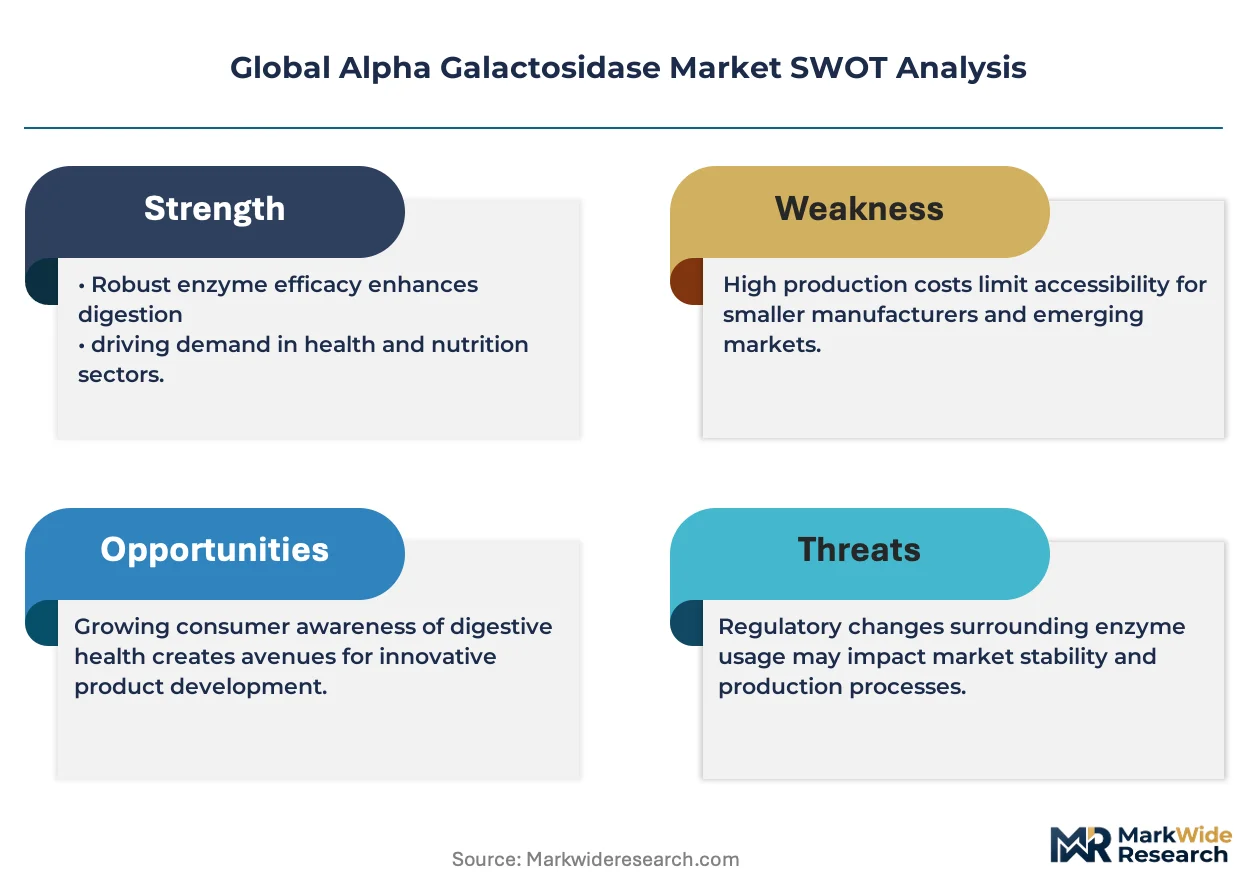
Growth Catalysts
- Orphan drug incentives:FDA's 7-year market exclusivity and tax credits for clinical trial costs accelerate investment in Fabry disease enzyme replacement pipelines. EMA's PRIME designation scheme mirrors these benefits in Europe.
- Japan's Sakigake pathway:PMDA's priority review system compresses commercialization schedules for innovative biologics, drawing biopharma investment toward alpha galactosidase development.
- Plant-cell expression technology:Proprietary moss and carrot-cell platforms sidestep mammalian cell culture capacity constraints, expanding supply elasticity for therapeutic enzymes.
Market Restraints
- CHO cell culture capacity scarcity:Fed-batch fermentation infrastructure for therapeutic-grade enzyme production concentrates among contract manufacturers in the United States and Switzerland, creating supply bottlenecks.
- Endotoxin specification compliance:REACH purity thresholds and evolving GB standards in China filter contract manufacturing qualifications, raising barriers for new production entrants.
- Gene therapy substitution threat:Lentiviral and AAV-based approaches for Fabry disease are advancing through clinical trials, potentially displacing lifelong enzyme replacement requirements.
Strategic Opportunities
- India's rare disease infrastructure:CDSCO's orphan drug framework and expanding tertiary care networks create whitespace for enzyme replacement therapy penetration.
- Automated food processing integration:Liquid enzyme dosing systems in continuous manufacturing lines open precision-application revenue pools beyond powder formulations.
- Biosimilar substitution rule convergence:Evolving EMA and FDA guidance on therapeutic enzyme interchangeability creates pathway clarity for follow-on biologic developers.
Industry Challenges
- Bioprocess engineering talent scarcity:Fed-batch optimization and downstream purification expertise for glycosylated enzymes concentrates among specialists in Denmark and Germany.
- Cold chain integrity requirements:Temperature-sensitive liquid enzyme formulations demand validated distribution infrastructure that many emerging market logistics networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alpha Galactosidase Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Enzymes, Powder Enzymes, Capsule Formulations, Tablet Formulations Application: Digestive Aid, Food Processing, Animal Feed, Pharmaceutical Additive, Nutraceuticals End User: Pharmaceutical Manufacturers, Food & Beverage Producers, Animal Nutrition Companies, Dietary Supplement Companies Distribution Channel: Online Retailers, Direct Sales, Distributors, Pharmacies, Health Stores |
| Companies Covered | JCR Pharmaceuticals, Novozymes, Advanced Enzymes, Protalix Biotherapeutics, Megazyme Ltd., Amano Enzyme Inc., Pharming Group, ISU ABXIS, Aumgene Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alpha Galactosidase Market Shifts & Advancements
Expression platform diversification and regulatory pathway acceleration are restructuring competitive economics across therapeutic and industrial enzyme segments.
Continuous manufacturing technology for biologics is migrating from small-molecule pharmaceuticals into enzyme replacement therapy production. Contract manufacturers in Switzerland and Singapore are adopting perfusion-based systems to intensify volumetric productivity. This shift is compressing batch-to-batch variability and enabling real-time release testing for glycoprotein quality attributes.
REACH authorization requirements for industrial enzyme imports are tightening purity and documentation standards across European procurement channels. ECHA's evolving substance evaluation protocols now capture alpha galactosidase preparations used in feed applications. German compound feed manufacturers are consolidating supplier qualifications to preempt authorization delays.
Direct-to-clinic distribution models for orphan enzyme therapies are displacing traditional wholesale-pharmacy channels in rare disease treatment. Specialty pharmacy networks in the United States and Japan are building in-home infusion capabilities to reduce site-of-care costs. This channel restructuring is most visible in Fabry disease management where patient registries enable demand forecasting precision.
Global Alpha Galactosidase Market Segmentation
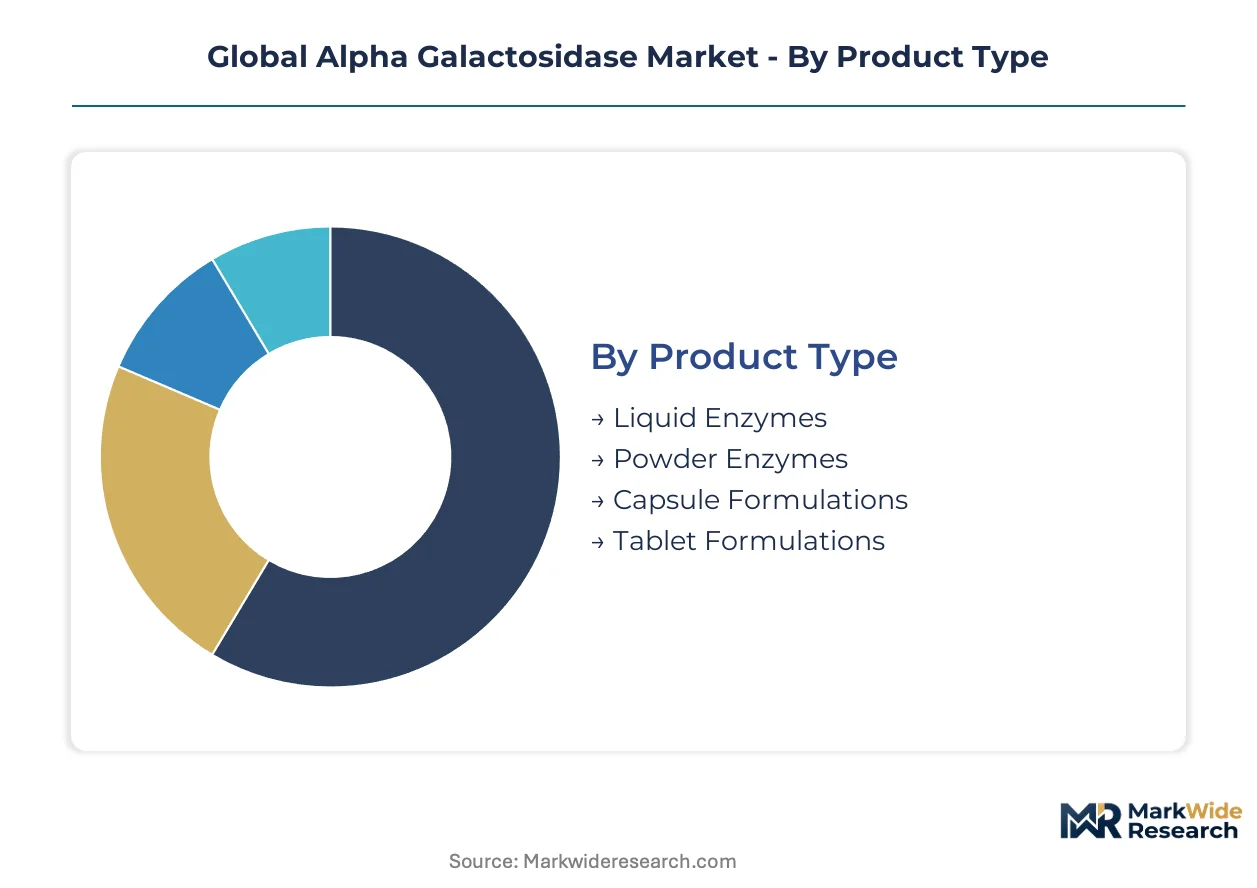
Segmentation in alpha galactosidase markets separates mature industrial formats from emerging therapeutic delivery systems. Each category reflects distinct regulatory pathways, margin structures, and procurement behaviors that shape supplier strategy.
Product Type:
Mature powder and liquid formats dominate procurement volumes, while capsule and tablet formulations represent emerging growth vectors in consumer-directed channels.
- Liquid Enzymes:Aqueous preparations with standardized activity units enable precision dosing in automated food processing lines. Demand concentrates in Germany and Japan where continuous manufacturing adoption is accelerating. FDA food additive clearances and EFSA enzyme approvals govern commercial deployment.
- Powder Enzymes:Lyophilized or spray-dried formulations offer superior shelf stability and reduced freight costs for bulk industrial procurement. Pharmaceutical manufacturers in Switzerland and the United States favor powder formats for downstream formulation flexibility. REACH documentation requirements and GB standards in China filter supplier qualifications.
- Capsule Formulations:Encapsulated enzyme blends target nutraceutical channels with concentrated margin profiles.
- Tablet Formulations:Compressed dosage forms serve retail digestive health segments with convenience positioning.
Powder enzymes retain volume leadership; capsule formulations hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity industrial uses from premium therapeutic applications, with regulatory intensity rising across the value ladder.
- Pharmaceutical Additive:Recombinant enzyme replacement therapies for Fabry disease command the highest purity specifications and orphan drug pricing structures. FDA accelerated approval pathways and EMA PRIME designation compress development timelines for manufacturers. Japan's PMDA Sakigake priority review draws biopharma investment toward this segment.
- Food Processing:Industrial enzyme preparations catalyze oligosaccharide hydrolysis in soybean and legume processing to improve digestibility. German compound feed manufacturers and Japanese soy sauce producers drive procurement volumes. EFSA enzyme evaluations and evolving GB standards govern market access.
- Digestive Aid:Over-the-counter enzyme supplements address lactose intolerance and general digestive discomfort in consumer markets.
- Animal Feed:Feed-grade preparations reduce anti-nutritional factors in legume-based livestock rations.
- Nutraceuticals:Positioned enzyme blends target wellness-oriented consumers through supplement channels.
Food processing commands absolute volume; pharmaceutical additive applications are climbing the fastest.
End User:
Customer type determines contract structure, with pharmaceutical manufacturers demanding long-term supply agreements and food producers favoring spot procurement.
- Pharmaceutical Manufacturers:Orphan drug developers and biosimilar producers secure multi-year enzyme supply contracts with quality attribute specifications. Novozymes and Protalix Biotherapeutics anchor supply relationships through proprietary expression platforms. FDA orphan drug exclusivity and EMA biosimilar guidance shape procurement timelines.
- Food & Beverage Producers:Industrial enzyme buyers prioritize unit economics and batch consistency in high-volume applications.
- Animal Nutrition Companies:Feed compounders integrate enzymes into premix formulations for livestock productivity.
- Dietary Supplement Companies:Brand marketers source encapsulated enzymes for consumer-facing digestive health products.
Pharmaceutical manufacturers anchor value concentration; dietary supplement companies are expanding most quickly.
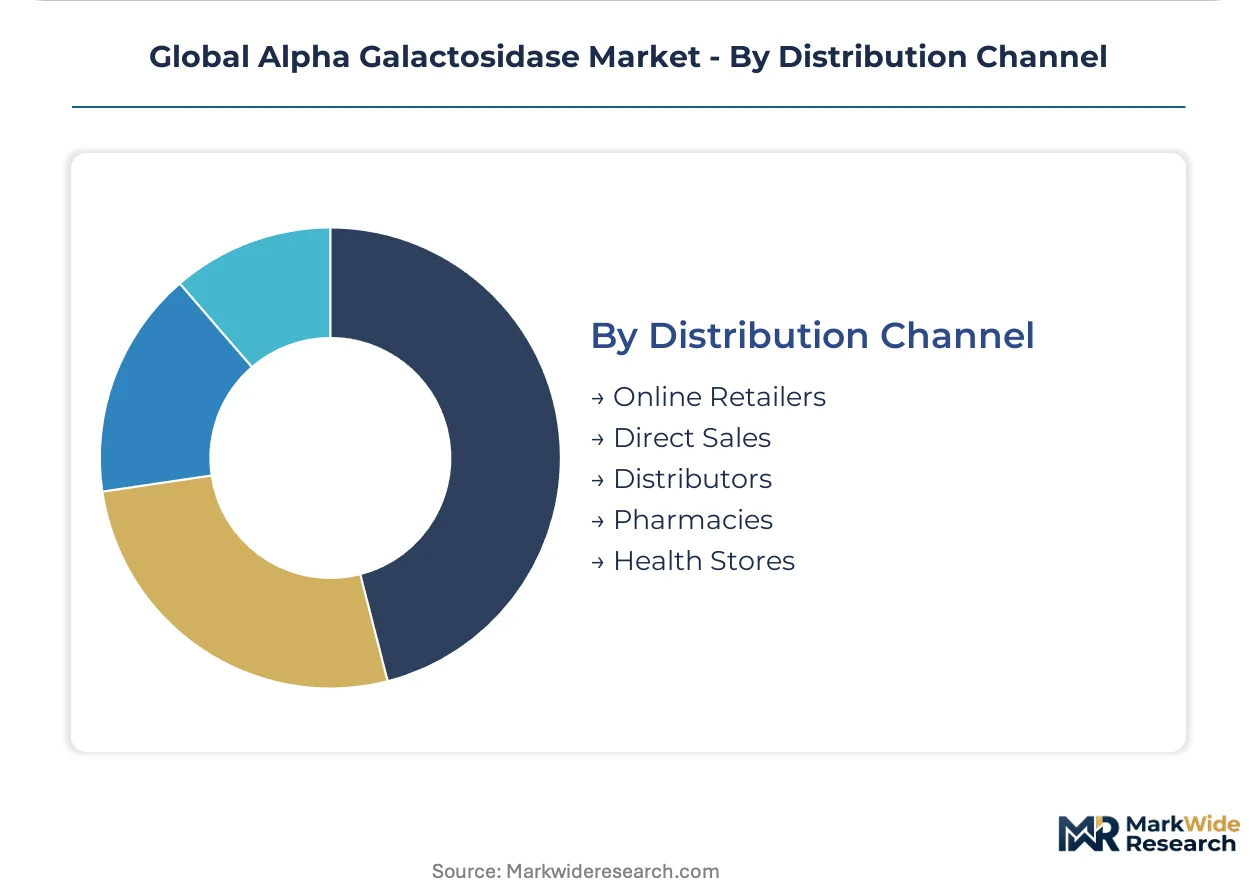
Distribution Channel:
Supply concentration in direct sales and distributor networks is displacing traditional wholesale channels, particularly for orphan therapeutic products.
- Direct Sales:Manufacturer-to-clinic relationships dominate orphan enzyme replacement therapy distribution, bypassing wholesale markups. Specialty pharmacy networks in the United States and Japan build in-home infusion capabilities. FDA drug distribution security requirements and Japan's cold chain regulations govern logistics qualifications.
- Distributors:Industrial enzyme procurement flows through qualified distributors with REACH authorization and documentation capabilities.
- Online Retailers:E-commerce platforms capture consumer-directed nutraceutical enzyme sales.
- Pharmacies:Retail dispensing channels serve prescription enzyme replacement patients.
- Health Stores:Specialty retail positions digestive enzyme supplements to wellness consumers.
Direct sales retain margin leadership; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German enzyme manufacturers export research-grade alpha galactosidase to United States pharmaceutical developers, while Japanese biotech firms supply therapeutic enzymes across Asia-Pacific distribution networks.
United States
FDA orphan drug incentives and specialty pharmacy networks drive therapeutic enzyme procurement. The agency's accelerated approval pathways compress development timelines for Fabry disease treatments. Boston and San Francisco biotech clusters concentrate contract manufacturing partnerships for glycoprotein production.
Germany
EFSA enzyme evaluations and REACH authorization requirements govern industrial procurement for food processing applications. German compound feed manufacturers consolidate supplier qualifications to preempt regulatory delays. The Rhine-Ruhr industrial corridor anchors fermentation infrastructure for bulk enzyme production.
Japan
PMDA Sakigake priority review draws biopharma investment toward innovative biologics development. METI standards and cold chain regulations shape distribution logistics for temperature-sensitive formulations. The Kanto region around Tokyo concentrates specialty pharmacy networks with in-home infusion capabilities.
India
CDSCO's emerging orphan drug framework and expanding tertiary care networks create whitespace for enzyme replacement therapy penetration. FSSAI regulations and DGFT import policies filter research-grade enzyme procurement channels. Maharashtra and Karnataka pharmaceutical clusters build bioprocess engineering capabilities for downstream formulation.
Switzerland
Swissmedic oversight and continuous manufacturing technology adoption intensify volumetric productivity for therapeutic enzymes. The country's contract manufacturers adopt perfusion-based systems to compress batch-to-batch variability. Basel and Zurich anchor precision biologics production for European distribution.
Global Alpha Galactosidase Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Industrial enzyme supply concentrates among fermentation-scale operators with REACH documentation capabilities. Three archetypes dominate: platform-technology developers, geographic-distribution specialists, and contract-manufacturing anchors. Capacity expansion and strategic technology licensing represent the dominant competitive vectors reshaping supply relationships.
Among platform-technology developers, Protalix Biotherapeutics exemplifies plant-cell expression specialization, while Novozymes occupies a position spanning industrial fermentation scale. JCR Pharmaceuticals represents geographic-distribution concentration within Asia-Pacific therapeutic channels. These three anchors illustrate how competitive positioning stratifies across expression technology, manufacturing scale, and regional market access.
| Leading Market Players |
|---|
| JCR Pharmaceuticals |
| Novozymes |
| Advanced Enzymes |
| Protalix Biotherapeutics |
| Megazyme Ltd. |
| Amano Enzyme Inc. |
| Pharming Group |
| ISU ABXIS |
| Aumgene Biosciences |
| Others |
Supply & Pricing Matrix
CHO cell culture undercapacity in Switzerland and the United States is tightening supplier bargaining power and compressing margin structures for therapeutic-grade alpha galactosidase. Fed-batch fermentation slot scarcity enables contract manufacturers to impose indexed pricing escalators on pharmaceutical clients while forcing food-grade enzyme producers toward alternative expression platforms.
Pricing Analysis
Cost-plus contracts with raw-material indexation dominate therapeutic enzyme procurement, linking unit prices to dextrose and yeast extract commodity benchmarks. Three-tier pricing structure across GMP-certified, research-grade, and feed-grade quality levels separates orphan drug manufacturers from industrial food processors. Price erosion runs through feed-grade powder enzymes as Novozymes and Amano Enzyme expand fermentation capacity. Pharmaceutical additive buyers exhibit lowest price sensitivity due to orphan drug reimbursement protections, while animal nutrition companies negotiate aggressively on volume commitments.
Supply Chain Analysis
Upstream fermentation media supply draws from corn-derived dextrose producers in the United States and yeast extract manufacturers in Germany. Therapeutic enzyme production concentrates in Switzerland, the United States, and Japan where GMP infrastructure and cold chain validation capabilities cluster. Single-source vulnerability pervades plant-cell expression platforms as Protalix Biotherapeutics anchors proprietary moss-based supply. Distribution runs through direct manufacturer-to-clinic channels for orphan therapies and qualified distributors with REACH authorization for industrial formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is restructuring competitive returns as expression technology interoperability enables supplier switching between CHO, plant-cell, and microbial systems. Ecosystem convergence around continuous manufacturing standards is compressing batch-to-batch quality variance and resetting procurement qualification timelines.
For Market Incumbents: Harden supply relationships through captive fermentation capacity additions in Basel and Singapore to preempt CHO cell culture slot scarcity. Secure backward integration into yeast extract and dextrose supply to buffer raw material indexation pressure. Lock multi-year offtake agreements with Fabry disease therapy developers before gene therapy substitution threat materializes.
For New Entrants and Emerging Players: India's CDSCO orphan drug framework and expanding tertiary care networks represent the most penetrable whitespace for enzyme replacement therapy distribution. Target Maharashtra pharmaceutical clusters with research-grade enzyme supply partnerships before GMP certification investments. Pursue licensing arrangements with established plant-cell expression platforms to bypass mammalian cell culture capacity constraints.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with validated GMP suites and long-term orphan drug supply contracts. Five-to-ten year viability favors platform-technology developers with proprietary expression systems over commodity fermentation operators. Watch for FDA biosimilar substitution guidance clarity as the inflection signal for follow-on biologic investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses Fabry disease therapy development timelines for enzyme developers. |
| Manufacturing Scale-Up | Perfusion-based continuous manufacturing adoption in Singapore intensifies volumetric productivity for glycoprotein output. |
| Licensing Agreement | Plant-cell expression technology licensing sidesteps CHO capacity scarcity for emerging therapeutic suppliers. |
| Long-term Supply Agreement | Multi-year enzyme offtake contracts with pharmaceutical manufacturers lock in quality-attribute pricing premiums. |
| Geographic Expansion | India CDSCO framework penetration builds orphan disease infrastructure for enzyme replacement therapy distribution. |
Research Methodology
Cross-validation between primary interviews with bioprocess engineering directors, regulatory affairs leads at orphan drug developers, specialty pharmacy procurement managers, and compound feed formulators anchors the qualitative findings. Secondary validation draws from FDA orphan drug designations, EMA PRIME submissions, EFSA enzyme evaluations, and REACH authorization databases. Bottom-up fermentation capacity modeling triangulates against top-down therapeutic enzyme demand projections across patient registry data.
Calibration against historical pricing indices for fermentation media and glycoprotein contract manufacturing rates shapes the analytical framework. Segmentation dimensions span expression platform type, quality grade tier, end-use application, and regional regulatory cluster. CAGRs derive from patient population epidemiology, therapy penetration assumptions, and industrial enzyme volume growth across food processing and feed applications. Biosimilar substitution probability and gene therapy clinical advancement serve as scenario-weighting inputs.
Practitioners should monitor FDA biosimilar interchangeability guidance, EMA substitution rule evolution, and gene therapy Phase III readouts for early signals of forecast revision. Cross-checking against CDSCO orphan drug framework implementation pace and PMDA Sakigake approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Proteinase K Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Biologics Contract Manufacturing Market