
 Loop-Mediated Isothermal Amplification (LAMP) Market | 2026-2036
Loop-Mediated Isothermal Amplification (LAMP) Market Size, Share, and Industry Trends Forecast 2026-2036
Loop-Mediated Isothermal Amplification (LAMP) Market Foresight
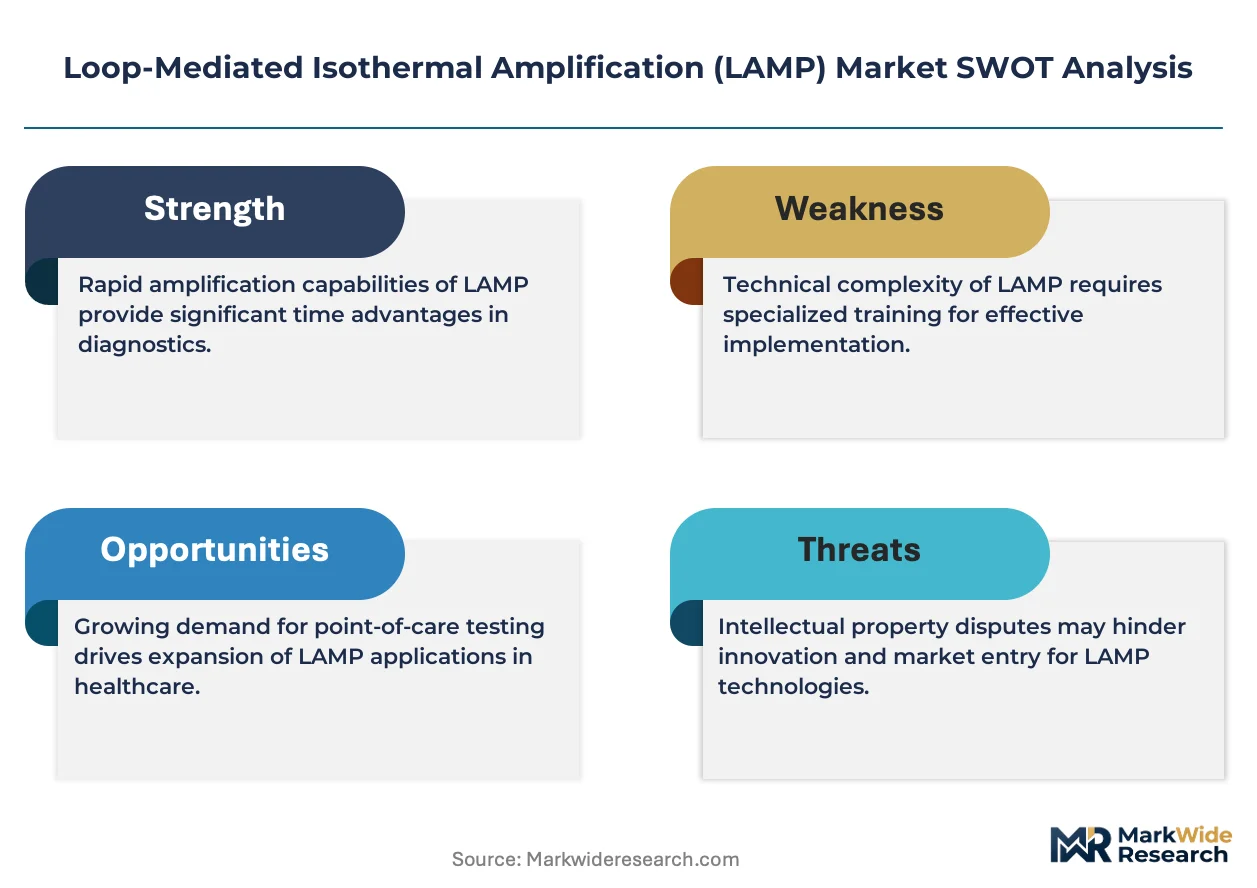
Asset-light leasing models for molecular diagnostic instruments is reconfiguring how mid-sized laboratories access LAMP technology without capital-intensive procurement. Thermo Fisher Scientific leverages its global distribution infrastructure to sustain kit replenishment revenue across installed instrument bases. Eiken Chemical Co., Ltd. anchors its competitive position through proprietary polymerase enzyme formulations optimized for loop-mediated protocols. Meridian Bioscience, Inc. differentiates via integrated assay-instrument bundles that reduce per-test operational complexity for clinical end users.
Loop-Mediated Isothermal Amplification denotes a nucleic acid amplification method operating at a constant temperature between 60°C and 65°C using Bst DNA polymerase and four to six primers recognizing six to eight distinct regions of a target sequence, eliminating thermal cycling requirements. The technology serves industrial and commercial purposes by enabling rapid pathogen detection at point-of-care settings without laboratory-grade thermal cyclers. Kits and reagents capture the dominant share of product-type revenue due to recurring consumable demand tied to instrument installed bases. Clinical diagnostics leads application segments structurally, while food safety testing registers faster growth trajectories as regulatory agencies mandate molecular verification of supply chain contaminants.
FDA Emergency Use Authorization and ISO 13485 quality management standards govern market access for LAMP-based diagnostic products in the United States, with the former accelerating pandemic-era commercialization and the latter establishing manufacturing benchmarks for sustained regulatory compliance. The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements that reshape product development timelines and post-market surveillance obligations for manufacturers seeking CE marking. Stakeholders must monitor evolving harmonization between FDA and EMA evidentiary standards to anticipate where parallel submission strategies reduce regulatory redundancy or create competitive delays.
Market Dynamics
Asset-light leasing models for molecular diagnostic instruments are compressing capital barriers for mid-sized clinical laboratories, fundamentally restructuring how LAMP technology penetrates routine infectious disease workflows.
Growth Catalysts
- FDA Emergency Use Authorization:The pathway accelerates commercialization timelines for molecular diagnostics, enabling rapid deployment of LAMP-based assays during public health emergencies.
- Point-of-care networks:Hospital laboratories and decentralized testing sites are integrating isothermal amplification to reduce turnaround times for pathogen detection.
- Bst DNA polymerase optimization:Advances in enzyme formulation stability are extending reagent shelf life and reducing cold-chain dependencies in field settings.
Market Restraints
- ISO 13485 compliance costs:Quality management system certification imposes substantial documentation and audit burdens on smaller reagent manufacturers.
- Primer design complexity:The requirement for four to six primers recognizing six to eight distinct regions increases assay development timelines compared to PCR alternatives.
- Thermal cycler substitution:Established PCR infrastructure in centralized laboratories creates switching friction for isothermal alternatives.
Strategic Opportunities
- Food safety testing:Regulatory agencies are mandating molecular verification of supply chain contaminants, opening new assay development verticals.
- CE marking harmonization:Convergence between FDA and EMA evidentiary standards enables parallel submission strategies that reduce redundant clinical trials.
- Digital LAMP integration:Smartphone-based result interpretation is eliminating dedicated reader hardware requirements in resource-limited settings.
Industry Challenges
- Multiplexing limitations:Current primer architectures complicate simultaneous detection of multiple targets, constraining panel-based assay development.
- Cross-platform standardization:Absence of universal reaction conditions across instrument manufacturers fragments protocol optimization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loop-Mediated Isothermal Amplification (LAMP) Market |
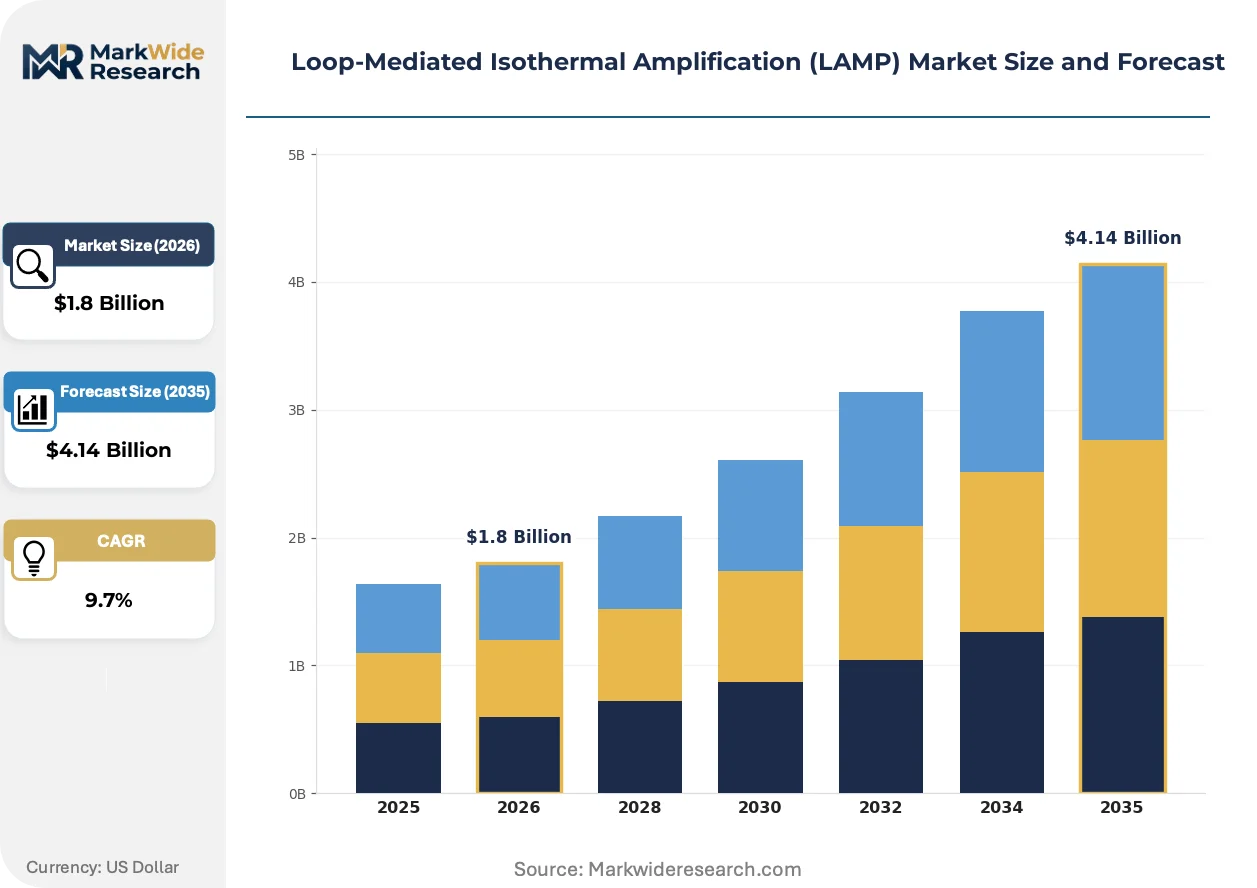
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Reagents, Devices, Instruments Technology: Nucleic Acid Amplification, Molecular Diagnostics, Microfluidics, Thermocyclers Application: Clinical Diagnostics, Food Safety Testing, Environmental Monitoring, Veterinary Use End User: Hospitals, Laboratories, Research Institutes, Clinics |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Inc., New England Biolabs, Inc., Nippon Gene Co., Ltd., Meridian Bioscience, Inc., Eiken Chemical Co., Ltd., Jena Bioscience GmbH, HiberGene Diagnostics, Omega Bio-tek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loop-Mediated Isothermal Amplification (LAMP) Market Shifts & Advancements
Digital integration and regulatory convergence are compressing development cycles while reshaping how end-users consume molecular diagnostic capabilities across decentralized care networks.
Real-time turbidimetry and fluorescence detection systems are digitizing result interpretation by enabling cloud-connected instruments that transmit amplification curves directly to laboratory information systems. Point-of-care operators in the United States are adopting these connected workflows to eliminate manual transcription errors. The shift is digitizing compliance documentation and enabling remote quality monitoring across distributed testing sites.
The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements that extend product development timelines for manufacturers seeking CE marking. Device sponsors must now generate performance data across broader patient populations and maintain rigorous post-market surveillance systems. Small-to-mid-sized assay developers are responding by prioritizing FDA submissions first, then leveraging that dossier for European regulatory packages.
Leasing arrangements for thermal instruments are displacing capital purchase models among hospital laboratories seeking to preserve balance sheet flexibility. Distributors are bundling reagent minimums with instrument placement to secure recurring revenue streams. This transformation is most visible in United States point-of-care networks where operational budgets dominate procurement decisions.
Loop-Mediated Isothermal Amplification (LAMP) Market Segmentation
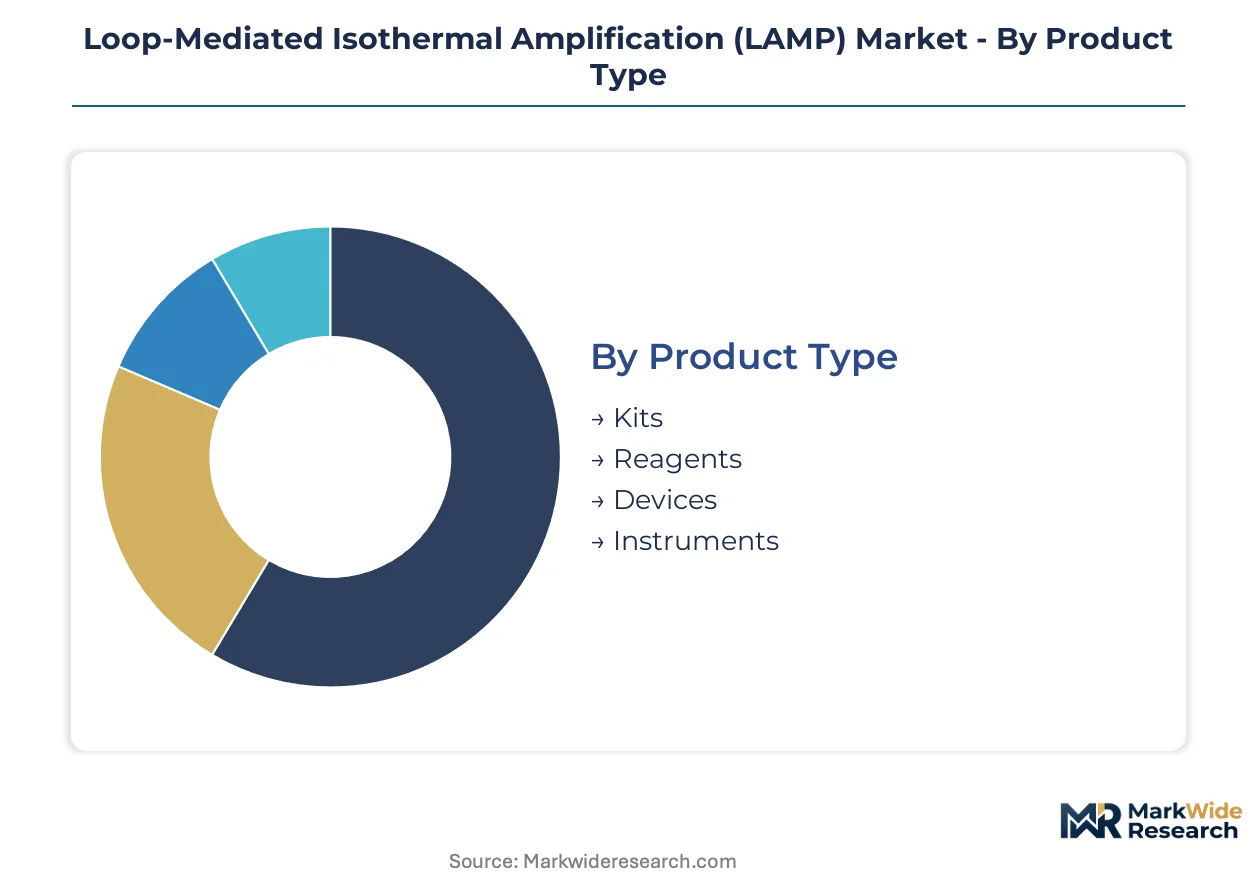
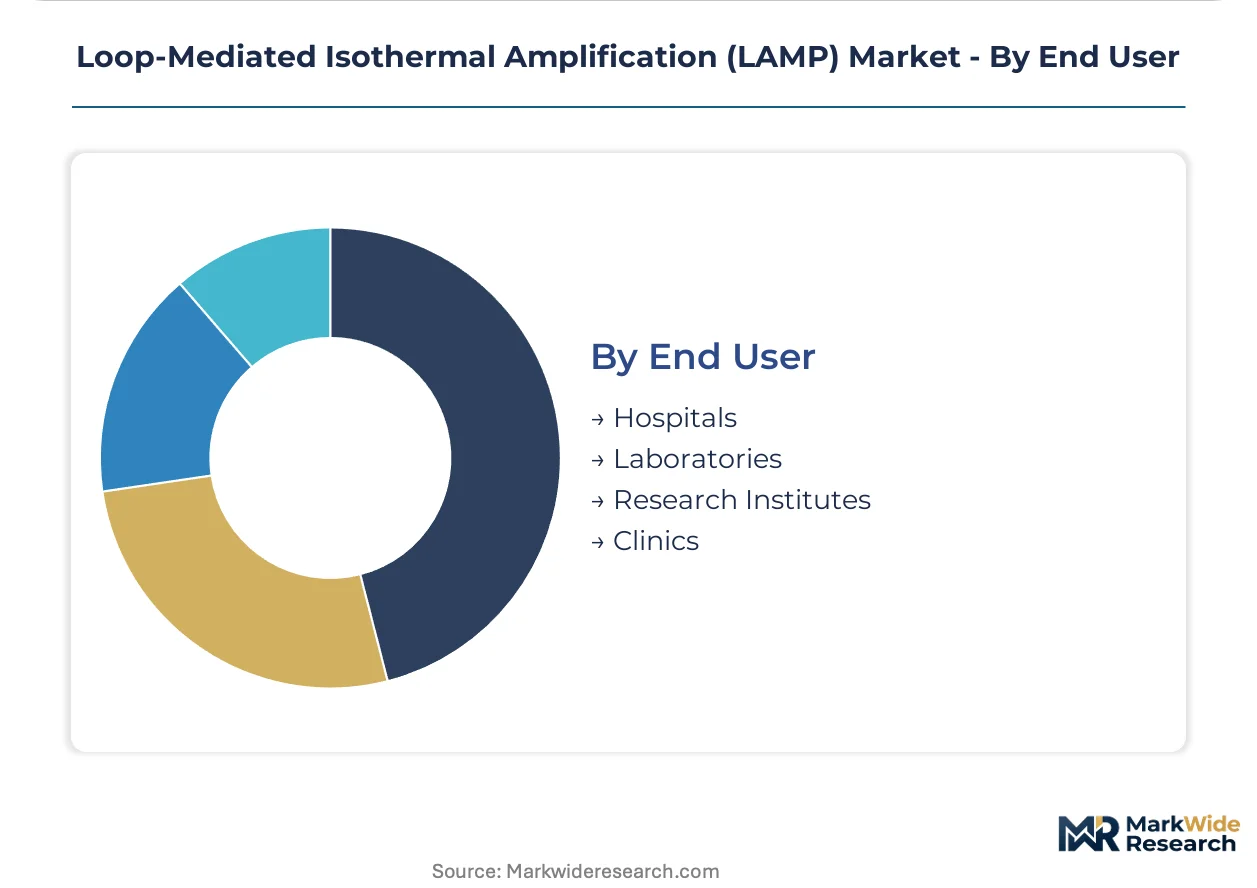
Segmentation in the LAMP market reveals distinct procurement rhythms across product types and end users. Consumable-heavy segments turn inventory faster than capital equipment categories, creating predictable replenishment cycles that anchor manufacturer revenue planning.
Product Type:
Consumable categories compress reorder cycles to weeks while instruments stretch replacement horizons across years, fragmenting cash flow profiles across the value chain.
- Kits:Pre-formulated master mixes containing Bst DNA polymerase, primers, and reaction buffers in lyophilized or liquid formats. Hospital point-of-care networks in the United States concentrate procurement here, driven by FDA Emergency Use Authorization pathways that validate assay performance for infectious disease panels.
- Reagents:Bulk enzymes, primers, and detection chemistry sold separately for laboratory-developed tests. Research institutes and mid-sized clinical laboratories optimize per-test economics through customized reaction formulations, though cold-chain logistics constrain field deployment flexibility.
- Devices:Portable heating blocks and fluorescence readers designed for isothermal protocols. Compact form factors suit decentralized testing sites lacking laboratory infrastructure.
- Instruments:Automated liquid handling and amplification platforms for high-throughput settings. Capital procurement cycles extend replacement timelines.
Kits anchor the volume base while reagents gain share at the steepest rate as laboratories internalize assay development capabilities.
Technology:
Core amplification chemistries command premium positioning against peripheral enabling technologies that compete on integration convenience.
- Nucleic Acid Amplification:Isothermal amplification chemistry using strand-displacing polymerases at constant temperature between 60°C and 65°C. Clinical diagnostics workflows in the United States drive adoption, with hospital laboratories replacing thermal cycler-dependent PCR for respiratory pathogen detection.
- Molecular Diagnostics:Integrated assay systems combining sample preparation, amplification, and result interpretation. Point-of-care clinics prioritize these bundled platforms to minimize operator training requirements.
- Microfluidics:Chip-based reaction chambers enabling sub-microliter volumes and parallel processing. Research institutes exploit these formats for multiplexed pathogen screening.
- Thermocyclers:Traditional thermal cycling instruments adapted for isothermal protocols through firmware modifications. Established installed bases in centralized laboratories create switching friction.
Nucleic acid amplification dominates revenue contribution while microfluidics climbs fastest through miniaturization demand in field diagnostics.
Application:
Regulatory validation intensity varies sharply across use cases, with human health applications facing steeper evidentiary thresholds than industrial monitoring.
- Clinical Diagnostics:Infectious disease detection in respiratory, bloodstream, and sexually transmitted pathogen panels. United States hospital laboratories anchor demand, propelled by CMS reimbursement codes that recognize molecular testing for antibiotic stewardship programs.
- Food Safety Testing:Supply chain verification for Salmonella, Listeria, and E. coli contamination. Regulatory agencies including the USDA and FDA mandate molecular confirmation for positive screening tests, accelerating assay validation.
- Environmental Monitoring:Water quality and soil pathogen surveillance. Public health laboratories deploy these assays for outbreak source tracing.
- Veterinary Use:Livestock and companion animal infectious disease screening. Agricultural extension networks drive volume in production animal settings.
Clinical diagnostics secures the revenue base while food safety testing expands most quickly under tightening supply chain verification mandates.
End User:
Capital availability and technical staffing depth segment procurement behavior, with resource-constrained sites favoring integrated solutions over modular configurations.
- Hospitals:Integrated health systems with centralized laboratories and satellite point-of-care units. United States health networks concentrate procurement through group purchasing organizations, negotiating reagent minimums against instrument placement.
- Laboratories:Independent clinical reference labs and public health facilities. ISO 15189 accreditation requirements drive quality system investments that favor established assay manufacturers.
- Research Institutes:Academic and government research facilities developing novel primer architectures. Funding cyclicality creates lumpy demand patterns.
- Clinics:Physician offices and urgent care centers with limited technical staff. Workflow simplicity dominates procurement criteria over analytical sensitivity.
Hospitals anchor the installed base while clinics capture share fastest through retail health expansion and decentralized testing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives from the Centers for Medicare & Medicaid Services in the United States are accelerating hospital laboratory adoption of molecular diagnostics. Japan's PMDA has streamlined approval pathways for isothermal amplification assays. Germany's EMA alignment with FDA evidentiary standards enables parallel regulatory submissions.
United States
Hospital point-of-care networks in Texas and California are replacing thermal cycler-dependent PCR workflows with isothermal protocols for respiratory pathogen detection. FDA Emergency Use Authorization pathways compressed commercialization timelines during public health emergencies, establishing precedent for rapid assay deployment. The Boston-Cambridge biotech corridor anchors development of novel primer architectures for multiplexed panels.
Japan
PMDA regulatory harmonization with FDA standards enables Japanese manufacturers to leverage U.S. clinical data packages for domestic approvals. Tokyo-Osaka pharmaceutical clusters drive demand for quality-controlled reagent supply chains in infectious disease diagnostics. METI funding programs support point-of-care instrument miniaturization for aging population healthcare access.
Germany
EMA In Vitro Diagnostic Regulation implementation is reshaping clinical evidence requirements for CE-marked LAMP products entering European markets. The Munich-Stuttgart medical technology corridor concentrates automated liquid handling platform manufacturing. Baden-Württemberg research institutes collaborate with industrial partners on microfluidic chip integration for field diagnostics.
China
NMPA priority review pathways for innovative diagnostics are accelerating domestic assay commercialization timelines. The Yangtze River Delta biotech cluster in Shanghai-Suzhou generates demand for cost-effective isothermal amplification reagents in veterinary and food safety applications. SAMR quality system inspections enforce ISO 13485-equivalent manufacturing standards for export-oriented producers.
India
CDSCO streamlined medical device rules are reducing registration timelines for imported molecular diagnostic platforms. Karnataka's Bangalore-Hyderabad pharmaceutical corridor drives adoption of asset-light leasing models among mid-sized clinical laboratories. ICMR funding supports development of indigenous isothermal amplification assays for tuberculosis and vector-borne disease surveillance.
Loop-Mediated Isothermal Amplification (LAMP) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Thermo Fisher Scientific leverages global distribution infrastructure against Eiken Chemical's proprietary enzyme formulations. Three archetypes dominate: integrated life science conglomerates with kit-instrument bundles, specialized reagent manufacturers with polymerase optimization, and regional distributors with localized technical support. Competitive moves center on strategic partnerships for regulatory dossier sharing and geographic expansion through distributor acquisition.
Among integrated diagnostic platform providers, Thermo Fisher Scientific and Bio-Rad Laboratories occupy positions exemplifying channel-control strategies through installed instrument bases and reagent pull-through economics. Eiken Chemical Co., Ltd. represents the specialist archetype with concentrated expertise in Bst DNA polymerase formulation. Meridian Bioscience, Inc. anchors the mid-tier integrated bundle segment, reducing operational complexity for clinical end users through combined assay-instrument offerings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories, Inc. |
| New England Biolabs, Inc. |
| Nippon Gene Co., Ltd. |
| Meridian Bioscience, Inc. |
| Eiken Chemical Co., Ltd. |
| Jena Bioscience GmbH |
| HiberGene Diagnostics |
| Omega Bio-tek, Inc. |
| Others |
Supply & Pricing Matrix
Shanghai-Suzhou freight corridors carry lyophilized reagent shipments from Yangtze River Delta manufacturing clusters to United States distribution hubs, with container cost volatility feeding directly into price spreads between FDA-validated premium tiers and research-grade economy alternatives.
Pricing Analysis
Certification level creates the primary spread across LAMP product tiers, with FDA Emergency Use Authorization and ISO 13485 quality grades commanding substantial premiums over research-use-only alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with hospital laboratories showing lowest price sensitivity due to CMS reimbursement coverage while mid-sized clinical laboratories drive cost compression through group purchasing organization negotiations. Pricing pressure stems from Bst DNA polymerase commoditization among second-source suppliers, though proprietary enzyme formulations retain margin protection.
Supply Chain Analysis
Export control regimes restricting nucleic acid amplification technology transfers constrain Bst DNA polymerase enzyme flows from Japanese and German specialty chemical manufacturers to certain end markets. Supply concentrates in Japan, Germany, and China for polymerase production, with primer synthesis capacity distributed across United States and South Korean oligonucleotide foundries. Cold-chain logistics for liquid reagent formats present single-source vulnerability where specialized packaging providers dominate. Distribution runs through life science distributors with regional technical support capabilities rather than direct manufacturer-to-laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LAMP technology sits in early-cycle expansion as point-of-care infectious disease testing penetrates hospital satellite networks and retail health clinics, with FDA Emergency Use Authorization precedent compressing commercialization timelines for new assay developers.
For Market Incumbents: Pre-empt emerging entrant pressure by locking in exclusive reagent supply agreements with Bst DNA polymerase manufacturers, while accelerating multiplexed panel development to defend against PCR instrument installed bases that create switching friction for single-target LAMP alternatives.
For New Entrants and Emerging Players: Build out food safety testing assay portfolios targeting USDA-mandated molecular confirmation workflows, where regulatory tailwinds outpace clinical diagnostics saturation, and pursue asset-light leasing partnerships with mid-sized veterinary laboratories in India and Southeast Asia.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized reagent manufacturers with proprietary polymerase optimization over integrated instrument platforms, as recurring consumable revenue anchors valuation stability across infectious disease surveillance budget cycles; watch for inflection where digital LAMP smartphone integration eliminates dedicated reader hardware requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance enables European market entry for FDA-validated assay dossiers. |
| Hospital System Partnership | Group purchasing organization contracts secure instrument placement with multi-year reagent minimum commitments. |
| Backward Integration into Enzyme Production | Captive Bst DNA polymerase manufacturing reduces supplier concentration risk and protects formulation IP. |
| Software Companion Development | Cloud-connected amplification curve interpretation eliminates manual transcription errors across distributed testing sites. |
| Reimbursement Strategy | CMS molecular testing code recognition for antibiotic stewardship programs drives hospital laboratory procurement decisions. |
Research Methodology
The analysis maps nucleic acid amplification chemistry, integrated diagnostic platforms, microfluidic enabling technologies, and thermal instrument adaptations, each validated through laboratory directors, point-of-care clinic operators, regulatory affairs specialists at assay manufacturers, and procurement managers at group purchasing organizations. Primary interview findings triangulate against FDA 510(k) and Emergency Use Authorization filings, EMA In Vitro Diagnostic Regulation technical documentation, CMS Medicare reimbursement databases, and ISO 13485 quality system audit records. Bottom-up instrument installation and reagent consumption estimates reconcile with top-down molecular diagnostics market sizing across the analysis window.
Assumptions held fixed include current FDA-EU regulatory harmonization trajectories and Bst DNA polymerase supplier concentration, while variables tested include point-of-care network expansion rates and digital LAMP adoption curves. Segmentation models incorporate product type, technology architecture, application vertical, and end-user capital availability. CAGRs derive from logistic penetration curves fitted to historical infectious disease diagnostic adoption patterns, with inputs including hospital laboratory capital expenditure cycles and food safety regulatory mandate implementation schedules.
Sensitivities concentrate around FDA Emergency Use Authorization pathway modifications and EMA clinical evidence requirement evolution. Forecasts reflect documented assumptions regarding reimbursement stability and polymerase supply chain continuity. Material shifts in point-of-care regulatory classification or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Biobank Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Biobanking Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market