
 Global Downstream Processing Market | 2026-2036
Global Downstream Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Downstream Processing Market Foresight
Single-use polymers are broadening access to flexible manufacturing suites across contract development organizations. Thermo Fisher Scientific leverages its chromatography resin portfolio to anchor downstream purification workflows for gene therapy vectors. Sartorius AG specializes in integrated filtration and separation platforms that reduce cross-contamination risks in multi-product facilities. Danaher Corporation competes through precision diagnostics-to-bioprocessing convergence that tightens process analytical control loops.
Downstream processing encompasses the isolation, purification, and concentration of target biomolecules following upstream cell culture or fermentation, typically operating at temperatures between 2°C and 25°C with purity thresholds exceeding 99.9% for injectable biologics. Chromatography systems command the largest product type position due to their resolution specificity for complex protein mixtures, while membrane technology segments within ultrafiltration and diafiltration are expanding fastest as continuous processing architectures displace batch operations. Biotechnology firms represent the most concentrated end user industry, though pharmaceutical manufacturers are deepening demand as in-house viral vector capacity replaces outsourced production.
FDA process validation protocols, EMA good manufacturing practice Annex 1 revisions, and ISO 13485 quality management standards collectively elevate equipment qualification burdens and documentation rigor for market entry. These frameworks compel vendors to embed automated cleaning validation and real-time release testing into system designs. Stakeholders must weigh capital intensity against operational flexibility when selecting between stainless-steel infrastructure and disposable processing trains.
Market Dynamics
Continuous processing architectures are compressing batch cycle times and forcing equipment vendors to redesign chromatography skids for real-time operation rather than discrete purification runs.
Growth Catalysts
- EMA Annex 1 Revisions:The updated good manufacturing practice standards mandate closed-system processing for sterile biologics, accelerating replacement of open stainless-steel infrastructure with single-use containment technologies.
- Cell Therapy Manufacturing:Autologous CAR-T production facilities require rapid turnaround between patient batches, creating pull for disposable chromatography and filtration trains that eliminate cleaning validation bottlenecks.
- Protein A Resin Innovation:Next-generation affinity chemistries with higher binding capacity reduce column volumes by half, enabling smaller footprint facilities in urban biotech clusters.
Market Restraints
- Resin Supply Concentration:Agarose and synthetic polymer base materials for chromatography media concentrate among Japanese and European chemical suppliers, exposing downstream processors to input cost volatility and allocation constraints during demand surges.
- Skilled Technician Scarcity:Purification process development requires hybrid expertise in analytical chemistry and bioprocess engineering, with training pipelines failing to match facility expansion rates in South Korea and Singapore.
- Stainless-Steel Asset Stranding:Existing multi-product facilities face sunk-cost pressure when evaluating single-use retrofits, particularly for validated monoclonal antibody platforms with decade-long depreciation schedules.
Strategic Opportunities
- India CDMO Expansion:Contract development organizations in Hyderabad and Bengaluru are building viral vector capacity to serve Western gene therapy sponsors, creating demand for integrated downstream purification suites with EMA-equivalent qualification documentation.
- Continuous Chromatography-Membrane Hybrid Systems:Convergence of simulated moving bed technology with single-use tangential flow filtration enables fully connected processing lines that eliminate intermediate hold tanks and reduce facility footprint by two-thirds.
- ISO 13485 Certification Pathways:Medical device quality management standards are expanding into cell therapy manufacturing equipment, allowing vendors to command premium positioning through differentiated compliance documentation.
Industry Challenges
- Extractables and Leachables Validation:Single-use polymer contact materials require extensive characterization studies to demonstrate that plasticizers and stabilizers do not contaminate high-value biologics, extending qualification timelines by six to twelve months.
- Legacy DCS Integration:Brownfield facilities with decade-old distributed control systems face protocol mismatches when connecting new purification skids, forcing costly middleware development or full automation replacements.
- Process Analytical Technology Deployment:Real-time release testing demands spectroscopic sensors and multivariate algorithms that most quality organizations lack expertise to validate, creating implementation bottlenecks despite regulatory encouragement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Downstream Processing Market |
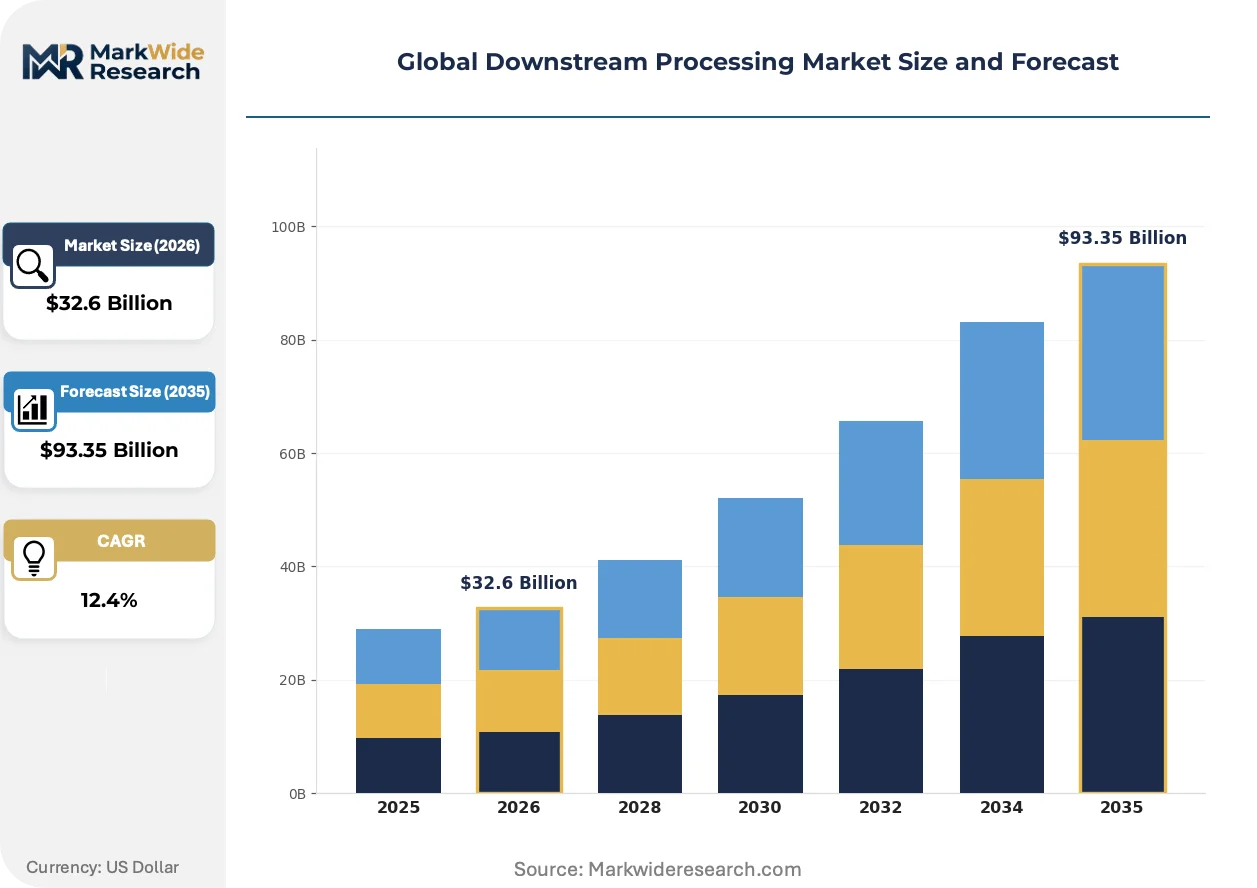
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $93.35 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Filtration Units, Centrifuges, Cell Disruption Equipment, Dryers Technology: Membrane Technology, Precipitation, Ultrafiltration, Flocculation, Extraction Application: Biopharmaceuticals, Enzyme Production, Vaccines, Food Additives, Biofuels End User Industry: Biotechnology Firms, Pharmaceutical Manufacturers, Agrochemical Developers, Specialty Chemical Producers |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Sartorius AG, Danaher Corporation, GE Healthcare, Repligen Corporation, Waters Corporation, Eppendorf AG, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Downstream Processing Market Shifts & Advancements
Modular facility designs and closed-system processing are reconfiguring how purification capacity gets deployed, with implications for equipment sizing, supplier relationships, and regulatory submission strategies.
Single-use chromatography systems are decentralizing biologics manufacturing by enabling distributed production networks. Biopharmaceutical companies deploy prefabricated cleanroom pods with disposable flow paths to university hospitals and regional infusion centers. This architecture collapses the cold-chain burden for unstable cell therapies and allows point-of-care manufacturing for personalized medicines.
FDA process validation guidance now requires continued process verification with statistical process control for all commercial biologics. Manufacturers must maintain electronic batch records demonstrating parametric control throughout purification. Small and mid-sized biotechnology firms without dedicated quality systems departments outsource this compliance burden to equipment vendors who embed automated documentation into chromatography software.
Biopharmaceutical procurement teams now specify total cost of ownership rather than capital expenditure when evaluating purification platforms. Finance departments amortize resin lifetime, cleaning validation burden, and facility downtime across multi-year operating contracts. This behavioral shift favors vendors with predictive maintenance algorithms and resin regeneration services, particularly among contract manufacturers in Germany competing for gene therapy sponsorships.
Global Downstream Processing Market Segmentation
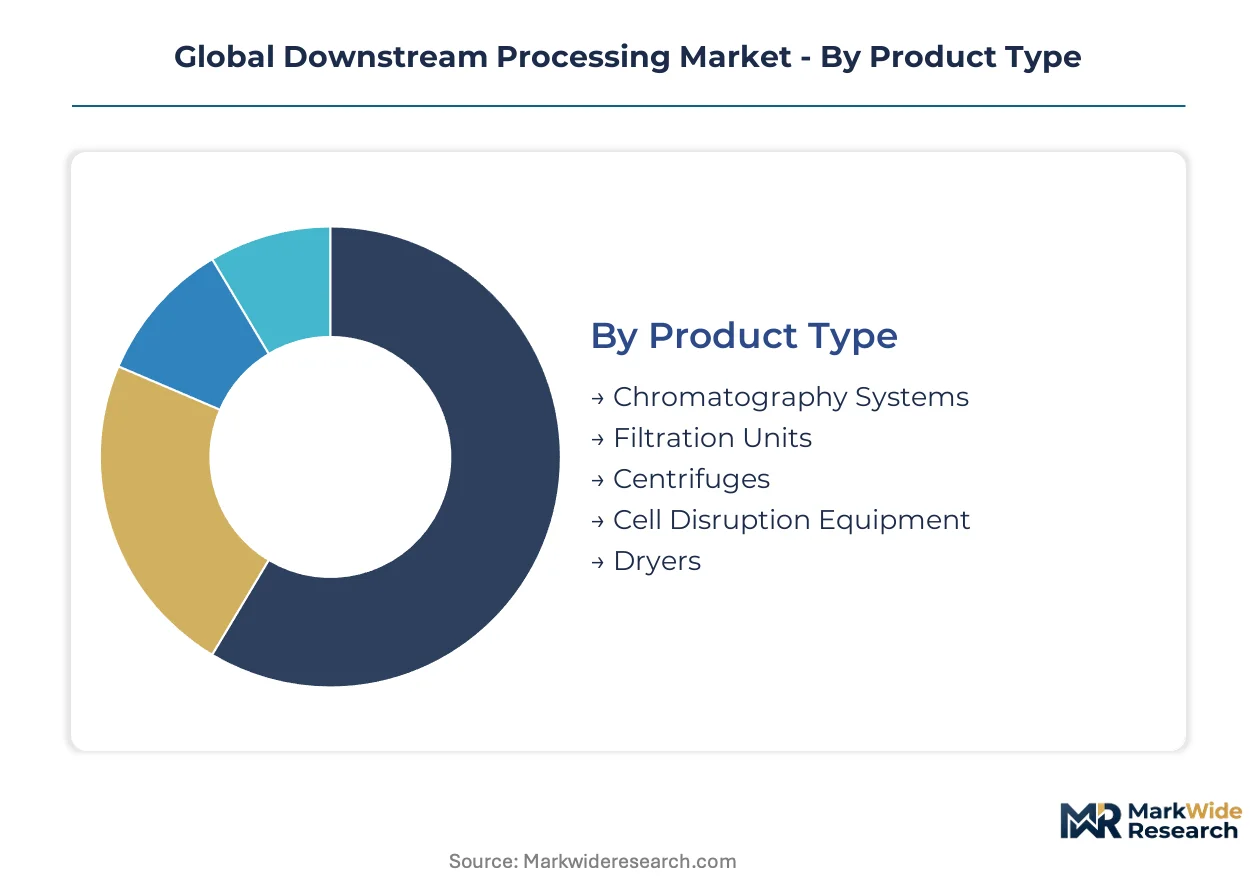
Downstream processing equipment and techniques vary sharply in capital intensity, operating temperature ranges, and validation requirements. Procurement decisions hinge on molecule stability, batch volume, and regulatory jurisdiction rather than unit economics alone.
Product Type:
Resolution specificity and contamination risk determine equipment selection across monoclonal antibody, viral vector, and enzyme manufacturing workflows.
- Chromatography Systems:Affinity, ion-exchange, and size-exclusion columns achieve 99.9% purity thresholds for injectable biologics. United States biopharmaceutical manufacturers deploy Protein A resin columns for monoclonal antibody capture, though resin lifetime and regeneration costs dominate total cost of ownership calculations.
- Filtration Units:Tangential flow filtration and normal flow filtration systems concentrate and diafilter protein solutions between purification steps. German contract manufacturers specify single-use membrane cassettes to eliminate cross-contamination risks in multi-product facilities.
- Centrifuges:Continuous-flow disk-stack and tubular bowl designs separate cell debris from harvested culture fluid. Industrial enzyme producers in South Korea operate high-speed centrifugation for biomass recovery at scales exceeding 10,000 liters.
- Cell Disruption Equipment:High-pressure homogenizers and bead mills lyse microbial cells to release intracellular proteins. Agrochemical developers deploy these systems for bacterial enzyme extraction where mechanical shear tolerance varies by strain.
- Dryers:Spray dryers and lyophilizers stabilize purified proteins for storage and shipment. Biotechnology firms processing heat-sensitive viral vectors prefer freeze-drying over thermal drying methods.
Chromatography systems lead on scale; filtration units lead on momentum.
Technology:
Physical separation principles differentiate cost structures, facility footprint requirements, and automation compatibility across downstream operations.
- Membrane Technology:Microfiltration and ultrafiltration membranes with defined molecular weight cut-offs separate particles without phase changes. Single-use hollow fiber modules from Sartorius AG and Repligen enable closed-system processing that satisfies EMA Annex 1 sterile manufacturing requirements.
- Precipitation:Salting-out and organic solvent precipitation concentrate proteins using differential solubility. Agrochemical developers favor precipitation for bulk enzyme recovery where purity requirements fall below pharmaceutical grades.
- Ultrafiltration:Pressure-driven concentration across semipermeable membranes retains macromolecules while passing salts and small molecules. Continuous ultrafiltration-diafiltration loops integrate with chromatography skids in South Korean gene therapy facilities.
- Flocculation:Polyelectrolyte-induced aggregation clarifies cell culture harvests prior to downstream purification. Biofuels producers deploy flocculation for algae dewatering where lipid recovery economics tolerate lower separation efficiency.
- Extraction:Aqueous two-phase systems and organic solvent extraction partition target molecules based on partition coefficients. Specialty chemical producers apply extraction for antibiotic recovery from fermentation broths.
Membrane technology commands installed base; ultrafiltration gains share fastest.
Application:
Target molecule characteristics—molecular weight, pH stability, aggregation propensity—dictate purification train configuration and validation depth.
- Biopharmaceuticals:Monoclonal antibodies, recombinant proteins, and plasma-derived therapeutics require multi-step purification with viral clearance validation. FDA process validation guidelines mandate continued process verification with statistical process control for all commercial biologics.
- Enzyme Production:Industrial biocatalysts for detergents, textiles, and food processing tolerate wider purity ranges than pharmaceuticals. Agrochemical developers in India scale enzyme fermentation with simplified downstream trains that omit expensive chromatography polishing steps.
- Vaccines:Inactivated viral vaccines, subunit vaccines, and mRNA lipid nanoparticles each demand specialized purification protocols. Cell and gene therapy manufacturing clusters in Germany and the United States drive demand for viral vector downstream suites.
- Food Additives:Natural colorants, sweeteners, and preservatives from microbial fermentation face FSSAI and FDA food safety regulations rather than GMP pharmaceutical standards. Extraction and membrane concentration dominate this cost-sensitive segment.
- Biofuels:Cellulosic ethanol and algal lipid recovery prioritize throughput over purity, deploying centrifugation and flocculation rather than chromatography. South Korean government biofuel mandates support pilot-scale downstream facilities.
Biopharmaceuticals anchor revenue; vaccines expand most quickly.
End User Industry:
Internal manufacturing capabilities versus outsourced production determines equipment ownership patterns and service contract structures.
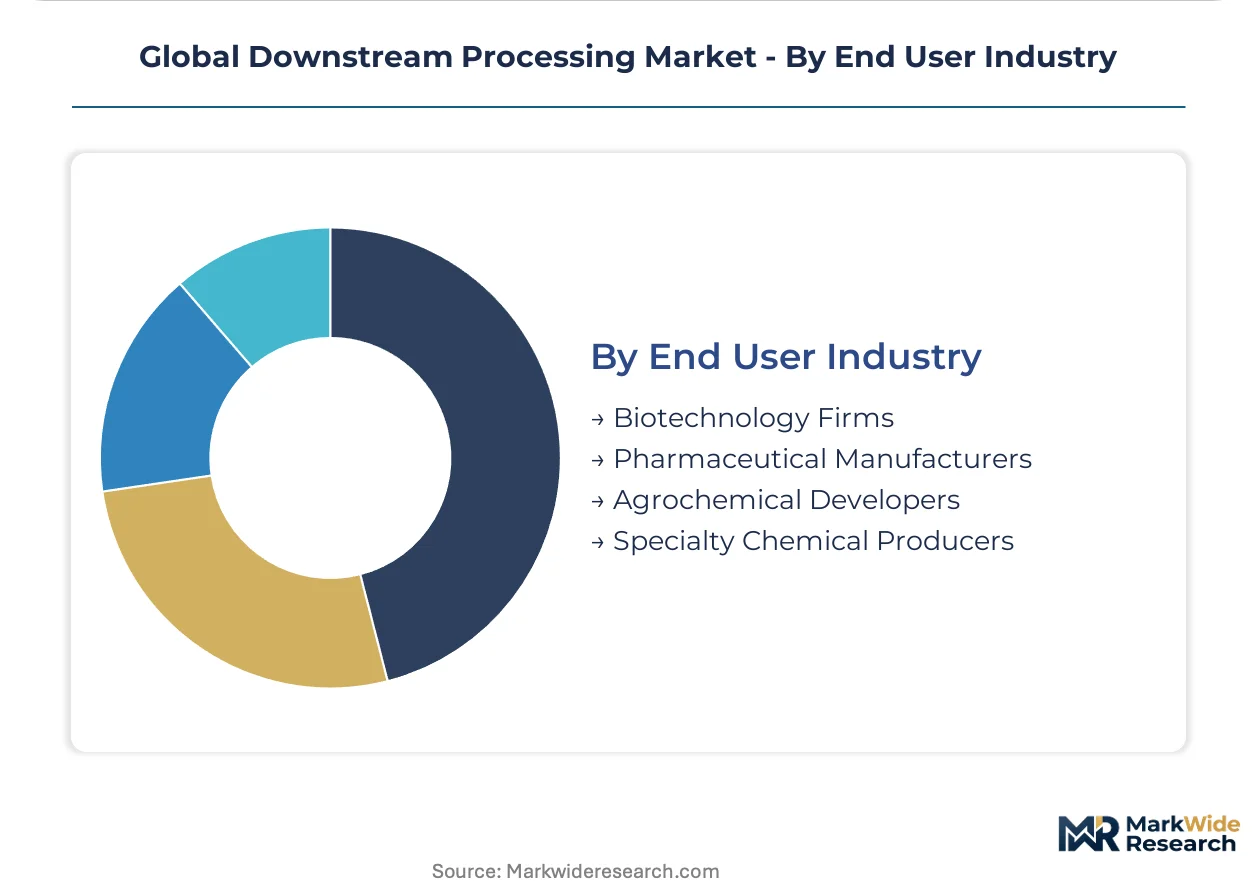
- Biotechnology Firms:Venture-backed developers of novel therapeutics outsource purification process development to specialized CDMOs. These firms specify single-use technologies to preserve capital for clinical milestone funding.
- Pharmaceutical Manufacturers:Large-cap companies with approved biologics portfolios operate validated stainless-steel facilities with decade-long depreciation schedules. FDA inspection history and prior approval supplements constrain their technology migration timelines.
- Agrochemical Developers:Crop protection and biopesticide producers blend in-house fermentation with toll manufacturing for downstream processing. Cost pressure favors precipitation and extraction over chromatography purification.
- Specialty Chemical Producers:Fine chemical and biochemical manufacturers supply pharmaceutical intermediates and industrial enzymes. These operators balance batch flexibility against economies of scale in multi-product facilities.
Pharmaceutical manufacturers dominate installed capacity; biotechnology firms drive new equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates the highest density of cell and gene therapy manufacturing facilities globally. FDA process validation requirements and EMA Annex 1 sterile manufacturing standards shape equipment procurement decisions across all major markets. Regional demand patterns reflect local regulatory timelines, CDMO cluster maturity, and government funding for advanced therapy manufacturing infrastructure.
United States
CAR-T autologous manufacturing facilities in Greater Boston and the San Francisco Bay Area drive single-use chromatography adoption. FDA continued process verification mandates with statistical process control compel electronic batch record integration. The Research Triangle Park in North Carolina anchors viral vector production expansion with purpose-built downstream suites.
Germany
Contract manufacturers in Bavaria and Baden-Württemberg serve Western gene therapy sponsors with EMA-equivalent qualification documentation. EMA Annex 1 revisions mandate closed-system processing for sterile biologics, accelerating stainless-steel replacement. The Rhine-Main biotech cluster around Frankfurt specializes in integrated filtration and separation platforms.
South Korea
Government bioeconomy initiatives fund cell therapy manufacturing infrastructure in the Songdo International Business District. MFDS good manufacturing practice inspections tighten purity benchmarks for viral vector production. The Osong Biovalley hosts rapid-turnaround autologous production facilities requiring disposable processing trains.
India
Contract development organizations in Hyderabad and Bengaluru build viral vector capacity for Western sponsors. CDSCO manufacturing license requirements and export-oriented EMA documentation standards elevate equipment qualification burdens. The Genome Valley biotechnology park anchors integrated downstream purification suite deployment.
Switzerland
Precision biologics manufacturers in the Basel region leverage proximity to German supply chains for chromatography resin procurement. Swissmedic manufacturing authorization standards align with EMA guidelines while permitting accelerated facility qualification. The Zurich biotech corridor specializes in continuous processing architecture implementation.
Global Downstream Processing Market Competitive Landscape
Portfolio diversification dominates the current landscape as equipment vendors expand from chromatography into integrated purification workflows. The market structures around three tiers: diversified life science conglomerates with full workflow coverage, specialized filtration and separation technology providers, and precision diagnostics-to-bioprocessing convergence platforms. Strategic archetypes include resin-and-system bundlers, single-use technology pure-plays, and analytical-to-process control integrators. M&A activity and capacity expansion in Asian CDMO markets represent the dominant competitive moves reshaping supplier relationships.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation occupy positions spanning chromatography resins through process analytical technologies. Sartorius AG exemplifies the specialized filtration archetype with integrated membrane platforms. These three entities collectively represent the competitive spectrum from broad workflow coverage to focused separation technology depth, with each anchoring distinct approaches to single-use system deployment and regulatory qualification support.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Sartorius AG |
| Danaher Corporation |
| GE Healthcare |
| Repligen Corporation |
| Waters Corporation |
| Eppendorf AG |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Chromatography resin base materials originating from Japanese and European chemical suppliers cascade through three-tier pricing structures across premium, standard, and economy levels before reaching biopharmaceutical manufacturers in the United States, Germany, and South Korea.
Pricing Analysis
Input-cost pass-through from agarose and synthetic polymer suppliers concentrates pricing power among resin manufacturers, forcing equipment vendors to absorb margin compression or push increases downstream. Pricing stratifies across premium, standard, and economy tiers based on binding capacity specifications and EMA-equivalent qualification documentation depth. Cost compression in standard-grade resin tiers is intensifying because CDMOs in India and contract manufacturers in Germany compete for gene therapy sponsorships on total cost of ownership metrics. Biotechnology firms with venture-backed funding structures exhibit highest price sensitivity, while large-cap pharmaceutical manufacturers with approved biologics portfolios prioritize qualification speed over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled chromatography resin shipments from Japan and Germany to United States biopharmaceutical clusters has prompted regional inventory pre-positioning near Boston-Cambridge and Research Triangle Park manufacturing corridors. Supply concentrates in Japan for agarose base materials, Germany for synthetic polymer chemistries, and the United States for precision diagnostics-to-bioprocessing convergence platforms. Raw material dependencies span agarose extraction from marine sources, synthetic polymer precursors from petrochemical feedstocks, and precision-machined stainless-steel hardware from German and Swiss metalworking centers. Single-source vulnerability in Protein A affinity ligand production exposes downstream processors to allocation constraints during demand surges. Distribution runs through direct vendor-to-manufacturer relationships for large-cap pharmaceutical accounts, with regional distributors serving mid-tier biotechnology firms and emerging CDMOs in India and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The downstream processing market operates as a regulatory compounder where EMA Annex 1 revisions mandating closed-system processing for sterile biologics accelerate equipment replacement cycles and inflate qualification documentation premiums.
For Market Incumbents: Cement market position by embedding automated cleaning validation and real-time release testing into chromatography software architectures, directly addressing FDA continued process verification mandates that small and mid-sized biotechnology firms lack internal quality systems to satisfy independently. Deepen backward integration into resin regeneration services and predictive maintenance algorithms to capture multi-year operating contract value from contract manufacturers competing for gene therapy sponsorships. Counter emerging entrant pressure in continuous chromatography-membrane hybrid systems through exclusive partnerships with South Korean and German CDMOs building viral vector capacity. For New Entrants and Emerging Players: Continuous processing architecture expertise offers entry traction against incumbent batch-optimized portfolios, particularly among Switzerland-based precision biologics manufacturers and Zurich biotech corridor operators implementing simulated moving bed technology. White-space concentration appears in India CDMO expansion serving Western gene therapy sponsors with EMA-equivalent qualification documentation, and in ISO 13485 certification pathways for cell therapy manufacturing equipment where quality management standards command premium positioning. Penetrate through point-of-care manufacturing partnerships with university hospitals deploying prefabricated cleanroom pods with disposable flow paths. For Investors and Strategic Acquirers: Roll-up economics work for specialized filtration and separation technology providers because facility footprint reduction demands and single-use containment technology mandates create acquisition currency for integrated platform vendors. Long-term viability through the analysis window hinges on exposure to cell and gene therapy manufacturing cluster expansion rather than legacy monoclonal antibody stainless-steel infrastructure. Target acquisition archetype: membrane technology pure-plays with EMA Annex 1-compliant closed-system processing portfolios. Signal to monitor: MFDS inspection intensity in South Korea and CDSCO manufacturing license enforcement in India as leading indicators of qualification documentation premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography-Membrane Hybrid System Development | Convergence technologies eliminate intermediate hold tanks and reduce facility footprint by two-thirds for urban biotech clusters. |
| EMA-Equivalent Qualification Documentation Investment | CDMOs in Hyderabad and Bengaluru require compliant suites to serve Western gene therapy sponsors. |
| Single-Use Containment Technology Manufacturing Scale-Up | EMA Annex 1 revisions mandate closed-system processing replacement of open stainless-steel infrastructure. |
| Resin Regeneration and Predictive Maintenance Service Expansion | Finance departments amortize resin lifetime across multi-year operating contracts favoring vendors with service depth. |
| ISO 13485 Certification Pathway Development | Medical device quality management standards expand into cell therapy equipment allowing premium positioning. |
Research Methodology
Multiple input streams — purification process development executives at biotechnology firms, regulatory affairs leads navigating FDA process validation protocols, CDMO procurement managers evaluating total cost of ownership, chromatography resin technical specialists, and EMA inspection history analysts — were reconciled against FDA 483 observation databases, EMA manufacturing authorization records, ISO 13485 certification registries, and SEC filings from diversified life science conglomerates. Bottom-up equipment shipment data and top-down biopharmaceutical capital expenditure disclosures were triangulated to anchor market sizing.
Data-stream reconciliation across product type, technology, application, and end user industry dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured chromatography systems versus filtration units versus centrifuges by membrane technology versus precipitation versus ultrafiltration by biopharmaceuticals versus vaccines versus enzyme production by biotechnology firms versus pharmaceutical manufacturers. CAGRs were derived from facility expansion announcements, CDMO capacity buildout timelines, and regulatory inspection intensity trends. Industry-specific forecast inputs included Protein A resin innovation cycles, autologous CAR-T manufacturing facility commissioning rates, and viral vector downstream suite qualification documentation depth.
The model holds under sustained regulatory tightening in United States, European, and South Korean jurisdictions; deviation in resin supply allocation constraints or stainless-steel asset stranding decisions by large-cap pharmaceutical manufacturers would shift equipment procurement mix assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Global Qpcr Reagents Market