
 Global CRISPR and Cas Genes Market | 2026-2036
Global CRISPR and Cas Genes Market Size, Share, and Industry Trends Forecast 2026-2036
Global CRISPR and Cas Genes Market Foresight
The CRISPR reagent landscape is pivoting on a sharp split between GMP-grade clinical vectors and research-use-only plasmids. Thermo Fisher Scientific leverages its end-to-end workflow portfolio to dominate high-volume research supply. Danaher Corporation anchors its position through precision instrumentation that tightens editing fidelity. CRISPR Therapeutics AG differentiates by concentrating therapeutic programs on validated targets with established delivery routes.
CRISPR and Cas genes comprise programmable RNA-guided nucleases and their associated DNA-cleavage machinery, typically requiring a protospacer-adjacent motif for target recognition and a guide RNA length of 20 nucleotides for specificity. These systems enable directed genetic modification across mammalian, plant, and microbial cells for therapeutic correction, trait enhancement, or metabolic engineering. The Crispr-Cas9 product category retains the largest installed base but faces margin compression as patent pools expire. Agricultural Biotechnology applications are expanding fastest as seed companies pursue drought-tolerant and disease-resistant varietals with reduced regulatory burden relative to transgenic approaches. Gene Therapy commands premium pricing due to stringent GMP compliance and lot-release testing requirements.
The FDA oversees Investigational New Drug applications for CRISPR-based therapeutics while the EMA enforces Good Manufacturing Practice standards for clinical-grade reagents entering European trials. China's NMPA has accelerated gene-edited agricultural product approvals under revised biosafety guidelines, opening a parallel demand channel distinct from Western therapeutic focus. Stakeholders must monitor how divergent regulatory pathways for food versus medicine reshape supplier qualification requirements and geographic market access.
Market Dynamics
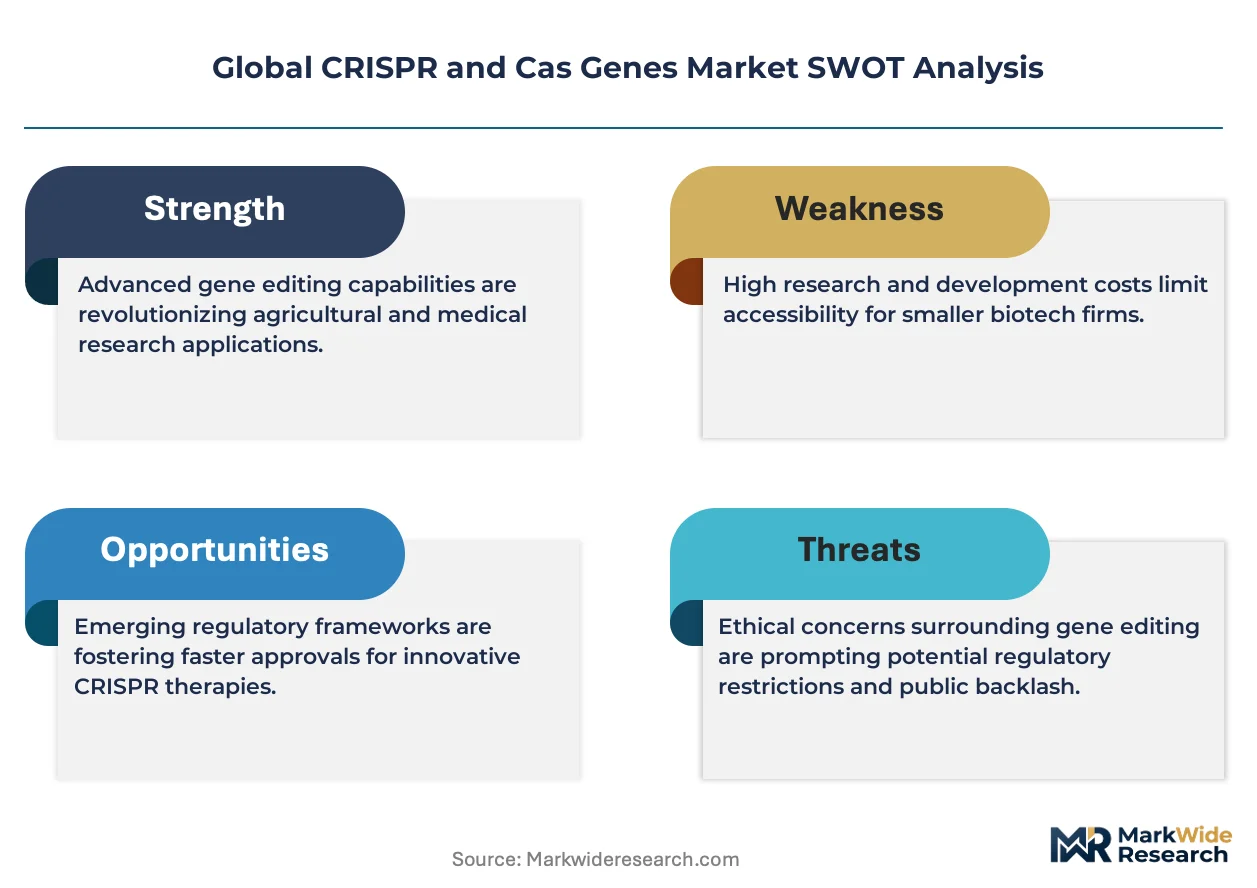
The CRISPR and Cas Genes Market pivots on the divergence between research-grade reagent commoditization and clinical-grade vector scarcity, with GMP certification bottlenecks now determining supplier viability more than raw technical performance.
Growth Catalysts
- EMA GMP framework tightening:Stringent purity standards for clinical-grade reagents are filtering out marginal suppliers and concentrating procurement among qualified vendors.
- Agricultural Biotechnology expansion:Seed companies in the United States and China are accelerating gene-edited crop programs for drought-tolerant varietals.
- Base editing maturation:Cytosine and adenine base editors are expanding addressable disease targets beyond double-strand break limitations.
Market Restraints
- GMP plasmid supply concentration:Clinical-grade DNA manufacturing clusters heavily in Germany and the United States, creating geographic vulnerability.
- Guide RNA synthesis cost volatility:Phosphoramidite raw material pricing swings squeeze margins for high-complexity synthetic guides.
- Off-target liability exposure:Persistent editing fidelity limitations elevate indemnification costs for therapeutic developers.
Strategic Opportunities
- India CDMO emergence:Contract development and manufacturing organizations in India are building GMP capabilities to capture overflow demand from Western biopharma.
- In vivo delivery convergence:Lipid nanoparticle and viral vector platform integration is opening new organ-specific targeting possibilities.
- China NMPA agricultural pathway:Accelerated gene-edited crop approvals under revised biosafety guidelines create parallel demand distinct from therapeutic markets.
Industry Challenges
- GMP auditor scarcity:Qualified inspectors for gene therapy manufacturing facilities are in critically short supply, extending facility qualification timelines.
- Legacy plasmid backbone IP:Persistent licensing disputes over foundational vector architectures complicate freedom-to-operate analyses for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CRISPR and Cas Genes Market |
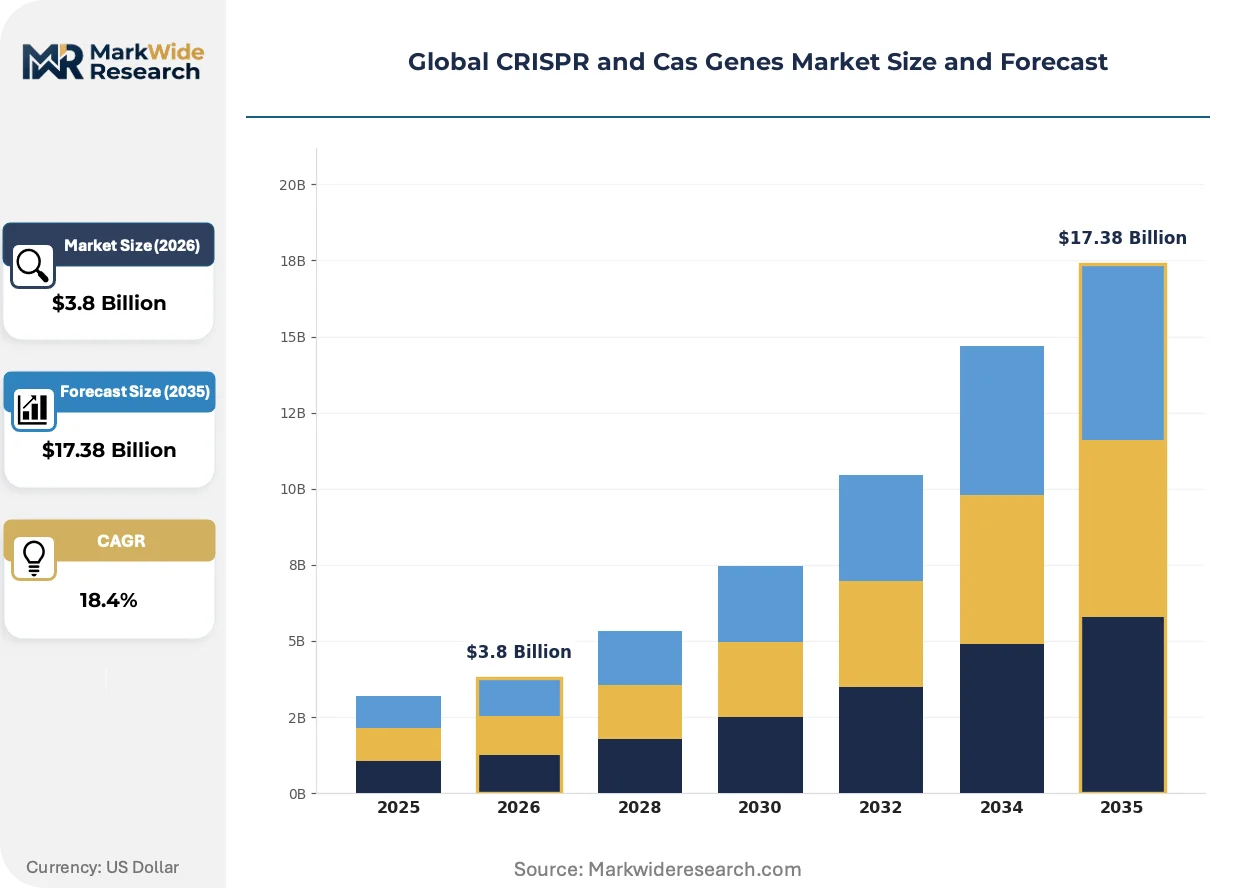
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crispr-Cas9, Crispr-Cas12, Crispr-Cas13, Crispr-Cas14, Base Editors Application: Gene Therapy, Agricultural Biotechnology, Industrial Biotech, Molecular Diagnostics, Functional Genomics End User: Research Laboratories, Biopharmaceutical Companies, Agricultural Firms, Contract Research Organizations, Diagnostic Centers Delivery Method: Viral Vectors, Lipid Nanoparticles, Electroporation, Microinjection, Physical Methods |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Merck KGaA, Illumina, Agilent Technologies, GenScript, CRISPR Therapeutics AG, Editas Medicine, OriGene Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CRISPR and Cas Genes Market Shifts & Advancements
CRISPR tooling is fragmenting into specialized modalities as base editors, prime editors, and epigenetic modifiers carve out distinct therapeutic niches, while regulatory frameworks race to keep pace with technical diversification.
Prime editing is decentralizing therapeutic development by enabling precise insertions and deletions without double-strand breaks or donor DNA templates. Mid-size biotech firms in Boston and Basel are adopting the platform for previously intractable monogenic diseases. The technology is decentralizing gene correction from large pharmaceutical infrastructure toward nimble, indication-focused development shops.
China's NMPA has issued technical guidelines distinguishing gene-edited crops from transgenic organisms, reducing regulatory burden for stacked trait development. Seed companies are reconfiguring R&D pipelines toward CRISPR-derived varietals with faster approval timelines. The policy shift most affects drought-resistant cereals targeting the North China Plain, where water stress is accelerating farmer adoption.
Biopharma procurement departments are consolidating guide RNA suppliers to reduce lot-to-lot variability in clinical programs. Long-term exclusive supply agreements are displacing spot purchasing for Phase II and III trials. This concentration is most pronounced in the United States, where FDA IND holders prioritize audit history over unit cost in vendor selection.
Global CRISPR and Cas Genes Market Segmentation
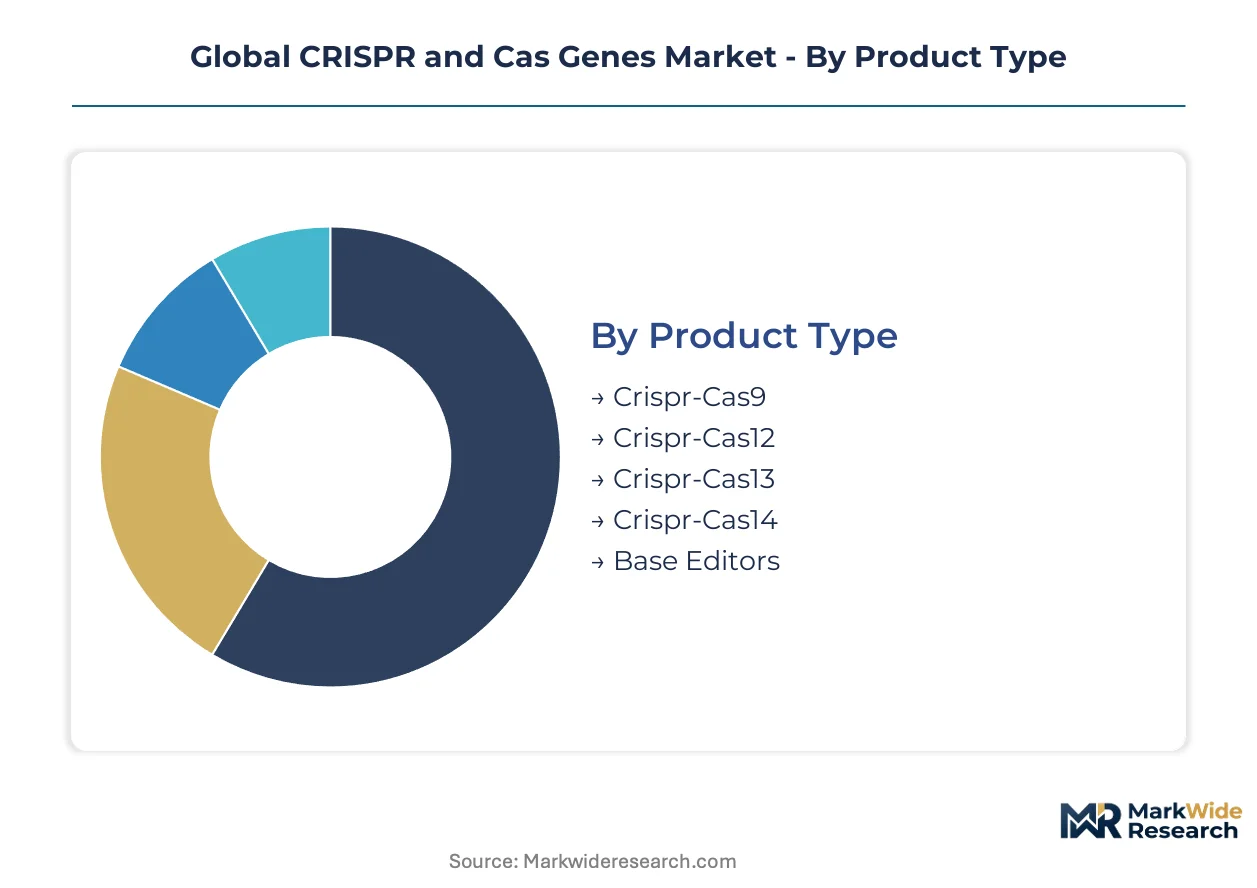
CRISPR market segmentation reveals how technical specifications, regulatory pathways, and end-use requirements fragment procurement behavior across fundamentally different buyer archetypes. Understanding these divides explains why pricing and supplier qualification criteria vary dramatically within the same product category.
Product Type:
Buyers segment primarily by editing precision requirements and intellectual property freedom, with clinical developers prioritizing fidelity metrics over research labs focused on cost per experiment.
- Crispr-Cas9:The original dual-RNA-guided nuclease system retains the largest installed instrumentation base across academic and commercial laboratories. Demand concentrates in United States research universities and Chinese agricultural institutes where established protocols minimize retraining costs, though margin compression intensifies as foundational patents expire.
- Base Editors:Cytosine and adenine deaminase fusions enable precise C-to-T or A-to-G conversions without double-strand breaks. Biopharma developers in Boston and Basel are adopting these systems for monogenic disorders where point mutation correction suffices, driving premium pricing for high-fidelity variants.
- Crispr-Cas12:Class 2 type V nucleases provide collateral cleavage activity exploitable for diagnostic signal amplification. Agricultural firms in Brazil and Australia are evaluating Cas12a for multiplexed trait stacking in cereals.
- Crispr-Cas13:RNA-targeting effectors enable transcriptome engineering and antiviral applications without genomic modification. Research laboratories in Germany and South Korea are deploying Cas13 for temporary gene knockdown studies.
- Crispr-Cas14:Ultra-compact single-RNA-guided nucleases derived from archaeal phages facilitate viral vector packaging constraints. Gene therapy developers exploring in vivo liver targeting are piloting Cas14 systems for size-restricted delivery vehicles.
Volume sits with Crispr-Cas9; growth tilts toward Base Editors.
Application:
Regulatory pathway divergence creates distinct procurement ecosystems, with clinical-grade vector manufacturing commanding tenfold price multiples over research reagents despite identical underlying biochemistry.
- Gene Therapy:In vivo and ex vivo therapeutic correction programs require GMP-certified reagents with extensive lot-release documentation. FDA IND holders in the United States and EMA-aligned developers in Switzerland and the Netherlands dominate procurement, prioritizing audit history over unit economics.
- Agricultural Biotechnology:Seed companies exploit reduced regulatory burden for gene-edited crops versus transgenic organisms in China, the United States, and Argentina. Drought-tolerant cereals targeting water-stressed regions of the North China Plain and the American Great Plains are expanding fastest.
- Industrial Biotech:Microbial strain engineering for enzyme production and biofuel synthesis employs CRISPR for metabolic pathway optimization. Contract manufacturers in India and Singapore are scaling CRISPR-edited yeast platforms for pharmaceutical precursor synthesis.
- Molecular Diagnostics:CRISPR-based nucleic acid detection leverages collateral cleavage for signal amplification. Diagnostic centers in South Korea and the United Kingdom are validating SHERLOCK and DETECTR platforms for point-of-care infectious disease testing.
- Functional Genomics:High-throughput screening and pathway mapping applications consume research-grade reagents at scale. Academic consortia in Germany and Japan are deploying CRISPR libraries for whole-genome knockout studies.
Revenue concentrates in Gene Therapy; Agricultural Biotechnology is climbing the fastest.
End User:
Procurement sophistication varies by organizational scale, with large biopharmaceutical companies enforcing supplier consolidation while research laboratories prioritize flexibility and rapid turnaround.
- Biopharmaceutical Companies:Integrated therapeutic developers maintain captive GMP manufacturing or exclusive long-term supply agreements with qualified CDMOs. United States and Swiss firms are consolidating guide RNA suppliers to reduce lot-to-lot variability in Phase II and III programs.
- Research Laboratories:Academic and government institutes purchase research-use-only reagents through distributor channels with minimal qualification overhead. Chinese and German universities represent high-volume spot purchasers sensitive to per-reaction pricing.
- Agricultural Firms:Seed companies and crop science divisions deploy CRISPR for varietal development with regulatory affairs teams navigating divergent national biosafety frameworks. Brazilian and Australian firms are expanding gene-edited soybean and wheat pipelines.
- Contract Research Organizations:Service providers serving multiple sponsor clients require flexible reagent sourcing across quality grades. Indian and Singaporean CROs are building GMP capabilities to capture overflow from Western biopharma.
- Diagnostic Centers:Clinical laboratories validate CRISPR-based assays under ISO 15189 or CAP accreditation. South Korean and United Kingdom health systems are piloting CRISPR diagnostics for tuberculosis and SARS-CoV-2 variant detection.
Procurement volume aggregates with Research Laboratories; contract value expansion favors Biopharmaceutical Companies.
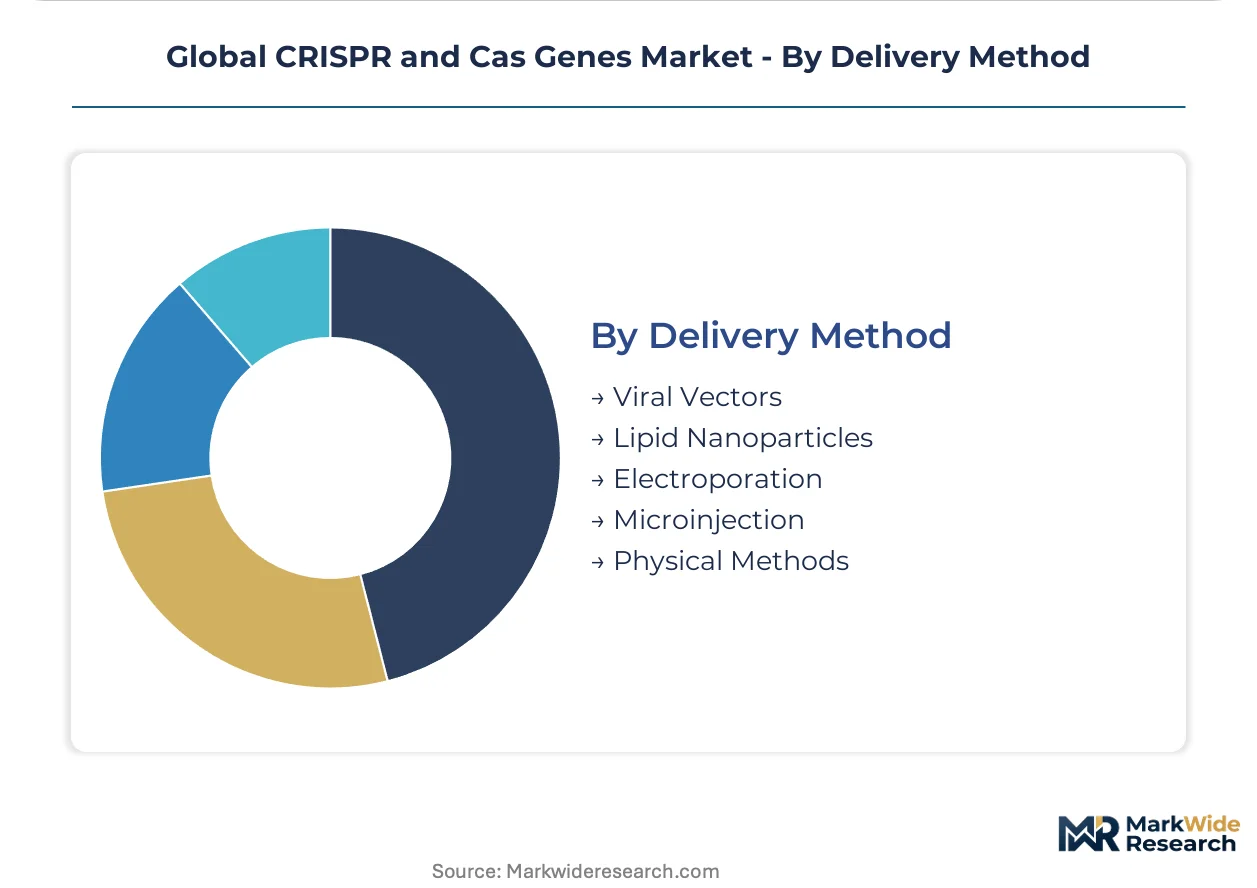
Delivery Method:
Organ targeting requirements and manufacturing scalability determine vector selection, with liver-directed programs converging on lipid nanoparticles while central nervous system indications remain dependent on viral engineering.
- Viral Vectors:Adeno-associated virus and lentiviral platforms enable stable transduction of dividing and non-dividing cells. United States and German gene therapy developers are securing dedicated viral vector manufacturing capacity amid chronic supply shortages.
- Lipid Nanoparticles:Ionizable lipid formulations facilitate transient hepatic delivery of mRNA-encoded CRISPR components. Biopharma firms in Massachusetts and California are integrating LNP platforms inherited from COVID-19 vaccine programs into gene editing pipelines.
- Electroporation:Ex vivo cell modification employs electrical membrane permeabilization for ribonucleoprotein delivery. CAR-T developers in China and the United States are scaling electroporation-based editing for autologous cell therapy manufacturing.
- Microinjection:Direct cytoplasmic delivery remains essential for embryo editing in agricultural applications. Seed companies in Japan and the Netherlands maintain specialized microinjection facilities for trait introduction in recalcitrant cereal varieties.
- Physical Methods:Cell-penetrating peptide conjugation and mechanical disruption techniques address delivery challenges in plant and microbial systems. Industrial biotech facilities in India are adopting sonoporation for CRISPR delivery to yeast and fungal chassis.
Clinical development volume clusters with Viral Vectors; Lipid Nanoparticles are gaining share fastest as liver-directed programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor anchors the densest concentration of gene therapy developers and CRISPR tool suppliers worldwide. The metropolitan area hosts overlapping ecosystems of academic research hospitals, venture capital, and specialized manufacturing infrastructure that smaller clusters struggle to replicate.
United States
FDA Investigational New Drug applications for CRISPR therapeutics concentrate in Massachusetts and California biopharma corridors. The agency's gene therapy framework enforces stringent purity standards that filter procurement toward qualified GMP vendors. Cambridge and South San Francisco house the dominant share of clinical-stage editing programs.
China
NMPA accelerated gene-edited agricultural product approvals under revised biosafety guidelines issued in recent years. Drought-resistant cereal development targets the North China Plain where water stress intensifies farmer demand. Beijing and Shanghai clusters drive parallel therapeutic and agricultural CRISPR pipelines.
Germany
EMA Good Manufacturing Practice standards for clinical-grade reagents concentrate qualified plasmid manufacturing in Bavaria and Baden-Württemberg. Heidelberg and Munich anchor precision instrumentation and editing fidelity tool development. German facilities face chronic GMP auditor scarcity extending qualification timelines.
Switzerland
Swissmedic alignment with EMA standards positions Basel as a gene therapy development hub alongside pharmaceutical legacy infrastructure. The country's therapeutic developers prioritize audit history over unit cost in vendor selection. Zurich and Geneva corridors support specialized guide RNA synthesis capabilities.
India
Contract development and manufacturing organizations in Hyderabad and Bangalore are building GMP capabilities to capture overflow demand from Western biopharma. The national pharmaceutical regulator oversees emerging gene therapy manufacturing capacity. Indian CDMOs target cost advantages in clinical-grade reagent production.
Global CRISPR and Cas Genes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification-grade divide, with GMP-qualified vector suppliers commanding tenfold price multiples over research-grade reagent vendors. The vendor base stratifies into three tiers: integrated life science conglomerates with end-to-end workflow portfolios, precision instrumentation specialists tightening editing fidelity, and therapeutic developers concentrating on validated targets. Dominant competitive moves include long-term exclusive supply agreements displacing spot purchasing, and backward integration into captive GMP manufacturing capacity.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven positions spanning research through clinical-grade supply. CRISPR Therapeutics AG occupies a distinct archetype as a therapeutic developer concentrating programs on established delivery routes. These three entities represent divergent strategic postures: horizontal workflow integration, precision instrumentation dominance, and indication-focused therapeutic development.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Merck KGaA |
| Illumina |
| Agilent Technologies |
| GenScript |
| CRISPR Therapeutics AG |
| Editas Medicine |
| OriGene Technologies |
| Others |
Supply & Pricing Matrix
Phosphoramidite pricing volatility cascades through synthetic guide RNA production into three distinct procurement tiers: GMP-certified clinical vectors, qualified research reagents, and unqualified spot-market supplies. Buyers in the United States and Germany absorb premium multiples for audit-documented lots while Chinese agricultural institutes optimize for per-reaction cost efficiency.
Pricing Analysis
Outcome-based pricing anchors clinical-grade CRISPR reagents to therapeutic correction success rates rather than input volumes. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified vectors from qualified research-grade from unqualified spot supplies. Cost compression in research-grade Cas9 plasmids intensifies as foundational patent pools expire and Chinese manufacturers scale fermentation capacity. Academic laboratories in Germany and Japan exhibit highest price sensitivity, while FDA IND holders in Massachusetts prioritize supplier audit history over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with phosphoramidite precursor manufacturing concentrated in Germany and the United States. Clinical-grade plasmid production draws from Bavarian and Baden-Württemberg facilities, with guide RNA synthesis anchored in Massachusetts and Zurich corridors. Tariff exposure on Chinese-sourced research-grade reagents threatens margin structures for European distributors. Distribution runs through qualified CDMO networks for clinical vectors and distributor channels for research supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global CRISPR and Cas Genes Market reads as a cost-of-compliance story where EMA GMP framework tightening constructs a barrier-to-entry moat favoring incumbent qualified suppliers over marginal entrants.
For Market Incumbents: Cement captive GMP manufacturing capacity in Germany and the United States to foreclose CDMO overflow opportunities for emerging Indian competitors. Consolidate guide RNA supplier relationships through exclusive long-term agreements that lock in Phase II and III trial procurement, while patent expiration pressure on Cas9 margins demands backward integration into high-fidelity base editor portfolios. For New Entrants and Emerging Players: Agricultural biotechnology firms in Brazil and Australia represent an underserved buyer archetype seeking drought-tolerant cereal editing platforms outside saturated North American and Chinese channels. Target gene-edited soybean and wheat pipelines with regulatory affairs support bundled into reagent supply contracts, leveraging faster approval timelines under revised biosafety frameworks versus therapeutic pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision instrumentation specialists in Germany and Switzerland facing temporary GMP auditor scarcity elongating facility qualification timelines. Long-term viability hinges on editing fidelity tool development converging with in vivo delivery platform integration, with the signal to monitor being NMPA agricultural approval velocity as indicator of parallel demand channel maturation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EMA qualification barriers filter procurement toward audited Bavarian and Massachusetts facilities. |
| Base Editor Pipeline Expansion | Cytosine and adenine deaminase fusions address monogenic disorders beyond double-strand break limitations. |
| Agricultural Regulatory Affairs Capability | NMPA technical guidelines distinguish gene-edited crops from transgenic organisms in China. |
| Guide RNA Supplier Consolidation | FDA IND holders in the United States prioritize lot-to-lot consistency over per-reaction pricing. |
| In Vivo Delivery Platform Integration | Lipid nanoparticle convergence from COVID-19 vaccine programs enables liver-directed therapeutic editing. |
Research Methodology
Document review covered FDA IND filings, EMA GMP inspection reports, NMPA biosafety guidelines, and patent expiration databases, complemented by interviews with gene therapy development executives, regulatory affairs leads at CDMOs, agricultural biotechnology R&D directors, and CRISPR platform engineers. Secondary validation drew from ClinicalTrials.gov entries, SEC 10-K disclosures, and customs trade data on phosphoramidite imports. Bottom-up reagent demand modeling and top-down therapeutic pipeline valuation were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs on regulatory approval velocity and delivery technology maturation. The analytical framework segmented across product type, application, end user, and delivery method dimensions throughout the forecast period. CAGRs were derived from fitted growth curves incorporating base editing adoption rates, agricultural approval pathway divergence, and GMP capacity expansion timelines. Industry-specific inputs included EMA auditor availability projections and NMPA agricultural guidance revision cycles.
Revisions become necessary when phosphoramidite supply disruptions, GMP facility inspection backlogs, or divergent national biosafety interpretations materialize. Forecasts reflect documented assumptions on regulatory harmonization and delivery technology convergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Zinc Finger Nuclease Technology Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market
Gene Editing & CRISPR
CRISPR Gene Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Gene Editing Technology Market