
 Moisture Curing Adhesives Market | 2026-2036
Moisture Curing Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Curing Adhesives Market Intelligence
The performance gap between commodity-grade polyurethane adhesives for general construction and specialized silicone formulations for electronics is shifting competitive dynamics. Henkel AG & Co. KGaA leverages its scale in the construction segment to offer cost-effective solutions. In contrast, 3M Company specializes in high-margin applications within automotive and aerospace. Sika AG positions its portfolio to capture demand across both high-volume and specialty applications, navigating varied customer requirements.
Moisture curing adhesives are single-component systems that polymerize and form a bond by reacting with moisture present in the air or on the substrate surface. These materials provide strong adhesion to dissimilar substrates without the need for heat, radiation, or complex mixing. Polyurethane adhesives represent the largest product segment by volume, driven by the construction end-user market. The automotive sector, however, offers higher margins for specialized formulations used in structural bonding and sealing applications.
Regulatory frameworks are a primary influence on product formulation and market access. The US Environmental Protection Agency (EPA) and Europe's REACH regulation impose strict limits on volatile organic compound (VOC) content. These rules, along with China's GB standards, compel manufacturers to develop lower-VOC and solvent-free adhesive systems. Formulators must continuously balance the need for regulatory compliance with the performance and cost expectations of diverse end-user industries.
Market Dynamics
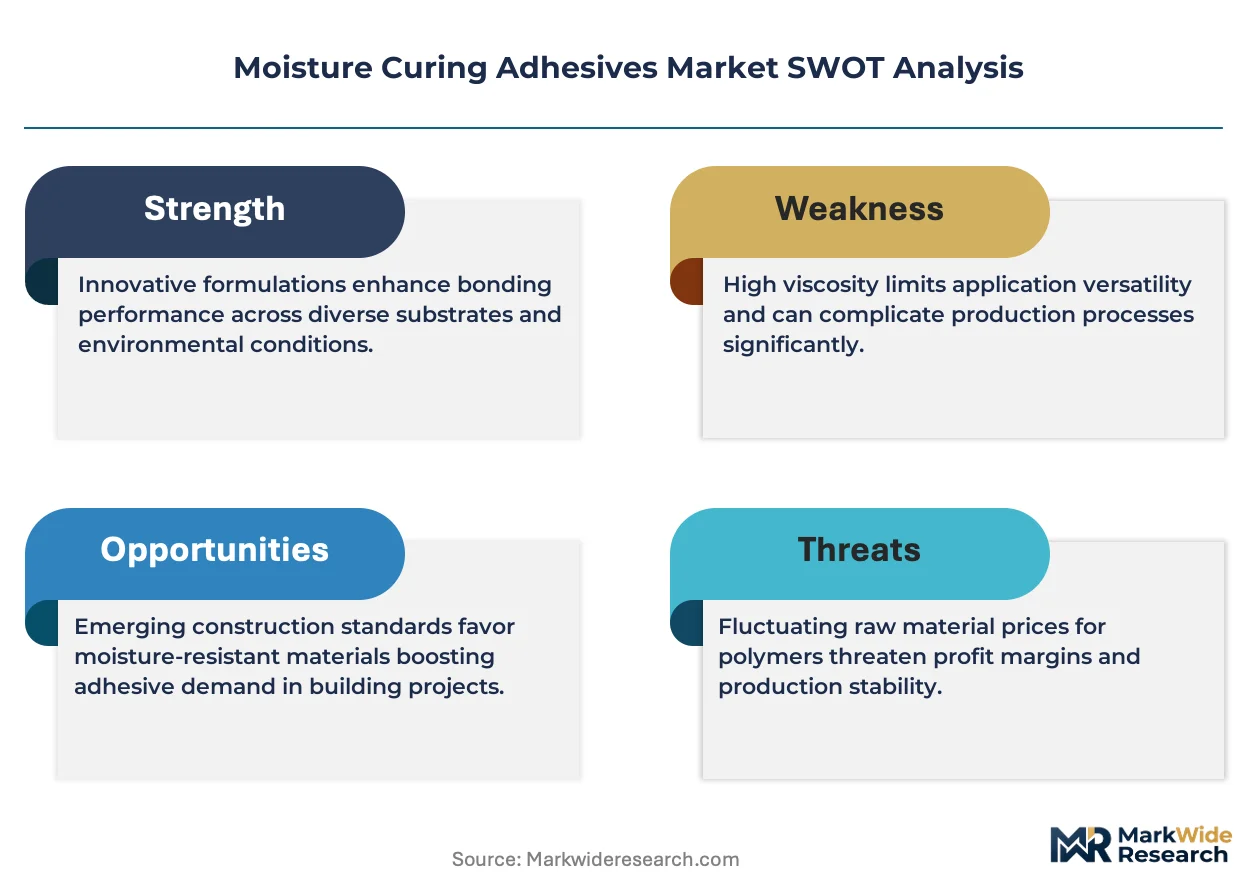
The imperative to reduce volatile organic compound emissions under global regulatory frameworks is the central force shaping the moisture curing adhesives market. This pressure compels innovation in polymer chemistry to deliver compliant, high-performance systems for demanding industrial applications.
Growth Catalysts
- Automotive Lightweighting:The push for greater fuel efficiency and extended range in electric vehicles drives the use of moisture curing adhesives for bonding dissimilar materials like composites, aluminum, and high-strength steel in body-in-white and battery pack assembly.
- Stringent VOC Regulations:Rules such as Europe's REACH framework and directives from the US Environmental Protection Agency (EPA) accelerate the substitution of solvent-borne adhesives, creating direct demand for single-component, low-VOC moisture curing formulations.
- Prefabricated Construction Methods:The expansion of modular and off-site building practices requires fast-setting, weather-resistant adhesives for structural panel bonding, window installation, and facade sealing, favoring moisture curing systems for their ease of use and reliability.
Market Restraints
- Cure Rate Sensitivity:Bond formation speed and ultimate performance are highly dependent on ambient temperature and relative humidity, creating process control challenges and inconsistent outcomes in variable manufacturing or construction site environments.
- Isocyanate Price Volatility:The cost structure of polyurethane adhesives, the largest product segment, is directly tied to a volatile supply chain for MDI and TDI precursors, creating pricing instability for formulators and end-users.
- Substitution from Two-Component Adhesives:In applications requiring rapid, predictable curing and maximum bond strength, two-component epoxies and methyl methacrylates present a significant substitution threat due to their controlled reaction mechanism.
Strategic Opportunities
- Bio-Based Formulations:Sustainability mandates under policies like the EU Green Deal create commercial opportunities for developing moisture curing adhesives from renewable feedstocks, such as bio-based polyols, to reduce carbon footprint.
- Flexible Electronics and Wearables:The development of low-modulus, high-elongation silicone and silane-modified polymer adhesives opens a new application frontier for bonding and encapsulating components in flexible hybrid electronics and wearable medical sensors.
- Manufacturing Expansion in Southeast Asia:Growth in automotive and electronics assembly within Vietnam, Thailand, and Malaysia offers an underpenetrated market for specialized adhesive formulations that meet the performance standards of export-oriented industries.
Industry Challenges
- Global Formulation Harmonization:Creating a single adhesive product that complies with the disparate chemical inventories and labeling requirements of Europe's REACH, the US EPA, and China's GB standards is a major technical and administrative burden.
- End-User Application Training:Bond failures are frequently traced to improper surface preparation or application technique by the end-user, requiring adhesive manufacturers to invest heavily in field technical support and customer training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Curing Adhesives Market |
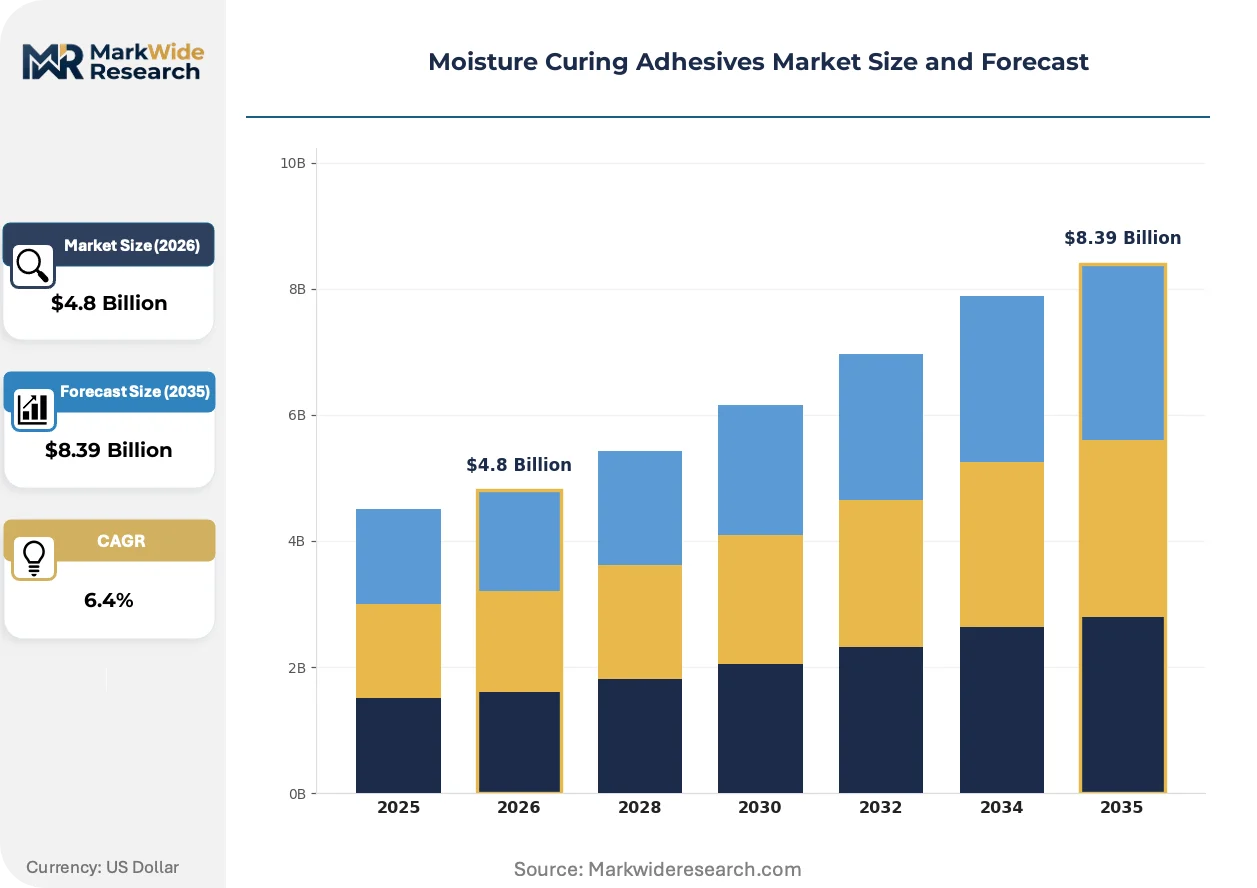
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Adhesives, Hot Melt Adhesives, Silicone Adhesives, Polyamide Adhesives End User: Construction, Automotive, Aerospace, Electronics Application: Woodworking, Coatings, Flooring, Packaging Technology: Solvent-Based, Water-Based, UV-Cured, Structural |
| Companies Covered | Sika AG, Dow, Inc., Henkel AG & Co. KGaA, Jowat SE, Tosoh Corporation, 3M Company, Bostik SA, Dymax Corporation, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Curing Adhesives Market Strategic Shifts & Innovations
Formulation science is converging with digital process control, enabling higher performance and greater reliability in industrial applications. This integration addresses both regulatory pressures for safer materials and end-user demands for manufacturing efficiency and quality assurance.
Smart dispensing systems integrated with real-time sensors monitor bead geometry, application temperature, and ambient humidity. The automotive and aerospace sectors are adopting these systems for critical structural bonding and sealing tasks. This technology is automating quality control processes, reducing material waste and ensuring consistent bond line integrity in high-volume assembly lines.
China's "dual carbon" goals and updated GB standards are imposing stricter limits on VOCs and hazardous substances like free isocyanate monomers. This regulatory push is compelling a rapid shift toward solvent-free and low-monomer polyurethane and silane-modified polymer (SMP) formulations. The building and construction sector is most affected, forcing suppliers to reformulate products specifically for the Chinese market to maintain access.
A demand-side shift toward evaluating life-cycle performance is replacing purely cost-per-unit procurement metrics in certain segments. End-users in infrastructure and commercial transportation specify adhesives based on long-term durability and environmental resistance, not just initial bond strength. This trend is most visible for public works projects and heavy-duty vehicle manufacturing in North America and Europe.
Moisture Curing Adhesives Market Segmentation
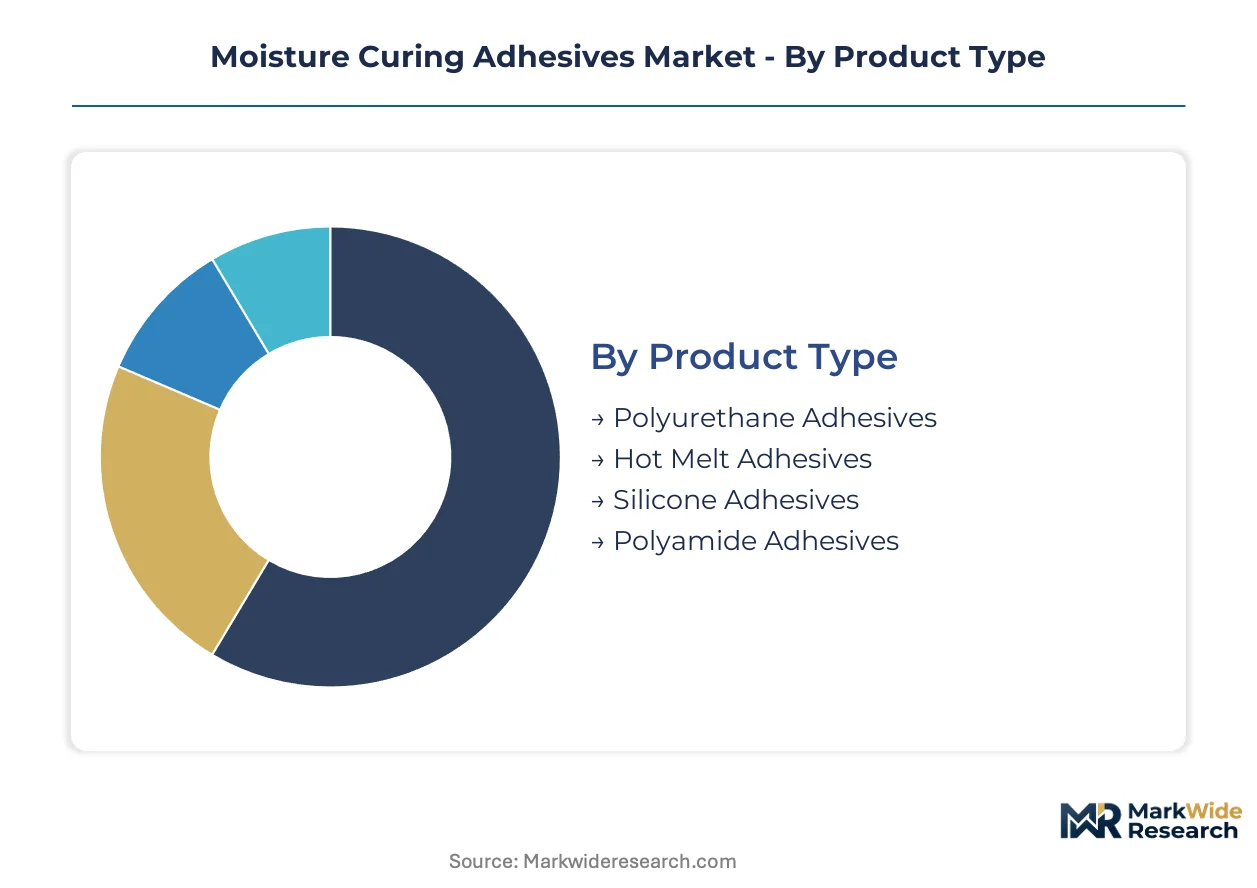
Understanding the distinct segments within the moisture curing adhesives market is critical for identifying specific growth vectors and navigating varied regulatory landscapes. Each category presents unique technical requirements and market dynamics that influence product development and commercial strategies.
Product Type:
The product type segmentation highlights varying regulatory approval pathways and performance specifications required for market access.
- Polyurethane Adhesives:These polymer systems form strong bonds by reacting with ambient moisture, offering versatility across many substrates. Construction and general assembly applications drive significant volume, though stricter VOC limits under Europe's REACH framework necessitate solvent-free formulations.
- Silicone Adhesives:Silicone-based formulations provide excellent flexibility, UV resistance, and thermal stability, making them suitable for demanding environments. Electronics and high-performance automotive applications require these specialized materials due to their durability and encapsulating properties.
- Hot Melt Adhesives:These adhesives melt upon heating and solidify upon cooling, offering fast processing speeds in packaging and assembly.
- Polyamide Adhesives:Polyamide systems offer good temperature resistance and strong adhesion for textile bonding and automotive interiors.
Polyurethane Adhesives sits at the top of the volume ranking, with Silicone Adhesives climbing the fastest.
End User:
This segmentation illustrates how diverse end-user industries prioritize different performance attributes and regulatory compliance levels.
- Construction:Construction relies on moisture curing adhesives for structural glazing, panel bonding, and sealing applications due to their weather resistance and ease of use. The EU Green Deal initiatives are accelerating demand for sustainable, low-VOC solutions in this high-volume sector.
- Automotive:The automotive industry utilizes these adhesives for structural bonding, interior trim, and battery pack assembly, driven by lightweighting mandates. Manufacturers specify high-performance formulations for bonding dissimilar materials like aluminum and composites.
- Aerospace:Aerospace applications demand extremely high-performance and durable adhesives for structural integrity and vibration damping in critical components.
- Electronics:Electronics manufacturing employs moisture curing adhesives for encapsulation, component bonding, and flexible circuit assembly requiring precise application.
The demand from the Construction sector continues to underpin market stability, while the Automotive sector seeks increasingly specialized formulations.
Application:
The application segment reveals where moisture curing adhesives provide specific functional benefits and processing advantages.
- Woodworking:Adhesives for woodworking offer strong, durable bonds for furniture, flooring, and structural timber components, often requiring moisture resistance. Prefabricated construction methods increasingly leverage these systems for efficient off-site assembly.
- Flooring:Flooring installations benefit from moisture curing adhesives' strong adhesion to various subfloors and resistance to moisture vapor transmission. Commercial and industrial projects demand long-term durability and low-VOC emissions for indoor air quality.
- Coatings:Moisture curing systems provide protective coatings with enhanced durability and chemical resistance for industrial and architectural surfaces.
- Packaging:Packaging applications use these adhesives for strong bonds on diverse substrates, facilitating high-speed assembly and product integrity.
Woodworking applications represent a significant volume base, with Flooring applications showing consistent expansion due to construction trends.
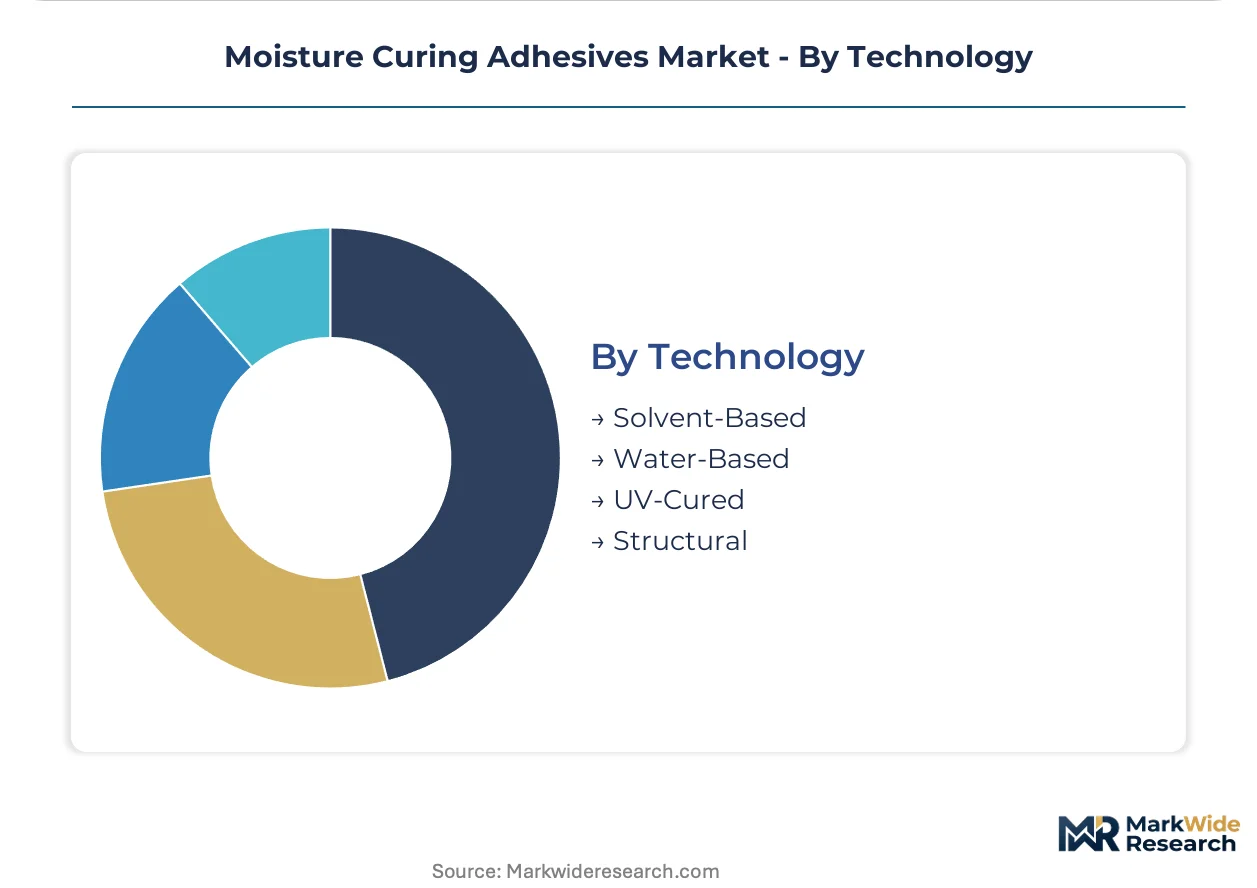
Technology:
Technology segmentation highlights the ongoing shift towards advanced formulations that balance performance with environmental compliance.
- Water-Based:Water-based moisture curing adhesives reduce reliance on organic solvents, addressing environmental and worker safety concerns. Regulatory pressures from the US Environmental Protection Agency (EPA) drive their adoption across various industrial sectors.
- Structural:Structural adhesives provide high load-bearing capacity and impact resistance, crucial for demanding applications like automotive body-in-white. The aerospace sector specifies these high-performance systems for critical bonding where strength and durability are paramount.
- Solvent-Based:Solvent-based systems offer specific processing advantages and adhesion characteristics, though their use is declining due to VOC regulations.
- UV-Cured:UV-cured adhesives provide rapid cure times upon exposure to ultraviolet light, suitable for high-speed assembly and electronics manufacturing.
The market is increasingly favoring Water-Based technologies, while Structural adhesive innovations continue to push performance boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing capabilities contrast with China's expansive industrial base, both driving significant demand for moisture curing adhesives. These regions prioritize different performance attributes and regulatory compliance levels for specialized applications. The market dynamics reflect varied industrial development and environmental policy approaches across continents.
Germany
Demand for high-performance moisture curing adhesives in Germany stems from its robust automotive and construction sectors. The EU Green Deal and REACH framework compel manufacturers to innovate in low-VOC and solvent-free formulations. Automotive clusters in Bavaria and Baden-Württemberg increasingly specify these adhesives for lightweighting initiatives in electric vehicle production.
China
China's "dual carbon" goals and updated GB standards are accelerating the adoption of compliant moisture curing adhesives across building and automotive industries. The country's vast manufacturing hubs, particularly in the Yangtze River Delta, require high volumes of specialized formulations for export-oriented goods. Local manufacturers are rapidly shifting towards solvent-free polyurethane and silane-modified polymer systems to meet stringent environmental regulations.
United States
The United States sees strong demand for moisture curing adhesives in its construction and aerospace sectors, driven by infrastructure projects and advanced manufacturing. The US Environmental Protection Agency (EPA) regulations on VOC emissions promote the use of water-based and low-monomer systems. Manufacturing centers in the Midwest and Southeast are adopting these adhesives for prefabricated construction and structural bonding applications.
Japan
Japan's electronics and automotive industries are key consumers of moisture curing adhesives, valuing precision and long-term durability. METI guidelines encourage sustainable material development and energy efficiency in manufacturing processes. The Kanto region, including Tokyo, continues to be a hub for research and development in advanced adhesive technologies for flexible electronics and next-generation vehicles.
India
India's burgeoning construction and automotive markets are generating increasing demand for moisture curing adhesives, particularly for infrastructure development. BIS standards are evolving to align with global environmental benchmarks, influencing product formulations. Industrial corridors like those around Pune and Chennai are experiencing growth in adhesive consumption for vehicle assembly and modular building projects.
Moisture Curing Adhesives Market Key Industry Players
Top-tier vendors anchor the global moisture curing adhesives market, offering broad portfolios and extensive technical support, while mid-sized specialists focus on niche applications. The market structure is tiered, reflecting diverse customer requirements and regulatory landscapes. Strategic archetypes include diversified chemical giants and specialized adhesive formulators. Dominant competitive moves involve portfolio diversification and geographic expansion to capture emerging market opportunities.
Within the diversified chemical giant tier, Henkel AG & Co. KGaA and Sika AG exemplify companies leveraging scale in both commodity and specialty segments. 3M Company occupies a position focused on high-performance, high-margin applications, particularly in automotive and aerospace. These companies represent the industry's drive to balance cost-effectiveness with stringent performance and regulatory demands across various end-user industries.
| Leading Market Players |
|---|
| Sika AG |
| Dow, Inc. |
| Henkel AG & Co. KGaA |
| Jowat SE |
| Tosoh Corporation |
| 3M Company |
| Bostik SA |
| Dymax Corporation |
| H.B. Fuller Company |
| Others |
Cost & Logistics Intelligence
Isocyanate precursor price volatility impacts final adhesive product pricing across all tiers, from commodity construction grades to specialized automotive formulations. This volatility necessitates strategic procurement and risk management throughout the supply chain.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade polyurethane adhesives. The market primarily operates on a contract-based long-term offtake model for large industrial buyers. Price differentiation stems from performance specifications for structural bonding and specific regulatory certifications like REACH compliance for European markets. Pricing pressure stems from raw material cost fluctuations, particularly for MDI and TDI precursors. The construction sector remains highly price-sensitive, while aerospace and high-performance automotive applications prioritize performance over initial cost.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke pattern characterize the downstream logistics for moisture curing adhesives. Geographic supply concentration for key precursors such as MDI and TDI lies primarily in Germany and China, reflecting major petrochemical production hubs. The supply chain sources heavily from specialized chemical manufacturers for polyols and isocyanates. Commodity price volatility for these precursors presents a structural risk to formulators. Distribution often runs through specialized chemical distributors or direct-to-OEM channels for large industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The moisture curing adhesives market is transitioning into a late-cycle quality story, driven by the imperative for enhanced durability and environmental compliance in demanding end-use applications.
For Market Incumbents: Deploy targeted R&D investment into bio-based polyols and low-monomer isocyanate technologies. This strategy helps mitigate the threat of increasingly stringent VOC regulations and fosters competitive differentiation. Incumbents must also strengthen channel partnerships to ensure proper application training, addressing a key cause of bond failures.
For New Entrants and Emerging Players: Launch via specialized technical support and direct-to-customer engagement models. Flexible electronics and advanced battery pack assembly represent white-space targets for highly specialized silane-modified polymer formulations. The modular construction segment in Southeast Asia offers a penetrable market for sustainable, easy-to-apply systems, leveraging rapid urbanization trends.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized formulation expertise meets unmet regulatory compliance needs. The long-term viability of this market is anchored in its essential role for lightweighting in automotive and sustainable construction practices. Acquisition targets include agile mid-sized firms with proprietary low-VOC or bio-based adhesive technologies. A signal to watch is the accelerated adoption rate of solvent-free SMPs in the Chinese building and construction sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Low-VOC Formulations | Increases production of compliant adhesives to meet global regulatory demand, particularly in Europe and China. |
| Green Manufacturing Transition | Reduces carbon footprint and aligns with sustainability mandates like the EU Green Deal for competitive advantage. |
| Long-term Bio-Polyol Supply Agreements | Secures stable access to renewable feedstocks, mitigating price volatility and enhancing product sustainability. |
| Joint Ventures for Application Training | Enhances end-user proficiency and reduces bond failures, improving product reputation and market acceptance. |
| Product Launch for Flexible Electronics | Captures high-growth opportunities in specialized bonding and encapsulation for advanced electronic devices. |
Research Approach
Bottom-up automotive assembly modeling reconciled against top-down chemical precursor tracking forms the analytical core. This approach combines insights from primary interviews with R&D directors, procurement managers, regulatory affairs specialists, and field application engineers. Secondary validation draws from chemical industry reports, national environmental agency publications, trade statistics, and company annual reports, ensuring data integrity.
An input-output matrix frames the forecast across the analysis window, segmenting by product type, end user, application, and technology. The model also incorporates industry-specific dimensions like VOC compliance level and substrate compatibility. Compound annual growth rates derive from historical trends, projected shifts in end-user demand, and technological advancements. Key forecast inputs include electric vehicle production forecasts and green building certification rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant raw material supply disruptions or unforeseen regulatory shifts. These forecasts reflect assumptions regarding technological progression and market adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market