
 Sodium Methyl P-Hydroxybenzoate Market | 2026-2036
Sodium Methyl P-Hydroxybenzoate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Methyl P-Hydroxybenzoate Market Analytics
Pharmaceutical formulation demand is recalibrating the Sodium Methyl P-Hydroxybenzoate market as sterile injectable and ophthalmic applications expand. Merck KGaA leverages its European manufacturing base to supply high-purity grades for parenteral use. Ueno Fine Chemicals Industry anchors supply to Japanese and Southeast Asian pharmaceutical customers. Alta Laboratories Ltd. specializes in cost-optimized production for generic drug manufacturers across emerging markets.
Sodium Methyl P-Hydroxybenzoate is the sodium salt of methyl parahydroxybenzoate, a water-soluble antimicrobial compound with optimal activity across pH 4-8, manufactured through esterification of p-hydroxybenzoic acid followed by neutralization. It functions primarily as a preservative in aqueous formulations where microbial contamination risks threaten product stability and patient safety. The Pharmaceutical segment dominates value capture due to stringent purity requirements and regulatory documentation burdens, while the Cosmetics segment occupies a mature position facing reformulation pressure from paraben-free positioning. Powder form leads manufacturing throughput for industrial buyers, though liquid emulsions are gaining traction in automated compounding operations.
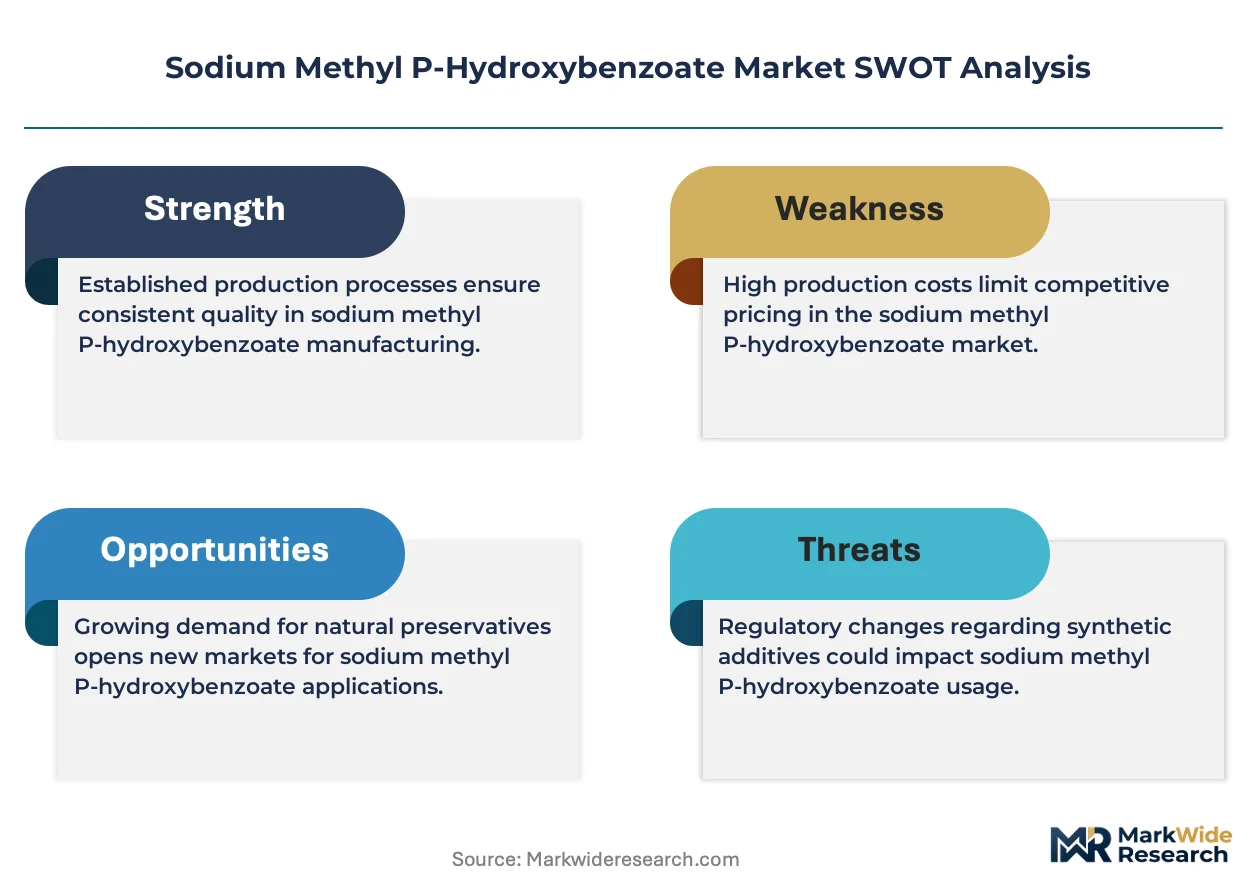
FDA oversight of paraben safety in drug and cosmetic applications shapes product liability exposure and reformulation timelines for manufacturers. EMA and REACH frameworks in Europe impose registration requirements and hazard communication obligations that filter market participants by compliance capability. BIS standards and CDSCO pharmaceutical guidelines in India create parallel certification pathways for domestic and export-oriented producers. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent acceptance thresholds for paraben-based preservatives.
Market Dynamics
REACH compliance deadlines and FDA paraben safety reviews are compressing formulation timelines for pharmaceutical manufacturers while simultaneously elevating purity specifications for preservative suppliers across multiple jurisdictions.
Growth Catalysts
- Sterile injectable expansion:Parenteral drug manufacturing in India and Southeast Asia is absorbing higher preservative volumes as domestic production scales under CDSCO oversight.
- REACH registration completion:ECHA dossier approvals for existing paraben substances are clearing regulatory uncertainty and restoring supply security for European formulators.
- Ophthalmic formulation growth:Multi-dose eye care products require water-soluble antimicrobial systems, directing procurement toward sodium salt grades over traditional esters.
Market Restraints
- p-Hydroxybenzoic acid feedstock volatility:Petrochemical-derived precursor costs fluctuate with benzene pricing, compressing margin stability for preservative manufacturers.
- Paraben-free positioning:Cosmetic brand reformulation away from paraben-based systems is eroding demand in personal care applications across North American and European markets.
- Substitution by phenoxyethanol:Alternative preservatives with broader pH tolerance are capturing share in topical pharmaceutical and cosmetic formulations.
Strategic Opportunities
- Biosimilar manufacturing in India:Domestic biologics production under PLI scheme incentives is creating new demand for high-purity excipients meeting BIS standards.
- Automated compounding systems:Liquid emulsion formats compatible with robotic filling lines are opening specification upgrades for hospital pharmacy and contract manufacturing segments.
- CDSCO export documentation:Indian manufacturers leveraging domestic regulatory compliance for WHO-prequalified supplier status are accessing African and Latin American tender markets.
Industry Challenges
- Analytical method standardization:Harmonizing impurity profiling protocols between USP, EP, and IP pharmacopeias extends batch release timelines for multinational suppliers.
- Legacy equipment retrofitting:Powder handling systems designed for organic solvents require capital modification to safely process hygroscopic sodium salt grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Methyl P-Hydroxybenzoate Market |
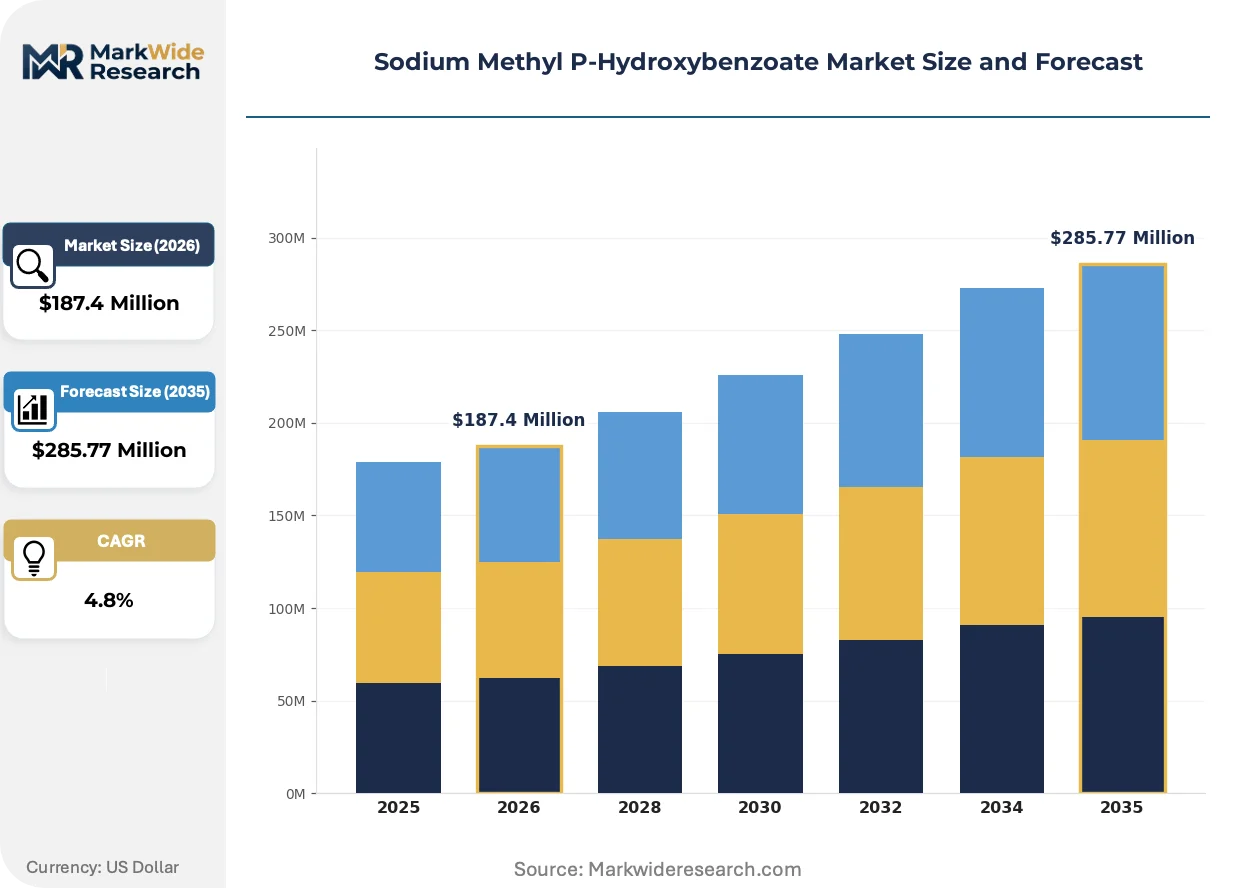
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Cosmetics, Food Preservatives, Personal Care Application: Antimicrobial Agent, Preservative, Stabilizer, Fragrance End User: Healthcare Providers, Cosmetic Manufacturers, Food Processing, Household Products Form: Powder, Granule, Liquid, Emulsion |
| Companies Covered | Merck KGaA, Ueno Fine Chemicals Industry, Alta Laboratories Ltd., Hefei TNJ Chemical Industry Co., Ltd., NBS Biological, Sharon Laboratories, Acme Hardesty, Sigma-Aldrich Co. LLC., Labeyond Chemicals Co.,Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Methyl P-Hydroxybenzoate Market Evolving Landscape
Continuous processing technologies and real-time release testing are compressing manufacturing cycles for pharmaceutical excipients while regulatory divergence between jurisdictions forces parallel qualification strategies.
Continuous manufacturing systems for paraben salt production are overtaking batch reactor operations in cost-sensitive supply chains. Indian and Chinese producers are adopting flow chemistry for esterification-neutralization sequences, cutting cycle times by half. This technology compression is enabling spot-market responsiveness that batch systems cannot match.
EMA's updated guideline on excipient risk assessment is forcing documented supply chain transparency for sodium methyl p-hydroxybenzoate used in parenteral products. European manufacturers must now submit supplier qualification dossiers with every marketing authorization application. Small-volume injectable specialists are consolidating supplier bases to reduce documentation burden.
Direct sourcing from API manufacturers is fragmenting traditional distributor channels for preservative procurement. Large generic drug producers in India and Brazil are establishing annual contracting relationships with sodium paraben manufacturers, bypassing regional chemical distributors. This channel compression is most pronounced in high-volume oral and topical formulation segments where specification standardization permits direct negotiation.
Sodium Methyl P-Hydroxybenzoate Market Segmentation
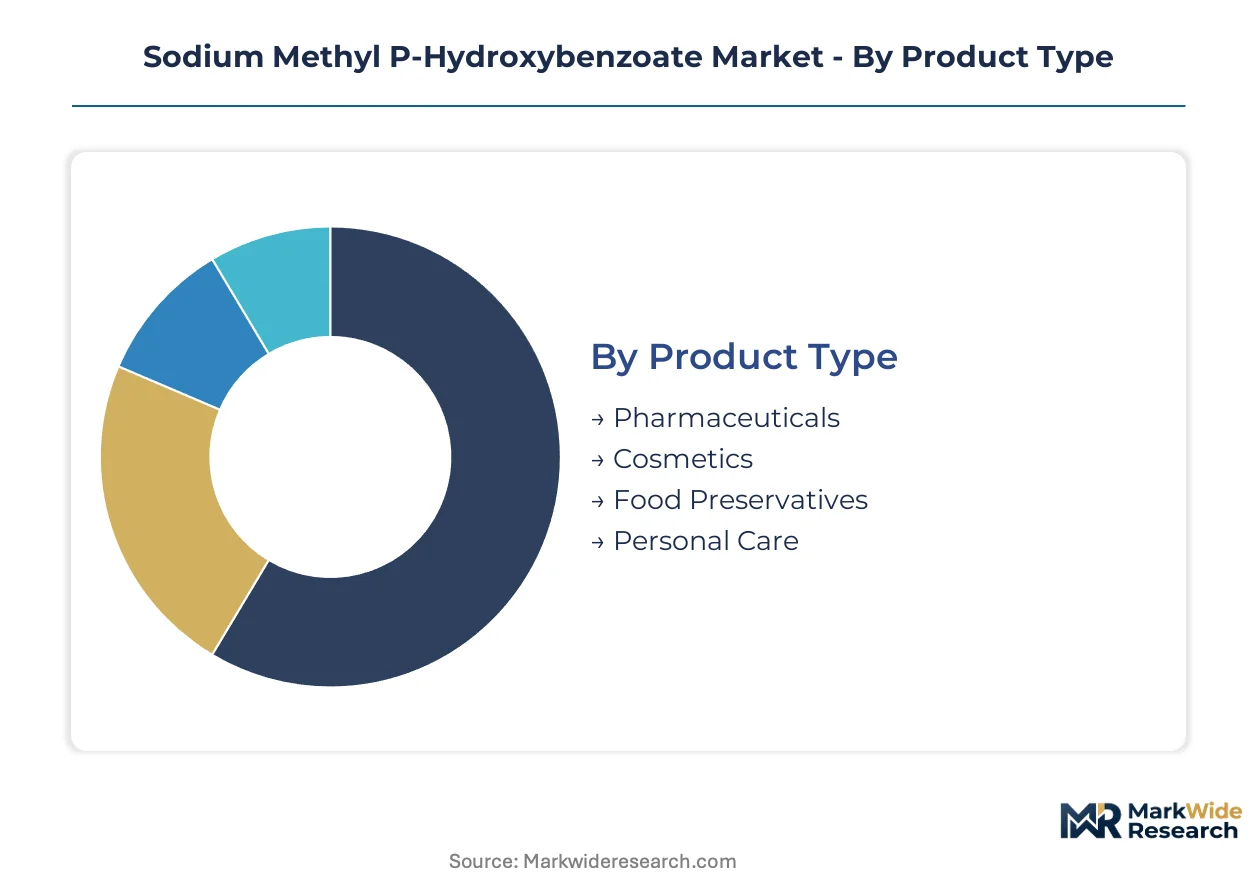
Procurement decisions for Sodium Methyl P-Hydroxybenzoate diverge sharply across end-use applications, with pharmaceutical buyers prioritizing pharmacopeial certification while cosmetic formulators weigh paraben-free positioning against cost efficiency. Form factor selection directly impacts automated compounding compatibility and moisture stability during storage.
Product Type:
Regulatory documentation burden and purity tier requirements drive buyer segmentation, with pharmaceutical-grade commanding premium positioning against commoditized food and personal care variants.
- Pharmaceuticals:USP/EP-compliant grades with documented impurity profiles support sterile injectable and ophthalmic formulations. CDSCO oversight in India and EMA risk assessment guidelines in Europe are elevating supplier qualification thresholds for parenteral applications.
- Cosmetics:Technical-grade sodium salt preserves aqueous creams and lotions across pH 4-8. Reformulation pressure from paraben-free marketing claims in North American and European retail channels is compressing volume outlook despite established efficacy.
- Food Preservatives:FSSAI-regulated grades protect processed sauces and beverages against yeast and mold contamination. Domestic sourcing mandates under India's PLI scheme for food processing are redirecting procurement toward local manufacturers.
- Personal Care:Mid-purity specifications serve shampoos, conditioners, and body washes where cost sensitivity outweighs certification requirements. Southeast Asian contract manufacturers favor this tier for export-oriented private label production.
Pharmaceuticals leads on scale; Cosmetics leads on reformulation momentum.
Application:
Functional role determines specification intensity, with antimicrobial deployment in sterile products demanding the most rigorous analytical documentation.
- Antimicrobial Agent:Direct microbiological inhibition in multi-dose parenterals and eye drops. FDA guidance on preservative effectiveness testing shapes validation protocols for sterile applications.
- Preservative:Shelf-life extension for oral solutions, syrups, and topical emulsions. REACH registration requirements in Europe filter supplier pools by toxicological dossier completeness.
- Stabilizer:pH buffering and oxidative protection in complex formulations. Biosimilar manufacturers in India under BIS standards are adopting this functionality for biologic excipient blends.
- Fragrance:Minor application masking base odor in low-fragrance personal care products. Niche demand from natural-positioning brands seeking minimal preservative systems.
Preservative captures volume concentration; Antimicrobial Agent captures value premium expansion.
End User:
Supply chain proximity and batch size flexibility segment procurement behavior, with large healthcare systems consolidating supplier relationships against fragmented cosmetic contract manufacturers.
- Healthcare Providers:Hospital pharmacy compounding and regional sterile manufacturing operations. Automated compounding system adoption in the United States is shifting preference toward liquid emulsion formats.
- Cosmetic Manufacturers:Brand-owner formulation labs and third-party contract producers. Direct sourcing from sodium paraben manufacturers in India and China is bypassing traditional distributor channels.
- Food Processing:Industrial bakeries, sauce producers, and beverage bottlers. BIS quality mandates are accelerating domestic supplier qualification for multinational food companies operating in India.
- Household Products:Surface cleaners and laundry formulations where antimicrobial claims support marketing positioning. Price-sensitive procurement favors powder form for high-volume blending operations.
Cosmetic Manufacturers lead on transaction volume; Healthcare Providers lead on specification intensity.
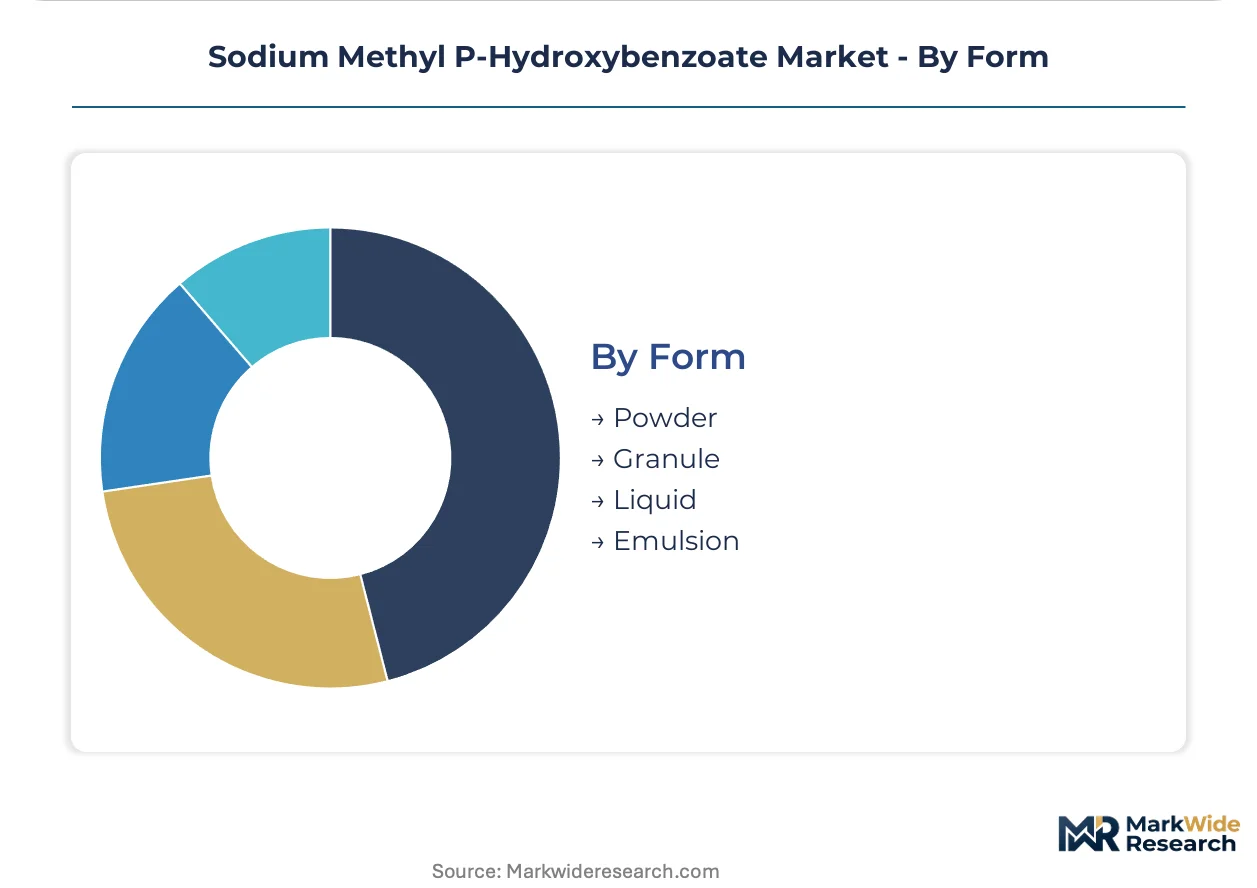
Form:
Handling characteristics and moisture sensitivity determine manufacturing compatibility, with hygroscopic sodium salt properties favoring controlled-environment processing for fine particle grades.
- Powder:Free-flowing crystalline material dominates industrial-scale procurement for dry blending operations. Legacy equipment retrofitting requirements for hygroscopic powder handling are extending qualification timelines for facility upgrades.
- Liquid:Pre-solubilized concentrate eliminates dissolution steps in automated filling lines. Robotic compounding system integration in European hospital pharmacies is expanding specification demand for this format.
- Granule:Agglomerated particles reduce dust generation during manual handling. Intermediate processing stage between powder and liquid for regional formulators with mixed equipment capabilities.
- Emulsion:Stabilized aqueous dispersion for direct incorporation without pre-mixing. Contract manufacturing organizations in India are specifying this form for WHO-prequalified export production.
Powder leads on manufacturing throughput; Liquid leads on automation compatibility expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting sodium methyl p-hydroxybenzoate production toward jurisdictions with streamlined compliance pathways, particularly as REACH dossier costs and FDA documentation burdens widen the cost-of-compliance gap between established and emerging manufacturing bases.
India
Domestic pharmaceutical manufacturing under CDSCO oversight is absorbing preservative volumes for sterile injectable and ophthalmic applications. The PLI scheme for active pharmaceutical ingredients incentivizes backward integration into excipient production. Manufacturing clusters in Hyderabad and Ahmedabad are scaling sodium paraben output to serve biosimilar contract manufacturers targeting WHO-prequalified export markets.
Germany
Merck KGaA leverages its Darmstadt manufacturing base to supply high-purity grades for European parenteral drug producers navigating EMA excipient risk assessment guidelines. REACH registration completion for existing paraben substances has restored supply security for formulators. The country's chemical industry concentration around Ludwigshafen and Frankfurt supports specialized preservative synthesis with documented impurity profiling.
United States
FDA guidance on paraben safety in drug applications is compressing reformulation timelines for sterile product manufacturers while elevating purity specifications for preservative procurement. Hospital pharmacy automation in the Northeast and Midwest is shifting preference toward liquid emulsion formats compatible with robotic compounding systems. Generic drug producers in New Jersey and North Carolina are consolidating supplier relationships to reduce documentation burden.
China
Hefei TNJ Chemical Industry and regional producers supply cost-optimized grades for personal care and household product manufacturers across Asia-Pacific. NMPA alignment with ICH quality guidelines is gradually elevating documentation standards for export-oriented pharmaceutical excipients. The Yangtze River Delta chemical corridor concentrates esterification-neutralization capacity serving both domestic and international formulation customers.
Japan
Ueno Fine Chemicals Industry anchors supply to domestic pharmaceutical customers and Southeast Asian markets requiring documented supply chain transparency. PMDA oversight of excipient quality agreements shapes procurement protocols for multi-dose parenteral products. The Osaka-Kobe industrial zone maintains specialized capacity for high-purity sodium paraben grades with pharmacopeial certification.
Sodium Methyl P-Hydroxybenzoate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade procurement consolidating around documented suppliers while personal care applications fragment across cost-optimized regional producers. The market exhibits a three-tier structure: multinational chemical conglomerates with integrated excipient portfolios, mid-scale specialists focused on paraben salt manufacturing, and commodity producers serving price-sensitive industrial applications. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into alternative preservative systems to hedge against paraben-free formulation trends.
Within the multinational tier, Merck KGaA and Sigma-Aldrich Co. LLC. represent the integrated chemical conglomerate archetype with broad excipient portfolios and established pharmacopeial documentation capabilities. Ueno Fine Chemicals Industry and Alta Laboratories Ltd. exemplify the regional specialist model, with the former anchoring Japanese and Southeast Asian supply and the latter occupying a position in cost-optimized production for emerging market generic manufacturers. Among China-based producers, Hefei TNJ Chemical Industry sits within the commodity-scale segment serving high-volume personal care and industrial applications.
| Leading Market Players |
|---|
| Merck KGaA |
| Ueno Fine Chemicals Industry |
| Alta Laboratories Ltd. |
| Hefei TNJ Chemical Industry Co., Ltd. |
| NBS Biological |
| Sharon Laboratories |
| Acme Hardesty |
| Sigma-Aldrich Co. LLC. |
| Labeyond Chemicals Co.,Ltd |
| Others |
Value Network & Pricing Analysis
Pharmaceutical procurement consolidation around documented suppliers for parenteral-grade sodium methyl p-hydroxybenzoate is compressing channel margins and forcing supply base rationalization. CDSCO-mandated impurity profiling and EMA excipient risk assessment dossiers elevate qualification costs that filter through to pricing premiums for compliant tiers.
Pricing Analysis
Distributor margins for pharmaceutical-grade sodium methyl p-hydroxybenzoate have compressed as generic drug manufacturers in India and Brazil establish direct annual contracts with manufacturers. Three-tier pricing structure across USP/EP-certified premium grades, technical-grade standard tiers, and economy personal care variants reflects certification burden and volume scale. Cost compression in technical-grade segments intensifies because phenoxyethanol substitution erodes paraben demand in cosmetics. Cosmetic contract manufacturers in Southeast Asia exhibit highest price sensitivity; sterile injectable specialists in Europe show lowest sensitivity due to regulatory lock-in.
Supply Chain Analysis
Dual-sourcing requirements from European pharmaceutical formulators mandate qualified backup suppliers for sodium methyl p-hydroxybenzoate, extending supplier qualification timelines. Manufacturing concentrates in India, China, and Germany, with Hyderabad-Ahmedabad clusters, Yangtze River Delta corridor, and Ludwigshafen-Frankfurt chemical belt anchoring output. Feedstock p-hydroxybenzoic acid draws from petrochemical benzene chains, with esterification-neutralization equipment and pharmacopeial reference standards as critical inputs. Single-source vulnerability runs through concentrated Indian supply for WHO-prequalified export grades. Distribution runs through direct manufacturer relationships for pharmaceutical volumes and regional chemical distributors for personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium methyl p-hydroxybenzoate procurement is shifting toward premium-certified tiers as regulatory documentation burdens concentrate demand among qualified suppliers, expanding margin capture for compliant manufacturers.
For Market Incumbents: Cement supplier qualification dossiers for EMA and CDSCO pathways to defend against phenoxyethanol substitution in ophthalmic applications. Deepen backward integration into p-hydroxybenzoic acid production to buffer benzene feedstock volatility. Capacity addition in Hyderabad-Ahmedabad clusters captures biosimilar manufacturing growth under PLI scheme incentives. For New Entrants and Emerging Players: Contract manufacturing organizations in India represent the most penetrable channel partner type for liquid emulsion format entry. Target automated compounding system suppliers in European hospital pharmacies as specification influencers. White-space exists in WHO-prequalified export documentation services for African and Latin American tender markets. Go-to-market through direct technical sales to generic drug producers bypassing distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Indian specialists possessing CDSCO compliance and BIS certification infrastructure. Long-term viability hinges on paraben preservation in sterile injectable applications where regulatory switching costs protect incumbent positions. Acquisition target archetype: Indian manufacturers with established impurity profiling capabilities and export documentation expertise. Signal to watch is FDA guidance revision on paraben safety thresholds in parenteral products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive p-hydroxybenzoic acid supply insulates margin from benzene price volatility. |
| CDSCO Export Documentation Investment | WHO-prequalified supplier status unlocks African and Latin American tender markets. |
| Liquid Emulsion Format Scale-Up | Robotic compounding compatibility captures European hospital pharmacy automation demand. |
| Continuous Manufacturing Adoption | Flow chemistry cuts cycle times and enables spot-market responsiveness against batch competitors. |
| Alternative Preservative R&D | Hedging portfolio diversification addresses paraben-free positioning pressure in cosmetics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical procurement managers, regulatory affairs leads at excipient manufacturers, CDSCO compliance officers, and hospital pharmacy automation specialists with secondary validation. Sources included customs trade data, FDA guidance documents, EMA excipient risk assessment guidelines, CDSCO pharmaceutical notifications, and SEC filings from listed chemical producers. Bottom-up volume modeling across grade tiers and end-use applications triangulated against top-down market sizing from production capacity analysis.
Historical reference periods anchored demand modeling to pre-pandemic baselines and post-REACH registration recovery phases across the projection horizon. Segmentation dimensions modeled included pharmaceutical grade tier, end-use industry, powder versus liquid format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to volume trajectories, with inputs from sterile injectable production forecasts and ophthalmic formulation pipeline data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA paraben safety guidance revisions and phenoxyethanol substitution rates in topical pharmaceuticals. Deviation in REACH dossier approval timelines or benzene feedstock price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Global 1-Hexanol Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Hydrogen Cyanide Market
High-Value Chemicals
High Purity Silica Market