
 Anti-Corrosion Tape Market | 2026-2036
Anti-Corrosion Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Corrosion Tape Market Analysis
Gulf Coast petrochemical capacity expansion is reshaping regional supply-demand balances for anti-corrosion tape manufacturers. 3M Company leverages its materials science portfolio to dominate high-performance pipeline segments with proprietary adhesive platforms. Nitto Denko Corporation anchors Asian supply chains through integrated polymer film production and regional distribution hubs. Berry Global Inc. competes on manufacturing scale, operating multi-plant converting capacity that sustains cost leadership in commodity-grade polyethylene tapes.
Anti-corrosion tape comprises polymer-backed adhesive systems engineered to isolate metallic substrates from moisture, oxygen, and electrolytic contact, typically specified with dielectric strength exceeding 10 kV/mm and elongation properties accommodating thermal pipe movement. Self-adhesive tapes occupy the largest volume share due to simplified field application, while wraparound tapes command premium positioning in subsea and directional drilling environments where mechanical damage resistance proves critical. Polyethylene-based formulations lead material demand given chemical inertness and UV stability, though rubber-modified asphalt tapes retain entrenched positions in buried pipeline cathodic protection overlap zones.
PHMSA regulations in the United States mandate documented external corrosion control programs for interstate hazardous liquid and natural gas transmission lines, directly specifying tape coating performance criteria. The EU REACH framework and associated SVHC restrictions constrain adhesive chemistry options available to manufacturers serving European infrastructure operators. ISO 21809 and NACE SP0169 standards establish international benchmark protocols for tape application thickness, surface preparation, and holiday detection testing. Stakeholders must monitor evolving biobased polymer certifications and carbon border adjustment mechanisms that could restructure raw material sourcing economics and regional manufacturing investment decisions.
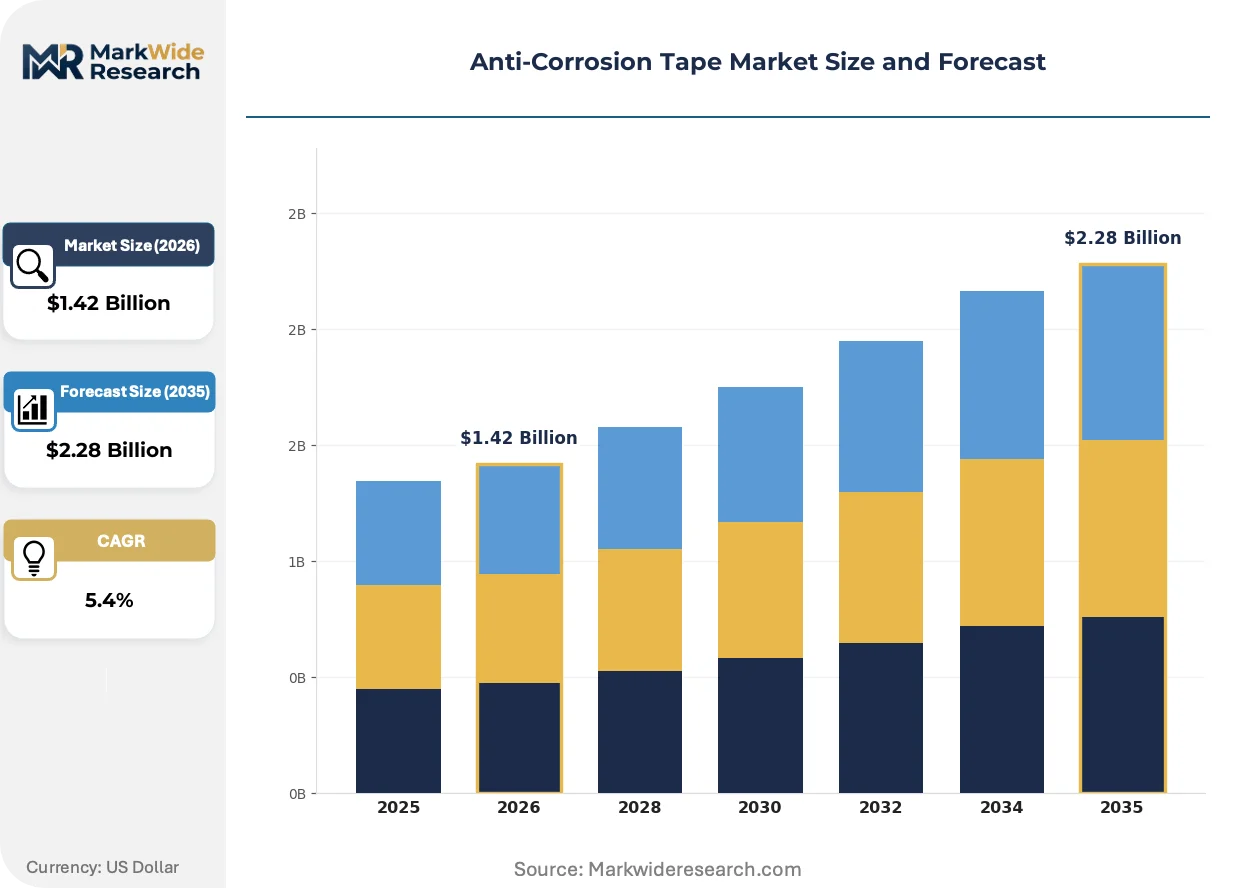
Market Dynamics
Pipeline infrastructure investment cycles and evolving PHMSA corrosion control mandates are restructuring procurement patterns for anti-corrosion tape, compressing specification timelines while elevating performance thresholds for subsea and high-temperature applications.
Growth Catalysts
- Subsea Pipeline Construction:Deepwater oil and gas developments in the US Gulf Coast and Brazil's pre-salt basins drive specialized tape demand for cathodic protection systems operating under extreme hydrostatic pressure.
- PHMSA Regulatory Intensification:The US Pipeline and Hazardous Materials Safety Administration's 2024 external corrosion control rulemaking mandates documented coating performance testing, forcing replacement cycles for aging tape inventories.
- Polyethylene Formulation Advances:Cross-linked polyethylene backing technologies improve dielectric strength and thermal cycling resistance, opening specification opportunities in refinery process piping and LNG export terminals.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings directly compress polyethylene tape margins, particularly for commodity-grade wraparound products with limited pricing power.
- Adhesive Chemistry Constraints:EU REACH SVHC restrictions on solvent-based adhesive systems force European manufacturers toward waterborne alternatives with inferior cold-temperature tack properties.
- Thermal Spray Metalizing Substitution:Aluminum and zinc thermal spray coatings capture share in above-ground pipeline segments where mechanical damage risk is lower and inspection accessibility is higher.
Strategic Opportunities
- Carbon Capture Infrastructure:CO2 transmission pipeline networks under development in the US Midwest and Texas require corrosion protection systems compatible with supercritical CO2 chemistries and acid gas environments.
- Biobased Polymer Certification:ASTM D6866 and similar biogenic carbon standards create premium positioning for tape manufacturers sourcing bio-polyethylene from sugarcane or agricultural waste feedstocks.
- Offshore Wind Export Cables:Subsea power cable protection for offshore wind farms in the North Sea and US Atlantic Coast represents an emerging specification channel with dielectric performance requirements overlapping pipeline tapes.
Industry Challenges
- Applicator Certification Bottlenecks:NACE SP0169 and ISO 21809 application standards require trained field technicians, creating workforce scarcity that delays project commissioning in remote construction sites.
- Multi-Standard Compliance Complexity:Tape manufacturers serving both US PHMSA-regulated interstate pipelines and EU infrastructure operators must maintain parallel testing protocols and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Corrosion Tape Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Tapes, Wraparound Tapes, Liquid Coatings, Others End User: Marine, Construction, Oil & Gas, Automotive Material: Polyethylene, PVC, Rubber, Asphalt Application: Pipelines, Tanks, Metal Structures, Electrical Components |
| Companies Covered | 3M Company, Nitto Denko Corporation, Shurtape Technologies, Scapa Group plc, Berry Global Inc., Polyken, Denso, Jining Xunda Pipe Coating Materials, PSI Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Corrosion Tape Market Emerging Trajectories
Material science convergence and regulatory chemistry constraints are forcing anti-corrosion tape developers toward hybrid formulations and application automation, compressing traditional specification cycles while expanding performance envelopes for extreme environments.
Multi-layer tape architectures are hybridizing polymer backing, rubber-modified asphalt, and viscoelastic adhesive layers into unified systems that combine mechanical protection with active corrosion inhibition. Offshore pipeline contractors in the North Sea and Gulf of Mexico specify these hybrid constructions for subsea tie-ins where single-layer products fail under thermal expansion cycling. The technology is hybridizing procurement categories previously segmented by backing chemistry, forcing manufacturers to develop integrated formulation capabilities rather than discrete product lines.
REACH SVHC candidate list expansions are systematically eliminating aromatic solvent options from adhesive formulations, compelling European tape producers to reformulate around bio-based tackifiers and UV-curable chemistries. Industrial consequence includes extended curing times and modified storage temperature requirements that disrupt established logistics patterns. Marine and subsea segments are responding fastest, as offshore operators face simultaneous pressure from EU environmental directives and North Sea decommissioning liability frameworks.
Specification authority is migrating from distributor sales networks toward engineering-procurement-construction firms with centralized materials qualification databases. Middle East pipeline developers and US utility operators now require pre-approved manufacturer lists with locked formulation specifications, displacing spot purchasing through regional distributors. This concentration is most visible in Saudi Aramco's long-term supply agreements and similar national oil company procurement frameworks across the Middle East and Central Asia.
Anti-Corrosion Tape Market Segmentation
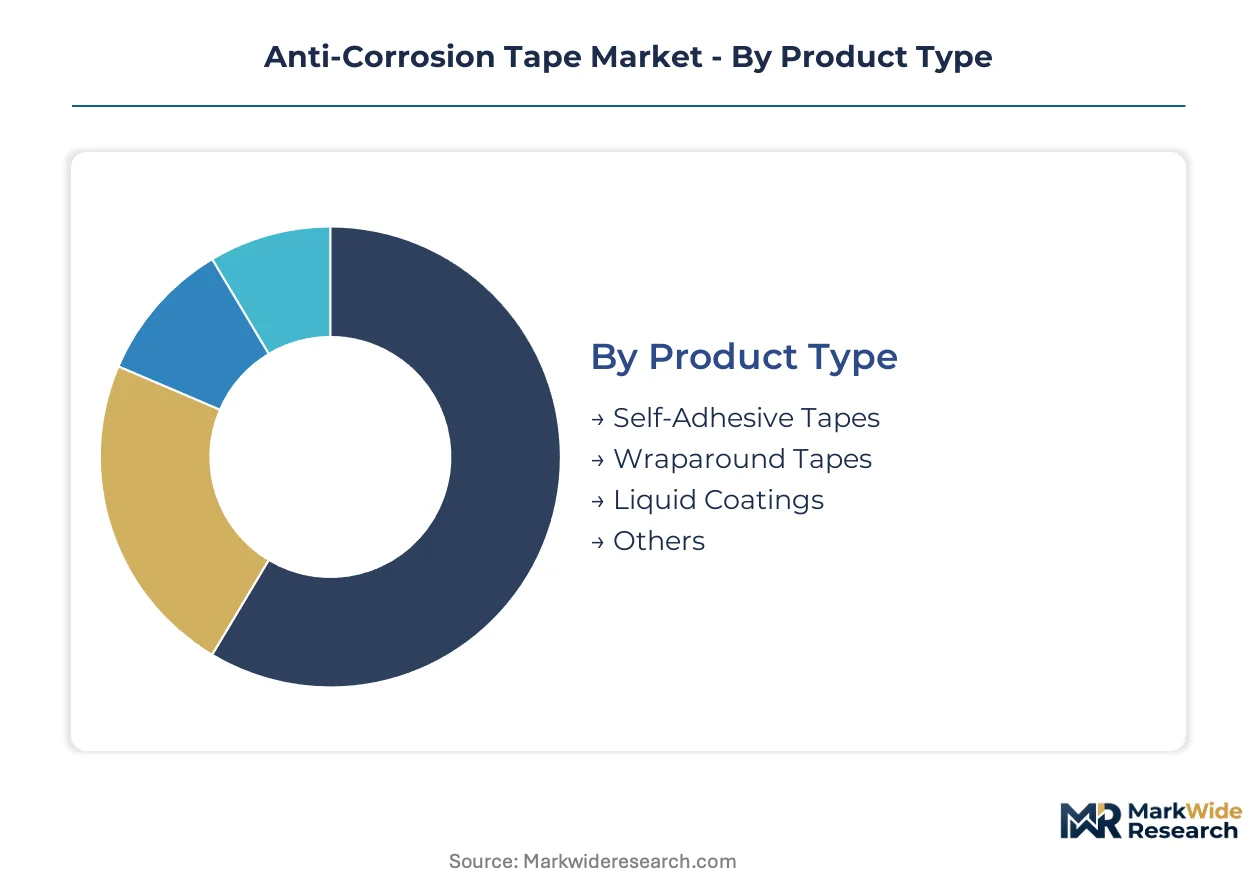
Segmentation in anti-corrosion tape markets reveals how procurement cycles, specification authority, and material science investments concentrate across distinct technical and commercial boundaries. Understanding these divides exposes where margin pools form and which segments drive replacement demand versus new installation volume.
Product Type:
Replacement cycles vary dramatically by product format, with field-applied systems turning over faster than factory-integrated coatings due to accessibility for inspection and repair.
- Self-Adhesive Tapes:These single-layer polymer-backed systems integrate pressure-sensitive adhesives that bond directly to prepared steel surfaces without additional curing equipment. Demand clusters around US Gulf Coast refinery maintenance turnarounds and European gas distribution network upgrades where speed of application outweighs premium performance requirements. PHMSA-mandated re-coating intervals for above-ground interstate pipelines sustain steady replacement volume.
- Wraparound Tapes:Multi-layer laminated constructions combine polyethylene backing with rubber-modified asphalt or viscoelastic adhesives, engineered for mechanical damage resistance in directional drilling and subsea tie-in applications. Brazil's pre-salt basin developments and North Sea decommissioning projects specify these systems for cathodic protection overlap zones where soil stress and hydrostatic pressure exceed single-layer capabilities. Specification timelines run longer due to engineering-procurement-construction firm qualification requirements.
- Liquid Coatings:Solvent-borne and waterborne epoxy or polyurethane systems applied by spray or brush methods, serving niche repair scenarios and complex geometries where tape conformability limits coverage.
- Others:Heat-shrink sleeves, fusion-bonded epoxy tapes, and specialty formulations for extreme temperature or chemical exposure environments.
Self-adhesive tapes dominate installed base across terrestrial pipeline networks. Wraparound tapes are where expansion concentrates as subsea and horizontal directional drilling applications multiply.
End User:
Customer sophistication and specification authority vary sharply across end-use sectors, with national oil companies and regulated utilities imposing stricter qualification protocols than commercial construction contractors.
- Oil & Gas:Pipeline operators and petrochemical producers specify tape systems for transmission lines, gathering systems, and refinery process piping. Saudi Aramco's long-term supply agreements and similar national oil company frameworks concentrate procurement authority among pre-approved manufacturer lists, locking formulation specifications and displacing spot purchasing through regional distributors.
- Marine:Shipbuilders, offshore platform operators, and port infrastructure developers apply anti-corrosion tapes for hull protection, deck equipment, and subsea riser splash zones. EU REACH SVHC restrictions on solvent-based adhesives force faster reformulation cycles in European shipyards than in Middle Eastern or Asian construction centers.
- Construction:Commercial and industrial building contractors specify tapes for structural steel, HVAC ductwork, and architectural metalwork where aesthetic finish and UV stability compete with corrosion protection performance.
- Automotive:OEM underbody coatings and aftermarket repair applications, representing a smaller volume channel with distinct automotive-grade adhesive and temperature resistance requirements.
Oil and gas commands specification authority through centralized engineering-procurement-construction qualification databases. Marine is climbing the fastest as offshore wind export cable protection and North Sea decommissioning create new dielectric performance requirements overlapping traditional pipeline applications.
Material:
Raw material sourcing economics and polymer conversion capabilities determine regional manufacturing footprints and margin structures across material categories.
- Polyethylene:Cross-linked and linear low-density polyethylene backings provide chemical inertness, UV stability, and dielectric strength exceeding 10 kV/mm. US Gulf Coast petrochemical corridor proximity to ethylene feedstock supplies anchors manufacturing concentration for export to Latin American and Middle Eastern pipeline projects.
- Rubber:Butyl and EPDM rubber formulations deliver conformability and moisture resistance for irregular substrates and cathodic protection overlap applications. Cold-temperature tack properties sustain demand in Canadian and Alaskan pipeline construction despite higher material costs versus polyethylene alternatives.
- PVC:Lower-cost backing option with limited thermal cycling performance, serving above-ground electrical conduit and architectural metalwork applications where mechanical damage risk is minimal.
- Asphalt:Rubber-modified bituminous compounds retain entrenched positions in buried pipeline cathodic protection systems, particularly in legacy infrastructure where compatibility with existing coating systems governs material selection.
Polyethylene dominates volume given feedstock integration advantages and specification breadth. Rubber is gaining share fastest in extreme climate and subsea environments where conformability and thermal cycling resistance justify premium positioning.
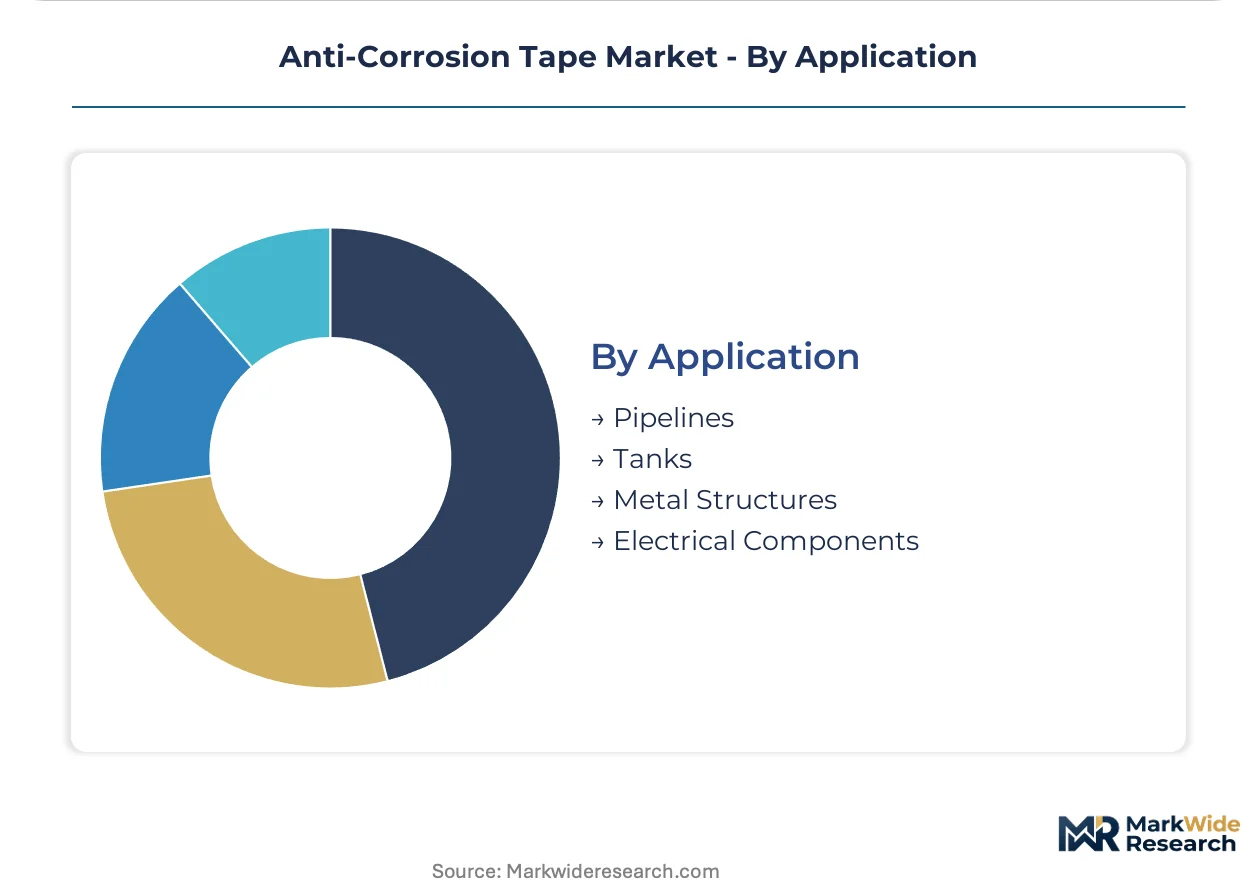
Application:
Asset accessibility and inspection regimes create divergent performance requirements and replacement economics across application categories.
- Pipelines:Transmission, distribution, and gathering line coatings represent the core demand channel, with PHMSA-regulated interstate systems requiring documented external corrosion control programs and holiday detection testing. Buried, above-ground, and subsea installation environments each demand tailored backing thickness and adhesive formulations.
- Tanks:Above-ground storage tank floors and roof seals require tape systems compatible with aggressive bottom water chemistries and thermal expansion from product cycling. API 653 inspection intervals drive replacement demand in US petroleum storage terminals.
- Metal Structures:Bridges, towers, and industrial frameworks specify tapes for bolted connection protection and weld overlay zones where spray coatings prove impractical.
- Electrical Components:Substations, switchgear, and cable termination protection applications emphasize dielectric performance and tracking resistance alongside corrosion isolation.
Pipelines anchor revenue concentration through infrastructure scale and regulatory compliance mandates. Tanks represent the steepest expansion trajectory as US Midwest CO2 storage hub development and LNG export terminal construction create new specification channels for cryogenic and acid gas environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PHMSA corrosion control mandates in the United States anchor regulatory intensity for anti-corrosion tape specifications. Pipeline construction cycles and petrochemical infrastructure investments concentrate demand across five national markets.
United States
Gulf Coast refinery expansions and LNG export terminal construction drive polyethylene tape procurement for process piping and cryogenic service. PHMSA's 2024 external corrosion control rulemaking mandates documented coating performance testing for interstate hazardous liquid lines. Houston anchors manufacturing concentration with multi-plant converting capacity serving Latin American export markets.
Brazil
Pre-salt basin deepwater developments specify wraparound tape systems for cathodic protection under extreme hydrostatic pressure. ANVISA and environmental licensing frameworks govern offshore construction materials qualification. Rio de Janeiro hosts engineering-procurement-construction firm headquarters that centralize procurement authority for subsea tie-in projects.
Germany
Industrial pipeline maintenance and chemical plant turnarounds sustain replacement demand for self-adhesive systems. ECHA REACH SVHC restrictions eliminate aromatic solvent options from adhesive formulations, forcing waterborne chemistry transitions. The Ruhr industrial corridor concentrates tape distribution networks serving Central European infrastructure operators.
China
West-to-East natural gas transmission pipeline networks and refinery capacity expansions absorb bulk volumes of commodity-grade polyethylene wraps. GB standards and MIIT industrial policy guide domestic procurement specifications for buried infrastructure. Shandong Province anchors polymer film production with integrated ethylene feedstock access.
Saudi Arabia
Saudi Aramco long-term supply agreements concentrate procurement authority among pre-approved manufacturer lists for oilfield gathering systems and export pipelines. The country's national oil company mandates locked formulation specifications that displace spot purchasing through regional distributors. The Eastern Province hosts petrochemical complexes with captive tape demand for process equipment protection.
Anti-Corrosion Tape Market Vendor Landscape
Capability concentration sits with materials science specialists; scale advantage sits with multi-plant converters. The market structures around three tiers: integrated polymer producers with captive film extrusion, regional converters sourcing commodity backings, and application-specific specialists serving subsea or extreme temperature niches. Dominant competitive moves include backward integration into adhesive formulation and geographic expansion through distribution partnerships in Middle Eastern and Latin American pipeline markets.
Within the integrated materials tier, 3M Company and Nitto Denko Corporation exemplify capability concentration through proprietary polymer science platforms. Berry Global Inc. occupies a position at the scale-driven end with multi-plant converting capacity. Shurtape Technologies and Scapa Group plc represent regional specialists with focused distribution networks. Denso and Polyken anchor positions in rubber-modified asphalt formulations for buried pipeline cathodic protection overlap zones. Jining Xunda Pipe Coating Materials exemplifies China-based fabrication serving domestic infrastructure buildout.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| Shurtape Technologies |
| Scapa Group plc |
| Berry Global Inc. |
| Polyken |
| Denso |
| Jining Xunda Pipe Coating Materials |
| PSI Products |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility compresses polyethylene tape margins unevenly across geographies, forcing three-tier pricing structure across premium, standard, and economy levels while reshaping where manufacturers anchor extrusion capacity versus converting operations.
Pricing Analysis
US Gulf Coast pricing runs 15-20% below European equivalents due to integrated ethylene feedstock access, while Asian spot markets trade at deeper discounts for commodity-grade wraps. Price differentiation hinges on PHMSA certification tier and volume scale, with national oil company long-term offtakes commanding locked-formulation premiums. Cost compression in standard-grade polyethylene tapes is intensifying because of propylene derivative volatility. Commercial construction contractors exhibit highest price sensitivity; subsea engineering-procurement-construction firms show lowest.
Supply Chain Analysis
Export control regimes on advanced polymer extrusion equipment limit technology transfer to certain geographies, constraining supply expansion in emerging pipeline markets. Manufacturing concentrates in the United States, China, and Germany. Supply chains draw from ethylene, butyl rubber, and specialty adhesive tackifier inputs. Single-source vulnerability sits with German-engineered extrusion line suppliers. Distribution runs through engineering-procurement-construction firm pre-approved manufacturer lists rather than spot distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-corrosion tape markets sit in early-cycle expansion as carbon capture infrastructure and offshore wind export cable protection create specification channels with limited incumbent penetration.
For Market Incumbents: Pre-empt thermal spray metalizing substitution by embedding tape systems into integrated cathodic protection packages with guaranteed performance warranties. Lock Saudi Aramco-style long-term supply agreements before specification authority migrates further toward centralized EPC databases. Prioritize backward integration into cross-linked polyethylene extrusion to defend margin position against resin price swings. For New Entrants and Emerging Players: Build out biobased polymer certification capabilities targeting EU REACH-compliant segments where incumbents face reformulation lag. Offshore wind export cable protection in the North Sea and US Atlantic Coast offers penetrable white space with overlapping dielectric requirements. Pursue direct qualification with national oil company procurement frameworks rather than distributor channel stacking. For Investors and Strategic Acquirers: Regional converters with captive adhesive formulation laboratories and locked EPC pre-approval status offer the strongest acquisition profile for mid-cycle consolidation. Long-term viability rests on exposure to subsea and carbon capture infrastructure buildouts rather than terrestrial pipeline replacement cycles. Watch for biobased certification mandates in EU infrastructure procurement as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captive ethylene feedstock access insulates margin compression at US Gulf Coast manufacturing hubs. |
| Biobased Polymer Certification Program | ASTM D6866 compliance unlocks premium positioning in EU REACH-regulated procurement channels. |
| Long-term Supply Agreement with NOCs | Saudi Aramco-style frameworks lock formulation specifications and displace spot distributor purchasing. |
| Subsea Application R&D Expansion | Hybrid multi-layer architectures address thermal cycling failure modes in North Sea tie-in projects. |
| EPC Pre-approval Database Qualification | Centralized materials qualification displaces regional distributor influence in Middle East pipeline markets. |
Methodological Framework
A standing panel of pipeline corrosion engineers, EPC procurement leads, petrochemical plant managers, and adhesive R&D directors provided ongoing calibration across the research window. Primary interviews combined with secondary validation from PHMSA incident databases, API standards documentation, customs trade data, and SEC filings from listed tape manufacturers. Bottom-up unit economics triangulated against top-down infrastructure investment forecasts.
Scenario-bracketing framed low, base, and high cases across the projection horizon without fixed-year anchors. Segmentation dimensions modeled include product format, material chemistry, application environment, and end-user procurement authority tier. CAGRs derived from pipeline mileage addition forecasts, refinery turnaround schedules, and regulatory re-coating interval mandates. Cross-linked polyethylene adoption curves and biobased feedstock cost parity timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed polymer producers would shift outcomes through capacity dumping in Southeast Asian export markets. Material shifts in EU carbon border adjustment mechanisms or PHMSA external corrosion control rulemaking stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Europe Reactive Adhesives Market