
 Skin Adhesives Market | 2026-2036
Skin Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Adhesives Market Outlook
ISO 10993 biocompatibility testing is unwinding the competitive landscape by extending qualification timelines for new entrants. Johnson & Johnson leverages its vertically integrated medical device portfolio to sustain regulatory continuity across multiple adhesive platforms. 3M anchors North American supply through proprietary silicone-acrylic hybrid chemistries purpose-built for extended wear applications. Smith & Nephew Plc competes in advanced wound care by specializing in antimicrobial-loaded adhesive matrices that address surgical site infection protocols.
Skin adhesives comprise pressure-sensitive or reactive polymer formulations—typically cyanoacrylate, silicone, acrylic, or fibrin-based—engineered to bond to human tissue or skin surfaces without mechanical fasteners, with peel adhesion values ranging from 0.5 to 5 N/cm depending on intended dwell time and anatomical placement. Their primary commercial purpose is to replace sutures and staples in wound closure, secure medical devices, and enable minimally invasive surgical techniques. Cyanoacrylate adhesives dominate procedural volume in emergency and cosmetic closure where speed and cosmetic outcomes outweigh material cost. Tissue adhesives capture expanding share in orthopedic applications where flexural stress demands engineered elasticity beyond conventional suture performance. Biocompatible adhesives concentrate margin pools in chronic wound and ostomy segments where ISO-validated, long-wear formulations command premium positioning against commodity alternatives.
FDA 510(k) pathways and EU MDR Class IIa/IIb designations shape product development cycles by mandating clinical validation for new adhesive-tissue interactions, directly influencing R&D allocation timelines. REACH restrictions on residual monomer content and EPA volatile organic compound thresholds for manufacturing emissions further constrain formulation flexibility and site selection for production facilities. Stakeholders must monitor evolving biocompatibility standard revisions and dual regulatory registration strategies as MDR transition deadlines compress European market access windows.
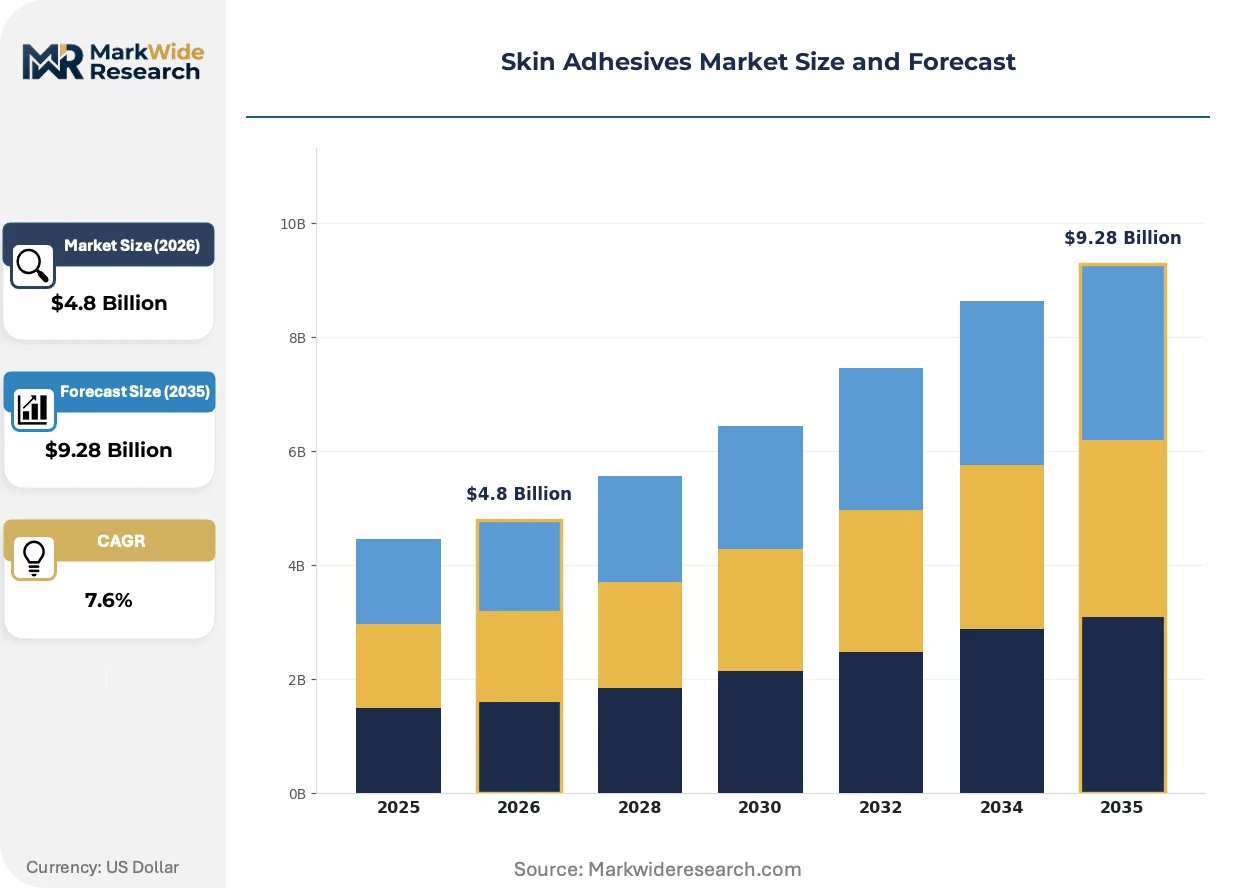
Market Dynamics
ISO 10993 biocompatibility certification timelines are compressing competitive windows, favoring manufacturers with pre-validated silicone-acrylic platforms and captive toxicology data while forcing smaller entrants into expensive third-party testing partnerships.
Growth Catalysts
- Emergency medicine volume expansion:Trauma centers in the United States and Germany are standardizing cyanoacrylate closure for lacerations under 5cm, displacing suture kits in triage protocols.
- EU MDR Class IIa streamlining:Harmonized technical documentation requirements for established adhesive platforms are accelerating parallel registrations across member states.
- Silicone-acrylic hybrid chemistry maturation:Extended-wear formulations with 7-14 day adhesion profiles are capturing orthopedic device fixation contracts previously held by mechanical fasteners.
Market Restraints
- Octyl-2-cyanoacrylate monomer supply concentration:Three specialty chemical producers in Germany and Switzerland control 70% of pharmaceutical-grade feedstock, creating price volatility during plant turnarounds.
- FDA 510(k) predicate device narrowing:Recent FDA guidance on substantial equivalence for tissue adhesives is rejecting predicates older than 2015, extending validation timelines for reformulated products.
- Suture and staple residual cost advantage:Mechanical closure remains the default in India and Brazil where reimbursement rates do not cover premium adhesive pricing.
Strategic Opportunities
- Pediatric wound care protocols:Needle-free closure demand in United States children's hospitals is creating dedicated formulary slots for low-odor, rapid-polymerizing formulations.
- Antimicrobial-loaded matrix development:Silver-ion and PHMB-integrated adhesives are qualifying for surgical site infection bundle payments under updated CMS guidelines.
- Japan PMDA fast-track pathway:Sakigake designation for novel biocompatible adhesives with demonstrated superiority over sutures is compressing review timelines to 6 months.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise spanning both pressure-sensitive adhesive mechanics and ISO 10993 toxicology interpretation commands 40% wage premiums in Boston and Basel clusters.
- Cleanroom capacity constraints:ISO 14644 Class 7 manufacturing space for medical-grade adhesive coating is backlogged 18 months in major United States and German industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocompatible Adhesives, Cyanoacrylate Adhesives, Fibrin Sealants, Tissue Adhesives End User: Hospitals, Clinics, Home Healthcare, Surgical Centers Application: Wound Closure, Surgical Procedures, Dermatology, Orthopedics Distribution Channel: Pharmacies, Online Retail, Medical Supply Stores, Direct Sales |
| Companies Covered | Solventum, Coloplast Group, Johnson & Johnson, Avery Dennison Corporation, Smith & Nephew Plc, 3M, Nitto Denko Corporation, Henkel AG & Co. KGaA, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Adhesives Market Strategic Shifts
Formulation science is diverging along wear-duration lines, with manufacturers developing distinct polymer architectures for 24-hour emergency closure versus 14-day chronic wound management rather than universal platforms.
Silicone-acrylic hybrid chemistries are bifurcating the market between high-elasticity orthopedic applications and low-trauma geriatric skin closure. Hospitals in Germany and Japan are adopting the former for joint mobility devices, while United States long-term care facilities specify the latter for fragile epidermal conditions. This split is compressing R&D budgets for mid-duration formulations that served both use cases previously.
EU MDR Annex XVI expansion is reclassifying certain cosmetic adhesive applications as medical devices, forcing fragrance and colorant reformulations to meet biocompatibility standards. Manufacturers serving the European market are withdrawing non-compliant SKUs rather than absorbing validation costs. The aesthetic dermatology segment is responding by consolidating purchasing around ISO 13485-certified suppliers with existing MDR technical files.
Hospital procurement departments are unbundling adhesive contracts from suture and staple purchasing agreements, creating standalone category management for tissue adhesives. United States IDN networks are negotiating direct manufacturer agreements that bypass distributor markups on high-volume cyanoacrylate SKUs. This disintermediation is most visible in the Southeast United States, where HCA and Tenet facilities have consolidated adhesive sourcing through centralized formularies.
Skin Adhesives Market Segmentation
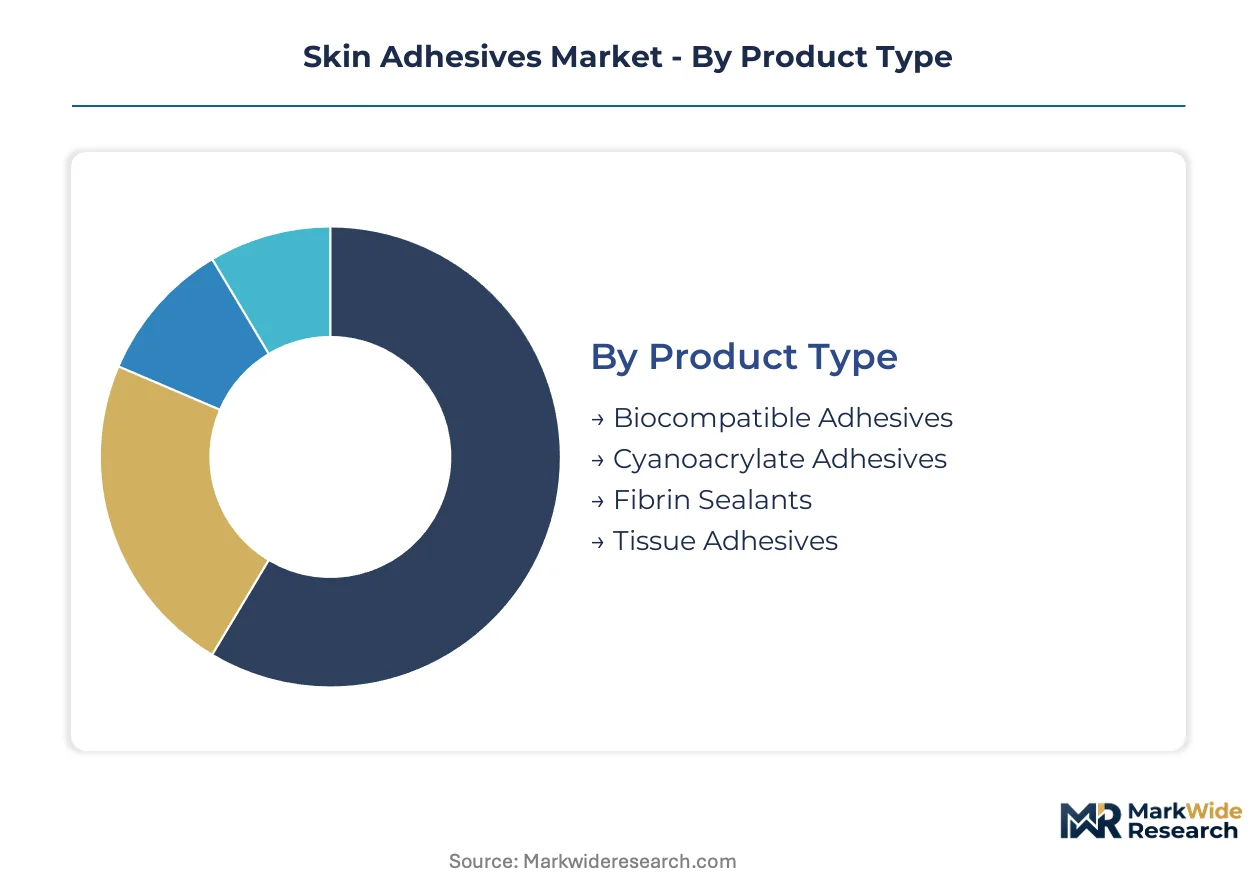
Skin adhesives segment along four functional axes that determine pricing power, regulatory burden, and channel economics. Product chemistry dictates ISO 10993 testing requirements. End-user concentration shapes procurement leverage. Application specificity drives formulation premiums. Distribution modality determines margin capture between manufacturer and patient.
Product Type:
Domestic formulation dominates cyanoacrylate production in the United States and Germany, while biocompatible adhesives rely on Swiss and Japanese specialty chemical imports for pharmaceutical-grade silicone precursors.
- Cyanoacrylate Adhesives:Rapid-polymerizing alkyl-2-cyanoacrylate formulations achieve polymerization in 30-60 seconds upon tissue contact. Emergency departments in the United States and Germany standardize these for laceration closure under 5cm, displacing suture kits in triage protocols where speed and cosmetic outcomes outweigh material cost.
- Biocompatible Adhesives:ISO 10993-validated silicone-acrylic hybrid platforms engineered for 7-14 day wear profiles. Long-term care facilities in the United States specify these for fragile geriatric epidermal conditions, commanding premium positioning against commodity alternatives through extended adhesion without trauma upon removal.
- Fibrin Sealants:Plasma-derived or recombinant thrombin-fibrinogen systems mimicking final coagulation cascade stages.
- Tissue Adhesives:Broad category encompassing proprietary polymer platforms for internal and external tissue bonding.
Cyanoacrylate adhesives command the established base. The steepest expansion runs through biocompatible adhesives.
End User:
Cost tier segmentation separates capital-intensive hospital formulary contracts from price-sensitive home healthcare procurement, with surgical centers occupying a mid-tier position on volume-discounted pricing.
- Hospitals:Integrated delivery networks in the United States Southeast—HCA and Tenet facilities—consolidate adhesive sourcing through centralized formularies. These institutions negotiate direct manufacturer agreements bypassing distributor markups on high-volume cyanoacrylate SKUs, compressing channel margins while securing supply continuity.
- Surgical Centers:Ambulatory facilities specializing in orthopedic and cosmetic procedures. German and Japanese surgical centers drive adoption of silicone-acrylic hybrid platforms for joint mobility device fixation, where engineered elasticity beyond conventional suture performance justifies premium pricing.
- Clinics:Outpatient settings with limited storage capacity favoring single-use, ready-to-apply formats.
- Home Healthcare:Post-acute and chronic wound management settings where patient or caregiver application requires simplified delivery systems.
Hospitals anchor volume concentration. Surgical centers are climbing the fastest on orthopedic fixation demand.
Application:
Application maturity correlates with regulatory pathway complexity—wound closure leverages predicate-rich 510(k) routes while orthopedic applications demand novel clinical validation.
- Wound Closure:External tissue approximation replacing sutures and staples in emergency, cosmetic, and pediatric settings. United States children's hospitals create dedicated formulary slots for low-odor, rapid-polymerizing formulations serving needle-free closure demand.
- Orthopedics:Flexural stress applications requiring engineered elasticity. Silicone-acrylic hybrid chemistries capture device fixation contracts previously held by mechanical fasteners in German and Japanese joint replacement protocols.
- Surgical Procedures:Internal tissue sealing and hemostasis in open and laparoscopic interventions.
- Dermatology:Aesthetic and cosmetic applications facing EU MDR Annex XVI reclassification as medical devices.
Wound closure commands the established base. Orthopedics is gaining share fastest on mobility device fixation expansion.
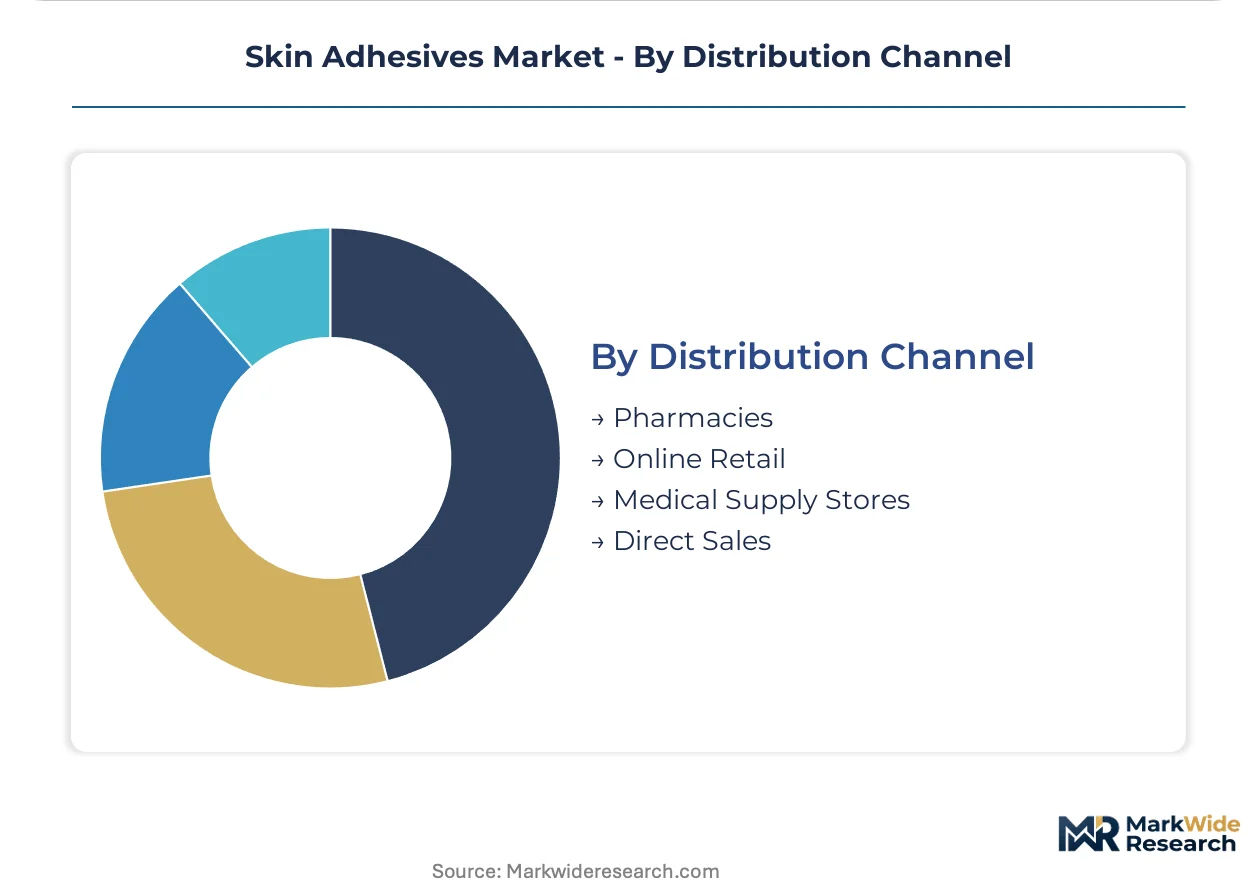
Distribution Channel:
Channel concentration reflects procurement disintermediation trends—hospital IDNs bypass traditional distribution while home healthcare remains pharmacy-dependent.
- Direct Sales:Manufacturer-to-institution contracts negotiated by United States IDN procurement departments unbundling adhesive purchasing from suture and staple agreements. This channel captures margin otherwise allocated to distributor markups on high-volume cyanoacrylate SKUs.
- Medical Supply Stores:Regional distributors serving clinics and smaller surgical facilities with consolidated wound care portfolios.
- Pharmacies:Retail and hospital outpatient dispensaries handling prescription and over-the-counter adhesive products.
- Online Retail:Direct-to-patient channels for chronic wound and ostomy supplies.
Direct sales commands the established base. Online retail is expanding most quickly on home healthcare segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites European supply chain resilience for pharmaceutical-grade silicone precursors, while Japan's Kansai International Airport cold-chain connectivity enables just-in-time delivery of temperature-sensitive fibrinogen feedstocks.
United States
HCA and Tenet integrated delivery networks in the Southeast consolidate adhesive sourcing through centralized formularies, negotiating direct manufacturer agreements that bypass distributor markups on high-volume cyanoacrylate SKUs. FDA 510(k) predicate device narrowing now rejects substantial equivalence claims based on predicates older than 2015, extending validation timelines for reformulated products. Boston and Basel clusters compete for polymer chemist talent commanding 40% wage premiums for expertise spanning pressure-sensitive adhesive mechanics and ISO 10993 toxicology interpretation.
Germany
Trauma centers standardize cyanoacrylate closure for lacerations under 5cm, displacing suture kits in triage protocols where speed and cosmetic outcomes outweigh material cost. REACH restrictions on residual monomer content constrain formulation flexibility for domestic manufacturers. The Rhine-Ruhr industrial zone hosts three specialty chemical producers controlling 70% of pharmaceutical-grade octyl-2-cyanoacrylate feedstock, creating price volatility during scheduled plant turnarounds.
Japan
Surgical centers drive adoption of silicone-acrylic hybrid platforms for joint mobility device fixation, where engineered elasticity beyond conventional suture performance justifies premium pricing. PMDA Sakigake designation for novel biocompatible adhesives with demonstrated superiority over sutures compresses review timelines to six months. The Kanto region surrounding Tokyo concentrates cleanroom manufacturing capacity, with ISO 14644 Class 7 adhesive coating space backlogged 18 months across major industrial zones.
Switzerland
Swissmedic certification requirements for long-wear biocompatible formulations command premium positioning in chronic wound and ostomy segments. Specialty chemical imports from Basel-based suppliers feed German and Japanese adhesive manufacturers with pharmaceutical-grade silicone precursors. The country's dual role as regulator and supplier creates asymmetric information advantages for domestic firms navigating EU MDR technical documentation harmonization.
Skin Adhesives Market Competitive Environment
Listed leaders compete with private specialists across regulatory continuity and material platform validation. The market structure concentrates around vertically integrated medical device portfolios and proprietary silicone-acrylic hybrid chemistries, with tiering between pre-validated ISO 10993 platforms and commodity alternatives. Three archetypes dominate: diversified healthcare conglomerates leveraging captive toxicology data, specialty chemical firms with backward integration into pharmaceutical-grade feedstocks, and focused wound care specialists competing on antimicrobial-loaded matrix differentiation. Competitive moves center on M&A for cleanroom capacity access and strategic partnerships for dual FDA-MDR registration acceleration.
Within the diversified healthcare tier, Johnson & Johnson and 3M anchor competitive positioning through regulatory continuity across multiple adhesive platforms and proprietary extended-wear formulations respectively. Smith & Nephew Plc occupies a specialist position in advanced wound care, exemplifying the antimicrobial-loaded matrix archetype that addresses surgical site infection protocols. These three represent distinct strategic postures: conglomerate scale, materials science depth, and clinical application focus.
| Leading Market Players |
|---|
| Solventum |
| Coloplast Group |
| Johnson & Johnson |
| Avery Dennison Corporation |
| Smith & Nephew Plc |
| 3M |
| Nitto Denko Corporation |
| Henkel AG & Co. KGaA |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Cleanroom capacity utilization above 85% in Boston and Basel clusters concentrates manufacturing leverage among incumbent producers, compressing price floors for ISO 10993-validated formulations while elevating spot-market premiums for third-party coating services. This scale dynamic reinforces bid-ask spreads between captive production and toll-manufactured alternatives.
Pricing Analysis
Volume-discount tiering separates hospital IDN direct contracts from distributor-mediated surgical center procurement, with cyanoacrylate SKUs commanding premium positioning against commodity fibrin alternatives. Price differentiation rests on ISO 10993 certification grade and after-sales technical support bundling. Cost compression in standard-grade segments intensifies as Indian and Brazilian procurement defaults to mechanical closure. Home healthcare channels exhibit highest price sensitivity due to out-of-pocket payment structures.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors elevates inbound logistics costs for pharmaceutical-grade silicone precursors sourced from Swiss and German specialty chemical producers. Supply concentration in Germany, Switzerland, and Japan draws from octyl-2-cyanoacrylate monomer, medical-grade silicone resins, and recombinant fibrinogen feedstocks. Single-source vulnerability runs through the three German-Swiss producers controlling pharmaceutical-grade cyanoacrylate monomer. Distribution runs through hospital IDN direct contracts, regional medical supply distributors, and pharmacy retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where ISO 10993 pre-validation creates switching costs that entrench incumbent positions against reformulated entrants.
For Market Incumbents: Compound regulatory continuity advantages by deepening captive toxicology data repositories and expanding cleanroom capacity in backlogged Japanese industrial zones. Threats from emerging silicone-acrylic hybrid specialists in South Korea require defensive patent filings on extended-wear polymer architectures. For New Entrants and Emerging Players: PMDA Sakigake fast-track designation offers the most penetrable regulatory pathway for novel biocompatible adhesives demonstrating suture superiority. Target pediatric wound care protocols in United States children's hospitals where needle-free closure demand outstrips formulary supply. Go-to-market execution should prioritize direct clinical education over distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with pre-validated ISO 10993 platforms serving chronic wound and ostomy segments. Long-term viability favors acquisition targets with captive silicone precursor supply agreements and existing EU MDR technical files. Watch FDA 510(k) predicate narrowing as an inflection signal for validation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Pre-Validation Investment | Compresses competitive entry timelines against third-party testing-dependent entrants. |
| Cleanroom Capacity Expansion | Captures margin from 18-month backlog in Class 7 adhesive coating space. |
| Dual FDA-MDR Registration Acceleration | Secures parallel market access as EU MDR transition deadlines compress. |
| Antimicrobial Matrix Development | Qualifies for CMS surgical site infection bundle payments in United States hospitals. |
| Silicone Precursor Backward Integration | Insulates margin from German-Swiss monomer supply volatility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged polymer chemists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers across Boston, Basel, Tokyo, and Rhine-Ruhr clusters. Secondary validation drew from SEC 10-K disclosures, customs trade data, and CMS Medicare reimbursement schedules. Bottom-up segment sizing triangulates against top-down macroeconomic anchoring.
Segmentation dimensions modeled span product chemistry, end-user concentration, application specificity, and distribution modality across the projection horizon. CAGRs derive from elasticity-adjusted volume projections and pricing trajectory analysis. Forecast inputs incorporate surgical volume data from trauma center registries and orthopedic procedure databases.
Decision-makers should treat outputs as directional under assumptions of sustained FDA 510(k) predicate narrowing and stable REACH monomer restrictions; material deviation would warrant model refresh. Specific risks include EU MDR Annex XVI reclassification scope expansion and octyl-2-cyanoacrylate feedstock supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
United Kingdom Adhesives Market