
 Bio-Based Adhesive and Sealant Market | 2026-2036
Bio-Based Adhesive and Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Adhesive and Sealant Market Analysis
Buyer concentration among packaging converters and automotive tier-one suppliers is hardening as sustainability scorecards become mandatory in vendor qualification. Henkel AG & Co. KGaA leverages its European manufacturing footprint to supply water-based formulations to major consumer goods brands. Sika AG anchors construction sector demand through certified green building product lines. Arkema differentiates via specialty bio-polyurethane chemistry for high-performance bonding applications.
Bio-based adhesives and sealants are polymeric bonding systems derived from renewable feedstocks such as plant oils, starch, lignin, or bio-succinic acid, formulated to achieve shear strengths and cure profiles comparable to petroleum-derived analogs while reducing cradle-to-gate carbon intensity. Their primary purpose is to replace conventional fossil-based bonding agents in regulated industries where scope-three emissions reporting now extends through the supply chain. Polyurethane formulations occupy the premium performance tier due to superior flexibility and moisture resistance, while acrylic systems compete on cost and UV stability in furniture and signage applications. Packaging demand concentrates in water-based acrylics and hot melt formulations as e-commerce shippers phase out solvent-borne tapes.
The EPA regulates volatile organic compound emissions from adhesive formulations under 40 CFR Part 59, while the EU Green Deal and REACH restrict hazardous substance content and mandate recyclability assessments. These frameworks force reformulation investments and create market access barriers for non-compliant imports. Stakeholders must monitor evolving bio-content certification standards and feedstock traceability requirements as downstream customers embed carbon accounting into procurement decisions.
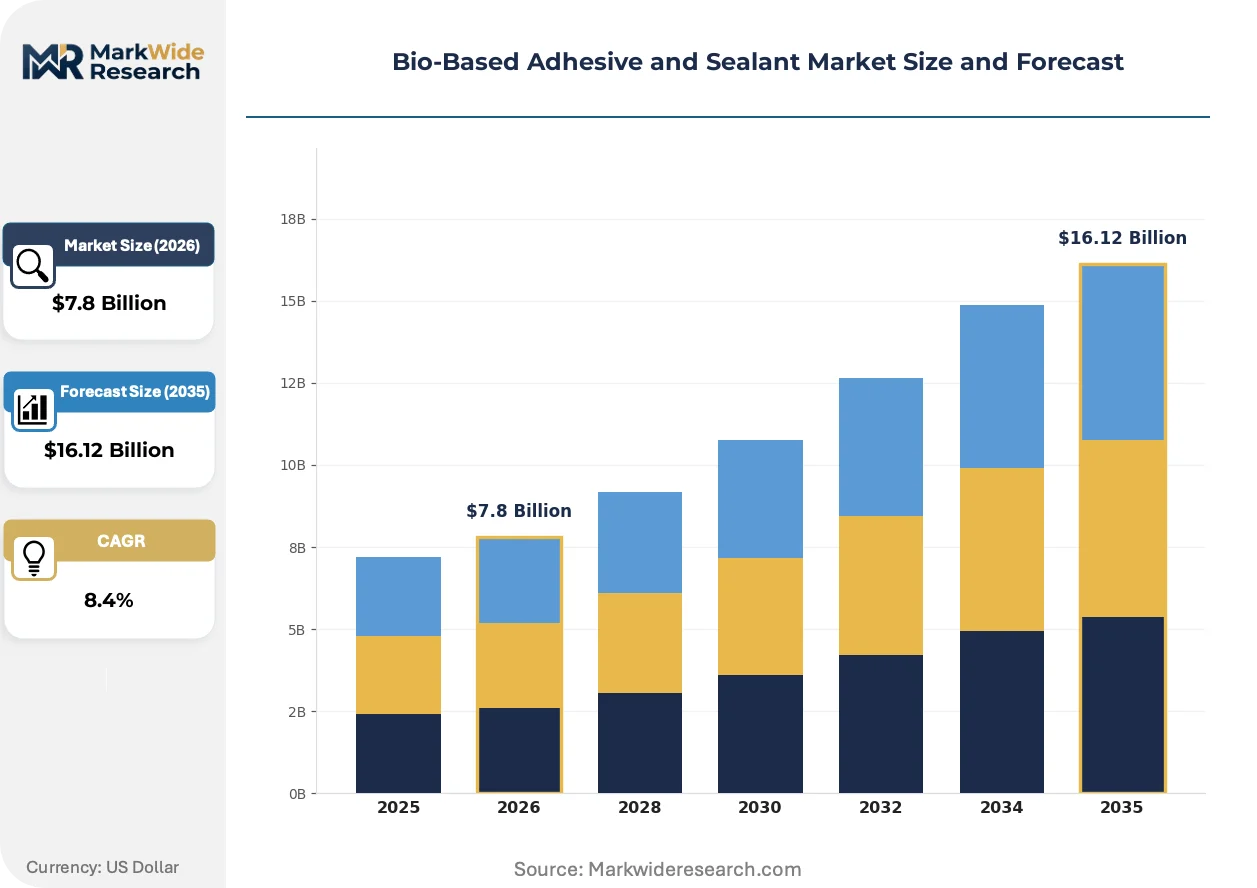
Market Dynamics
Packaging converters and automotive tier-one suppliers now mandate sustainability scorecards in vendor qualification, hardening buyer concentration and forcing feedstock traceability investments across formulation supply chains.
Growth Catalysts
- EU Green Deal:REACH framework restrictions on hazardous substances accelerate substitution away from petrochemical feedstocks in consumer goods packaging.
- Automotive lightweighting:Germany, the United States, and Japan concentrate demand through green building certifications and vehicle weight reduction programs.
- Starch-based hot melts:E-commerce shippers phase out solvent-borne tapes, expanding procurement of water-based acrylics and bio-based hot melt formulations.
Market Restraints
- Plant oil price volatility:Feedstock costs for bio-polyurethane chemistry fluctuate with agricultural commodity markets, compressing margin predictability for formulators.
- Technical performance gaps:Bio-based alternatives struggle to match petroleum-derived analogs in high-temperature shear strength for under-hood automotive bonding.
- Regulatory friction:EPA 40 CFR Part 59 VOC emission limits create compliance burdens that favor incumbent solvent-borne suppliers with established abatement infrastructure.
Strategic Opportunities
- Japan construction sector:METI green building incentives and JIS certification standards create premium positioning for certified bio-based sealant product lines.
- Bio-succinic acid convergence:Fermentation-derived building blocks enable novel polyester polyols with improved hydrolytic stability for marine and outdoor applications.
- Direct-to-converter distribution:Digital procurement platforms bypass traditional distributor markups, capturing margin in high-volume packaging adhesive segments.
Industry Challenges
- Feedstock certification timelines:Third-party bio-content verification under evolving ISO 16620 standards delays product launches by 12-18 months.
- Legacy equipment incompatibility:Water-based formulations require humidity-controlled application environments that solvent-borne lines lack, forcing capital retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Adhesive and Sealant Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Epoxy, Silicones Application: Construction, Automotive, Furniture, Packaging End User: Manufacturers, Contractors, Consumers, Industries Formulation: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Arkema, Evonik Industries AG, Henkel AG & Co. KGaA, Ashland Global Holdings Inc., Wacker Chemie AG, H.B. Fuller Company, Sika AG, Avery Dennison Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Adhesive and Sealant Market Emerging Trajectories
Formulation chemistry and procurement infrastructure are undergoing parallel transformation as renewable feedstock validation tools and digital supply chain tracking reshape how bonding agents are specified, priced, and audited.
Lignin-derived phenolic resins are unifying aromatic structural elements with aliphatic bio-polyol flexibility in hybrid polyurethane systems. Furniture manufacturers in Northern Europe adopt these formulations for panel bonding where formaldehyde emission regulations tighten. The technology is unifying cost-competitive positioning with regulatory compliance in a segment historically resistant to bio-based premiums.
REACH Article 33 disclosure requirements now mandate communication of Substances of Very High Concern content throughout the supply chain. Adhesive formulators face reformulation investments or market access loss for non-compliant imports into EU member states. Construction sealant producers respond by accelerating green building product line certifications under DGNB and BREEAM frameworks.
Scope-three emissions accounting now extends through tier-two supplier tiers in automotive and consumer electronics value chains. Purchasing departments embed carbon intensity thresholds in RFP scoring, displacing price-only sourcing for bonding agents. Germany and California exhibit the most advanced procurement model evolution, with supplier sustainability portals becoming mandatory qualification gates.
Bio-Based Adhesive and Sealant Market Segmentation
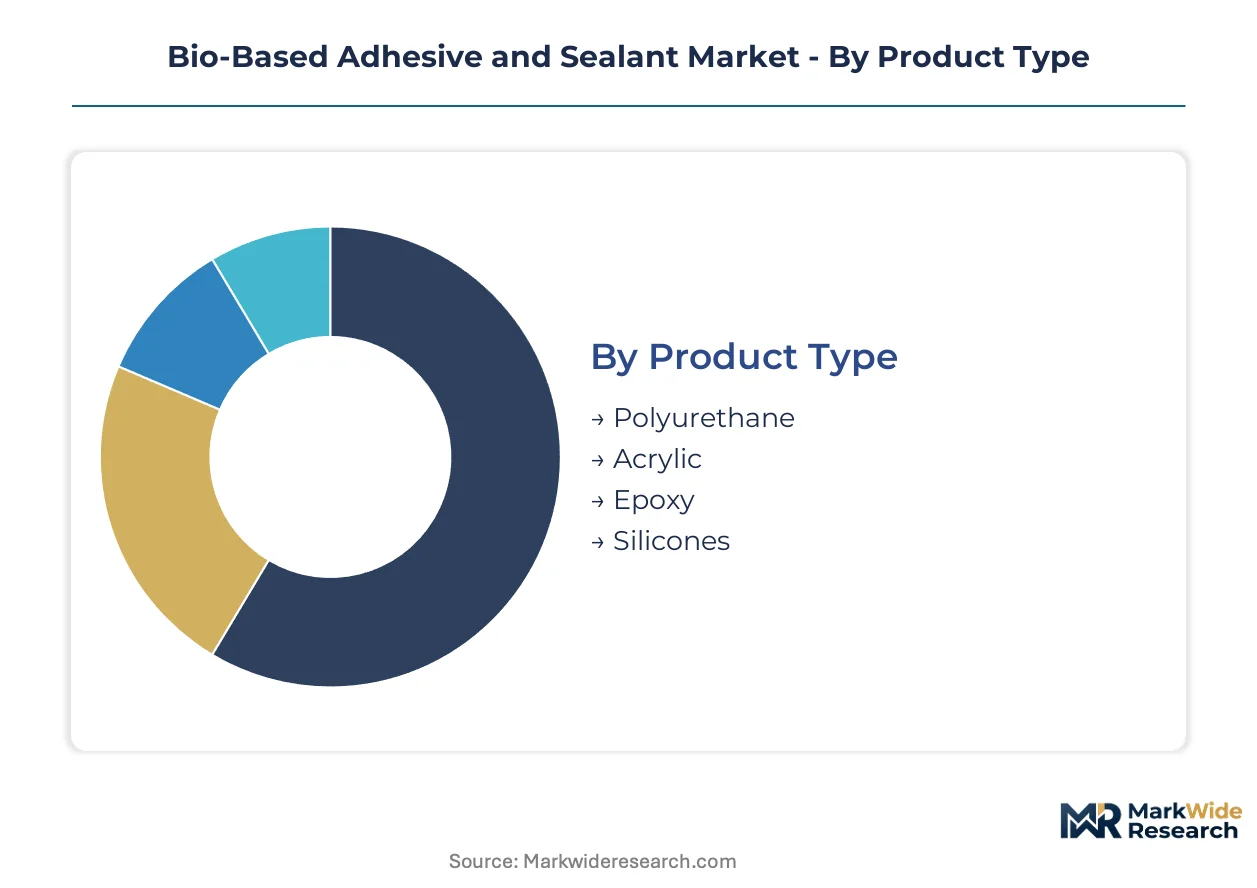
Bio-based adhesive and sealant procurement increasingly hinges on certified bio-content thresholds and formulation-specific regulatory clearances. Segmentation reveals how certification burdens concentrate in high-performance tiers while cost-sensitive applications accept lower bio-content ratios.
Product Type:
Polyurethane formulations carry the heaviest certification load, requiring ISO 16620 bio-content verification plus REACH SVHC disclosure for automotive and construction specifications. Acrylic systems face lighter documentation demands in packaging and furniture segments where performance standards are less stringent.
- Polyurethane:Hybrid systems combining lignin-derived polyols with petroleum isocyanates deliver superior moisture resistance and flexibility for under-hood automotive bonding and structural construction joints. Germany's automotive tier-one suppliers mandate polyurethane grades with minimum 30% bio-based carbon content under sustainability scorecard requirements. Technical performance gaps in high-temperature shear strength persist for fully bio-sourced variants, limiting penetration in engine compartment applications.
- Acrylic:Water-borne emulsions derived from bio-succinic acid and plant-based esters dominate packaging tape and furniture lamination markets. E-commerce shippers in the United States phase out solvent-borne alternatives under EPA 40 CFR Part 59 VOC limits, expanding procurement of certified low-emission acrylic grades. UV stability limitations constrain outdoor signage applications.
- Epoxy:Bio-glycerol and tannin-based curing agents serve marine and industrial coating markets where hydrolytic stability requirements are moderate.
- Silicones:Fermentation-derived siloxane precursors remain nascent, with commercial volumes concentrated in European personal care adjacencies rather than structural bonding.
Polyurethane sits at the top of the volume ranking, with acrylic climbing the fastest as packaging converters accelerate solvent phase-out programs.
Application:
Construction and automotive applications command premium pricing through green building certification alignment, while furniture and packaging compete on reformulation cost parity with incumbent petrochemical systems.
- Construction:Sealant specifications under Germany's DGNB and Japan's CASBEE frameworks require cradle-to-gate carbon documentation. Sika AG and Henkel AG anchor European demand through certified product lines meeting JIS A 5758 and EN 15651 performance standards. Bio-polyurethane construction sealants face 12-18 month third-party verification timelines under evolving ISO 16620 standards.
- Automotive:Lightweighting programs in Germany, Japan, and the United States concentrate demand for high-shear structural adhesives. Scope-three emissions accounting through tier-two supplier tiers now embeds carbon intensity thresholds in OEM RFP scoring. Bio-based alternatives struggle to match petroleum-derived analogs in continuous operating temperatures above 120°C.
- Furniture:Northern European panel manufacturers adopt lignin-phenolic hybrid systems where formaldehyde emission regulations tighten under E1 classification requirements.
- Packaging:Water-based acrylics and starch-based hot melts serve corrugated board and e-commerce fulfillment applications with minimal performance certification overhead.
Construction commands the highest margin tier, with packaging expanding most quickly as sustainability mandates penetrate consumer-facing supply chains.
End User:
Manufacturer procurement exhibits the steepest sustainability integration, while contractor and consumer channels lag in bio-content specification sophistication.
- Manufacturers:Automotive OEMs and packaging converters embed carbon accounting into vendor qualification portals. Supplier sustainability scorecards have become mandatory gates in Germany and California procurement frameworks. Direct-to-converter digital platforms bypass traditional distributor markups in high-volume segments.
- Contractors:Construction applicators select certified sealants based on project-specific green building point contributions rather than standalone bio-content premiums.
- Consumers:Retail DIY adhesive purchases show limited price tolerance for bio-based premiums, with uptake concentrated in Nordic markets with strong environmental labeling recognition.
- Industries:Marine and electronics manufacturers represent niche demand for specialty bio-polyurethane grades with hydrolytic stability specifications.
Manufacturers represent the dominant volume channel, with contractors gaining specification influence as green building certification spreads.
Formulation:
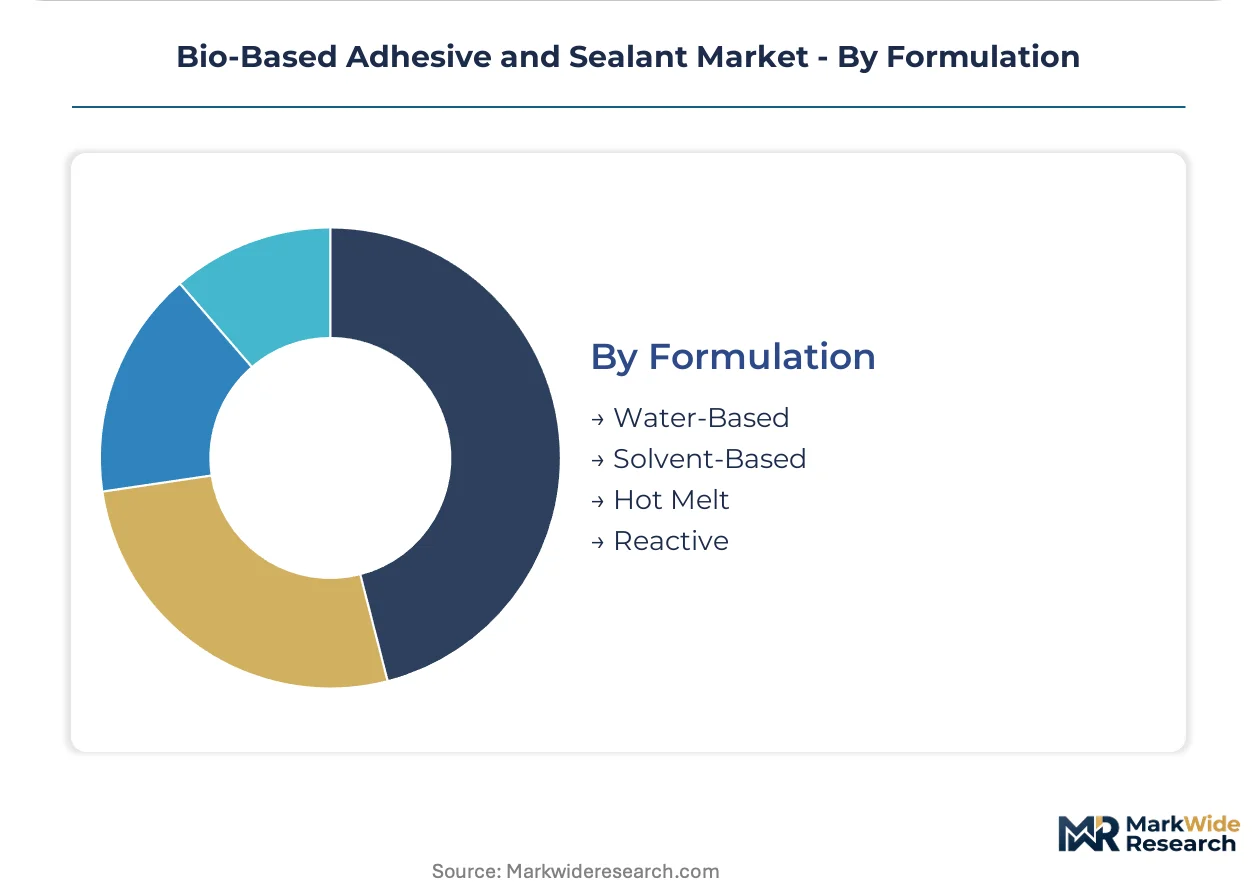
Water-based systems require humidity-controlled application infrastructure investments, while hot melt and reactive formulations align better with legacy solvent-borne equipment footprints.
- Water-Based:Acrylic and polyurethane dispersions serve packaging and furniture markets where VOC emission limits are most restrictive. Legacy solvent-borne lines require capital retrofit for humidity-controlled environments, forcing mid-tier converters into equipment replacement decisions. EPA 40 CFR Part 59 compliance favors incumbent suppliers with established abatement infrastructure.
- Hot Melt:Starch and plant-oil derived formulations compete with ethylene-vinyl acetate in corrugated board sealing and bookbinding. E-commerce fulfillment growth drives volume expansion with lower capital barriers than water-based conversion.
- Solvent-Based:Declining share in regulated markets, with residual demand in industrial maintenance coatings where performance specifications resist reformulation.
- Reactive:Two-component polyurethane and epoxy systems serve structural automotive and marine applications with extended cure profiles accepted in factory-controlled environments.
Water-based formulations lead by volume, with hot melt gaining share fastest among converters seeking minimal equipment retrofit pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive lightweighting demand while the United States drives packaging converter procurement through EPA emission mandates. Japan anchors construction sector certification requirements under METI green building frameworks.
Germany
Automotive tier-one suppliers in Stuttgart and Munich mandate minimum 30% bio-based carbon content in polyurethane adhesives for under-hood bonding applications. The EU Green Deal and REACH Article 33 SVHC disclosure requirements force reformulation investments across supplier tiers. Bavarian industrial clusters around Ingolstadt and Wolfsburg concentrate R&D activity for high-shear structural bonding systems.
United States
E-commerce fulfillment networks in California and Texas phase out solvent-borne packaging tapes under EPA 40 CFR Part 59 VOC emission limits. The Inflation Reduction Act bio-preferred procurement guidelines create federal purchasing preferences for certified bio-content products. Midwestern corrugated board converters in Illinois and Ohio expand water-based acrylic capacity to serve Amazon and Walmart sustainability scorecards.
Japan
Construction sealant demand concentrates in Tokyo and Osaka metropolitan areas where CASBEE green building certification requires cradle-to-gate carbon documentation. METI green building incentives and JIS A 5758 performance standards create premium positioning for certified product lines. Nagoya automotive clusters drive polyurethane formulation demand for vehicle weight reduction programs.
China
Furniture manufacturing in Guangdong and Zhejiang provinces adopts lignin-phenolic hybrid adhesives under tightening formaldehyde emission regulations. The country's dual carbon goals and GB standards for indoor air quality accelerate substitution away from urea-formaldehyde systems. Yangtze River Delta packaging hubs in Shanghai and Jiangsu expand water-based hot melt capacity for export-oriented consumer goods.
France
Aerospace and luxury goods manufacturers in Île-de-France embed carbon intensity thresholds in supplier RFP scoring for bonding agents. The EU Green Deal and DGNB-aligned national building codes mandate bio-content verification for construction sealants in public procurement. Lyon chemical clusters develop fermentation-derived polyester polyols for specialty coating applications.
Bio-Based Adhesive and Sealant Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven chemical majors anchor premium performance segments while regional formulators capture cost-sensitive packaging volumes. The vendor base separates into three strategic archetypes: integrated resin producers controlling upstream bio-polyol supply, formulation houses blending certified feedstocks for end-user specifications, and application-technology providers bundling adhesive systems with dispensing equipment. Dominant competitive moves include backward integration into fermentation-derived building blocks and strategic partnerships with packaging converters for direct procurement platform development.
Within the European formulation tier, Henkel AG & Co. KGaA and Sika AG exemplify divergent specialization strategies. Henkel leverages its Düsseldorf-based manufacturing footprint to supply water-based systems to consumer goods brands with sustainability scorecard requirements. Sika anchors construction sector positioning through certified green building product lines meeting JIS and EN performance standards. Arkema occupies a specialty chemistry position focused on high-performance bonding applications where bio-polyurethane hybrid systems command technical premiums.
| Leading Market Players |
|---|
| Arkema |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| Ashland Global Holdings Inc. |
| Wacker Chemie AG |
| H.B. Fuller Company |
| Sika AG |
| Avery Dennison Corporation |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap German formulators anchor premium polyurethane pricing through captive bio-polyol supply arrangements, while private-equity-rolled-up packaging specialists compete on starch-based hot melt volume with thinner margin structures. This ownership bifurcation concentrates pricing power upstream with integrated resin producers and compresses returns for converters lacking backward integration into plant oil or fermentation feedstock sourcing.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for water-based acrylic systems as corrugated board converters expand in-house blending capabilities. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified construction sealants from uncertified furniture grades and commodity packaging tapes. Price differentiation rests on ISO 16620 bio-content verification and JIS A 5758 performance certification. Cost compression in standard-tier acrylics is intensifying because Midwestern converters bypass distributor markups through direct procurement platforms. Packaging converters exhibit the highest price sensitivity, while Japanese construction contractors accept premiums for CASBEE-aligned sealant specifications.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal and US Inflation Reduction Act bio-preferred procurement guidelines are reshaping sourcing patterns toward regional fermentation-derived building blocks. Feedstock supply concentrates in Germany, the United States, and Brazil for plant oil and bio-succinic acid precursors. Formulation output draws from lignin-derived polyols, starch feedstocks, and petroleum isocyanate crosslinkers. Single-source vulnerability runs through agricultural commodity price volatility for soybean and corn-derived inputs. Distribution runs through direct-to-converter digital platforms in high-volume packaging segments and authorized distributor networks for certified construction and automotive grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive OEMs and packaging converters now embed carbon intensity thresholds as mandatory gates, displacing price-only sourcing for bonding agents with premium-certified specifications.
For Market Incumbents: Deploy backward integration into fermentation-derived polyester polyol production to defend margin position against emerging pure-play bio-succinic acid specialists. Henkel AG and Sika AG already anchor European demand through certified product lines; laggards face exclusion from tier-one automotive RFPs as scope-three emissions accounting extends through supplier tiers. Priority investments center on ISO 16620 verification infrastructure and humidity-controlled application equipment partnerships for packaging converter retrofit programs. For New Entrants and Emerging Players: Begin with lignin-phenolic hybrid systems for Northern European furniture manufacturers where formaldehyde emission regulations tighten under E1 classification requirements. White-space concentration sits in marine and outdoor applications requiring hydrolytic stability specifications that incumbent petroleum-derived epoxies currently dominate. A direct-to-converter digital procurement platform bypassing traditional distributor markups offers the cleanest go-to-market angle for high-volume starch-based hot melt penetration. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators lacking captive bio-polyol supply but holding established converter relationships in packaging and furniture segments. Long-term viability over the projection horizon favors acquisition targets with ISO 16620 certification pipelines and established sampling programs with German automotive tier-one suppliers. The signal to watch is METI green building incentive expansion beyond Tokyo and Osaka into Nagoya and Fukuoka construction markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Production | Captive supply of fermentation-derived polyester polyols insulates margin from agricultural commodity volatility. |
| ISO 16620 Certification Investment | Third-party bio-content verification unlocks automotive and construction procurement portals in Germany and Japan. |
| Direct-to-Converter Digital Platform | Bypassing distributor markups captures margin in high-volume e-commerce packaging adhesive segments. |
| Humidity-Controlled Application Equipment Partnership | Equipment retrofit financing removes capital barriers for mid-tier converters transitioning from solvent-borne lines. |
| Joint Venture with Fermentation Building Block Producers | Strategic alignment with bio-succinic acid specialists accelerates novel hydrolytically stable polyurethane development. |
Methodological Framework
Coverage spans Germany, the United States, Japan, China, and France, with primary inputs from each market's adhesive formulators and downstream procurement officers. The analysis combines structured interviews with plant managers at European resin producers, procurement leads at automotive tier-one suppliers, distribution channel partners in Midwestern corrugated board networks, and technical R&D directors at construction sealant specialists. Secondary validation draws from ECHA REACH registration databases, EPA 40 CFR Part 59 compliance filings, JIS A 5758 certification records, and customs trade data for bio-polyol feedstock flows. Bottom-up demand modeling triangulates against top-down chemical industry capacity assessments.
Granularity extends to product-type level for polyurethane, acrylic, epoxy, and silicone formulations, crossed with application segments in construction, automotive, furniture, and packaging. End-user channels separate manufacturer direct procurement, contractor specification, and retail DIY purchase patterns. Regional production hub clustering and formulation technology diffusion curves inform volume and value trajectory derivation across the modeling period. Industry-specific forecast inputs incorporate automotive lightweighting program timelines and e-commerce fulfillment network expansion rates.
Caveats apply where EU Green Deal implementation delays, REACH SVHC list expansion, or bio-succinic acid fermentation yield breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding certification standard stability and converter equipment retrofit pacing. Feedstock price volatility, regulatory friction in EPA compliance pathways, and technical performance gaps in high-temperature automotive applications represent specific revision triggers. A small set of named triggers—METI incentive expansion, ISO 16620 standard finalization, and major packaging converter vertical integration announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Italy Sealants Market