
 Polyurethane (PU) Adhesives in Electronics Market | 2026-2036
Polyurethane (PU) Adhesives in Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Adhesives in Electronics Market Analytics
Multi-source procurement for specialty polymers is pivoting as electronics OEMs reduce dependency on single adhesive suppliers amid resin volatility. Henkel AG & Co. KGaA leverages its European formulation centers to sustain consistent supply to automotive electronics Tier-1s. Dow anchors its position through captive polyol production and direct technical service models in Asia-Pacific. H.B. Fuller Company competes on customized dispense-system compatibility for high-speed SMT lines.
Polyurethane adhesives in electronics are thermoset or thermoplastic polymer systems formed from isocyanate and polyol reactions, typically cured at 80-150°C to achieve dielectric strength above 10 kV/mm and elongation of 100-400% for stress relief in thermal cycling. These materials bond dissimilar substrates, encapsulate sensitive components, and seal against moisture ingress in portable and automotive electronics. Thermosetting formulations dominate volume owing to their superior heat resistance and structural permanence under continuous operation. Water-based PU adhesives represent the fastest-expanding product category as VOC regulations tighten across manufacturing jurisdictions. Bonding applications capture the largest share of value, though encapsulation commands premium pricing due to purity requirements and long-term reliability testing.
EPA oversees VOC emissions from adhesive manufacturing facilities in the United States, while REACH governs substance registration and restriction across European electronics supply chains. RoHS directly limits hazardous substances in finished electronic equipment, forcing reformulation of legacy PU catalysts and stabilizers. Stakeholders must monitor evolving chemical restriction schedules and pre-qualify alternative catalyst systems before regulatory deadlines disrupt material approvals.
Market Dynamics
Miniaturization imperatives in portable electronics are compressing bond-line tolerances below 50 microns, forcing adhesive formulators to engineer ultra-low-viscosity PU systems that cure without void formation in confined geometries. This structural pressure cascades through raw material specifications, equipment compatibility requirements, and supplier qualification timelines.
Growth Catalysts
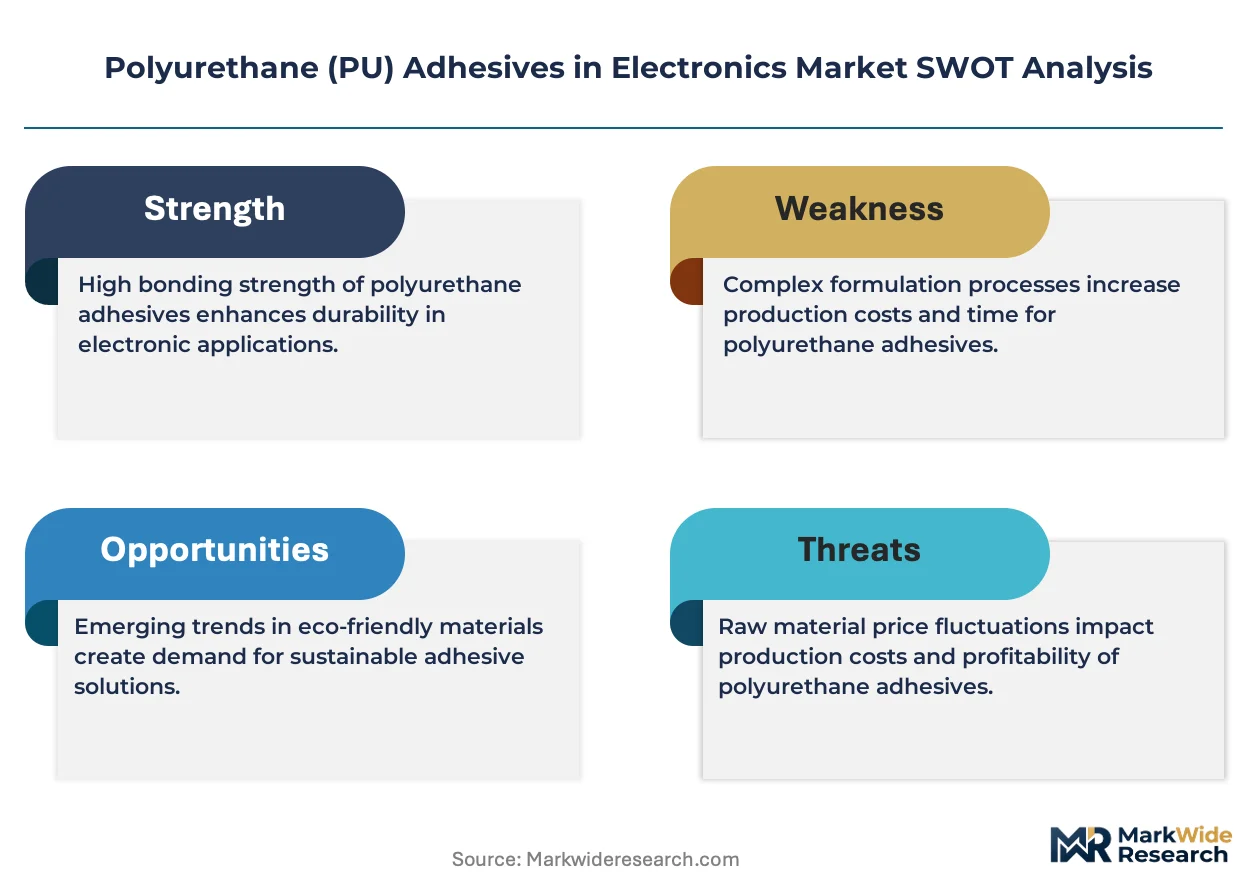
- RoHS substance restrictions:European electronics manufacturers face mandatory elimination of legacy lead-based solder alternatives, accelerating PU adhesive adoption for compliant thermal management assemblies.
- Wearable device proliferation:Smartwatch and hearable manufacturers specify flexible encapsulants that withstand repeated flex cycling while maintaining IP67 ingress protection ratings.
- Automotive electronics integration:Advanced driver-assistance system module producers in Germany and Japan specify PU potting compounds for sensor housing sealing under vibration and thermal shock conditions.
Market Restraints
- Isocyanate price volatility:Crude-linked MDI and TDI feedstock costs swing with energy markets, compressing formulation margins unpredictably.
- Specialty polyol supply concentration:Caprolactone and polycarbonate polyol production clusters in Belgium and Japan create geographic vulnerability for high-performance electronics grades.
- Catalyst substitution complexity:REACH Annex XIV authorization requirements for tin-based catalysts force reformulation cycles that extend qualification timelines by 18-24 months.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone and component production create captive demand for localized adhesive supply with reduced import duty exposure.
- UV-curable PU hybrid systems:Combination radiation-thermal cure chemistries enable bond-and-cap processing in single-pass automated lines for display module assembly.
- Water-based technology migration:EPA NESHAP compliance deadlines for coating and adhesive operations drive solvent-to-aqueous conversion programs across US contract manufacturers.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in isocyanate-polyol stoichiometry and rheology control for electronics applications concentrates among specialists with 15+ years of experience.
- Cleanroom manufacturing capex:Semiconductor-grade encapsulant production requires ISO Class 7 environments and continuous particle monitoring systems that demand substantial facility investment.
- Dual-carbon alignment verification:Chinese electronics OEMs now require Scope 3 emissions documentation that traces polyol feedstocks through multiple chemical processing tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Adhesives in Electronics Market |
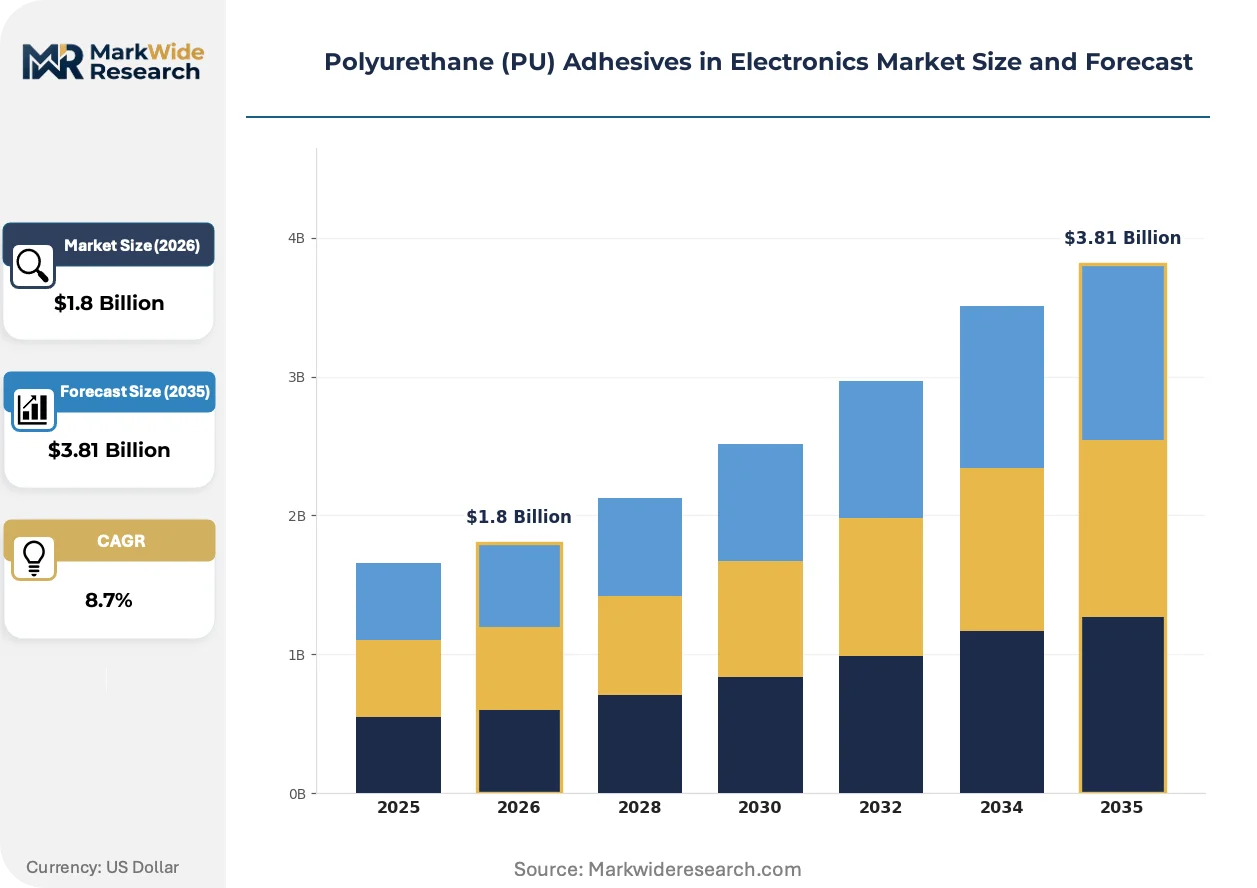
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting, Thermoplastic, Solvent-based, Water-based End User: Consumer Electronics, Automotive Electronics, Industrial Equipment, Telecommunications Application: Coating, Encapsulation, Bonding, Sealing Installation: Manual, Automated, Hybrid, On-site |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Dow, Covestro AG, Arkema, BASF, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Adhesives in Electronics Market Evolving Landscape
Electronics adhesive technology is bifurcating between ultra-high-reliability formulations for automotive and aerospace applications and cost-optimized systems for high-volume consumer assembly. This divergence is reshaping R&D resource allocation and supplier portfolio architecture.
Thermally conductive PU adhesives incorporating boron nitride or aluminum oxide fillers are converging with die-attach and heat-spreader applications previously dominated by epoxy and silicone chemistries. Power semiconductor module manufacturers in automotive traction inverters specify these materials for direct chip-to-substrate bonding. The structural consequence is compression of the thermal interface material stack from three discrete layers to a single adhesive bond line.
REACH substance restriction schedules are tightening allowable residual monomer content in cured adhesives to below 0.1% by mass for isocyanate species. Electronics OEMs serving European markets must requalify existing PU grades or face supply discontinuity. High-reliability automotive Tier-1s are responding fastest, with some completing catalyst system transitions 18 months ahead of regulatory deadlines.
Contract electronics manufacturers are consolidating adhesive procurement from multiple regional suppliers toward single-source technical partnerships with formulation houses that provide integrated dispense equipment and process engineering support. This consolidation displaces transactional spot purchasing for standard grades. The shift is most visible in Vietnam and Mexico, where new surface-mount technology lines are being commissioned with vendor-locked adhesive-dispense systems.
Polyurethane (PU) Adhesives in Electronics Market Segmentation
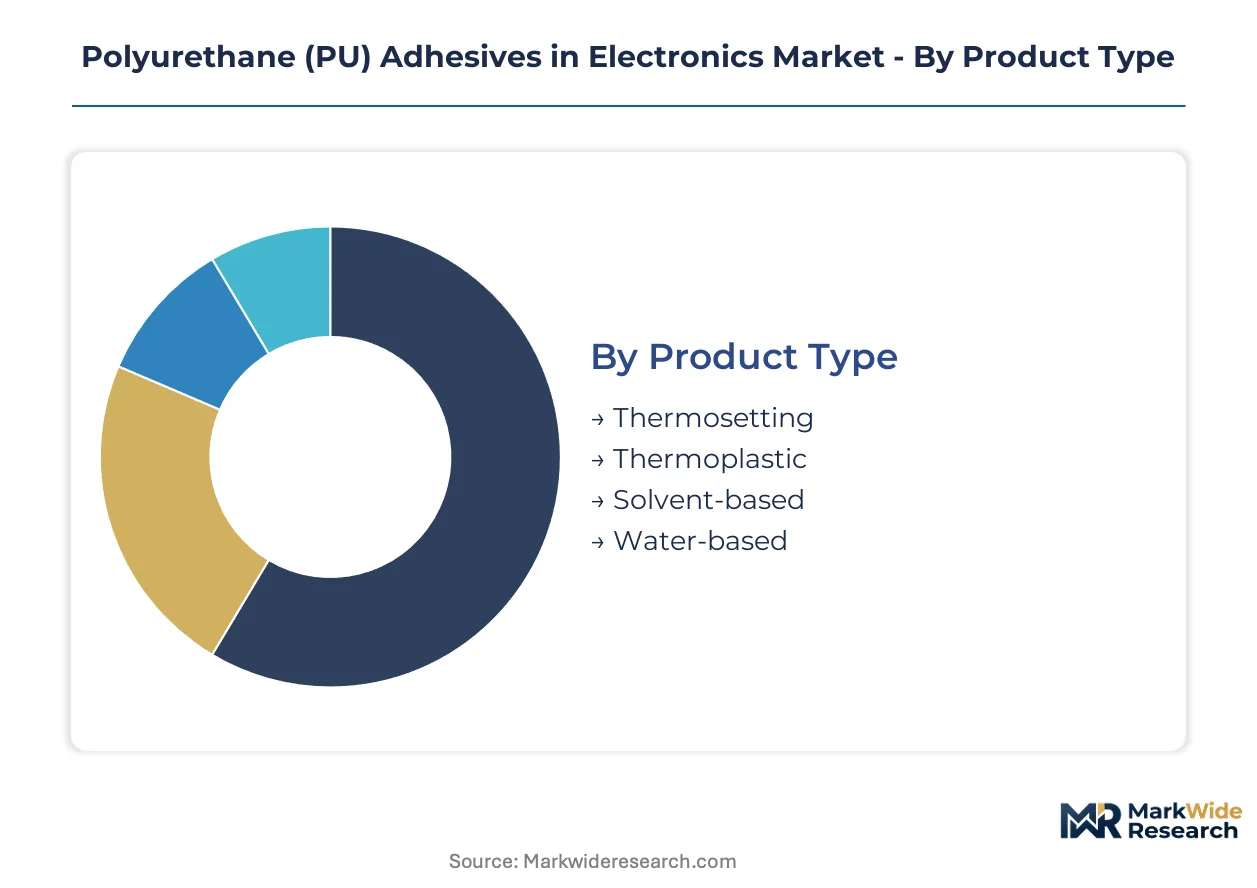
Segmentation in the polyurethane adhesives electronics market reveals how formulation chemistry, end-use reliability requirements, and manufacturing process constraints interact to shape procurement decisions. Each dimension carries distinct technical specifications, regulatory burdens, and margin structures that suppliers must navigate simultaneously.
Product Type:
Thermosetting formulations command procurement budgets for applications where thermal permanence outweighs reworkability, while water-based systems attract investment from OEMs facing VOC compliance deadlines.
- Thermosetting:Cross-linked polymer networks cure irreversibly at 80-150°C to deliver dielectric strength above 10 kV/mm and structural integrity under continuous thermal cycling. Automotive electronics Tier-1s in Germany and Japan specify these grades for power module encapsulation where rework is prohibitively expensive. Volume sits with thermosetting; growth tilts toward water-based.
- Thermoplastic:Linear polymer chains enable reversible softening for repair and recycling of bonded assemblies, suiting consumer electronics with shorter design lifecycles. Chinese smartphone contract manufacturers favor these grades for display bonding where yield recovery matters.
- Solvent-based:Traditional formulations utilizing organic carriers face EPA NESHAP compliance pressure and REACH substance restriction schedules across European supply chains.
- Water-based:Aqueous dispersions eliminate VOC emissions at point of application, expanding most quickly as US and European electronics manufacturers convert coating and bonding operations ahead of regulatory deadlines.
Formulation R&D investment clusters on thermosetting durability improvements and water-based drying speed acceleration.
End User:
Reliability tier requirements create sharp price-performance boundaries between consumer-grade and automotive-grade specifications, with telecommunications infrastructure occupying an intermediate position on mean-time-between-failure metrics.
- Consumer Electronics:Smartphone, tablet, and wearable device manufacturers prioritize thin bond lines below 50 microns, rapid cure cycles compatible with high-speed SMT lines, and cost structures that absorb commodity pricing pressure. Vietnam and Mexico assembly plants specify adhesives with integrated dispense system compatibility.
- Automotive Electronics:Advanced driver-assistance system module producers demand potting compounds that withstand vibration, thermal shock from -40°C to 150°C, and 15-year service life validation. REACH-compliant catalyst systems and RoHS substance documentation are mandatory for European vehicle program qualification.
- Industrial Equipment:Factory automation and process control electronics require moisture ingress protection in harsh operating environments without the full automotive validation burden.
- Telecommunications:Base station and network infrastructure equipment manufacturers balance outdoor weathering resistance with multi-decade depreciation schedules.
Automotive electronics generate premium pricing; consumer electronics drive volume scale.
Application:
Functional performance requirements and purity standards determine whether an adhesive functions as a commodity consumable or a qualified structural material with 18-24 month approval timelines.
- Encapsulation:Semiconductor-grade purity requirements and long-term reliability testing command premium pricing for sensor housing and power module protection. Cleanroom manufacturing at ISO Class 7 or better is mandatory, concentrating supply among specialized formulators with substantial facility investment.
- Bonding:Structural attachment of dissimilar substrates—metal to plastic, glass to frame—represents the largest volume consumption across portable and automotive electronics assembly.
- Coating:Conformal protection of printed circuit board assemblies competes with acrylic, silicone, and epoxy chemistries on cost and reworkability trade-offs.
- Sealing:Gasket and enclosure sealing for IP67 ingress protection in wearables and hearables requires flexible formulations that withstand repeated flex cycling without crack propagation.
Encapsulation captures margin; bonding captures throughput.
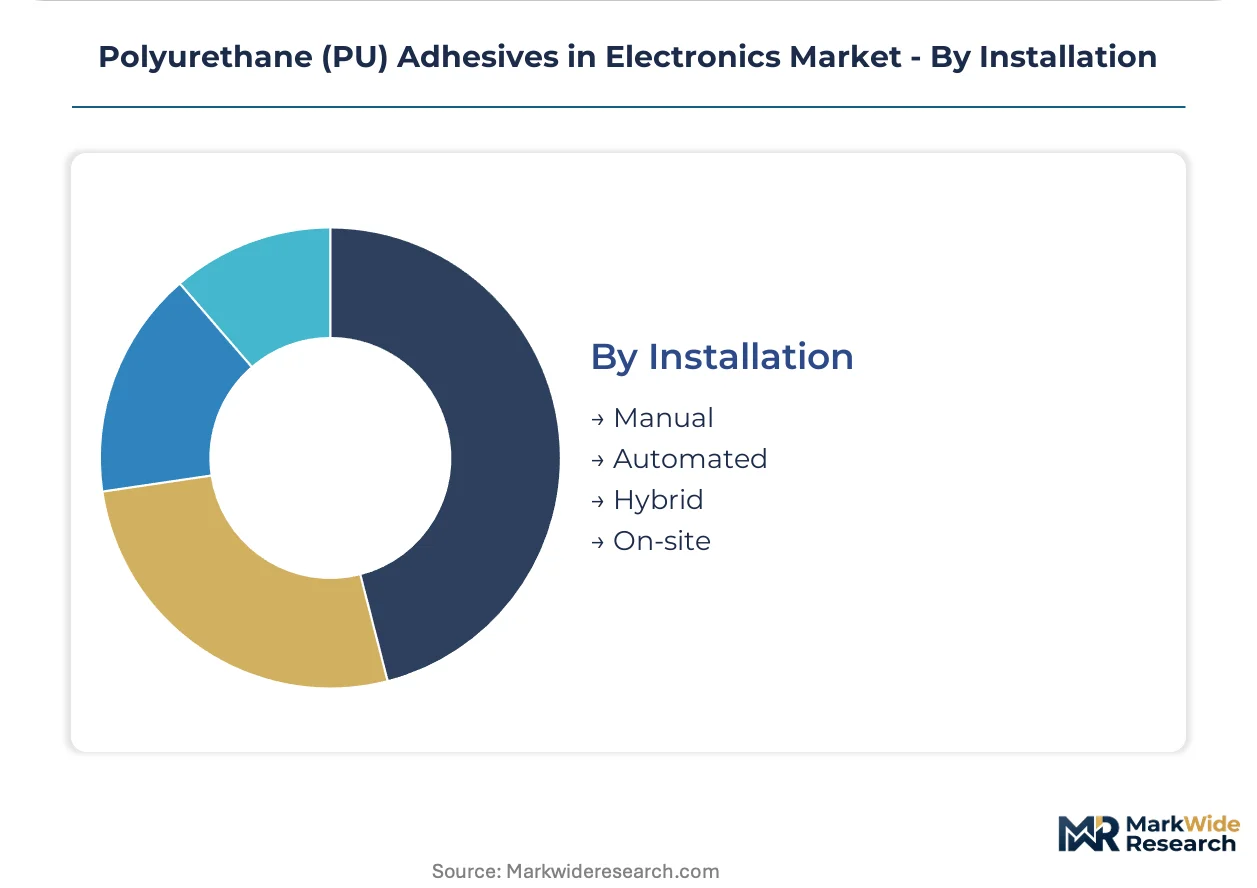
Installation:
Capital equipment intensity and labor cost arbitrage between developed and emerging manufacturing economies determine which installation mode dominates regional procurement patterns.
- Automated:Robotic dispense systems with vision-guided needle positioning achieve bond line tolerances below 50 microns at cycle times compatible with high-volume consumer electronics assembly. China and Vietnam surface-mount technology lines increasingly specify vendor-locked adhesive-dispense systems from formulation partners providing integrated process engineering support.
- Manual:Hand dispense operations persist in prototype, repair, and low-volume industrial equipment applications where capital investment in automation cannot be amortized.
- Hybrid:Semi-automated systems combine operator loading with machine-controlled dispense parameters for mid-volume production.
- On-site:Field installation and repair operations for telecommunications infrastructure and industrial equipment require portable curing equipment and extended working time formulations.
Automated installation dominates new line investment; manual methods retain niche utility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isocyanate and polyol production clusters in Belgium, Japan, and the United States anchor regional supply capabilities for electronics-grade polyurethane adhesives. Manufacturing investment flows toward contract electronics assembly concentrations in Asia-Pacific and North America.
China
Smartphone and wearable device contract manufacturers in Shenzhen and Dongguan specify ultra-low-viscosity PU systems for sub-50-micron bond lines. The Ministry of Ecology and Environment enforces dual carbon goals requiring Scope 3 emissions documentation through polyol processing tiers. Yangtze River Delta electronics parks in Suzhou and Kunshan host captive adhesive blending facilities serving automotive sensor module producers.
Germany
Automotive electronics Tier-1s in Stuttgart and Munich demand REACH-compliant catalyst systems for power module encapsulation with 15-year service life validation. ECHA substance restriction schedules force 18-24 month reformulation cycles for tin-based catalyst alternatives. Bavaria's automotive electronics corridor concentrates potting compound procurement for advanced driver-assistance systems.
United States
EPA NESHAP compliance deadlines drive solvent-to-aqueous conversion programs across Texas and California contract manufacturing operations. Power semiconductor module producers specify thermally conductive PU adhesives for automotive traction inverters. Pacific Northwest electronics assembly clusters specify vendor-locked dispense systems with integrated process engineering support.
Japan
METI industrial standards govern isocyanate residual monomer thresholds in cured adhesives for consumer electronics exports. Caprolactone polyol production in the Chubu region supplies high-performance electronics grades with geographic concentration vulnerability. Kansai-area electronics chemical formulators complete catalyst transitions ahead of European regulatory deadlines.
India
PLI scheme incentives for mobile phone production in Uttar Pradesh and Tamil Nadu create captive demand for localized adhesive supply chains. BIS certification requirements for imported bonding materials extend supplier qualification timelines. Gujarat specialty chemical parks attract polyurethane formulation investment to serve Maharashtra electronics assembly corridors.
Polyurethane (PU) Adhesives in Electronics Market Competitive Landscape
Global majors compete with regional champions across formulation technology and integrated dispense system partnerships. Market structure tilts toward consolidated supply among European and North American chemical conglomerates with captive polyol production, while Asian contract manufacturers fragment procurement across multiple regional blenders. Three archetypes dominate: integrated chemical producers with backward polyol control, specialty adhesive houses with dispense equipment partnerships, and regional formulators serving single-country electronics clusters. Competitive moves center on catalyst system pre-qualification ahead of REACH deadlines and technical service model deployment in Vietnam and Mexico assembly corridors.
Within the integrated chemical producer tier, Dow and Covestro AG exemplify upstream control strategies through captive polyol manufacturing. Henkel AG & Co. KGaA occupies a position bridging formulation expertise with direct technical service models. These three companies represent distinct competitive positioning: Dow anchors through raw material integration, Covestro AG sits within high-performance polymer systems, and Henkel AG & Co. KGaA exemplifies adhesive-specialist-with-equipment-partnership archetypes. Regional formulators in China and Southeast Asia compete on import duty avoidance and localized qualification support.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Dow |
| Covestro AG |
| Arkema |
| BASF |
| Huntsman Corporation |
| Others |
Value Network & Pricing Analysis
REACH Annex XIV authorization deadlines for tin-based catalysts gate both qualified supply and premium-tier pricing access, forcing electronics OEMs to pre-qualify alternative formulations 18-24 months ahead of regulatory cutoffs or face supply discontinuity at contracted price points.
Pricing Analysis
Warranty-backed technical service separates premium-tier suppliers from commodity blenders in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—automotive-grade encapsulants with 15-year service life validation command substantial premiums over consumer electronics bonding grades. Cost compression in standard-tier formulations is intensifying because Chinese contract manufacturers consolidate procurement toward single-source partnerships with integrated dispense equipment providers. Consumer electronics assemblers in Vietnam and Mexico exhibit highest price sensitivity; automotive Tier-1s in Germany and Japan demonstrate lowest sensitivity due to rework cost exposure.
Supply Chain Analysis
Isocyanate feedstock supply rests on MDI and TDI production clusters in Belgium, Japan, and the United States. Specialty polyol manufacturing draws from caprolactone producers in the Chubu region and polycarbonate polyol facilities in Belgium, creating geographic concentration vulnerability for high-performance electronics grades. Single-source dependency on Japanese and Belgian polyol suppliers presents structural risk amid energy market volatility and shipping chokepoint exposure. Distribution runs through formulation houses with captive blending capabilities in China, Germany, and the United States, supported by direct technical service models in emerging assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH catalyst substitution complexity extends qualification timelines beyond 18 months, forcing smaller regional blenders without reformulation expertise to exit.
For Market Incumbents: Anticipate tin-based catalyst obsolescence by accelerating alternative system pre-qualification with automotive Tier-1s ahead of ECHA deadlines. Deepen backward integration into captive polyol production to insulate margin structures from MDI-TDI feedstock volatility. Secure vendor-locked dispense system partnerships in Vietnam and Mexico assembly corridors to displace transactional spot purchasing.
For New Entrants and Emerging Players: Begin with water-based PU adhesive formulation for US EPA NESHAP compliance deadlines, where solvent-to-aqueous conversion programs create immediate procurement windows among Texas and California contract manufacturers. Target India PLI scheme electronics clusters in Uttar Pradesh and Tamil Nadu for localized blending investment with BIS certification support. Lead with integrated process engineering and dispense equipment compatibility rather than commodity grade supply.
For Investors and Strategic Acquirers: ECHA substance restriction schedule acceleration is the leading indicator that catalyst system transition capability will separate viable acquisition targets from stranded assets. Five-to-ten year viability hinges on pre-qualified REACH-compliant formulations rather than legacy product portfolios. Acquire specialty formulators with ISO Class 7 cleanroom encapsulant production and established automotive Tier-1 qualification records.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst System Pre-qualification | ECHA REACH deadlines force 18-24 month reformulation cycles ahead of authorization dates. |
| Backward Integration into Polyol Production | Captive MDI-TDI supply insulates margin structures from crude-linked feedstock volatility. |
| Water-based Technology Migration | EPA NESHAP compliance deadlines drive solvent-to-aqueous conversion across US contract manufacturing. |
| Vendor-locked Dispense System Partnerships | Integrated process engineering support displaces transactional spot purchasing in Vietnam and Mexico. |
| Cleanroom Manufacturing Scale-up | ISO Class 7 encapsulant production capability qualifies suppliers for semiconductor-grade purity requirements. |
Research Methodology
Multi-period observation of REACH substance restriction schedules, EPA NESHAP compliance deadlines, and catalyst system transition timelines anchored the trend analysis, supplemented by interviews with adhesive formulation chemists, automotive electronics Tier-1 procurement directors, contract manufacturing plant managers, and specialty polyol production engineers. Secondary validation drew from ECHA authorization databases, EPA regulatory filings, SEC 10-K disclosures from listed chemical conglomerates, and customs trade data tracking isocyanate and polyol cross-border flows. Bottom-up segment sizing triangulated against top-down industry value chain estimates.
Segment-weighting across thermosetting, thermoplastic, solvent-based, and water-based product categories combined with end-user stratification by reliability tier shaped the analytical framework across the projection horizon. Application-level modeling separated encapsulation, bonding, coating, and sealing functions with purity-grade differentiation. CAGRs derived from elasticity-adjusted demand curves incorporating miniaturization imperatives, regulatory compliance deadlines, and automotive electronics integration rates. Forecast inputs included dual-carbon documentation requirements from Chinese OEMs and PLI scheme incentive structures in India.
Underlying measurement precision varies by segment; automotive-grade encapsulation with 15-year validation carries tighter precision than consumer electronics bonding grades subject to rapid design cycle turnover. Forecasts reflect documented assumptions regarding catalyst substitution timelines, resin volatility patterns, and regional manufacturing investment flows. A small set of triggers—ECHA authorization acceleration, crude price shocks affecting MDI-TDI spreads, and India BIS certification requirement changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
North America Adhesives Market