
 Polyurethane (PU) Adhesives Market | 2026-2036
Polyurethane (PU) Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Adhesives Market Intelligence
The automotive sector's demand for specialized bonding solutions is decoupling from traditional construction adhesive applications. This shift favors suppliers with deep application-specific expertise. Sika AG specializes in high-performance sealants for both construction and automotive clients. Henkel AG & Co. KGaA leverages its broad portfolio across industrial and consumer channels, while Huntsman International LLC competes on the strength of its advanced isocyanate chemistry.
Polyurethane adhesives are polymers formed by the reaction of an isocyanate with a polyol, creating strong yet flexible bonds. Their primary purpose is joining dissimilar materials in demanding industrial applications. Water-based and bio-based formulations are gaining share from solvent-based systems due to stricter environmental standards. Among product types, two-component systems command the market for high-performance structural bonding in automotive and construction sectors.
Regulations such as the EU's REACH and directives from the US EPA strictly control the use of volatile organic compounds and specific isocyanates. In parallel, China's GB standards dictate product safety and performance criteria for adhesives. These frameworks compel innovation in lower-toxicity formulations. Future investment decisions will hinge on developing cost-effective, high-performance bio-based alternatives that comply with evolving chemical regulations.
Market Dynamics
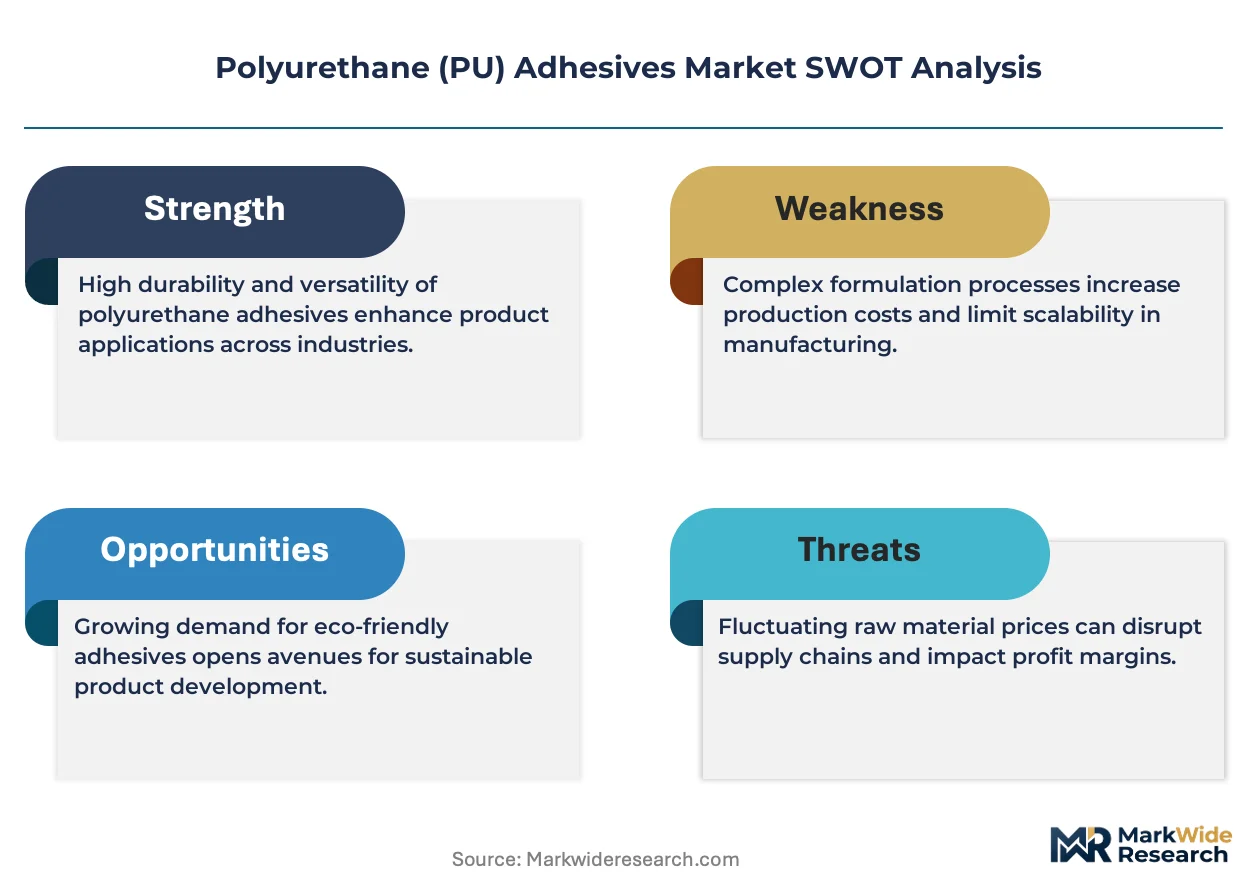
The market's central dynamic is the tension between escalating performance demands from the automotive sector for lightweighting and the stringent regulatory pressure from bodies like the EU's ECHA to reduce isocyanate exposure and VOC content.
Growth Catalysts
- Electric Vehicle Adoption:The shift to electric vehicles creates demand for specialized PU adhesives for bonding battery pack components, joining dissimilar materials like composites and metals, and providing thermal management solutions.
- Energy Efficiency Mandates:Stricter building codes in North America and Europe promoting energy efficiency drive consumption of PU sealants and adhesives for creating airtight building envelopes, sealing windows, and insulating structures.
- Automotive Lightweighting:Vehicle manufacturers are increasingly replacing mechanical fasteners with structural adhesives to bond lightweight materials such as aluminum and carbon fiber composites, reducing overall vehicle weight to improve fuel economy or battery range.
Market Restraints
- Raw Material Volatility:The prices of core feedstocks like MDI and TDI isocyanates, as well as various polyols, are subject to significant volatility tied to petrochemical markets, impacting production costs and margin stability.
- Regulatory Restrictions:The EU's REACH regulation places strict controls on diisocyanates, requiring specialized training for professional users and pushing formulators toward lower-monomer or alternative systems, which adds compliance costs.
- Substitution from Epoxies:In certain ultra-high-performance structural applications requiring extreme temperature or chemical resistance, epoxy-based adhesives present a significant substitution threat, limiting PU's penetration in niche segments.
Strategic Opportunities
- Bio-Based Formulations:Developing and scaling production of adhesives from bio-based polyols and non-petroleum-derived isocyanates opens access to green building projects and consumer goods markets where sustainability certifications command premium pricing.
- Renewable Energy Sector:The wind energy industry presents a major opportunity for high-strength PU adhesives used in bonding the large composite blades of wind turbines, which require exceptional fatigue resistance and durability.
- Medical Device Bonding:Expansion into the medical device market offers a high-value opportunity for specialized, biocompatible PU adhesives for assembling equipment and bonding flexible substrates that meet stringent regulatory approvals from bodies like the FDA.
Industry Challenges
- Formulation Expertise Scarcity:A persistent shortage of polymer chemists and application engineers skilled in developing next-generation water-based, bio-based, or low-monomer PU systems hampers innovation and slows product development cycles.
- Capital-Intensive Production:The manufacturing of isocyanates and specialized polyols requires significant capital investment in complex chemical plants, creating high barriers to entry for new competitors and concentrating supply among a few large producers.
- End-of-Life Recyclability:Addressing the challenge of debonding and recycling cross-linked thermoset PU adhesives at a product's end-of-life is a critical hurdle for achieving circular economy goals, particularly in the automotive and electronics industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Adhesives Market |
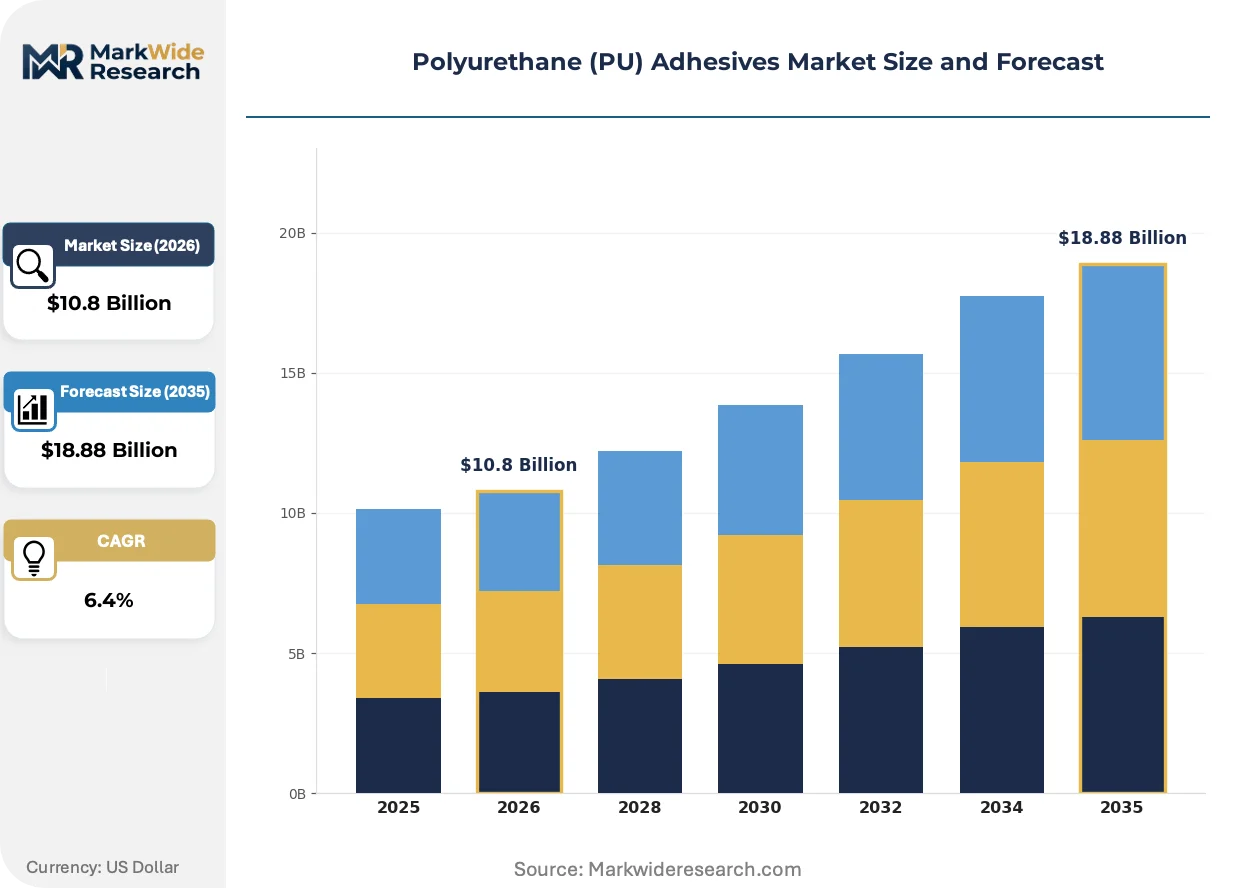
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Component, Two Component, Reactive Hot Melt, Pressure Sensitive End User: Construction, Automotive, Furniture, Footwear Formulation: Water Based, Solvent Based, 100% Solid, Bio-Based Application: Wood Bonding, Metal Bonding, Plastic Bonding, Textile Bonding |
| Companies Covered | 3M, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Arkema, Huntsman International LLC, Dow Chemical Company, BASF, Ashland Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Adhesives Market Strategic Shifts & Innovations
The market is being reshaped by a fundamental pivot towards formulations that deliver enhanced performance while complying with an increasingly complex global web of environmental and health regulations. This dual-focus drives innovation in both chemistry and application technology.
Bio-Based Chemistry
Bio-based PU adhesive technology utilizes polyols derived from renewable sources such as castor oil, soy, or corn to reduce the product's overall carbon footprint. The sustainable packaging and footwear sectors are notable early adopters, responding to consumer preference for eco-friendly products. This green chemistry approach is converging with structural bonding requirements, enabling a new class of high-performance, sustainable adhesives for automotive interiors and construction.
Regulatory-Driven Reformulation
China's GB standards and national "dual carbon" objectives are enforcing strict limits on volatile organic compound (VOC) content in industrial products. This regulatory pressure is accelerating the displacement of solvent-based systems with water-based and 100% solids PU adhesives. The electronics and furniture manufacturing sectors in industrial zones like the Pearl River Delta are most affected, investing in new dispensing equipment to manage these reformulated products.
Application-Specific Expertise
A clear shift in buying behavior sees Original Equipment Manufacturers (OEMs) prioritizing suppliers who offer deep, application-specific engineering support over those competing on price alone. This disrupts traditional distribution channels that focused on volume, favoring direct collaboration between adhesive formulators and end-user design teams. This trend is most pronounced in the aerospace and automotive sectors, where adhesive performance is integral to product safety and structural integrity.
Polyurethane (PU) Adhesives Market Segmentation
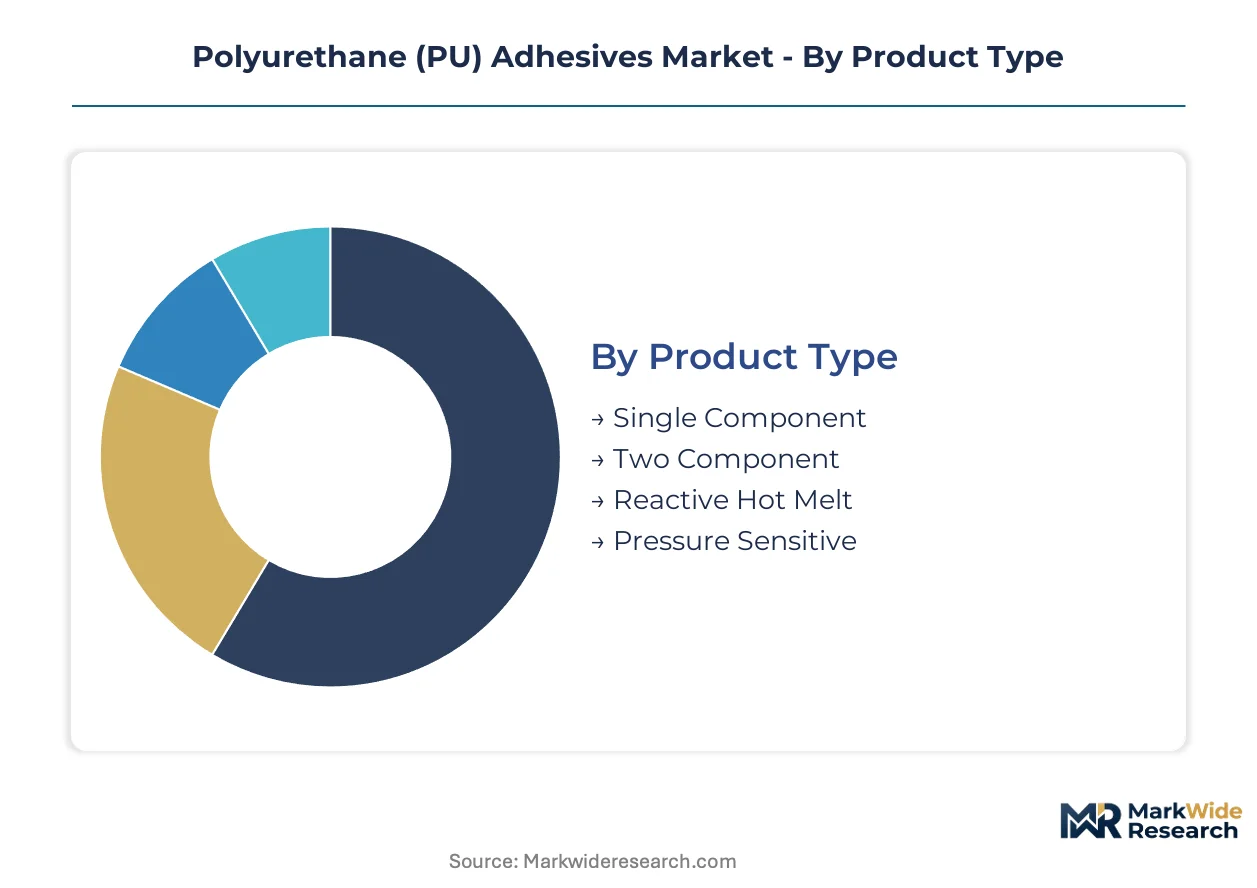
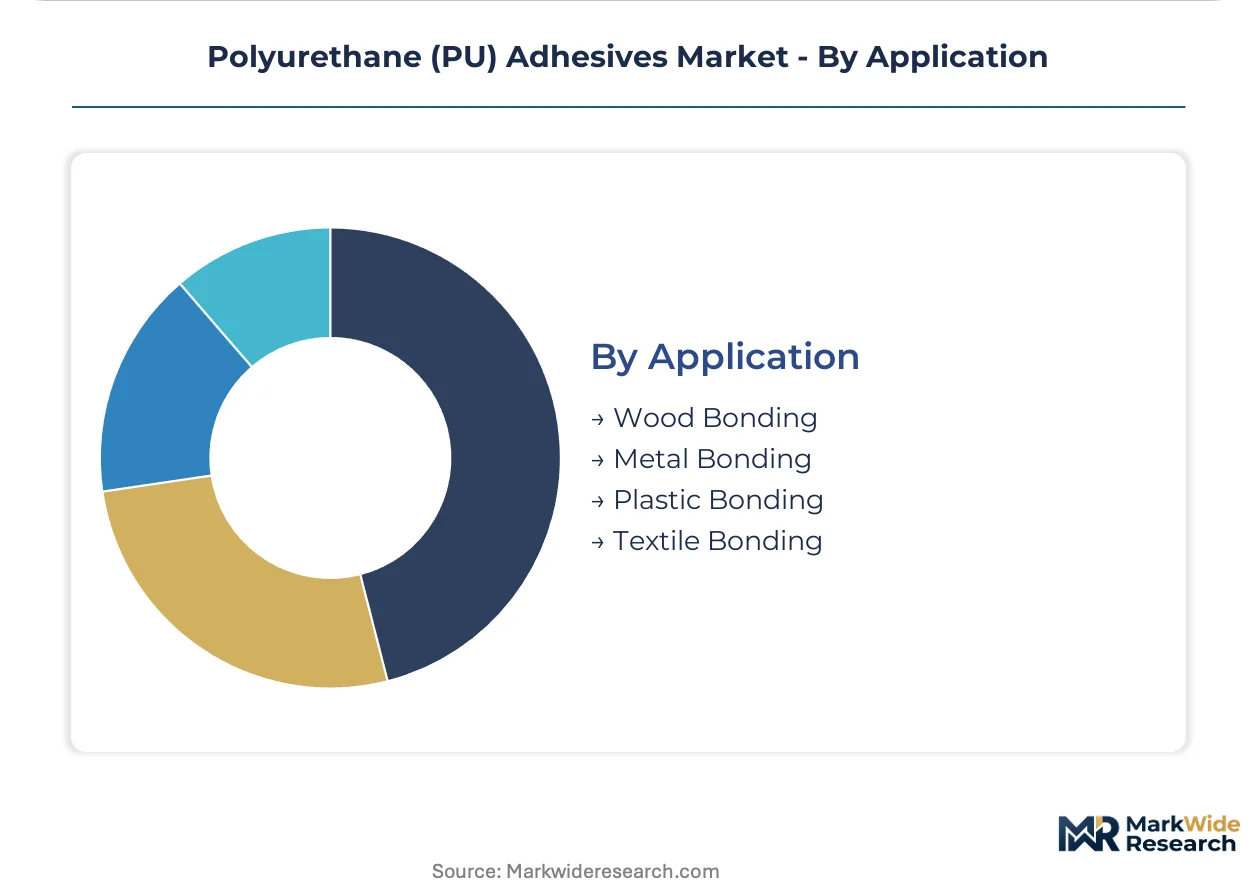
The Polyurethane (PU) Adhesives Market is highly segmented, reflecting the diverse performance requirements and end-use applications across various industries. Understanding these distinct segments is crucial for identifying specific growth opportunities and navigating evolving regulatory landscapes.
Product Type:
This category distinguishes PU adhesives by their chemical composition and curing mechanisms, which directly influence their application and performance characteristics, ranging from standalone systems to embedded formulations.
- Two Component:These systems consist of a polyol and an isocyanate component mixed at the point of application, initiating a chemical reaction that forms a strong, durable bond. Demand is concentrating in the automotive sector for structural bonding of lightweight materials, driven by crash safety and fuel efficiency mandates.
- Reactive Hot Melt:These adhesives solidify upon cooling to provide initial green strength, then undergo a secondary chemical cure, typically with atmospheric moisture, for enhanced final properties. The construction industry is a key adopter for rapid assembly of panels and flooring, optimizing project timelines.
- Single Component:These adhesives cure through exposure to atmospheric moisture or heat, simplifying application processes for general assembly tasks in various manufacturing environments.
- Pressure Sensitive:Adhesives that form a bond when light pressure is applied, offering repositionability and temporary or permanent adhesion in packaging and label applications.
Volume placements concentrate in Two Component; the faster expansion belongs to Reactive Hot Melt.
End User:
The end-user segmentation highlights the primary industries consuming PU adhesives, with demand often driven by specific application needs and material compatibility requirements.
- Automotive:This sector requires specialized PU adhesives for bonding dissimilar lightweight materials, assembly of battery pack components, and interior trim applications. Demand for these solutions is significant in Germany and China, driven by electric vehicle production and stringent safety standards.
- Construction:Utilizes PU sealants and adhesives for creating airtight building envelopes, installing flooring, and laminating structural panels. Stricter energy efficiency mandates in North America and Europe are driving consumption for improved thermal performance.
- Furniture:Employs PU adhesives for wood bonding, upholstery, and foam lamination, valued for their design flexibility and strong, durable bond requirements in various furniture pieces.
- Footwear:Uses PU adhesives for sole attachment and upper assembly in shoe manufacturing, prized for their flexibility, durability, and strong adhesion to diverse materials.
The largest demand originates from Automotive, while Construction shows significant potential.
Formulation:
This segment categorizes PU adhesives based on their chemical composition and environmental profile, reflecting the impact of regulatory pressures and sustainability initiatives.
- Water Based:These formulations use water as a carrier, significantly reducing volatile organic compound (VOC) emissions compared to traditional solvent-based systems. Demand is concentrating in manufacturing zones within China and the EU, driven by GB standards and REACH regulations.
- Bio-Based:Adhesives derived from renewable resources such as castor oil or soy polyols, reducing reliance on petrochemical feedstocks and lowering the product's carbon footprint. Green building projects in Europe and North America are early adopters, responding to sustainability certifications.
- Solvent Based:Traditional formulations offering strong initial tack and fast drying, though facing increasing regulatory scrutiny over VOC content and environmental impact.
- 100% Solid:Adhesives containing no solvents or water, curing by chemical reaction or heat, preferred for high-performance structural applications where zero VOCs are required.
Regulatory shifts are accelerating adoption in Water Based, with Bio-Based gaining traction.
Application:
This category delineates the specific bonding tasks performed by PU adhesives, highlighting their versatility across different material substrates and industrial processes.
- Metal Bonding:Crucial for joining aluminum and steel components in automotive bodies, aerospace structures, and industrial machinery, offering high shear strength and fatigue resistance. Automotive lightweighting initiatives in Japan and the United States are driving this application.
- Plastic Bonding:Essential for assembling interior components, electronic housings, and composite structures, requiring good adhesion to diverse polymer substrates. The electronics sector and electric vehicle interiors represent significant demand for robust plastic bonding.
- Wood Bonding:Utilizes PU adhesives in furniture manufacturing, flooring installation, and construction for strong, moisture-resistant bonds that withstand environmental fluctuations.
- Textile Bonding:Employs PU adhesives for laminating fabrics in apparel, automotive interiors, and technical textiles, providing flexibility, durability, and resistance to washing or abrasion.
High-performance requirements define the landscape for Metal Bonding, as Plastic Bonding addresses specific substrate needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial zones, particularly the Pearl River Delta, drive significant manufacturing and consumption of polyurethane adhesives. This concentration is due to robust domestic demand and the country's position as a global manufacturing hub. The market's diverse applications span automotive, construction, and electronics sectors across these regions.
China
Demand for PU adhesives in China stems from its expansive automotive production and construction boom. Stringent GB standards for VOC content compel manufacturers toward water-based and 100% solids formulations. Industrial zones like the Yangtze River Delta are investing heavily in new dispensing equipment to manage these reformulated products.
Germany
Germany's automotive sector creates substantial demand for high-performance PU adhesives, particularly for electric vehicle battery bonding and lightweighting. The EU's REACH regulation dictates strict controls on diisocyanates, influencing product development. Bavaria and Baden-Württemberg host key automotive OEMs and adhesive formulators, driving innovation in lower-monomer systems.
United States
The United States sees strong demand for PU adhesives in automotive lightweighting and energy-efficient building construction. The US EPA's focus on low-VOC formulations encourages sustainable product development. Manufacturers in states like Michigan and Ohio are adapting their portfolios to meet evolving regulatory and performance requirements.
France
France's construction sector utilizes PU sealants and adhesives for airtight building envelopes, driven by national energy efficiency mandates. EU Green Deal initiatives also promote bio-based adhesive solutions for sustainable projects. The Île-de-France region and its surrounding industrial clusters are adopting these advanced materials for commercial and residential developments.
Polyurethane (PU) Adhesives Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. Large chemical conglomerates and dedicated adhesive manufacturers form distinct strategic archetypes. Competitive moves center on portfolio diversification into sustainable formulations and geographic expansion into high-growth regions.
On the premium-tier vector, Henkel AG & Co. KGaA leverages its broad portfolio across industrial and consumer channels. Sika AG occupies a strong position with its specialization in high-performance sealants for construction and automotive clients. Huntsman International LLC anchors its competitive positioning on advanced isocyanate chemistry, serving demanding industrial applications.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema |
| Huntsman International LLC |
| Dow Chemical Company |
| BASF |
| Ashland Inc |
| Others |
Cost & Logistics Intelligence
Automotive OEMs' concentrated procurement for high-performance polyurethane adhesives often dictates long-term contract-based pricing. This model emphasizes supply stability and technical support over spot market fluctuations.
Pricing Analysis
Short lead times for specialized polyurethane adhesive formulations command a premium, particularly for critical automotive production schedules. The dominant pricing structure is contract-based long-term offtake for high-volume industrial applications. Price differentiation drivers include stringent application-specific performance certifications and the level of integrated technical support provided. Pricing softness stems from raw material volatility, impacting margins for standard construction-grade adhesives. Furniture manufacturers demonstrate high price sensitivity, while automotive OEMs prioritize performance and reliability.
Supply Chain Analysis
Regulatory qualification for specialized isocyanates and polyols significantly gates market entry and influences the available supply base. Geographic supply concentration for core chemical inputs, including MDI and TDI, centers in China, Germany, and the United States. The supply chain relies heavily on petrochemical-derived isocyanates and polyols. Commodity price volatility in these core feedstocks presents a significant structural risk. Distribution for high-performance formulations often involves direct sales to large automotive and construction OEMs, complemented by specialized chemical distributors for broader industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyurethane adhesives market operates as a supply-constrained story, particularly for specialized isocyanates. This limited capacity bottleneck for key feedstocks props up pricing for high-performance formulations.
For Market Incumbents: Cement market leadership by aggressively investing in bio-based R&D and expanding production capacity for low-monomer systems. This counters the threat of stricter EU REACH regulations and potential substitution from epoxy alternatives. Deepen vertical integration into specialized polyol production to secure feedstock supply and control costs. Focus on application engineering expertise to maintain differentiation against generic offerings.
For New Entrants and Emerging Players: Small and medium-sized enterprises in the renewable energy sector represent an underserved buyer archetype. Target high-growth white-space applications like wind turbine blade bonding and medical device assembly. The most penetrable segment is bio-based formulations for green building projects in European markets. A compelling go-to-market angle involves offering integrated application engineering support coupled with sustainability certifications.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers with deep chemical and application expertise. Long-term viability over the next 5-10 years hinges on regulatory compliance and successful sustainable innovation. Target mid-sized specialists in water-based or bio-based chemistry with established intellectual property portfolios. A critical signal to watch is the accelerated adoption rate of bio-based formulations in electric vehicle battery pack assembly.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and meets EU Green Deal sustainability mandates. |
| Capacity Expansion | Addresses supply constraints for specialized isocyanates in China and Germany. |
| Joint Venture | Accelerates development of application-specific solutions for automotive lightweighting. |
| Long-term Supply Agreement | Mitigates raw material volatility for MDI and TDI feedstocks. |
| Product Launch | Introduces next-generation low-VOC formulations compliant with US EPA regulations. |
Research Approach
EU REACH documents, US EPA reports, China GB standards, and industry association publications formed the secondary backbone of this study. Primary interviews with R&D directors at adhesive formulators, procurement leads at automotive OEMs, construction project managers, and polymer chemists provided crucial insights. This research combined bottom-up market sizing with top-down validation, triangulating data points for robust analysis.
Historical trendline analysis informed the projection framework, analyzing market evolution across the analysis window. Segmentation dimensions modeled included product type, end-user industry, formulation, application, and regional regulatory clusters. Compound annual growth rates were derived from a multi-factor regression model incorporating macroeconomic indicators. Forecast inputs included electric vehicle production forecasts and global energy efficiency mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and evolving environmental regulations. Forecasts reflect assumptions regarding technological advancements and regulatory stability. A model refresh is warranted upon material change in major petrochemical feedstock prices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market