
 Middle East & Africa Automotive Adhesives & Sealants Market | 2026-2036
Middle East & Africa Automotive Adhesives & Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Automotive Adhesives & Sealants Market Insights
Market Context with Strategic Players
Multi-sourced procurement of structural bonding chemistries is expanding across North African and Gulf vehicle assembly operations. Henkel AG & Co. KGaA leverages its global formulation portfolio to serve Moroccan OEM lines with epoxy and polyurethane systems tailored to hot-climate durability. Sika AG anchors regional supply through its Dubai-based distribution hub, sustaining just-in-time deliveries to Saudi Arabian vehicle assemblers. Dow competes on silicone technology leadership, particularly for under-the-hood thermal management applications where Gulf ambient temperatures exceed design thresholds.
Technical Definition and Structural Segments
Automotive adhesives and sealants comprise formulated polymer systems—epoxy, polyurethane, silicone, and thermoplastic resins—engineered to bond dissimilar substrates, seal joints against fluids and gases, and dampen structural vibration in vehicle assemblies. These materials replace mechanical fasteners in body-in-white construction, enabling weight reduction while meeting crash-performance specifications. Polyurethane formulations dominate volume demand across body assembly applications where flexibility and impact resistance prove critical. Silicone systems command premium positioning in electrical and exterior sealing, where thermal stability from negative forty degrees Celsius to two hundred degrees Celsius protects sensor housings and lighting modules. Water-based formulations are gaining formulation share as Moroccan and South African plants retrofit spray booths to comply with tightening volatile organic compound limits.
Regulatory Frame and Forward-Looking Close
South Africa's Department of Forestry, Fisheries and the Environment enforces National Ambient Air Quality Standards that restrict solvent emissions from automotive coating and adhesive operations, while Morocco's environmental regulator aligns industrial chemical use with REACH-equivalent substance restrictions through its EU association agreement. Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) is developing technical regulations for automotive material safety that will require adhesive suppliers to submit migration and flammability test data. Stakeholders must monitor which Gulf standardization body moves first on mandatory VOC certification, as that jurisdiction will likely become the template for regional harmonization.
Market Dynamics
Electric vehicle battery pack assembly is rewriting material specifications across Middle East and African automotive plants, forcing adhesive formulators to develop thermally conductive systems that bond dissimilar substrates under extreme Gulf ambient conditions.
Growth Catalysts
- Renault-Stellantis expansion in Morocco:The Tangier-Med manufacturing corridor is pulling structural polyurethane and epoxy systems into North African assembly lines as OEM localization requirements tighten.
- South Africa's Air Quality Act amendments:Stricter VOC emission thresholds under the National Ambient Air Quality Standards are redirecting procurement toward low-solvent silicone and water-based formulations.
- Thermal management demand:Under-the-hood applications in Saudi Arabia and UAE are accelerating consumption of high-temperature silicone sealants as engine compartments face design thresholds exceeding ambient capacity.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with regional oil pricing, compressing margin stability for formulators serving price-sensitive North African assemblers.
- Import dependency for specialty resins:Epoxy hardeners and modified silanes concentrate in European and Asian supply bases, exposing Moroccan and South African plants to currency-driven cost spikes and extended lead times.
- Cure-time limitations in hot climates:Rapid solvent evaporation in Gulf assembly halls degrades open-time windows for conventional adhesives, forcing expensive formulation modifications or climate-controlled application booths.
Strategic Opportunities
- Underpenetrated East African assembly:Kenya and Ethiopia's nascent vehicle kit operations present first-mover positioning for suppliers offering simplified two-component systems with ambient cure profiles.
- EU association agreement alignment:Morocco's REACH-equivalent substance restrictions create regulatory tailwinds for European-certified adhesive suppliers to displace non-compliant regional competitors.
- Battery thermal interface materials:The convergence of phase-change compounds with pressure-sensitive adhesives is opening specification windows for suppliers capable of combined thermal conductivity and structural bonding.
Industry Challenges
- Formulation chemist scarcity:Gulf-based plants struggle to recruit specialists capable of balancing hot-climate durability with VOC compliance across polyurethane, silicone, and hybrid systems.
- SASO pre-market certification timelines:Saudi Arabia's developing technical regulations for automotive material safety are creating extended approval cycles that delay new product introductions by 12-18 months.
- Spray booth retrofit integration:South African and Moroccan facilities face capital-intensive reconfigurations to accommodate water-based adhesive application without disrupting existing solvent-based coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Automotive Adhesives & Sealants Market |
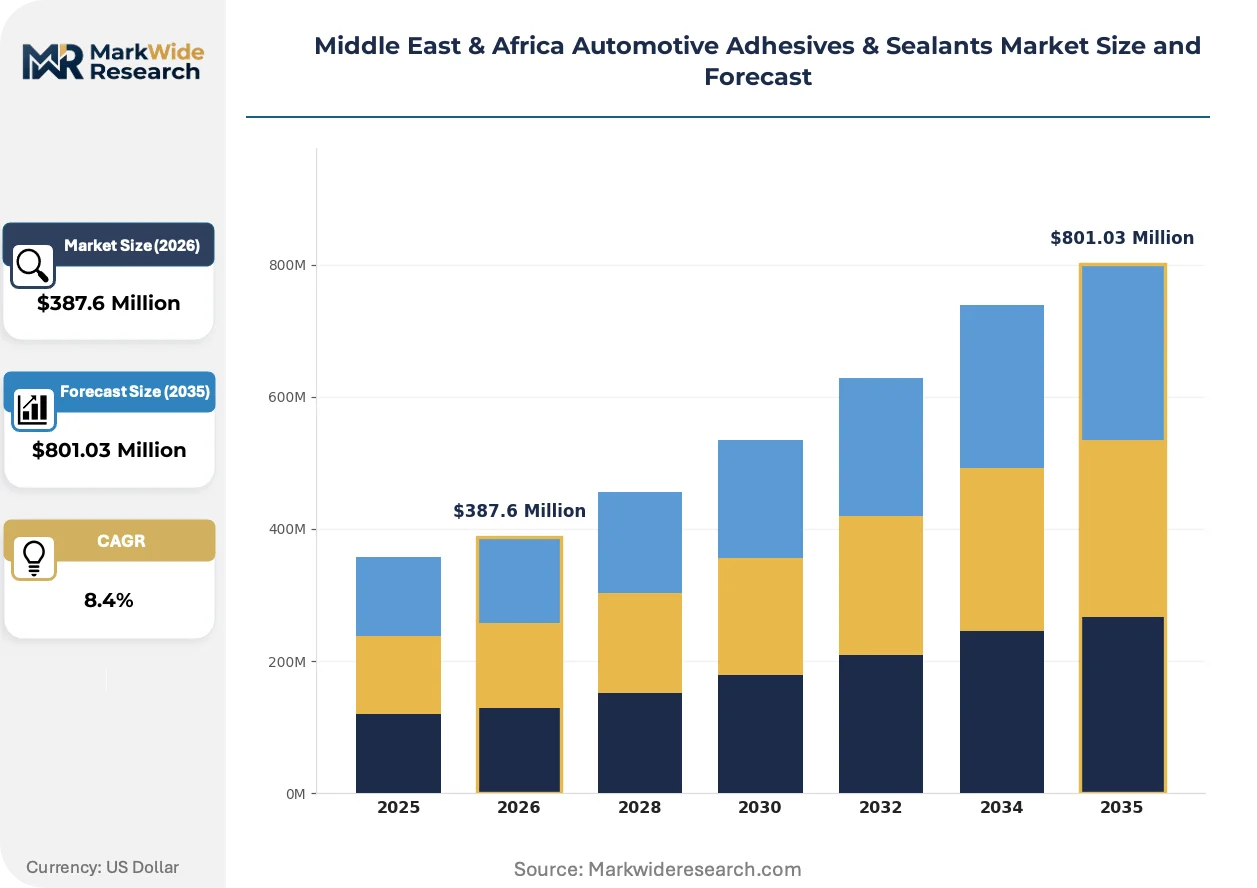
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Thermoplastic Formulation: Single Component, Two Component, Water-Based, Solvent-Based Application: Body Assembly, Interior, Exterior, Electrical End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Dow, PPG Industries, Henkel AG & Co. KGaA, Huntsman International LLC, Arkema Group, 3M, H.B. Fuller Company, DELO Industrie Klebstoffe, Sika AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Automotive Adhesives & Sealants Market Trends and Innovations
Formulation chemistry and application methodology are converging to address thermal stress and regulatory compliance simultaneously across Middle Eastern and African vehicle assembly operations.
Two-component polyurethane systems with built-in thermal conductivity fillers are rewriting specification standards for battery module attachment. Moroccan EV pilot lines are specifying these materials at double the rate of conventional mechanical fastening. The shift is compressing design cycles as engineers eliminate separate thermal interface layers from pack architecture.
South Africa's Department of Forestry, Fisheries and the Environment is enforcing National Ambient Air Quality Standards that cap solvent emissions from adhesive spray operations. Industrial consequence includes mandatory capture-system installation and formulation reformulation toward water-borne or 100%-solid systems. Body shop segments in Gauteng and Eastern Cape provinces are responding fastest, driven by OEM audit pressure and insurance liability exposure.
Just-in-time adhesive delivery contracts are displacing bulk inventory models across Saudi Arabian vehicle assemblers. Tier-1 suppliers are consolidating purchase orders through Dubai-based distribution hubs that maintain temperature-controlled stock near Jeddah and Dammam assembly plants. The reconfiguration is most visible in exterior sealing applications where silicone paste shelf-life constraints previously forced excessive safety stock.
Middle East & Africa Automotive Adhesives & Sealants Market Segmentation
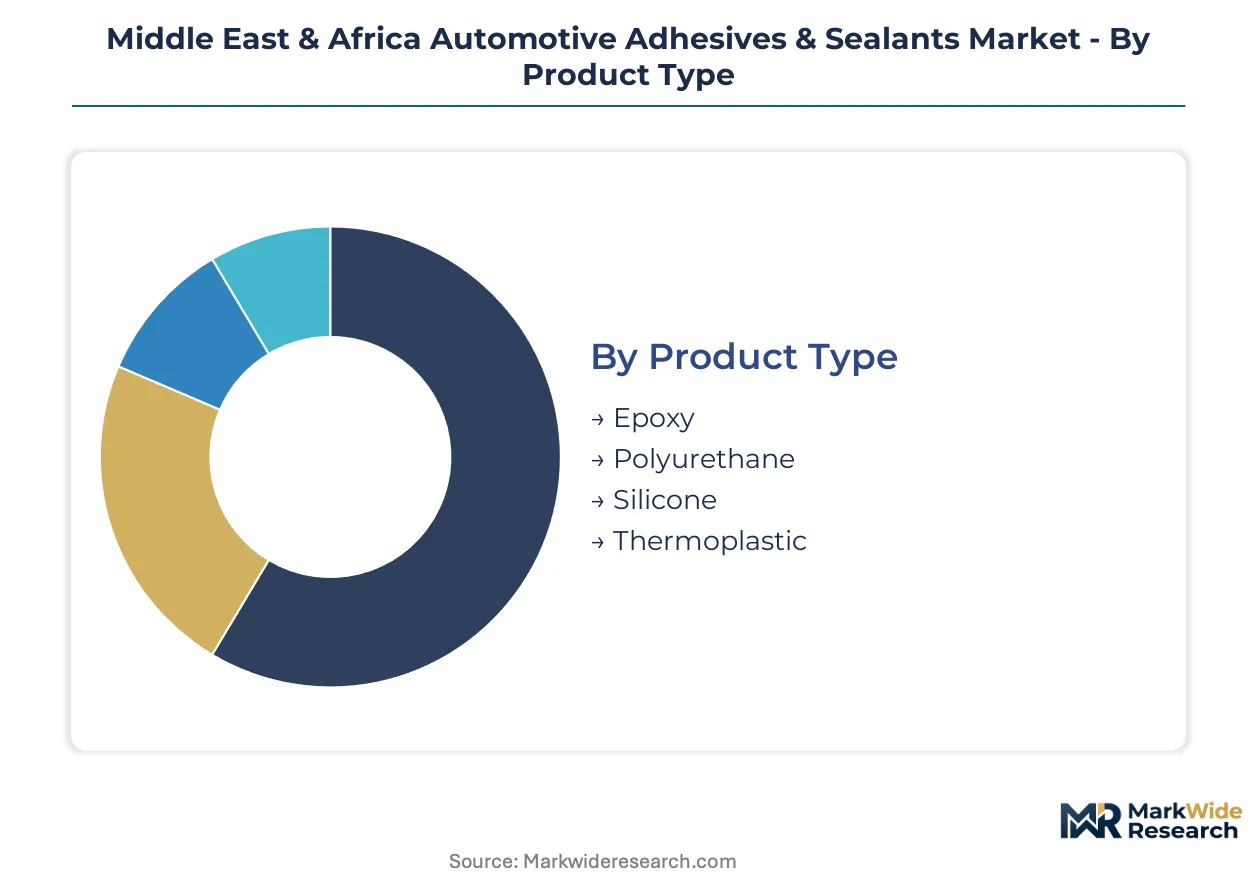
Segmentation reveals how adhesive specifications diverge across Moroccan battery plants, South African retrofit body shops, and Gulf thermal management applications. Understanding these splits exposes where formulation investments concentrate and where procurement patterns are shifting.
Product Type:
Polyurethane and silicone systems anchor volume demand while epoxy commands premium positioning in structural EV applications.
- Polyurethane:Flexible, impact-resistant formulations dominate body-in-white construction across Tangier-Med assembly corridors. Renault and Stellantis operations in Morocco specify these systems for crash-performance compliance where mechanical fasteners once prevailed.
- Silicone:Thermal stability from negative forty to two hundred degrees Celsius protects sensor housings and lighting modules in Saudi Arabian and UAE under-the-hood applications. Gulf ambient temperatures exceeding design thresholds accelerate consumption of high-temperature grades.
- Epoxy:Rigid, high-strength bonding systems serve battery module attachment in emerging EV pilot lines.
- Thermoplastic:Hot-melt formulations enable rapid assembly in interior trim applications where rework flexibility matters.
Today's leader: Polyurethane. Tomorrow's challenger: Silicone.
Formulation:
Component complexity and carrier chemistry determine application speed, VOC compliance, and climate adaptability across regional plants.
- Two Component:Built-in thermal conductivity fillers are rewriting battery module attachment standards. Moroccan EV lines specify these at double the rate of conventional mechanical fastening, compressing design cycles by eliminating separate thermal interface layers.
- Water-Based:Formulation share climbs as South African and Moroccan plants retrofit spray booths to comply with National Ambient Air Quality Standards and REACH-equivalent substance restrictions.
- Single Component:Moisture-cure systems simplify logistics for aftermarket providers serving dispersed African vehicle populations.
- Solvent-Based:Conventional formulations face procurement redirection as South Africa's Air Quality Act amendments tighten emission thresholds.
Water-based systems gain share fastest in audited OEM supply chains; two-component systems climb steepest in EV battery specifications.
Application:
Structural versus sealing functions drive divergent material specifications across vehicle zones.
- Body Assembly:Structural bonding enables weight reduction while meeting crash-performance specifications, concentrating demand in Moroccan OEM lines.
- Electrical:Sensor housing and battery pack sealing command premium silicone grades in Gulf thermal management applications.
- Exterior:Weatherstrip and lighting module sealing consumes silicone paste with shelf-life constraints that force just-in-time delivery models.
- Interior:Acoustic dampening and trim attachment favor polyurethane systems where flexibility and odor control prove critical.
Body assembly captures current volume concentration; electrical applications show the steepest specification upgrade trajectory.
End User:
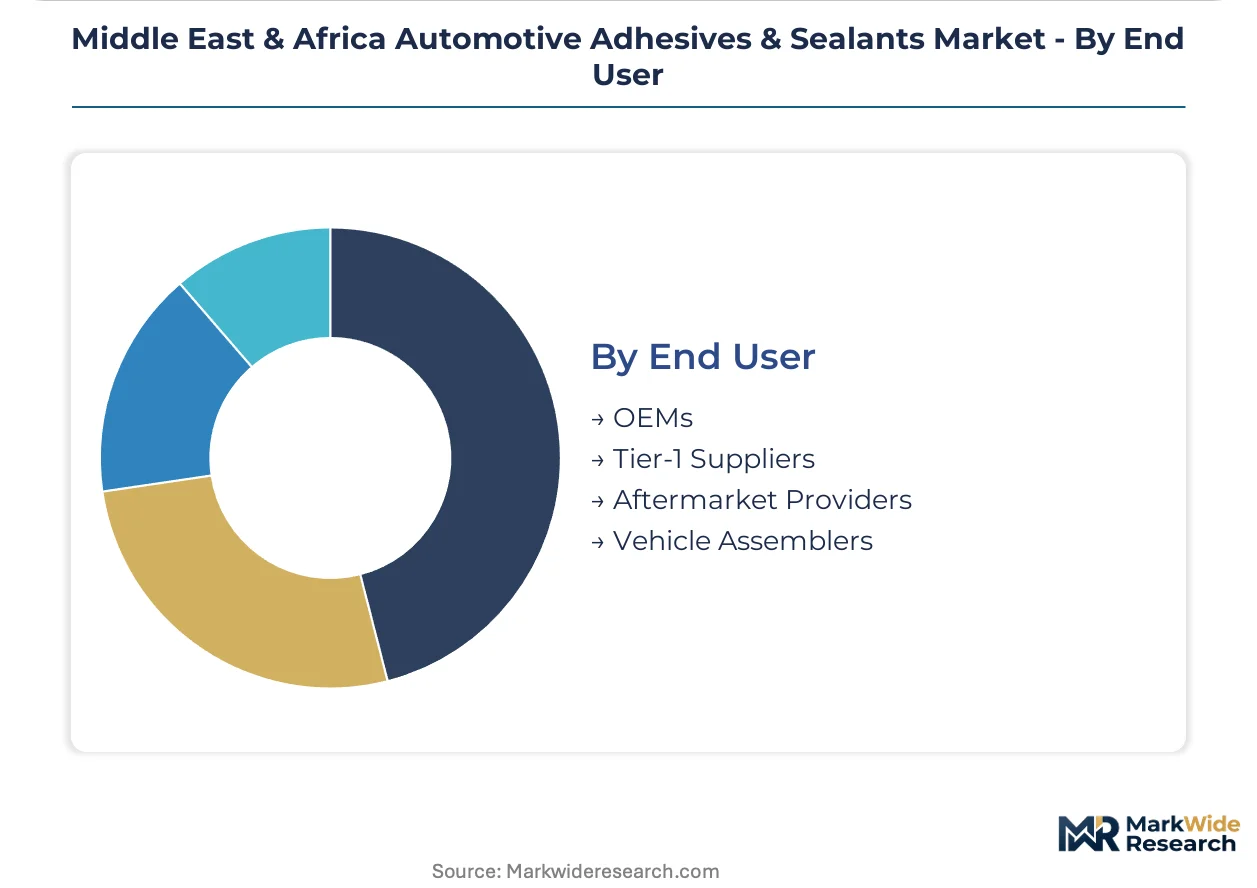
Supply chain position dictates formulation sophistication, certification burden, and inventory model.
- OEMs:Direct specification authority in Moroccan and South African plants drives procurement of European-certified systems aligned with EU association agreement requirements.
- Tier-1 Suppliers:Consolidated purchase orders through Dubai-based distribution hubs sustain just-in-time deliveries to Saudi Arabian vehicle assemblers.
- Vehicle Assemblers:Kit operations in Kenya and Ethiopia present first-mover positioning for simplified two-component systems with ambient cure profiles.
- Aftermarket Providers:Dispersed service networks across Africa favor single-component, moisture-cure formulations with extended shelf stability.
OEMs set specification standards today; tier-1 suppliers are consolidating procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting automotive adhesive procurement toward North African and Gulf assembly corridors where REACH-equivalent compliance costs undercut European manufacturing bases. South Africa's environmental enforcement meanwhile compresses margins for solvent-dependent formulators unable to retrofit operations.
Morocco
Renault and Stellantis expansion at Tangier-Med is pulling structural polyurethane and epoxy systems into North African assembly lines. The country's EU association agreement aligns industrial chemical use with REACH-equivalent substance restrictions, creating procurement preference for European-certified suppliers. The Tangier-Med manufacturing corridor concentrates demand as OEM localization requirements tighten and battery pilot lines specify thermally conductive bonding systems.
Saudi Arabia
SASO's developing technical regulations for automotive material safety are forcing adhesive suppliers to submit migration and flammability test data. The Saudi Standards, Metrology and Quality Organization timelines extend new product approval cycles by 12-18 months. Jeddah and Dammam assembly plants are consolidating purchase orders through Dubai-based distribution hubs that maintain temperature-controlled silicone stock for just-in-time exterior sealing delivery.
South Africa
The Department of Forestry, Fisheries and the Environment enforces National Ambient Air Quality Standards that cap solvent emissions from adhesive spray operations. Air Quality Act amendments redirect procurement toward low-solvent silicone and water-based formulations. Gauteng and Eastern Cape body shop segments retrofit spray booths fastest, driven by OEM audit pressure and insurance liability exposure.
United Arab Emirates
Gulf ambient temperatures exceeding engine compartment design thresholds accelerate consumption of high-temperature silicone sealants for under-the-hood thermal management. Dubai-based distribution hubs anchor regional supply chains sustaining just-in-time deliveries to vehicle assemblers. The emirate's logistics infrastructure enables consolidated procurement models that displace bulk inventory systems.
Kenya
Nascent vehicle kit operations present first-mover positioning for suppliers offering simplified two-component systems with ambient cure profiles. The country's national automotive regulator has not yet implemented mandatory VOC certification, creating a compliance-cost gap versus North African markets. Nairobi and Mombasa assembly zones favor moisture-cure formulations that simplify logistics for dispersed aftermarket service networks.
Middle East & Africa Automotive Adhesives & Sealants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery thermal interface specialization. The market structure consolidates around multinational chemical conglomerates with global formulation portfolios and regional distribution infrastructure. Three archetypes dominate: integrated resin-to-formulation operators, application-technology licensors, and climate-adapted specialty compounders. Competitive moves concentrate on strategic partnerships with battery pack assemblers and spray booth retrofit alliances with South African body shop networks.
Among European-headquartered suppliers, Henkel AG & Co. KGaA and Sika AG exemplify the integrated archetype with regional distribution anchoring. Dow represents North American silicone technology leadership in thermal management applications. These three occupy positions that span formulation development through just-in-time delivery contracting, with each sitting within distinct competitive vectors—Henkel in hot-climate durability systems, Sika in Dubai-hub logistics, and Dow in high-temperature grades.
| Leading Market Players |
|---|
| Dow |
| PPG Industries |
| Henkel AG & Co. KGaA |
| Huntsman International LLC |
| Arkema Group |
| 3M |
| H.B. Fuller Company |
| DELO Industrie Klebstoffe |
| Sika AG |
| Others |
Pricing and Supply Chain Analysis
Polyol and isocyanate feedstock costs cascade through three distinct pricing tiers as Moroccan OEM lines, South African retrofit body shops, and Gulf aftermarket distributors absorb differential pass-through rates from European and Asian resin suppliers.
Pricing Analysis
Input-cost pass-through from petrochemical precursors stratifies procurement across certification-grade tiers. European-certified polyurethane systems command premium positioning against non-compliant regional alternatives, with price differentiation anchored in REACH-equivalent substance documentation and hot-climate durability testing. Pricing pressure stems from currency-driven cost spikes as Moroccan and South African plants import specialty epoxy hardeners and modified silanes. Tier-1 suppliers serving Saudi Arabian assemblers show lowest price sensitivity due to just-in-time delivery premiums, while East African kit operations remain most exposed to spot-market volatility.
Supply Chain Analysis
Morocco's EU association agreement and South Africa's Air Quality Act amendments are redirecting sourcing toward compliant European resin suppliers and local water-based formulation partners. Geographic supply concentration centers on Germany, Belgium, and the Netherlands for specialty epoxy systems, with silicone precursors drawing from South Korean and Japanese chemical conglomerates. Raw material dependencies rest on MDI, polyether polyols, and fumed silica as critical inputs. Single-source vulnerability concentrates in modified silane supply chains feeding Moroccan battery pilot lines. Distribution runs through Dubai-based temperature-controlled hubs sustaining just-in-time deliveries to Jeddah and Dammam assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EV battery thermal interface specifications displace commodity-grade mechanical fastening across North African OEM lines.
For Market Incumbents: Hedge formulation exposure by securing backward integration into water-based resin production ahead of South Africa's National Ambient Air Quality Standards enforcement. Diversify supply footprints beyond European epoxy hardener sources to mitigate currency-driven margin compression. Prioritize certification investment in SASO pre-market approval capabilities to compress 12-18 month timelines threatening new product introductions. For New Entrants and Emerging Players: Tier-1 supplier procurement consolidation creates partnership entry points for specialized thermal conductivity compounders lacking global distribution infrastructure. Target Kenya and Ethiopia's nascent vehicle kit operations with simplified two-component ambient-cure systems before mandatory VOC certification closes the compliance-cost gap with North African markets. Lead with spray booth retrofit alliances in Gauteng and Eastern Cape body shop networks. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity intersects with Gulf-based plant expansion timelines. Long-term viability favors acquirers of climate-adapted specialty compounders with proven hot-climate durability portfolios and existing SASO certification relationships. Battery thermal interface material capabilities represent the signal to watch as specification windows converge phase-change compounds with pressure-sensitive structural bonding.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water-Based Resins | South Africa's Air Quality Act amendments redirect procurement toward compliant local production. |
| SASO Pre-Market Certification Investment | Saudi Arabia's developing technical regulations extend approval cycles without certified submission capabilities. |
| Thermal Interface Material R&D Partnership | Moroccan EV pilot lines specify thermally conductive bonding at double conventional mechanical fastening rates. |
| Dubai Hub Temperature-Controlled Expansion | Silicone paste shelf-life constraints force just-in-time delivery models displacing bulk inventory systems. |
| Spray Booth Retrofit Alliance Formation | Gauteng and Eastern Cape body shops face capital-intensive reconfigurations under OEM audit pressure. |
Research Methodology
Coverage spans North Africa, the Gulf Cooperation Council, and Southern Africa, with primary inputs from each cluster combining structured interviews with adhesive formulators, OEM platform engineers, Tier-1 procurement leads, and aftermarket distribution operators. Secondary validation draws from customs and trade flow data, vehicle production databases, SASO technical regulation drafts, and EU association agreement chemical restriction schedules. Bottom-up demand modeling triangulates against top-down market sizing across polyurethane, silicone, epoxy, and thermoplastic resin categories.
Rate-of-change decomposition separates volume growth from specification-grade mix shifts across the projection horizon. Segmentation dimensions include product chemistry, formulation complexity, vehicle assembly zone, and end-user supply chain position. CAGRs derive from production capacity buildouts at Tangier-Med, EV penetration assumptions in Moroccan and South African fleets, and VOC regulatory enforcement timelines. Industry-specific forecast inputs incorporate battery pack thermal interface material adoption curves and spray booth retrofit investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, SASO regulatory finalization timelines, and currency fluctuation impacts on European resin import costs. Forecasts reflect assumptions around OEM localization requirements and REACH-equivalent alignment trajectories without claiming certainty on enforcement pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Glass Adhesive Market