
 Water-Borne Adhesives Market | 2026-2036
Water-Borne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Borne Adhesives Market Analytics
Buyer concentration among large packaging converters and automotive Tier-1 suppliers is recalibrating procurement leverage across the supply base. Henkel AG & Co. KGaA leverages its European formulation footprint to serve these consolidated accounts with customized acrylic emulsions. H.B. Fuller Company anchors its position through deep relationships with North American woodworking and construction contractors. Dow competes on manufacturing scale, operating integrated polymer supply chains that feed captive water-borne adhesive production.
Water-borne adhesives are aqueous polymer dispersions, typically 40-60% solids content, that bond substrates through film formation as water evaporates or absorbs into porous materials; they serve industries requiring reduced volatile organic compound emissions without sacrificing peel strength or heat resistance. Acrylic emulsions command the largest volume share due to their versatility across paper, film, and textile lamination, though polyurethane dispersions represent the fastest-expanding margin pool as automotive interior specifications tighten. Packaging applications generate the steadiest demand flow, while construction end-use exhibits cyclical sensitivity tied to housing starts and infrastructure spending.
REACH registration requirements and the EU Green Deal's decarbonization targets are restricting solvent-based adhesive formulations in Europe, redirecting formulation investment toward water-borne platforms. EPA VOC regulations in the United States enforce parallel compliance pathways through architectural and industrial maintenance coating rules. India's BIS certification for adhesive products and China's GB standards on indoor air quality add further jurisdictional complexity for multinational suppliers. Stakeholders must monitor evolving substance restriction lists and carbon border adjustment mechanisms to anticipate which chemistries retain market access.
Market Dynamics
Packaging converters and automotive Tier-1 suppliers are consolidating procurement volumes, forcing adhesive formulators to invest in captive emulsion capacity and dedicated technical service teams to defend account relationships.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving candidate list is eliminating solvent-borne chemistries from European furniture and automotive assembly lines, redirecting specification authority toward water-borne platforms.
- Flexible packaging lamination:Food-grade acrylic emulsions are capturing share in snack and beverage pouch sealing as brand owners eliminate VOC emissions from converting operations.
- Polyurethane dispersion chemistry:Heat-activated PUDs for automotive interior bonding are expanding specification wins against hot-melt alternatives in seat assembly and headliner attachment.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and isocyanate price swings compress formulation margins, particularly for small-batch custom emulsion producers without long-term supply contracts.
- Freezer-grade performance gap:Water-borne adhesives exhibit reduced tack and cohesive strength below minus-twenty degrees Celsius, limiting penetration in cold-chain packaging and refrigerated transport applications.
- Application equipment retrofit costs:Converters switching from solvent systems must install forced-air drying tunnels and humidity controls, creating capital friction for mid-tier packaging plants.
Strategic Opportunities
- India's PLI scheme for packaging:Domestic manufacturing incentives are attracting multinational formulators to establish local emulsion plants serving food processing and pharmaceutical blister pack converters.
- Construction panel lamination:Cross-laminated timber and engineered wood producers are specifying low-VOC adhesives for mass timber buildings targeting LEED and WELL certification.
- Bio-based acrylic monomers:Fermentation-derived feedstocks from agricultural waste streams are enabling carbon-negative emulsion claims for sustainability-mandated procurement tenders.
Industry Challenges
- Formulation chemist scarcity:Expertise in colloidal stability and rheology control for water-borne systems is concentrating at a handful of European and North American technical centers, creating hiring bottlenecks for regional producers.
- Multi-jurisdiction certification timelines:Securing food-contact approvals from FDA, EFSA, and China's NMPA simultaneously extends product launch cycles by eighteen to thirty months for global adhesive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Borne Adhesives Market |
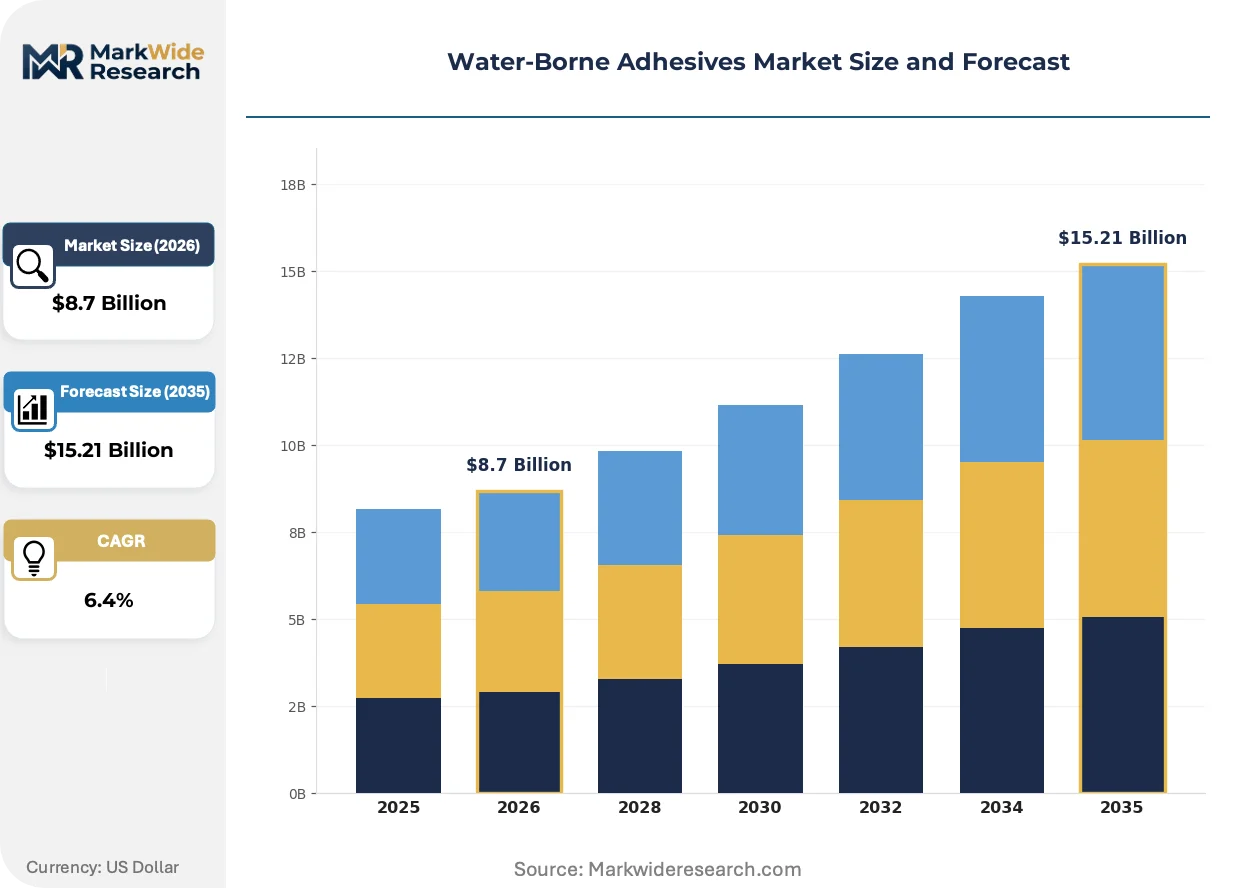
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Vinyl Acetate, Epoxy Application: Construction, Woodworking, Automotive, Packaging Technology: Emulsion, Solution, Spray, Film End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema, 3M, Dow, Sika AG, Ashland, Avery Dennison Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Borne Adhesives Market Evolving Landscape
Formulation science is converging with digital manufacturing controls and bio-based feedstock engineering to redefine performance benchmarks and supply chain accountability across adhesive procurement.
Hybrid acrylic-polyurethane copolymer emulsions are modularizing. These systems combine the cost position of acrylics with the heat and chemical resistance of polyurethanes in single-package formulations. Automotive seating suppliers in Germany and Mexico are qualifying these materials for bonded foam-to-fabric assemblies previously reserved for solvent-borne or two-component systems. The technology is modularizing specification requirements, allowing one adhesive grade to replace multiple legacy products and compressing converter inventory complexity.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants are tightening compliance windows for wood furniture manufacturers in North Carolina and California. The rules mandate seventy-five percent reduction in HAP emissions from coating and adhesive operations by 2027. Medium-density fiberboard laminators are responding by converting spray lines to water-borne roll-coat systems, triggering equipment replacement cycles across the Southeast and Pacific Coast manufacturing corridors.
Consolidated buying desks at multinational packaging groups are unbundling technical service from base material supply. These buyers now contract formulation development separately from volume purchasing, pitting regional emulsion specialists against global suppliers in discrete competitive arenas. The shift is most visible in Germany and the Netherlands, where converters like Mondi and Smurfit Kappa operate centralized procurement functions with dedicated sustainability scorecards that weight carbon intensity above unit price in supplier selection.
Water-Borne Adhesives Market Segmentation
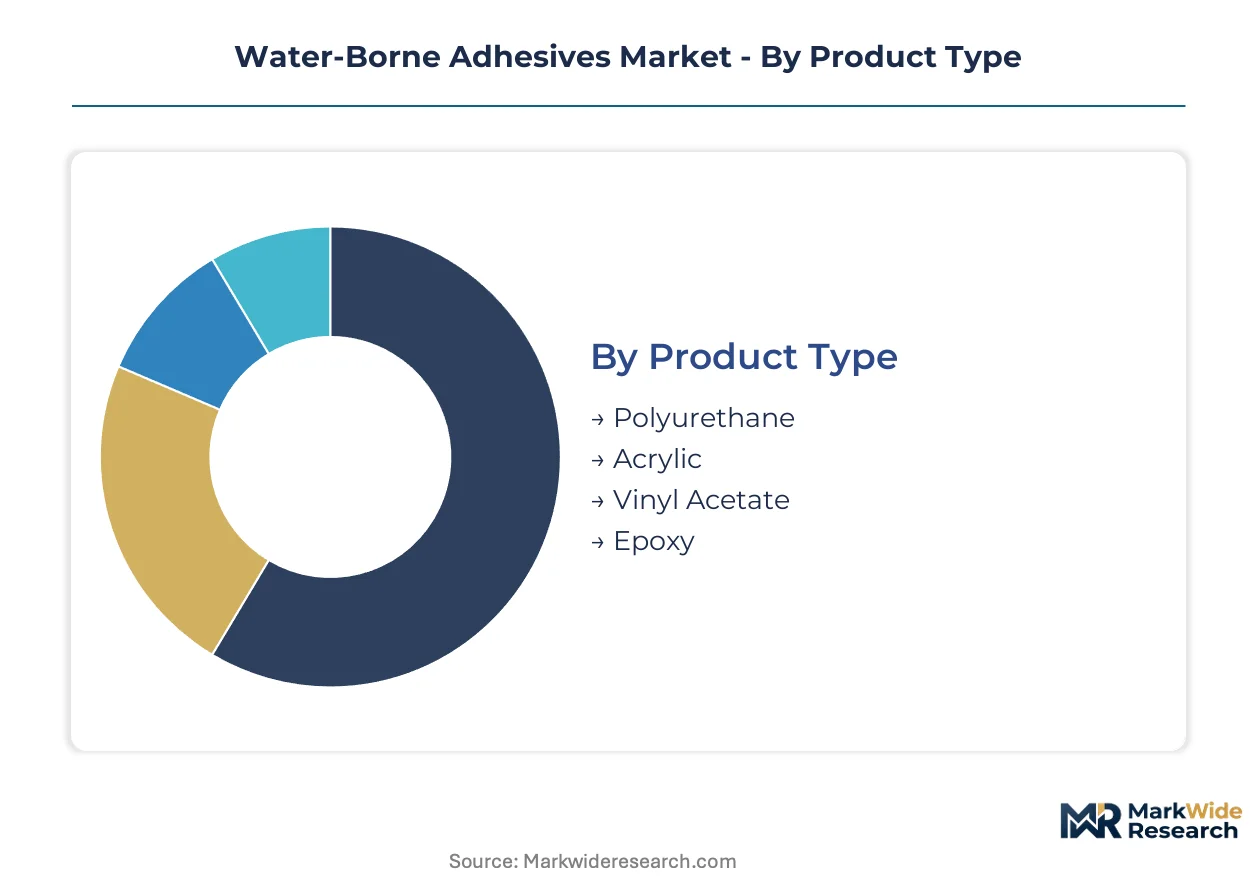
Formulation chemistry and application method dictate procurement specifications across water-borne adhesive categories. Buyers prioritize VOC compliance thresholds, substrate compatibility, and curing equipment requirements when segmenting supplier qualifications.
Product Type:
Price-performance positioning determines specification authority across chemistry platforms.
- Polyurethane:Heat-activated dispersions bond foam-to-fabric assemblies in automotive seating with superior hydrolysis resistance. Tier-1 suppliers in Germany and Mexico specify PUDs for headliner and dashboard lamination as OEM interior durability standards tighten.
- Acrylic:Emulsion polymers with 40-60% solids content dominate paper and film lamination through rapid tack development and clarity. Packaging converters in the Netherlands and Germany favor food-grade acrylics for snack pouch sealing under EFSA compliance pathways.
- Vinyl Acetate:Cost-effective homopolymers and copolymers serve porous substrate bonding in woodworking and paper packaging applications.
- Epoxy:Two-component water-borne systems deliver structural adhesion for construction panel lamination and engineered wood products.
Acrylic leads on scale; polyurethane leads on momentum.
Application:
End-use cyclicality and regulatory exposure shape volume allocation decisions.
- Packaging:Flexible lamination and carton sealing generate consistent demand flow from food processing and pharmaceutical blister pack operations. REACH substance restrictions accelerate conversion from solvent systems in European converting corridors.
- Automotive:Interior bonding specifications for seats, headliners, and trim panels demand heat resistance and fogging compliance. German OEMs phase in PUD-based assemblies under EU Green Deal decarbonization mandates.
- Construction:Cross-laminated timber and engineered wood panel lamination exhibit cyclical sensitivity tied to housing starts and infrastructure spending cycles.
- Woodworking:Furniture manufacturers in North Carolina and California retrofit spray lines to roll-coat water-borne systems under EPA NESHAP compliance deadlines.
Packaging commands volume stability; automotive commands specification premium.
Technology:
Application equipment compatibility constrains technology selection at the plant level.
- Emulsion:Aqueous polymer dispersions with controlled particle size distribution enable spray, roll, and curtain coating methods. Forced-air drying tunnels represent the dominant curing infrastructure across European and North American converting plants.
- Solution:Fully dissolved polymer systems penetrate porous substrates in woodworking applications requiring deep fiber saturation.
- Spray:Atomized application methods suit complex geometries in automotive interior assembly and furniture manufacturing.
- Film:Pre-cast adhesive layers activate under heat and pressure for precision lamination in electronics and medical device assembly.
Emulsion dominates installed base; film gains share in precision bonding segments.
End User:
Procurement scale and technical service requirements differentiate buyer categories.
- Manufacturers:OEMs and Tier-1 suppliers in automotive and furniture sectors negotiate formulation customization with dedicated technical service teams. Consolidated buying desks at multinational packaging groups unbundle R&D contracts from volume purchasing.
- Contractors:Construction and installation operators prioritize ready-to-use formulations with simplified application protocols and ambient cure conditions.
- Distributors:Regional stockists buffer small-batch demand from mid-tier converters lacking direct supplier relationships.
- Retailers:Consumer-facing channels supply DIY woodworking and home repair segments with pre-packaged emulsion products.
Manufacturers concentrate procurement leverage; contractors concentrate volume fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium specification authority for automotive PUDs while China scales emulsion capacity to serve domestic packaging converters. India attracts multinational formulators through manufacturing incentives. The United States enforces parallel VOC reduction mandates across furniture and construction sectors.
Germany
Automotive OEMs in Stuttgart and Munich specify heat-activated polyurethane dispersions for interior bonding assemblies. REACH substance restrictions under ECHA eliminate solvent-borne alternatives from Tier-1 supplier qualification lists. The Baden-Württemberg automotive cluster drives formulation customization contracts with dedicated technical service teams.
China
Domestic packaging converters in the Yangtze River Delta expand food-grade acrylic emulsion procurement for flexible lamination. GB standards on indoor air quality and MEE enforcement tighten compliance windows for adhesive imports. Shanghai-based emulsion plants scale captive polymer supply chains to serve regional converting corridors.
United States
Wood furniture manufacturers in North Carolina and California retrofit spray lines to water-borne roll-coat systems. EPA NESHAP mandates seventy-five percent HAP emission reductions from coating and adhesive operations by 2027. The Southeast manufacturing corridor triggers equipment replacement cycles among medium-density fiberboard laminators.
India
Food processing and pharmaceutical blister pack converters expand procurement of low-VOC compliant formulations. The PLI scheme for packaging attracts multinational formulators to establish local emulsion plants. Maharashtra and Gujarat host emerging technical centers serving domestic converting demand with reduced import dependency.
Netherlands
Consolidated buying desks at multinational packaging groups unbundle technical service from base material supply. EFSA compliance pathways for food-contact adhesives concentrate specification authority among qualified suppliers. The Randstad region hosts centralized procurement functions with sustainability scorecards weighting carbon intensity above unit price.
Water-Borne Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry platforms. The market structure concentrates specification authority among three to five integrated suppliers with captive polymer supply chains and regional emulsion plants. Strategic archetypes include diversified chemical conglomerates with adhesive divisions, pure-play adhesive specialists with formulation expertise, and integrated polymer producers with downstream emulsion capacity. Competitive moves center on captive capacity expansion in high-growth jurisdictions and technology licensing partnerships for hybrid copolymer platforms.
Within the diversified conglomerate tier, Henkel AG & Co. KGaA and Dow exemplify scale-driven positioning through integrated supply chains and regional manufacturing footprints. H.B. Fuller Company represents the pure-play specialist archetype with concentrated formulation expertise. These three entities anchor the competitive structure by occupying positions that span from upstream polymer control through downstream technical service delivery.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema |
| 3M |
| Dow |
| Sika AG |
| Ashland |
| Avery Dennison Corporation |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Colloidal stability expertise concentration in Germany's Baden-Württemberg cluster feeds directly into pricing-tier spreads across European emulsion markets, with formulation chemist scarcity widening the gap between premium customized acrylics and commodity vinyl acetate alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for food-grade acrylic emulsions. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant custom formulations from mass-market vinyl acetate copolymers. Cost compression in standard-grade acrylics is intensifying because domestic Chinese producers are scaling captive polymer supply chains. Mid-tier packaging converters in India exhibit highest price sensitivity; German automotive Tier-1 suppliers show least sensitivity due to specification lock-in for PUD-based interior bonding.
Supply Chain Analysis
Acrylic acid and isocyanate supply rests on integrated petrochemical producers in Germany, the United States, and Saudi Arabia. Raw material dependencies include propylene derivatives, MDI/TDI precursors, and specialty surfactants for emulsion stabilization. Single-source vulnerability concentrates around isocyanate feedstocks following European capacity rationalizations. Distribution runs through regional stockists buffering small-batch demand from mid-tier converters lacking direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-borne adhesives function as a stable compounder anchored by regulatory mandates that permanently displace solvent-borne alternatives across automotive and packaging end-uses.
For Market Incumbents: Acquire captive emulsion capacity in India and Southeast Asia to preempt PLI-scheme localization requirements. Consolidate formulation chemist talent pools in Germany and North America before regional producers exhaust hiring pipelines. Threat from bio-based acrylic startups in fermentation-derived feedstocks demands accelerated R&D partnerships with agricultural waste processors. For New Entrants and Emerging Players: Regional woodworking contractors in the United States Southeast represent an underserved buyer archetype requiring ready-to-use water-borne formulations with simplified roll-coat protocols. Cold-chain packaging converters seeking freezer-grade performance gaps offer specification white-space. Go-to-market leverage hinges on equipment retrofit financing bundled with adhesive supply contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play emulsion specialists lacking backward integration into polymer supply. Five-to-ten-year viability favors suppliers with REACH-registered portfolios and automotive PUD qualification tracks. Signal to watch: carbon border adjustment mechanism implementation tightening cost structures for imported solvent-borne alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Local emulsion plants in Maharashtra and Gujarat reduce import dependency for Indian pharmaceutical blister pack converters. |
| Backward Integration | Captive acrylic acid production insulates formulators from propylene derivative volatility in European supply corridors. |
| Green Manufacturing Transition | Fermentation-derived monomers from agricultural waste streams enable carbon-negative claims for sustainability-mandated tenders. |
| Long-term Supply Agreement | Fixed-volume contracts with German automotive OEMs secure PUD specification wins across seat assembly and headliner attachment. |
| Joint Venture | Technology licensing partnerships for hybrid acrylic-polyurethane copolymers accelerate automotive qualification timelines in Mexico. |
Research Methodology
Coverage spans Germany, China, the United States, India, and the Netherlands, with primary inputs from each jurisdiction combining formulation R&D directors, procurement leads at multinational packaging groups, automotive Tier-1 supplier technical managers, and regional emulsion plant operators. Secondary validation draws from ECHA substance restriction updates, EPA NESHAP compliance filings, customs trade data for acrylic acid and isocyanate flows, and SEC disclosures from integrated chemical conglomerates. Bottom-up emulsion volume estimates triangulate against top-down adhesive market allocations.
Granularity-level modeling disaggregates volume and value across chemistry platforms, application methods, and end-use industries at the country level. Segmentation dimensions include formulation chemistry, curing technology, and regional regulatory cluster intensity. CAGRs derive from regression-based trajectory fitting anchored to disclosed capacity expansion timelines and OEM specification phase-in schedules. Forecast inputs incorporate REACH candidate list evolution pace and automotive interior durability standard tightening rates.
Underlying measurement precision varies by segment; automotive PUD specifications carry tighter precision than commodity woodworking applications due to concentrated buyer transparency. Forecasts reflect assumptions on regulatory enforcement consistency and feedstock price regime stability. A small set of triggers warrants ongoing watch: ECHA substance restriction list acceleration, carbon border adjustment mechanism rollout timing, and bio-based acrylic monomer cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
France Adhesives Market