
 Global Bio Based Polyurethane Market | 2026-2036
Global Bio Based Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Based Polyurethane Market Intelligence
The market’s historical dependence on the construction sector for insulation is decoupling as the automotive industry's demand for sustainable interior components and lightweight foams increases. BASF SE leverages its deep expertise in chemical synthesis to develop novel bio-polyols. Covestro AG specializes in high-performance materials for automotive and electronics applications. Meanwhile, Huntsman International LLC competes with a diverse portfolio of polyurethane systems for various end uses.
Bio-based polyurethane is a polymer class where a portion of the polyol precursor is derived from renewable feedstocks such as vegetable oils, sucrose, or lignin. These materials react with isocyanates to form polymers that reduce the carbon footprint compared to conventional petroleum-based polyurethane. Among product types, flexible and rigid foams account for the majority of consumption, primarily for cushioning and insulation. The footwear and furniture end-use industries exhibit strong demand, driven by consumer preferences for sustainable products.
Regulatory frameworks are pivotal in shaping material substitution trends. The European Union's REACH regulation and directives on bio-based content influence product formulation and market access in Europe. In the United States, EPA standards on volatile organic compounds (VOCs) encourage the use of waterborne or high-solids formulations. The ability to secure a consistent and economically viable supply of bio-based raw materials will determine long-term competitive advantage.
Market Dynamics
The market's trajectory is defined by a structural shift away from petroleum-based inputs, driven by regulatory pressure for decarbonization and corporate sustainability goals. This transition is most pronounced in consumer-facing industries where brand value is increasingly tied to environmental credentials.
Growth Catalysts
- Regulatory Frameworks:The European Union's Green Deal and circular economy action plan create strong incentives for adopting renewable materials, compelling manufacturers in sectors like automotive and construction to seek out bio-based polyurethane alternatives.
- Footwear Industry Demand:Major footwear brands are aggressively incorporating bio-based polyurethane into midsoles, uppers, and insoles to meet consumer demand for sustainable products, creating a high-volume demand channel.
- Bio-Polyol Innovation:Advances in chemical processes for converting vegetable oils, sucrose, and lignin into polyols are improving performance characteristics and cost-competitiveness, broadening the application scope for bio-based polyurethane formulations.
Market Restraints
- Cost Competitiveness:Bio-based polyurethane often carries a price premium compared to its conventional petroleum-derived counterparts, a barrier for adoption in price-sensitive applications, compounded by the price volatility of agricultural feedstocks.
- Performance Parity:While performance has improved, some bio-based formulations still exhibit limitations in mechanical properties like durability and thermal resistance, restricting their use in demanding industrial and automotive applications.
- Feedstock Supply Chain:The supply chain for bio-based feedstocks like vegetable oils is subject to agricultural variables, including weather and competition with food production, creating potential for supply inconsistency and price fluctuations.
Strategic Opportunities
- Medical Device Applications:The development of high-performance bio-based thermoplastic polyurethane (TPU) opens opportunities in the medical sector for applications like catheters and device housings, where biocompatibility and a lower carbon footprint are valued.
- Expansion in Asian Markets:Underpenetrated markets in Southeast Asia, particularly in Vietnam and Indonesia, represent a significant growth opportunity as their manufacturing sectors for footwear, furniture, and electronics expand.
- Government Incentives:Policy mechanisms like the US Inflation Reduction Act (IRA) offer tax credits and support for domestic production of bio-based materials, creating a favorable investment climate for scaling up bio-polyurethane manufacturing.
Industry Challenges
- Standardization and Certification:A lack of globally harmonized standards for measuring and verifying bio-content complicates marketing claims and international trade, leading to consumer confusion and creating compliance hurdles for producers.
- Scale-Up Capital Requirements:Constructing and commissioning new biorefineries and polymer production facilities capable of producing bio-based polyols and isocyanates at an industrial scale demands significant capital investment.
- Production Line Integration:Adapting existing polyurethane manufacturing infrastructure to process bio-based precursors can present technical challenges, requiring process adjustments and potential equipment retrofits to maintain quality and output efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Based Polyurethane Market |
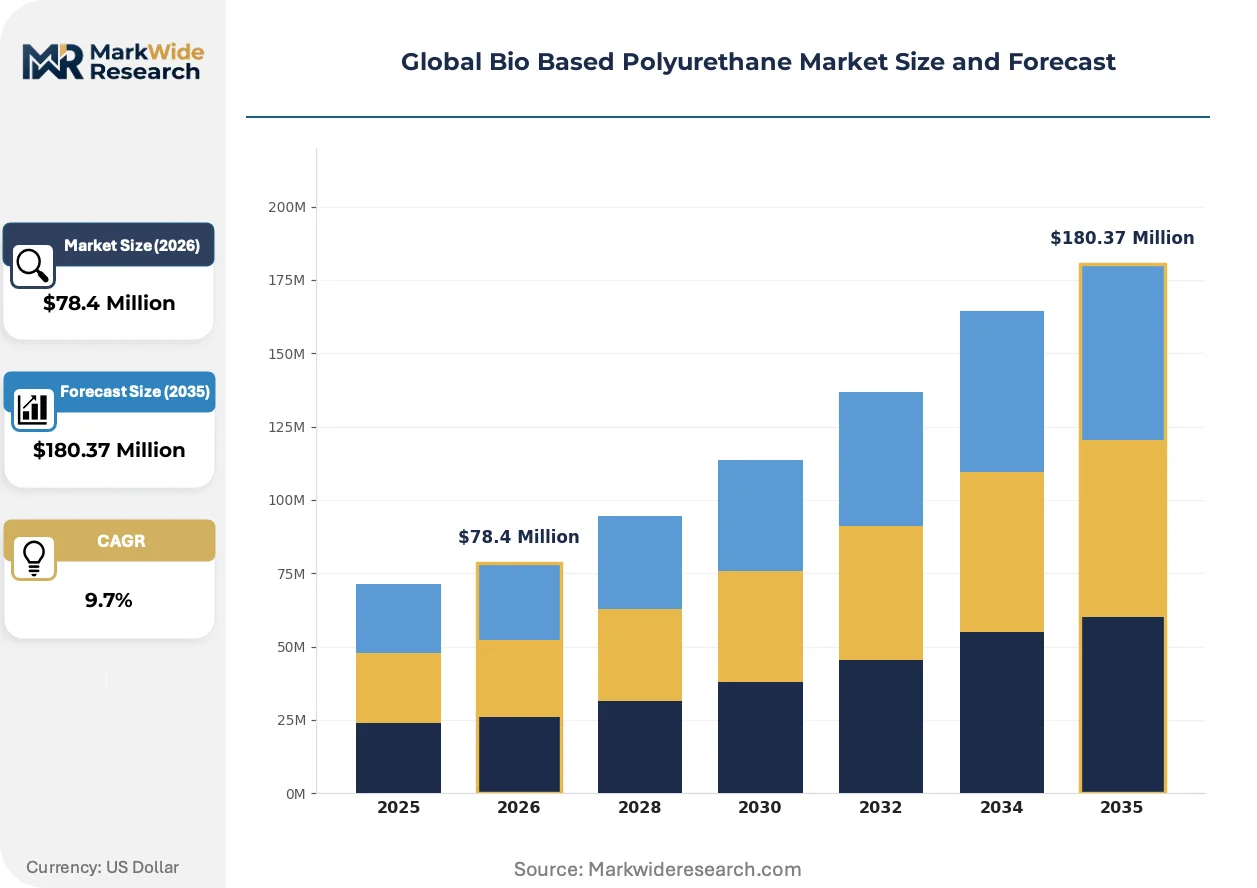
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $180.37 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives End Use Industry: Automotive, Construction, Furniture, Footwear Formulation Type: Waterborne, Solvent-borne, High-solids, 100% Solid Application: Insulation, Sealants, Elastomers, Composites |
| Companies Covered | Huntsman International LLC, Cargill, Incorporated, BASF SE, Wanhua Chemical Group Co., Ltd., Mitsui Chemicals, Inc., Covestro AG, The Lubrizol Corporation, RAMPF Holding GmbH & Co. KG, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Based Polyurethane Market Strategic Shifts & Innovations
The convergence of material science and circular economy principles is actively defining the next generation of bio-based polyurethane products. Innovation is focused on diversifying feedstock sources beyond primary crops and designing materials for end-of-life recyclability, moving the industry toward closed-loop systems.
The utilization of non-food feedstocks, particularly lignin derived from forestry and paper pulp waste, is a key technological shift. Automotive and construction material specifiers are evaluating these second-generation polyols for rigid foam and composite applications. The valorization of this abundant biomass waste stream is rewriting the economic viability of integrated biorefineries by creating a high-value co-product.
Europe's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory driver. The directive mandates that large companies provide extensive, audited disclosures on their supply chain's environmental impact, including material sourcing. This requirement directly impacts automotive, furniture, and electronics OEMs, compelling them to demand transparent and verifiable bio-content data from their polyurethane suppliers.
A notable behavioral shift is the move from simple material substitution toward procurement based on comprehensive Life Cycle Assessments (LCAs). Commodity-focused suppliers are being challenged by integrated producers who can provide transparent data on carbon footprint, water usage, and end-of-life options. This trend is most advanced in the European contract furniture and consumer electronics sectors, where brands leverage sustainability metrics as a core marketing differentiator.
Global Bio Based Polyurethane Market Segmentation
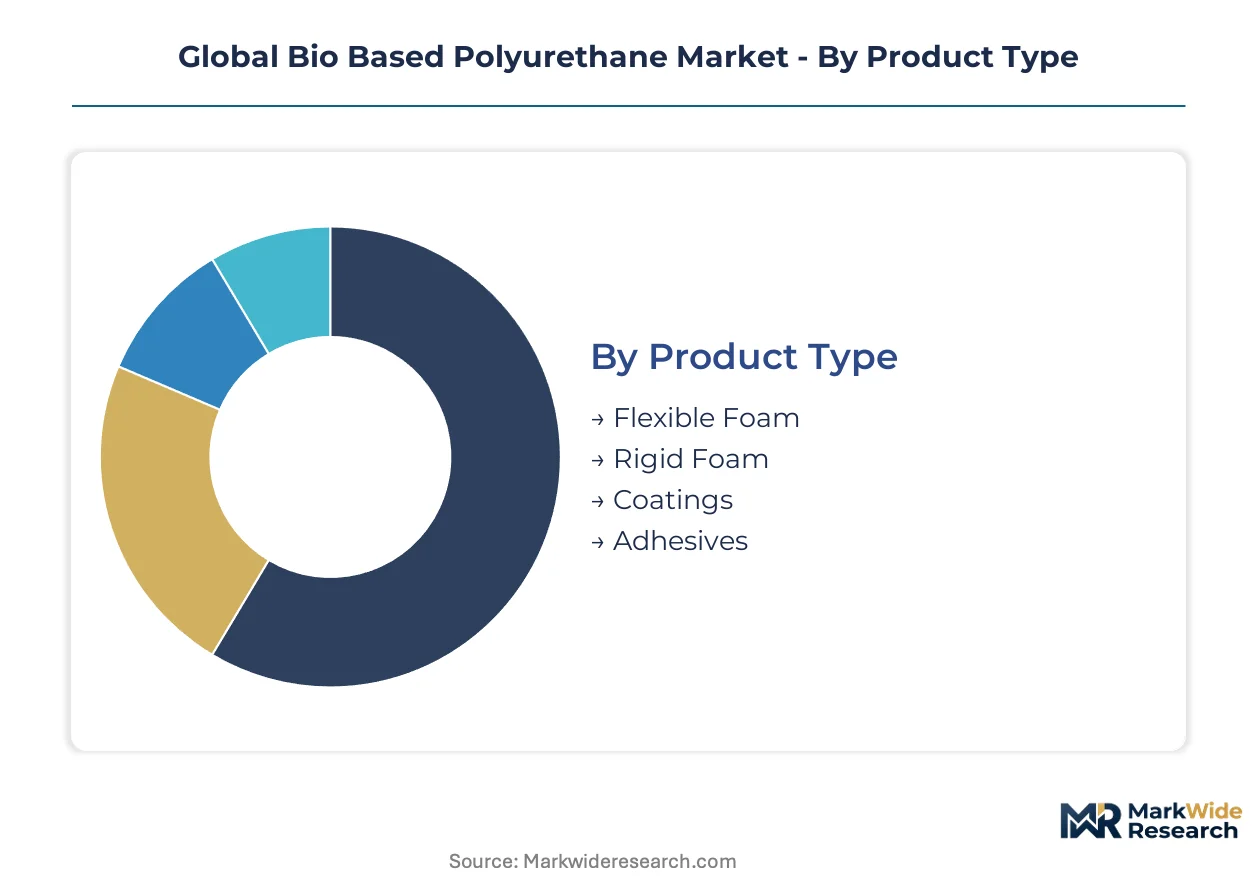
The global bio-based polyurethane market exhibits diverse segmentation reflecting varied material properties and end-use requirements. Understanding these distinct segments helps identify specific growth pockets and competitive landscapes. Each category addresses unique performance demands and regulatory compliance challenges across different industries.
Product Type:
Product type segmentation often dictates specific certification burdens, particularly for materials used in consumer goods and construction. Regulatory bodies like the EU Green Deal directly influence material choices for these applications.
- Flexible Foam:These low-density, open-cell polymers offer excellent cushioning and shock absorption properties. Demand concentrates in the furniture and footwear industries, driven by consumer preferences for comfort and sustainability in European markets.
- Rigid Foam:Characterized by high compressive strength and thermal insulation capabilities, these closed-cell structures are crucial for energy efficiency. The construction sector in Germany and automotive lightweighting initiatives increasingly specify rigid bio-based foams.
- Coatings:Bio-based polyurethane coatings provide durable, protective layers for surfaces, reducing VOC emissions.
- Adhesives:These formulations offer strong bonding capabilities with reduced environmental impact for various assembly applications.
Leading the category by volume: Flexible Foam. Growing fastest: Rigid Foam.
End Use Industry:
Segmentation by end-use industry highlights the distinct customer requirements and purchasing criteria that drive material selection. Each sector presents unique challenges for integrating bio-based solutions.
- Footwear:This industry rapidly adopts bio-based polyurethane for midsoles, outsoles, and uppers, directly responding to strong consumer demand for sustainable products. Major brands actively seek materials that enhance their environmental credentials across global supply chains.
- Automotive:Bio-based polyurethanes find application in interior components, seating, and lightweight foams, supporting vehicle manufacturers' decarbonization goals. German automotive OEMs are particularly focused on incorporating these materials to meet stringent EU regulations.
- Construction:Bio-based materials are increasingly used for insulation panels and sealants in buildings, targeting energy efficiency improvements.
- Furniture:This sector utilizes bio-based foams for cushioning and upholstery, driven by demand for eco-friendly home furnishings.
Footwear and automotive applications collectively define the market’s expansion trajectory.
Formulation Type:
Formulation type directly impacts processing characteristics and overall cost-effectiveness for manufacturers. The balance between performance, price, and environmental compliance drives choices in this segment.
- Waterborne:These formulations use water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions. US EPA standards strongly encourage their use, making them preferred in coatings and adhesives for indoor applications.
- High-solids:Characterized by a high percentage of non-volatile components, these formulations minimize solvent content and associated emissions. They offer robust performance and efficiency, particularly in industrial coatings and sealants.
- Solvent-borne:These traditional formulations utilize organic solvents, offering specific performance advantages but facing increasing regulatory scrutiny.
- 100% Solid:These solvent-free systems minimize environmental impact, providing durable and high-performance solutions for specialized applications.
The market exhibits a clear preference for waterborne and high-solids formulations.
Application:
The application segment reflects how bio-based polyurethanes are functionally deployed, often determining the specific performance criteria and supply chain requirements. Each application demands tailored material properties.
- Insulation:Bio-based polyurethane rigid foams provide superior thermal resistance, crucial for energy-efficient buildings and cold chain logistics. The European construction sector is a primary demand driver, responding to strict energy performance directives.
- Sealants:These materials offer excellent adhesion and flexibility, providing critical environmental barriers in construction and automotive assemblies. REACH regulations influence the formulation of bio-based sealants across Europe.
- Elastomers:Bio-based elastomers provide flexibility and durability for parts requiring resilience, such as wheels and technical components.
- Composites:Bio-based polyurethanes are integrated into composite structures, enhancing sustainability in lightweight panels and structural elements.
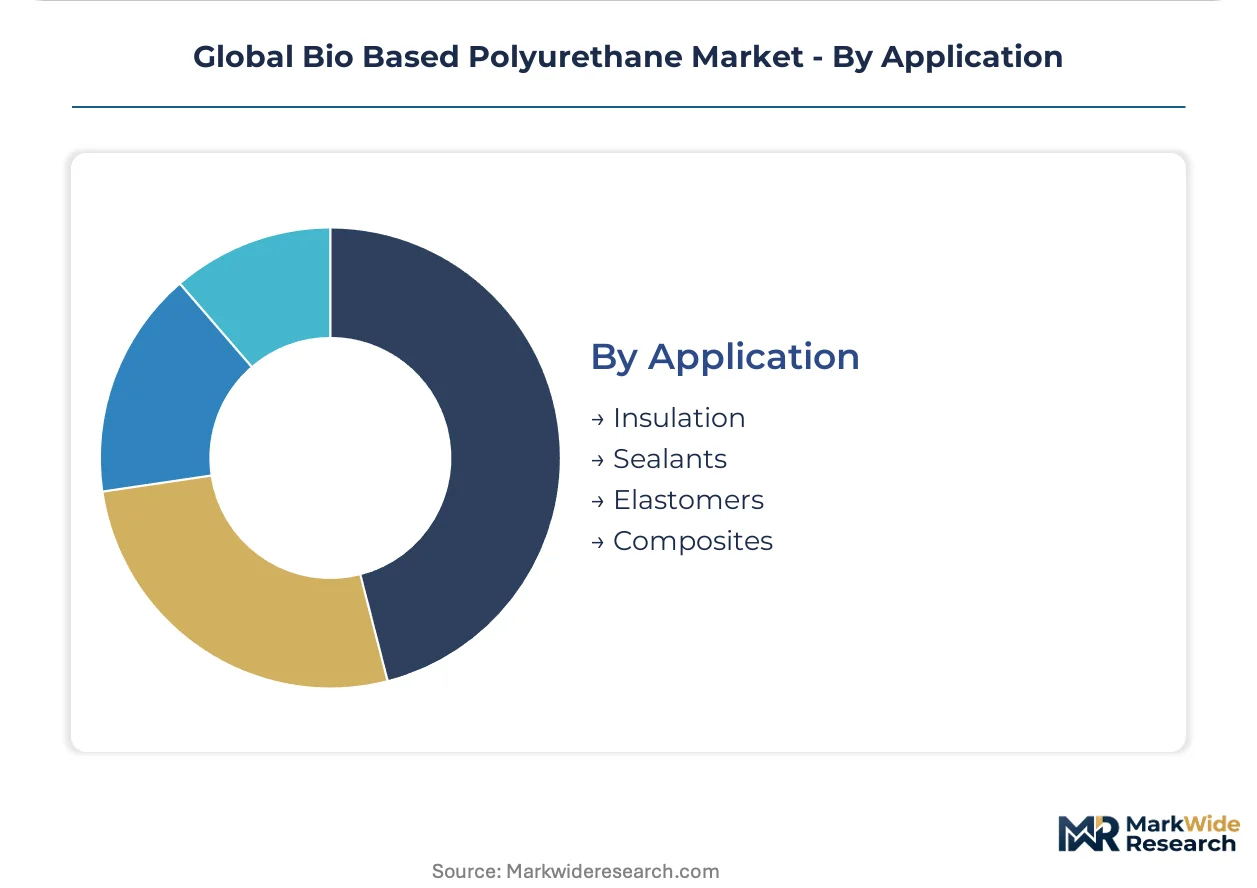
Insulation applications lead in volume, while sealants demonstrate significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of bio-based polyurethane often concentrates in regions with strong chemical industries, while consumption is increasingly distributed across global manufacturing hubs. This market dynamic creates complex supply chains balancing feedstock availability with end-use demand for sustainable materials. Regulatory incentives further shape both production and adoption patterns.
Germany
Demand for bio-based polyurethane in Germany stems from its robust automotive and construction sectors, seeking sustainable material solutions. The EU Green Deal and REACH regulations compel manufacturers to integrate bio-based alternatives for interior components and insulation. Major chemical parks like Ludwigshafen and Leverkusen actively develop novel bio-polyols for diverse industrial applications.
United States
The United States exhibits strong demand for bio-based polyurethane in consumer goods, packaging, and insulation applications. EPA standards on volatile organic compounds (VOCs) strongly encourage the use of waterborne or high-solids formulations across industries. Tax credits from the US Inflation Reduction Act (IRA) support domestic bio-material production, particularly in states like Ohio and Pennsylvania.
China
China's vast manufacturing base drives significant consumption of bio-based polyurethane in footwear, electronics, and furniture production. The country's stringent dual carbon goals push industries towards sustainable material sourcing and reduced environmental impact. Industrial zones in Guangdong and Jiangsu provinces are actively adopting bio-based foams for export-oriented products.
Vietnam
Vietnam's rapidly expanding footwear and furniture industries are embracing bio-based polyurethane to meet global brand sustainability targets. Government policies supporting green manufacturing initiatives contribute to material adoption and export competitiveness. Production facilities around Ho Chi Minh City and Hanoi integrate bio-based components into high-volume consumer goods.
Global Bio Based Polyurethane Market Key Industry Players
Top-tier vendors anchor the global bio-based polyurethane market, while specialized material science firms and feedstock suppliers occupy distinct niches. The market structure exhibits a tiered consolidation, with large chemical conglomerates dominating key segments. Strategic archetypes include integrated chemical producers, bio-polyol innovators, and application-specific formulators. Companies primarily focus on portfolio diversification and strategic partnerships to expand their market reach.
Integrated chemical producers, such as BASF SE, represent the established players leveraging extensive R&D capabilities for novel bio-polyol development and advanced material formulations. These companies occupy a position focused on high-performance materials for demanding applications like automotive and electronics, often with a global footprint. Covestro AG further exemplifies this tier, specializing in high-performance materials while also emphasizing circular economy principles in its product offerings. Huntsman International LLC, meanwhile, occupies a strategic position with a diverse portfolio of polyurethane systems, serving various end-use industries globally.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Cargill, Incorporated |
| BASF SE |
| Wanhua Chemical Group Co., Ltd. |
| Mitsui Chemicals, Inc. |
| Covestro AG |
| The Lubrizol Corporation |
| RAMPF Holding GmbH & Co. KG |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Vegetable oil price volatility, a key input for bio-polyols, cascades through the supply chain, influencing pricing tiers for bio-based polyurethane products.
Pricing Analysis
Cost-down pressure on standard bio-based polyurethane formulations accelerates because of agricultural feedstock price fluctuations. The market primarily operates on contract-based long-term offtake agreements for large volumes. Price differentiation stems from certification levels, such as EU Green Deal compliance, and customization requirements. Automotive and medical applications exhibit lower price sensitivity, while construction and furniture segments remain highly cost-sensitive.
Supply Chain Analysis
Reverse logistics for bio-based polyurethane products currently focus on end-of-life options like chemical recycling, driven by circular economy principles. Supply concentration for bio-polyols resides in Germany and the United States, with downstream manufacturing hubs in China and Vietnam. Key dependencies include vegetable oils and lignin, alongside specialized isocyanates. Commodity price volatility of agricultural feedstocks presents a structural supply chain risk, while distribution runs primarily through direct sales to industrial OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global bio-based polyurethane market is a supply-constrained story, with biorefinery scale-up challenges for novel bio-polyols propping pricing across segments.
For Market Incumbents: To counter performance parity limitations and cost competitiveness challenges, incumbents must invest heavily in advanced R&D for novel bio-polyols. Strategic partnerships with feedstock suppliers ensure consistent raw material access and price stability. Deepening certification investments, particularly for EU Green Deal compliance, reinforces market position. Expanding production capacity in key European and North American regions strengthens supply resilience.
For New Entrants and Emerging Players: Begin with targeting underpenetrated Asian markets like Vietnam and Indonesia, where footwear and furniture manufacturing is expanding. Focus on niche applications such as high-performance medical device components, leveraging biocompatibility and sustainability. A go-to-market angle emphasizing cost-competitive, application-specific formulations can gain traction. Collaborate with local manufacturers to integrate bio-based solutions into export-oriented products.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized bio-polyol innovators in Europe and North America, leveraging strong intellectual property. The long-term viability of this market is anchored in the global shift towards sustainable materials and decarbonization goals. Acquisition targets should include firms with established feedstock supply agreements or advanced biorefining technologies. Practitioners should monitor regulatory mandates on bio-content and scaling of industrial biorefinery capacity for early inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling biorefinery production addresses supply constraints for bio-polyols, stabilizing raw material availability. |
| Backward Integration | Securing captive feedstock supply reduces reliance on volatile agricultural commodity markets. |
| Green Manufacturing Transition | Adopting sustainable production processes enhances brand value and meets stringent environmental regulations. |
| Long-term Supply Agreement | Ensuring consistent supply of bio-based inputs mitigates price volatility and production risks for manufacturers. |
| Joint Venture | Combining expertise and capital accelerates novel bio-polyol development and market penetration. |
Research Approach
Independent corroboration across chemical synthesis experts, automotive procurement managers, and footwear R&D specialists underwrites the qualitative findings. This approach combines primary interviews with industry stakeholders and secondary validation from sources like EU Green Deal reports and EPA standards documents. Bottom-up and top-down triangulation ensures data consistency. This study gathered insights from manufacturing leads and material specifiers.
Rate-of-change decomposition analyzes market dynamics across the forecast period, identifying drivers for each segment. Segmentation dimensions modeled include product type, end-use industry, formulation type, application, and bio-content percentage. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key industry-specific forecast inputs include bio-polyol production capacity and regulatory compliance deadlines.
Raw material price volatility, technological breakthroughs in alternatives, and shifts in regulatory enforcement are the dominant revision risks for market projections. Forecasts reflect assumptions documented through extensive primary and secondary research. Practitioners should monitor these triggers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market