
 UV Glue Market | 2026-2036
UV Glue Market Size, Share, and Industry Trends Forecast 2026-2036
UV Glue Market Analytics
Multi-source procurement among electronics assemblers is broadening as supply-chain resilience replaces single-vendor dependency. Henkel AG & Co. KGaA leverages its European R&D base to dominate high-purity optical grades. 3M Company anchors North American demand through direct technical-service relationships with medical-device OEMs. Dymax Corporation specializes in rapid-cure systems for microelectronics, competing on cure-speed specifications rather than volume pricing.
UV glue comprises photoinitiator-dispersed acrylate or epoxy formulations that polymerize upon exposure to ultraviolet light in the 200–400 nanometer range, delivering bond strengths from 5 to 30 MPa depending on substrate preparation and lamp intensity. The chemistry serves precision assembly where thermal curing risks component damage or where solvent evaporation introduces contamination. Clear adhesives occupy the largest volume share across electronics display lamination, where optical clarity requirements exclude tinted alternatives. Medical Devices represents the fastest-growing application segment, driven by catheter and diagnostic cartridge assembly that demands biocompatible, room-temperature cure cycles. Flexible adhesives command premium positioning in automotive sensor encapsulation, where thermal expansion mismatches between dissimilar substrates require compliant bond lines.
FDA 21 CFR Part 175.105 governs indirect food-contact adhesives in the United States, while REACH Annex XVII restricts certain photoinitiator chemistries within the European Union. China's GB standards through SAMR set Volatile Organic Compound limits for industrial adhesive formulations, influencing export-oriented manufacturers in Zhejiang and Jiangsu provinces. Stakeholders must monitor regulatory divergence on photoinitiator safety classifications, as classification shifts in one jurisdiction trigger reformulation costs across multi-regional supply chains.
Market Dynamics
Electronics miniaturization is compressing cure-cycle tolerances to sub-second windows, forcing adhesive suppliers to reengineer photoinitiator kinetics for micro-assembly lines in Guangdong and Gyeonggi-do provinces.
Growth Catalysts
- REACH Annex XVII photoinitiator restrictions:European formulation standards are accelerating R&D investment in safer acrylate alternatives, creating first-mover advantages for compliant suppliers.
- Medical device catheter assembly:Biocompatible room-temperature cure cycles are displacing thermal bonding in cardiovascular and diagnostic cartridge manufacturing.
- Guangdong display-panel clusters:Concentrated procurement from liquid-crystal and OLED lamination facilities is pulling volume-grade UV adhesive through bonded warehouses.
Market Restraints
- Acrylate monomer price volatility:Petrochemical feedstock fluctuations compress margin buffers for commodity-grade formulations.
- Photoinitiator supply concentration:German and Chinese specialty chemical producers control 80 percent of high-purity benzoin ether supply.
- Oxygen inhibition in thin-film applications:Surface cure failures in sub-50-micron bond lines limit adoption in flexible electronics.
Strategic Opportunities
- India medical device PLI scheme:Domestic catheter and surgical instrument manufacturing incentives create import-substitution openings for certified adhesive suppliers.
- UV-LED convergence with adhesive dispensing:Solid-state lamp retrofits are enabling precision curing in battery assembly lines without mercury-vapor equipment.
- SAMR GB VOC compliance:Stricter Chinese emissions standards are disqualifying solvent-based competitors in export-oriented Zhejiang coating facilities.
Industry Challenges
- Photoinitiator toxicology assessment:ECHA substance evaluation timelines stretch 18-24 months, freezing formulation decisions during regulatory review.
- Cleanroom-grade certification:ISO 14644 Class 7 compliance for medical adhesive production demands seven-figure capital investment in filtration and monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Glue Market |
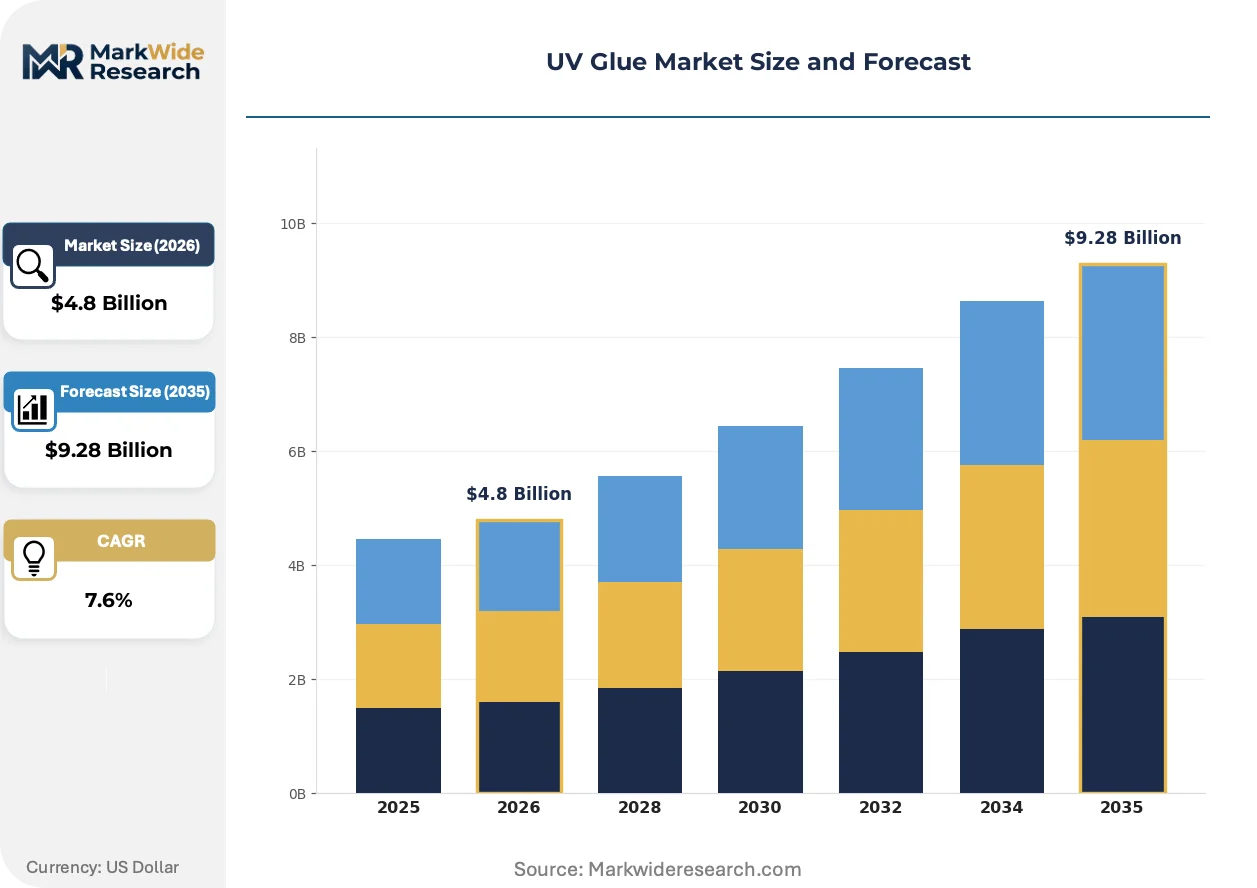
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Adhesives, High Viscosity Adhesives, Low Viscosity Adhesives, Flexible Adhesives Application: Electronics, Automotive, Medical Devices, Optical Products End User: Manufacturers, Repair Services, Retailers, Distributors Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale Distributors |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Dymax Corporation, Arkema, DELO Industrial Adhesives, Permabond LLC, Panacol-Elosol GmbH, Master Bond Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Glue Market Evolving Landscape
Dual-cure systems combining UV initiation with moisture or thermal secondary curing are expanding process windows for complex geometries. Formulation chemists are prioritizing low-intensity LED compatibility over legacy mercury-arc lamp optimization.
Cationic epoxy formulations are overtaking radical acrylate systems in automotive sensor encapsulation. Tier-1 suppliers in Stuttgart and Toyota City are specifying these chemistries for under-hood applications where thermal cycling exceeds 150 degrees Celsius. The shift is compressing demand for conventional acrylates in powertrain electronics.
REACH restriction proposals on TPO (trimethylbenzoyl diphenyl phosphine oxide) are forcing reformulation across European optical bonding applications. Medical device manufacturers are accelerating biocompatibility validation for alternative photoinitiators ahead of anticipated 2025 classification shifts. Diagnostic cartridge assemblers in Ireland and Switzerland are pre-qualifying TPO-free grades to avoid supply disruption.
Consolidated technical-service contracts are displacing spot purchasing in North American medical-device supply chains. OEM procurement teams in Minnesota and Massachusetts are bundling adhesive supply with dispensing equipment calibration and cure-process validation. This bundling concentrates vendor relationships around Henkel and 3M field-engineering networks, compressing opportunities for regional distributors.
UV Glue Market Segmentation
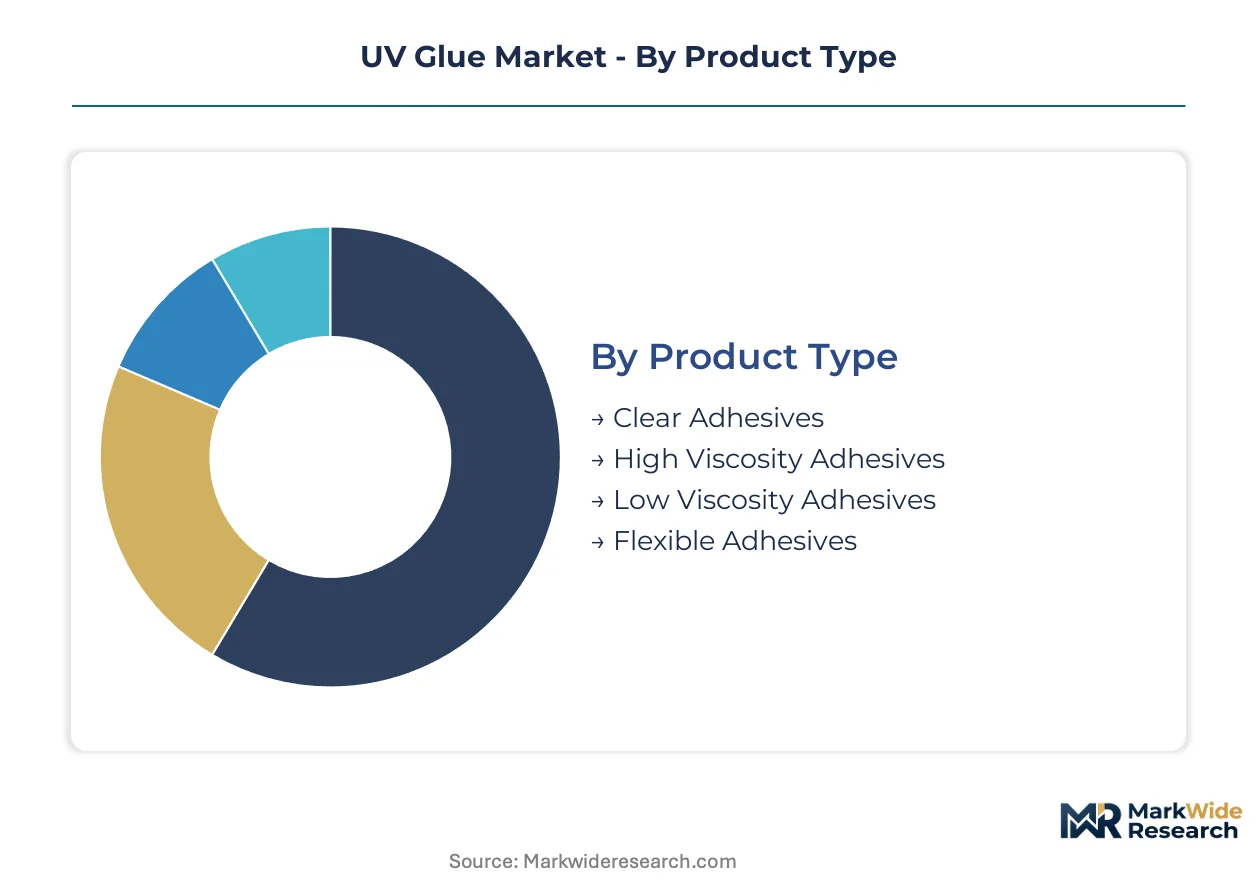
UV glue segmentation reveals distinct certification burdens across product grades, with medical and optical applications demanding FDA or ISO biocompatibility validation while industrial electronics prioritize cure-speed specifications over formal approvals. Understanding these tiered requirements helps suppliers allocate R&D resources and pricing power across divergent customer bases.
Product Type:
FDA 21 CFR Part 175.105 governs indirect food-contact clear adhesives in the United States, while REACH Annex XVII restricts photoinitiator loadings in high-viscosity European formulations; flexible grades for automotive sensors carry no mandatory pre-market clearance but face OEM material qualification protocols.
- Clear Adhesives:Photoinitiator-dispersed acrylate formulations delivering optical clarity above 90 percent transmission in the visible spectrum. Display-panel lamination facilities in China's Guangdong province concentrate procurement for liquid-crystal and OLED bonding, driven by zero-yellowing requirements under high-intensity LED backlighting.
- High Viscosity Adhesives:Thixotropic formulations maintaining structural integrity on vertical surfaces during cure cycles. Gap-filling applications in automotive sensor encapsulation and heavy-duty electronics housings concentrate demand, constrained by slower flow characteristics that complicate micro-assembly dispensing.
- Low Viscosity Adhesives:Capillary-flow formulations penetrating sub-100-micron gaps in precision electronics.
- Flexible Adhesives:Elastomer-modified systems accommodating thermal expansion mismatches between dissimilar substrates.
Clear adhesives sit at the top of the volume ranking, with flexible adhesives climbing the fastest.
Application:
Cost tier differentiation separates premium-certified medical grades from commodity electronics formulations, with catheter assembly commanding three to five times the per-gram pricing of display lamination adhesives.
- Electronics:Micro-assembly bonding for semiconductors, PCBs, and display components requiring sub-second cure windows. Procurement from Guangdong and Gyeonggi-do province clusters dominates volume, pressured by compressing tolerances in miniaturized device architectures.
- Automotive:Sensor encapsulation and powertrain electronics under thermal cycling regimes exceeding 150 degrees Celsius. Stuttgart and Toyota City tier-1 suppliers are specifying cationic epoxy systems over radical acrylates for under-hood reliability.
- Medical Devices:Catheter, diagnostic cartridge, and surgical instrument assembly demanding biocompatible room-temperature cure cycles. Cardiovascular device manufacturers in Minnesota and Massachusetts are displacing thermal bonding to protect heat-sensitive components.
- Optical Products:Lens bonding and fiber-optic termination requiring refractive index matching and zero-outgassing.
Electronics holds the largest installed base, though medical devices is expanding most quickly.
End User:
Customer type determines technical service intensity, with manufacturers requiring embedded field engineering and repair services purchasing through spot channels with minimal support attachment.
- Manufacturers:OEM and contract electronics assemblers procuring through consolidated technical-service contracts bundling adhesive supply with dispensing equipment calibration. Minnesota and Massachusetts medical-device procurement teams are compressing vendor relationships around integrated field-engineering networks.
- Repair Services:Aftermarket electronics and automotive maintenance operations purchasing lower-volume SKUs through distributor channels.
- Retailers:Consumer-facing hardware and hobbyist supply outlets carrying small-format UV glue products.
- Distributors:Regional chemical and industrial supply intermediaries holding bonded warehouse inventory for just-in-time delivery to manufacturing clusters.
Manufacturers command the dominant share of volume flow, with repair services gaining traction in aftermarket segments.
Distribution Channel:
Supply concentration in German and Chinese photoinitiator production shapes channel strategy, with direct sales relationships securing allocation priority during feedstock constraints.
- Online Retail:E-commerce platforms serving small-volume purchasers and geographically dispersed repair operations.
- Direct Sales:Technical-service relationships with medical-device OEMs and tier-1 automotive suppliers. 3M Company anchors North American medical-device demand through this channel, embedding cure-process validation within supply contracts.
- Specialty Stores:Regional industrial chemical distributors with formulation expertise and local inventory.
- Wholesale Distributors:Broad-line industrial supply houses moving volume-grade electronics adhesives through bonded warehouses in Guangdong province.
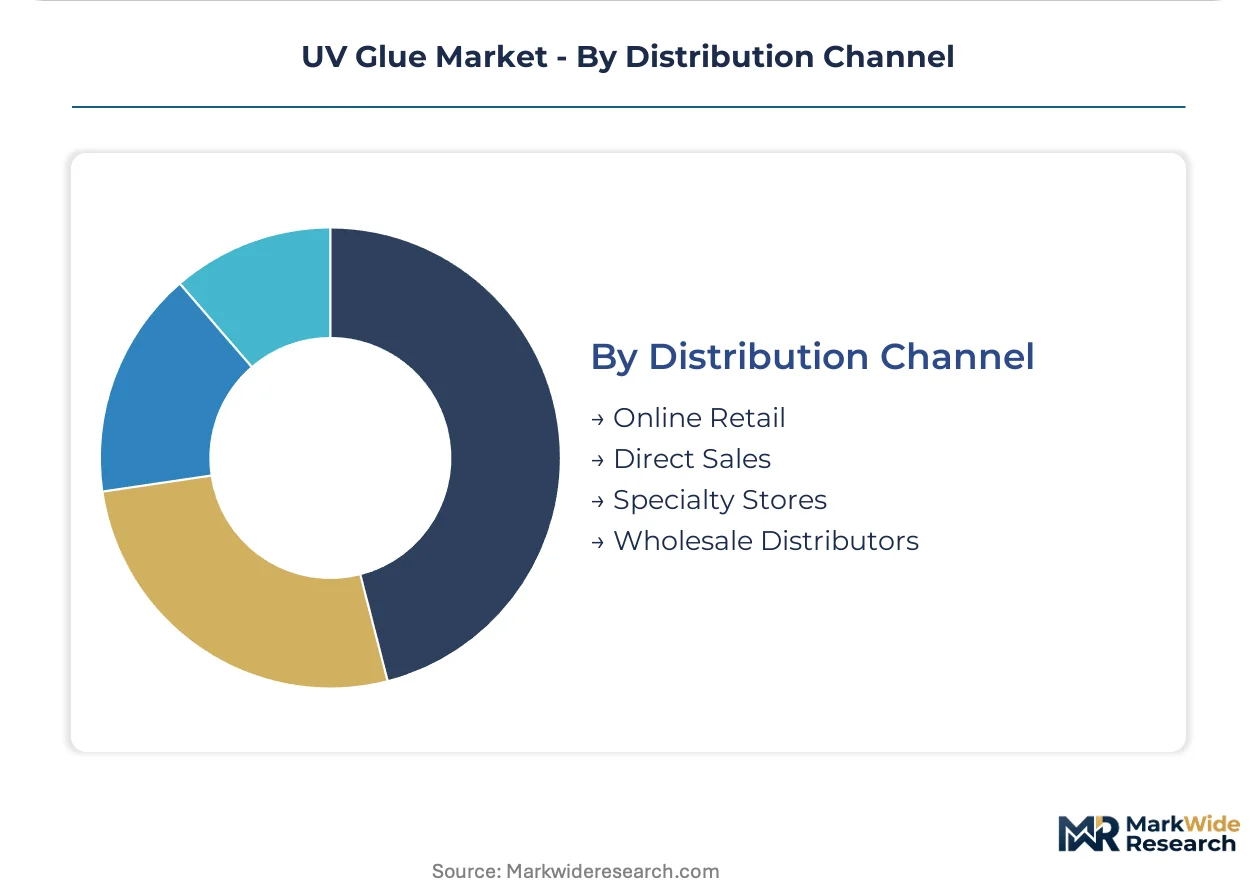
Direct sales captures the highest value per transaction, while wholesale distributors handle the greatest physical volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors industrial UV adhesive consumption through concentrated display-panel and semiconductor packaging clusters. Procurement patterns across major economies diverge sharply based on regulatory stringency and end-use specialization.
United States
FDA device-clearance pathways govern medical-grade UV adhesive qualification for catheter and diagnostic cartridge manufacturers. Minnesota and Massachusetts procurement teams bundle adhesive supply with dispensing equipment calibration through consolidated technical-service contracts. Cardiovascular device OEMs displace thermal bonding to protect heat-sensitive components.
Germany
REACH Annex XVII restrictions on benzoin ether photoinitiators accelerate R&D investment in safer acrylate alternatives. Stuttgart tier-1 automotive suppliers specify cationic epoxy systems for under-hood sensor encapsulation exceeding 150 degrees Celsius thermal cycling. ECHA substance evaluation timelines stretch formulation decisions across 18-24 month review windows.
China
SAMR GB standards set Volatile Organic Compound limits for industrial adhesive formulations in export-oriented manufacturing. Zhejiang and Jiangsu province coating facilities face disqualification of solvent-based competitors under stricter emissions enforcement. Guangdong bonded warehouses pull volume-grade UV adhesive through just-in-time delivery channels serving liquid-crystal and OLED lamination facilities.
Japan
METI industrial standards shape photoinitiator safety classifications for electronics assembly applications. Toyota City automotive electronics manufacturers specify rapid-cure systems for powertrain sensor encapsulation. Kanto region micro-assembly lines compress cure-cycle tolerances to sub-second windows for miniaturized device architectures.
South Korea
MFDS medical device regulations align with international biocompatibility standards for catheter assembly applications. Gyeonggi-do province semiconductor packaging clusters expand UV adhesive procurement for micro-assembly bonding operations. Seoul Capital Area display-panel manufacturers concentrate demand for zero-yellowing clear adhesive grades under high-intensity LED backlighting.
UV Glue Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue LED-compatible formulations and secondary-cure system development. The vendor base stratifies across three tiers: multinational chemical conglomerates with integrated R&D infrastructure, mid-cap specialists focusing on rapid-cure microelectronics applications, and regional distributors holding bonded inventory for just-in-time electronics clusters. Dominant competitive moves include portfolio diversification into medical-grade certifications and geographic expansion through technical-service contract bundling.
Within the multinational tier, Henkel AG & Co. KGaA and 3M Company occupy positions shaped by regional R&D anchoring and direct OEM relationship structures. Henkel exemplifies European-based high-purity optical grade specialization, while 3M represents North American medical-device technical-service integration. Dymax Corporation sits within the rapid-cure specialist archetype, competing on cure-speed specifications rather than volume pricing structures.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Dymax Corporation |
| Arkema |
| DELO Industrial Adhesives |
| Permabond LLC |
| Panacol-Elosol GmbH |
| Master Bond Inc. |
| Others |
Value Network & Pricing Analysis
Captive photoinitiator production by German and Chinese specialty chemical producers anchors both supply security and pricing power for UV adhesive formulators serving medical-device and optical-bonding tiers. This backward integration into benzoin ether manufacturing insulates volume-grade suppliers from petrochemical feedstock volatility while compressing margin buffers for non-integrated compounders dependent on spot-market monomer procurement.
Pricing Analysis
Acrylate monomer cost pass-through from petrochemical feedstock fluctuations compresses margin buffers for commodity-grade formulations while premium medical tiers absorb input volatility through biocompatibility certification premiums. Three-tier pricing structure across medical-certified, industrial-electronics, and economy repair grades separates catheter assembly pricing from display-lamination volumes. Pricing pressure stems from oxygen-inhibition failures in thin-film applications limiting yield rates for flexible electronics formulators. Contract electronics assemblers in Guangdong province exhibit highest price sensitivity through consolidated technical-service bidding, whereas Minnesota cardiovascular OEMs prioritize supply assurance over unit cost.
Supply Chain Analysis
India's medical device PLI scheme and China's SAMR GB standards are reshaping sourcing patterns for export-oriented adhesive manufacturers seeking domestic-content qualification. Photoinitiator supply concentrates in Germany and China, with high-purity benzoin ether production anchored by specialty chemical producers controlling upstream synthesis. Raw material dependencies span acrylate monomers, epoxy resins, and LED-curable photoinitiator packages. Single-source vulnerability in benzoin ether supply creates allocation risk during feedstock constraints. Distribution runs through bonded warehouses in Guangdong province serving just-in-time procurement from display-panel clusters, supplemented by direct technical-service relationships with North American medical-device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UV adhesives rests on LED-curable formulation premiums displacing mercury-arc systems and REACH-compliant photoinitiator substitutes capturing first-mover pricing power. Cost-down drivers include UV-LED equipment retrofits eliminating mercury-vapor infrastructure and dual-cure systems reducing scrap rates in complex geometries.
For Market Incumbents: To counter TPO photoinitiator REACH restrictions freezing European formulation decisions, accelerate biocompatibility validation for alternative photoinitiators ahead of anticipated classification shifts. Deepen backward integration into high-purity benzoin ether production to secure allocation priority during German and Chinese supply constraints. Expand technical-service contract bundling in Minnesota and Massachusetts to compress distributor channel opportunities. For New Entrants and Emerging Players: Enter via India's catheter and surgical instrument manufacturing incentives under the medical device PLI scheme, where import-substitution demand outpaces certified domestic supply. Target Gyeonggi-do province semiconductor packaging clusters with rapid-cure systems competing on sub-second cure specifications rather than volume pricing. Pursue UV-LED convergence partnerships with battery assembly line retrofits seeking mercury-free curing infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for rapid-cure microelectronics specialists because cure-speed specification gaps create acquisition synergies with multinational technical-service networks. Long-term viability hinges on LED-compatible formulation portfolios and medical-grade certification infrastructure. Watch ECHA substance evaluation timelines for TPO alternatives as inflection indicator for reformulation capex cycles and first-mover premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Production | Secures benzoin ether supply allocation for medical-grade formulators facing REACH restrictions. |
| Medical Device Certification Investment | ISO 14644 Class 7 compliance opens catheter assembly procurement from Minnesota cardiovascular OEMs. |
| UV-LED Equipment Partnership Program | Mercury-free curing retrofits capture battery assembly line demand from Guangdong manufacturers. |
| Dual-Cure Formulation Development | Moisture-secondary curing expands process windows for automotive sensor encapsulation in Stuttgart. |
| India PLI Scheme Market Entry | Domestic catheter manufacturing incentives create import-substitution openings for certified suppliers. |
Research Methodology
Direct dialogue with adhesive formulators, medical-device procurement managers, display-panel manufacturing engineers, and photoinitiator specialty chemical producers grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance evaluation databases, FDA 21 CFR filings, SAMR GB standard publications, and SEC 10-K disclosures from multinational chemical conglomerates. Bottom-up demand modeling from end-use application clusters triangulated against top-down supply-side capacity assessments across German, Chinese, and North American production hubs.
Segment-level value and volume trajectories across the projection horizon reflect adhesive grade tier, end-use industry concentration, cure-technology compatibility, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating UV-LED adoption rates, REACH compliance timelines, and medical-device PLI scheme implementation pace. Industry-specific forecast inputs included photoinitiator toxicology assessment durations, cleanroom certification capex cycles, and miniaturization-driven cure-window compression in microelectronics assembly.
Inputs from ECHA evaluation timelines and SAMR enforcement calendars were available through the study window; gaps in real-time benzoin ether spot pricing and confidential OEM contract terms introduce uncertainty bands around medical-grade pricing trajectory assumptions. Forecasts reflect documented assumptions regarding LED-curable substitution rates and REACH restriction implementation sequencing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
High Strength Laminated Adhesives Market