
 Middle East and Africa Epoxy Curing Agents Market | 2026-2036
Middle East and Africa Epoxy Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Epoxy Curing Agents Market Foresight
The gap between performance-grade amine systems and basic polyamide formulations is broadening across the Middle East and Africa. KUKDO Chemical leverages its regional production footprint to supply standardized curing agents for volume construction applications. Hexion anchors the premium segment with specialized anhydride and cycloaliphatic amine portfolios targeting industrial coatings and composites. Arkema competes through differentiated low-VOC and rapid-cure technologies suited to tightening environmental specifications in the UAE and Saudi Arabia.
Epoxy curing agents are chemical compounds that react with epoxy resins to form cross-linked thermoset polymers, with amine-based systems typically requiring stoichiometric ratios of 1:1 to 1:3 (amine hydrogen to epoxide equivalent) and curing temperatures ranging from ambient to 180°C depending on molecular structure and accelerator presence. These agents serve as the reactive backbone for adhesives, protective coatings, and structural composites across industrial manufacturing. Amine-based products dominate volume consumption in the region due to their versatility in construction and marine applications, while acid anhydride systems command premium positioning in electrical laminates and high-temperature aerospace components where thermal stability requirements exceed 150°C continuous service. Polyamide curing agents sustain steady demand in corrosion-resistant marine coatings and DIY enthusiast segments across North Africa and the Levant.
SFDA chemical substance notification requirements and Saudi Arabia's SASO technical regulations govern product registration and labeling standards for imported curing agents across the GCC. The EU REACH framework exerts indirect pressure through supply chain compliance demands on European exporters serving African markets. South Africa's NRCS maintains local chemical control ordinances affecting formulation approvals and hazard communication protocols. Stakeholders must monitor accelerating localization mandates and evolving VOC thresholds as Gulf states advance industrial chemical self-sufficiency agendas.
Market Dynamics
Megaproject execution across the GCC is compressing specification cycles for epoxy curing agents, forcing formulators to reconcile rapid-cure performance with tightening VOC thresholds under Saudi SASO and UAE MOHAP chemical regulations.
Growth Catalysts
- Neom and Red Sea Project Buildouts:Saudi Arabia's gigaprojects are specifying high-performance epoxy flooring and protective coatings for logistics hubs and residential districts, pulling volume demand for amine-based curing systems.
- SASO Technical Regulation Alignment:Saudi Arabia's standardization body is harmonizing import requirements with EU REACH safety data sheet protocols, reducing technical barriers for compliant European suppliers.
- Marine Coatings Refurbishment:Suez Canal traffic expansion and North African port modernization are accelerating hull recoating cycles, sustaining polyamide curing agent consumption across Egyptian and Moroccan shipyards.
Market Restraints
- Cycloaliphatic Amine Feedstock Volatility:Benzene derivative pricing swings are compressing margins for premium-grade curing agent producers serving electrical laminate applications.
- Chinese Import Concentration:Basic polyamide and aliphatic amine supply chains remain anchored to East Asian producers, exposing African distributors to freight cost spikes and currency mismatch risks.
- Anhydride Curing Temperature Floors:Acid anhydride systems require sustained thermal profiles above 120°C, limiting their deployment in ambient-cure construction coatings across the Gulf's summer construction windows.
Strategic Opportunities
- Nigeria Industrial Corridor Expansion:Dangote Refinery and associated petrochemical clusters are creating first-mover openings for localized curing agent blending operations serving West African coatings demand.
- Waterborne Epoxy Convergence:Low-VOC emulsion technologies are intersecting with rapid-cure amine chemistry, enabling formulators to capture interior commercial flooring specifications previously closed to solvent-based systems.
- Saudi Localization Mandates:The kingdom's industrial chemical self-sufficiency agenda is incentivizing joint ventures between international curing agent specialists and domestic petrochemical producers.
Industry Challenges
- Formulation Chemist Scarcity:The GCC lacks sufficient technical personnel trained in stoichiometric ratio optimization for high-performance amine-epoxy systems, delaying product qualification timelines.
- SFDA Notification Backlogs:Saudi Arabia's chemical substance registration queue is extending market entry lead times for novel curing agent chemistries by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Epoxy Curing Agents Market |
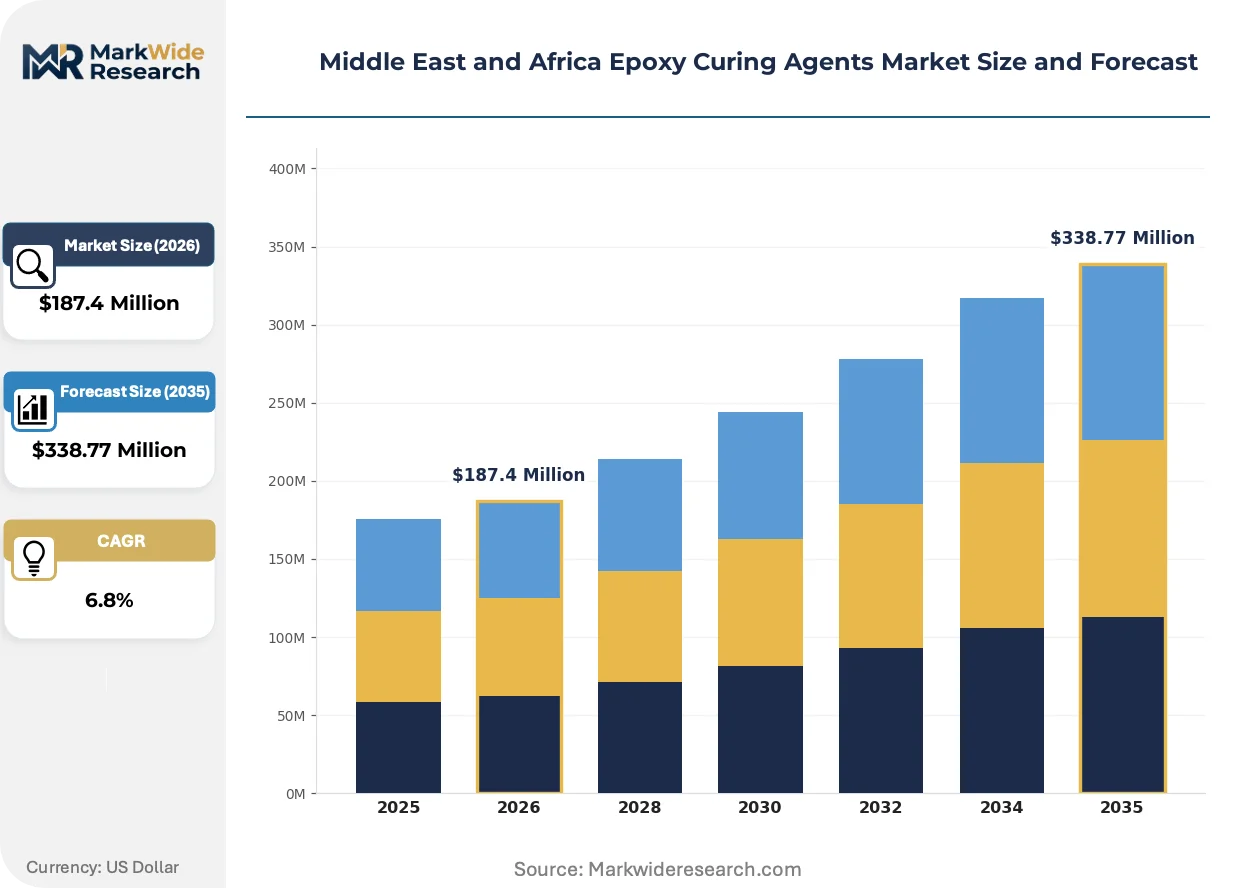
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amine-Based, Acid Anhydride, Polyamide, Others Application: Aerospace, Automotive, Construction, Marine Curing Mechanism: Thermal, UV Light, Moisture, Chemical End User: Manufacturers, OEMs, Contractors, DIY Enthusiasts |
| Companies Covered | KUKDO Chemical, Hexion, Arkema, BASF SE, Dow, Huntsman International, NAMA Chemicals, Mitsubishi Chemical Corporation, Evonik Industries, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Epoxy Curing Agents Market Shifts & Advancements
Formulation chemistry across the Middle East and Africa is pivoting toward systems that reconcile ambient-cure convenience with regulatory compliance, compressing the traditional trade-off between performance and environmental acceptability.
Adducted amine technology is converging with latent curing accelerator packages to enable single-component epoxy systems with extended pot life and snap-cure activation. Saudi precast concrete producers are piloting these systems for infrastructure joint sealing. The convergence is displacing conventional two-component mixing protocols on congested construction sites where labor skill variability compromises mix ratio accuracy.
SASO technical regulations governing chemical substance labeling and hazard communication are tightening alignment with EU REACH Article 31 safety data sheet requirements. Industrial coatings importers must now submit extended toxicological dossiers for amine hardener classifications. Saudi-based formulators are responding by pre-qualifying curing agent grades against both Gulf and European standards to maintain supply optionality.
Specification authority is migrating from general contractors to asset owner engineering departments, particularly in Saudi Aramco and ADNOC downstream projects. Owner-engineered material approvals are replacing contractor-driven substitution freedoms, compressing the approved products list for epoxy flooring and tank lining applications. This concentration is most visible in Saudi Arabia's industrial city developments where master specifications now mandate pre-approved curing agent suppliers.
Middle East and Africa Epoxy Curing Agents Market Segmentation
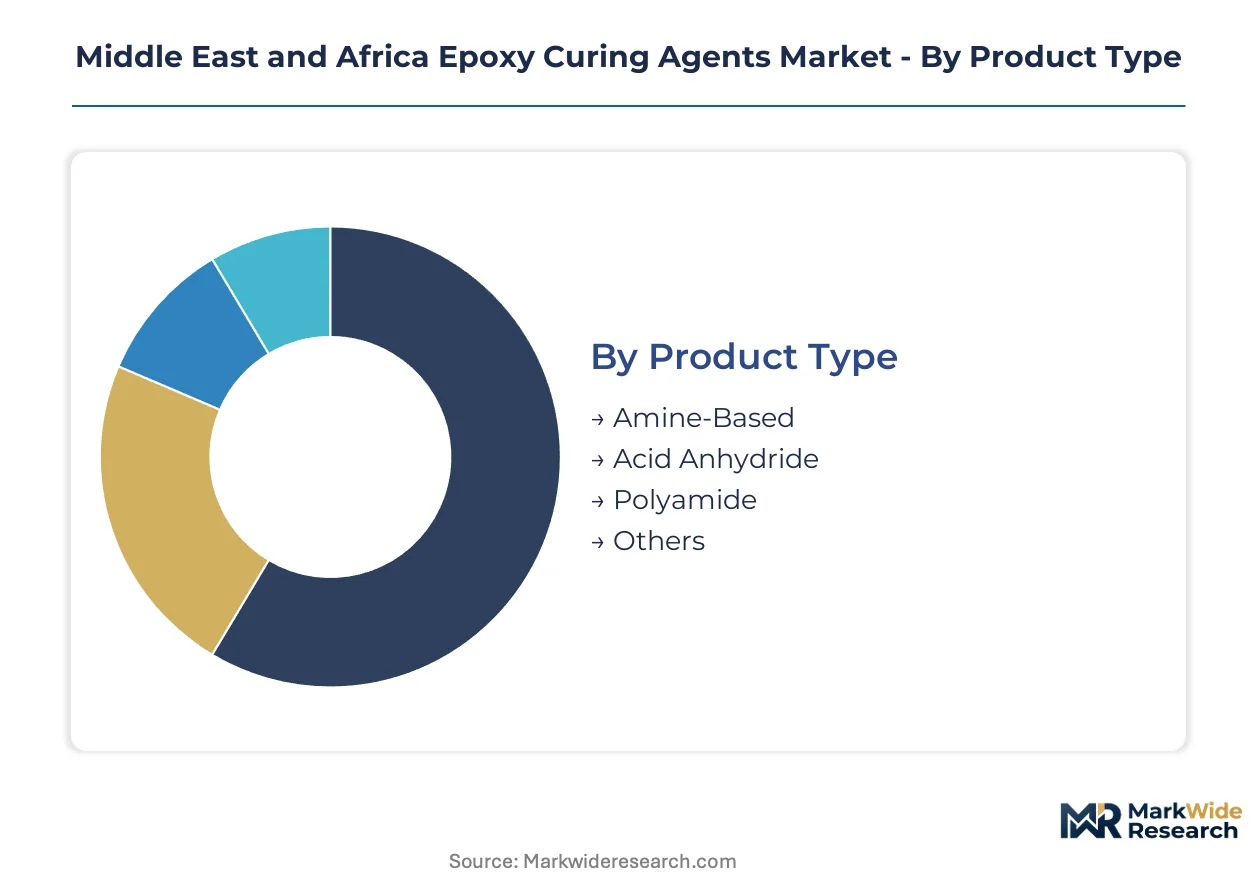
Epoxy curing agent selection across the Middle East and Africa hinges on reconciling ambient-cure feasibility with SASO and MOHAP compliance thresholds. Specification authority now rests with asset owner engineering departments rather than general contractors, compressing approved product lists and forcing suppliers to pre-qualify grades across multiple regulatory frameworks simultaneously.
Product Type:
Customization intensity spans from commodity polyamide formulations to precision-engineered anhydride systems, with formulation flexibility determining margin capture across construction and industrial applications.
- Amine-Based:Aliphatic and cycloaliphatic variants dominate volume consumption through their versatility in ambient-cure construction coatings and marine applications. Saudi Aramco downstream projects specify these systems for tank linings and industrial flooring across Jubail Industrial City and Yanbu, where rapid-cure requirements intersect with tightening VOC thresholds under SASO technical regulations.
- Acid Anhydride:High-performance systems requiring sustained thermal profiles above 120°C serve electrical laminates and aerospace composites where continuous service temperatures exceed 150°C. Demand concentrates in UAE-based aerospace maintenance facilities and Saudi petrochemical cluster expansions, though ambient-cure limitations restrict deployment in Gulf summer construction windows.
- Polyamide:Corrosion-resistant marine coatings and DIY segments across Egyptian and Moroccan shipyards sustain steady consumption.
- Others:Latent and phenolic curing systems address specialized encapsulation and high-voltage electrical applications.
Most installed capacity flows through Amine-Based systems. Expansion is steepest in Acid Anhydride as electrical laminate and aerospace specifications proliferate.
Application:
Project scale and asset ownership structure determine specification tier, with gigaproject engineering departments imposing stricter pre-approval protocols than contractor-driven maintenance cycles.
- Construction:Epoxy flooring and protective coatings anchor regional demand through Neom, Red Sea Project, and Qiddiya buildouts specifying high-performance amine systems. Logistics hubs and residential districts across Saudi Arabia pull volume for self-leveling and anti-static formulations, with SASO-aligned safety data sheet requirements now mandatory for import clearance.
- Marine:Suez Canal traffic expansion and North African port modernization accelerate hull recoating cycles, sustaining polyamide curing agent consumption. Egyptian and Moroccan shipyards favor ambient-cure systems for dry-dock efficiency, while UAE-based superyacht maintenance drives premium-grade specification.
- Aerospace:Thermal stability requirements favor anhydride and cycloaliphatic amine systems for composite structures and electrical components.
- Automotive:Refinish coatings and structural adhesives represent emerging specification territory as regional vehicle assembly expands.
Construction commands the dominant share of formulation volumes. Marine applications are gaining share fastest as canal expansion and port privatization deepen maintenance cycles.
Curing Mechanism:
Energy availability and labor skill levels determine mechanism selection, with thermal systems demanding infrastructure investment that ambient alternatives circumvent.
- Thermal:Sustained heat input enables anhydride and elevated-temperature amine systems for electrical laminates and high-performance composites. Saudi precast concrete producers increasingly specify thermal-cure protocols for infrastructure joint sealing, though Gulf summer ambient temperatures occasionally substitute for active heating.
- Chemical:Two-component mixing of resin and hardener dominates construction and marine applications where portable application equipment prevails. Stoichiometric ratio sensitivity drives demand for pre-measured kits and automated mixing systems on congested Saudi gigaproject sites.
- UV Light:Rapid surface cure suits thin-film decorative coatings and rapid-turnaround maintenance applications.
- Moisture:Latent systems activated by atmospheric humidity serve concrete repair and underground infrastructure where active heating is impractical.
Thermal mechanisms anchor industrial-grade capacity. Chemical curing is climbing the fastest as single-component adducted amine technologies displace conventional mixing protocols.
End User:
Technical sophistication and procurement scale separate specification authority, with large asset owners increasingly bypassing contractor intermediaries.
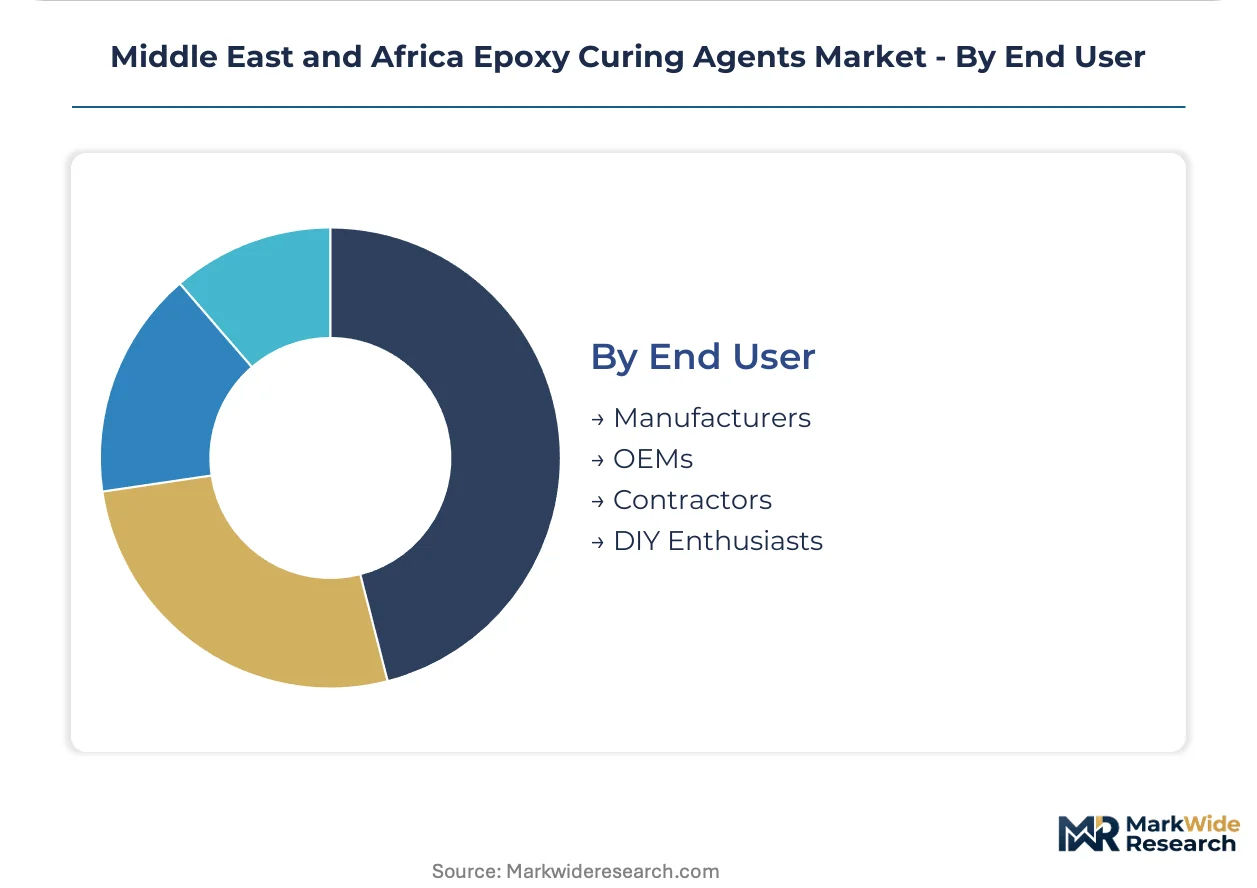
- Contractors:General construction and maintenance operations across GCC commercial and industrial projects drive standardized amine system volumes. Labor skill variability on congested Saudi sites is accelerating adoption of pre-formulated single-component systems that eliminate on-site mixing errors.
- Manufacturers:Industrial coatings producers and composite fabricators in Jubail, Yanbu, and Ruwais specify technical-grade curing agents for captive formulation. These entities maintain in-house laboratories for stoichiometric optimization and SASO pre-qualification testing.
- OEMs:Original equipment manufacturers in aerospace and automotive supply chains impose stringent qualification protocols extending market entry timelines.
- DIY Enthusiasts:North African and Levant retail segments sustain polyamide and basic amine consumption for small-scale marine and household repair applications.
Contractors represent the largest installed base of consumption. Manufacturers are expanding most quickly as localization mandates incentivize domestic formulation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical formulation specialists cluster around Jubail and Yanbu industrial cities, anchoring Saudi Arabia's curing agent demand concentration. Egyptian and Moroccan coating applicators supply Suez Canal and Mediterranean port maintenance cycles.
Saudi Arabia
Neom, Red Sea Project, and Qiddiya buildouts specify high-performance amine systems for logistics hubs and residential districts. SASO technical regulations now mandate REACH-aligned safety data sheet protocols for all imported curing agents. Jubail Industrial City hosts the densest concentration of precast concrete producers piloting single-component adducted amine systems.
United Arab Emirates
MOHAP chemical regulations are tightening VOC thresholds for interior commercial flooring specifications. Dubai and Abu Dhabi-based superyacht maintenance operations drive premium-grade cycloaliphatic amine consumption. Ruwais petrochemical cluster expansions are pulling technical-grade anhydride systems for captive composite fabrication.
Egypt
Suez Canal traffic expansion is accelerating hull recoating cycles across Egyptian shipyards. The country's national chemical control ordinances govern hazard communication protocols for imported marine coatings. Alexandria and Port Said dry-dock facilities favor ambient-cure polyamide systems for operational efficiency.
South Africa
NRCS chemical control ordinances affect formulation approvals for corrosion-resistant coatings serving mining and industrial maintenance. Durban and Cape Town port modernization is sustaining polyamide consumption for marine protection systems. Local distributors face freight cost exposure on basic amine imports from East Asian supply chains.
Nigeria
Dangote Refinery and associated petrochemical clusters are creating first-mover openings for localized curing agent blending operations. The country's national standards body governs product registration for industrial chemical imports. Lagos and Port Harcourt industrial corridors represent emerging specification territory for West African coatings demand.
Middle East and Africa Epoxy Curing Agents Market Competitive Landscape
Top-tier vendors anchor premium-grade anhydride and cycloaliphatic amine supply, while regional compounders and construction-grade specialists occupy volume-driven segments. The vendor base spans three strategic tiers: multinational chemical conglomerates with integrated resin-curing agent portfolios, regional producers leveraging feedstock proximity for standardized construction formulations, and specialized importers serving niche marine and DIY applications. Competitive positioning hinges on SASO pre-qualification speed and localization joint venture formation.
Within the multinational tier, KUKDO Chemical, Hexion, and Arkema exemplify contrasting strategic postures. KUKDO Chemical occupies a position anchored to regional production footprint advantages for volume construction applications. Hexion sits within the premium segment specialization, representing archetype positioning around high-performance industrial and aerospace-grade systems. Arkema exemplifies technology-led differentiation, occupying a position aligned with low-VOC and rapid-cure regulatory convergence in Gulf markets.
| Leading Market Players |
|---|
| KUKDO Chemical |
| Hexion |
| Arkema |
| BASF SE |
| Dow |
| Huntsman International |
| NAMA Chemicals |
| Mitsubishi Chemical Corporation |
| Evonik Industries |
| Others |
Supply & Pricing Matrix
EU REACH Article 31 safety data sheet alignment gates qualified supply access for premium-tier curing agent formulations across GCC import channels. Buyers without pre-qualified SASO-compliant documentation face technical barriers that compress their addressable market to basic polyamide grades with thinner margin structures.
Pricing Analysis
Bundled technical service and formulation support separates premium-grade anhydride suppliers from unbundled commodity amine traders. Three-tier pricing structure across certified industrial-grade, standard construction-grade, and economy DIY-grade levels tracks VOC compliance thresholds and cure-speed specifications. Price differentiation centers on REACH-aligned certification investment and localized blending capability. Cost compression in standard-grade aliphatic amines intensifies as Chinese import volumes expand, while electrical laminate buyers show lowest price sensitivity due to thermal performance requirements.
Supply Chain Analysis
Freight cost spikes on Asia-Gulf routes amplify landed cost volatility for basic polyamide and aliphatic amine distributors serving African markets. Manufacturing concentrates in China, South Korea, and Saudi Arabia's emerging Jubail petrochemical corridor. Feedstock draws from benzene derivatives, ethyleneamines, and dimer fatty acids. Single-source vulnerability runs through concentrated East Asian producers for cycloaliphatic amine precursors. Distribution runs through regional compounders in Jubail and Ruwais with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa epoxy curing agents market reads as a late-cycle quality story as Saudi Aramco and ADNOC downstream specifications migrate toward pre-approved supplier lists with stringent thermal performance and VOC compliance requirements.
For Market Incumbents: Extend SASO pre-qualification pipelines to capture specification authority migration toward asset owner engineering departments. Threat substitution from waterborne epoxy emulsion technologies demands accelerated low-VOC amine adduct development. Backward integration into captive ethyleneamine production in Jubail Industrial City defends margin position against feedstock volatility. For New Entrants and Emerging Players: Enter via Nigerian industrial corridor localization partnerships serving Dangote Refinery-associated coatings demand. White-space concentrates in West African blending operations and Egyptian shipyard maintenance cycles. Most penetrable segment: ambient-cure polyamide systems for Suez Canal hull recoating specifications. Go-to-market angle: automated mixing system partnerships reducing on-site labor skill dependency. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with SASO pre-qualification assets because specification authority concentration compresses approved supplier lists and creates local monopoly rents. Long-term viability frames around 5-10 year industrial chemical self-sufficiency mandates across GCC states. Acquisition target archetype: Jubail-based formulators with captive laboratory and regulatory affairs infrastructure. Signal to watch: Saudi Aramco master specification updates mandating single-component adducted amine systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethyleneamine Feedstock | Jubail-based producers secure margin control against benzene derivative volatility. |
| SASO Pre-Qualification Acceleration | REACH-aligned dossier submission compresses market entry timelines for novel chemistries. |
| Single-Component Adducted Amine Launch | Precast concrete producers pilot snap-cure systems eliminating on-site mixing errors. |
| Nigerian Localization Joint Venture | Dangote Refinery corridor creates first-mover blending capacity for West African coatings demand. |
| Waterborne Epoxy Convergence R&D | Low-VOC emulsion chemistry captures interior commercial flooring specifications. |
Research Methodology
Bottom-up construction and coatings demand modeling reconciled against top-down resin-curing agent production tracking forms the analytical core. Primary interviews with formulation chemists, procurement leads at Saudi Aramco and ADNOC downstream contractors, distribution channel partners in Egyptian shipyards, and technical R&D directors at regional compounders were triangulated against secondary validation. Secondary sources include customs and trade flow data, SASO technical regulation filings, SEC 10-K disclosures from multinational chemical producers, and ACC regional capacity reports.
Historical trendline analysis across amine-based, anhydride, and polyamide product categories established baseline consumption patterns. The projection framework segments by curing mechanism, application tier, and end-user procurement sophistication. CAGRs were derived through regression analysis of construction spend correlations and petrochemical cluster expansion timelines. Industry-specific forecast inputs include Neom and Red Sea Project buildout schedules and Suez Canal traffic modernization cycles.
Inputs from Saudi gigaproject engineering departments and Egyptian dry-dock operators were available through the study window; gaps in Nigerian industrial corridor consumption data introduce uncertainty bands around West African volume estimates. Forecasts reflect assumptions regarding SASO regulatory alignment speed and localization mandate enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Polyurethane Sealant Market