
 Global Footwear Adhesives Market | 2026-2036
Global Footwear Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Footwear Adhesives Market Intelligence
Europe's REACH regulation, which restricts volatile organic compounds in manufacturing, is rebalancing demand toward safer adhesive formulations. Henkel AG & Co. KGaA leverages its extensive research in water-based systems to address these new standards. H.B. Fuller Company competes on its global supply chain for hot melt adhesives, serving large-scale footwear manufacturers. Arkema specializes in advanced reactive adhesives for specialized athletic and safety footwear applications.
Footwear adhesives are specialized bonding agents formulated to join diverse shoe materials such as leather, textiles, polymers, and rubber. These products are engineered for high peel strength and flexibility to withstand the mechanical stresses of walking and running. Water-based polyurethane adhesives are displacing traditional solvent-based options due to lower VOC emissions. While sole bonding constitutes the primary application, demand for reactive adhesives is growing for attaching specialized decorative components.
Product formulation is heavily influenced by chemical safety regulations from multiple bodies. The US EPA monitors air quality standards related to solvent emissions, while China’s GB standards set specific limits for hazardous substances in consumer goods. Compliance with these frameworks, alongside the EU's REACH, is a prerequisite for market access. Future investment decisions will depend on navigating the divergent timelines and technical requirements of these key regulatory systems.
Market Dynamics
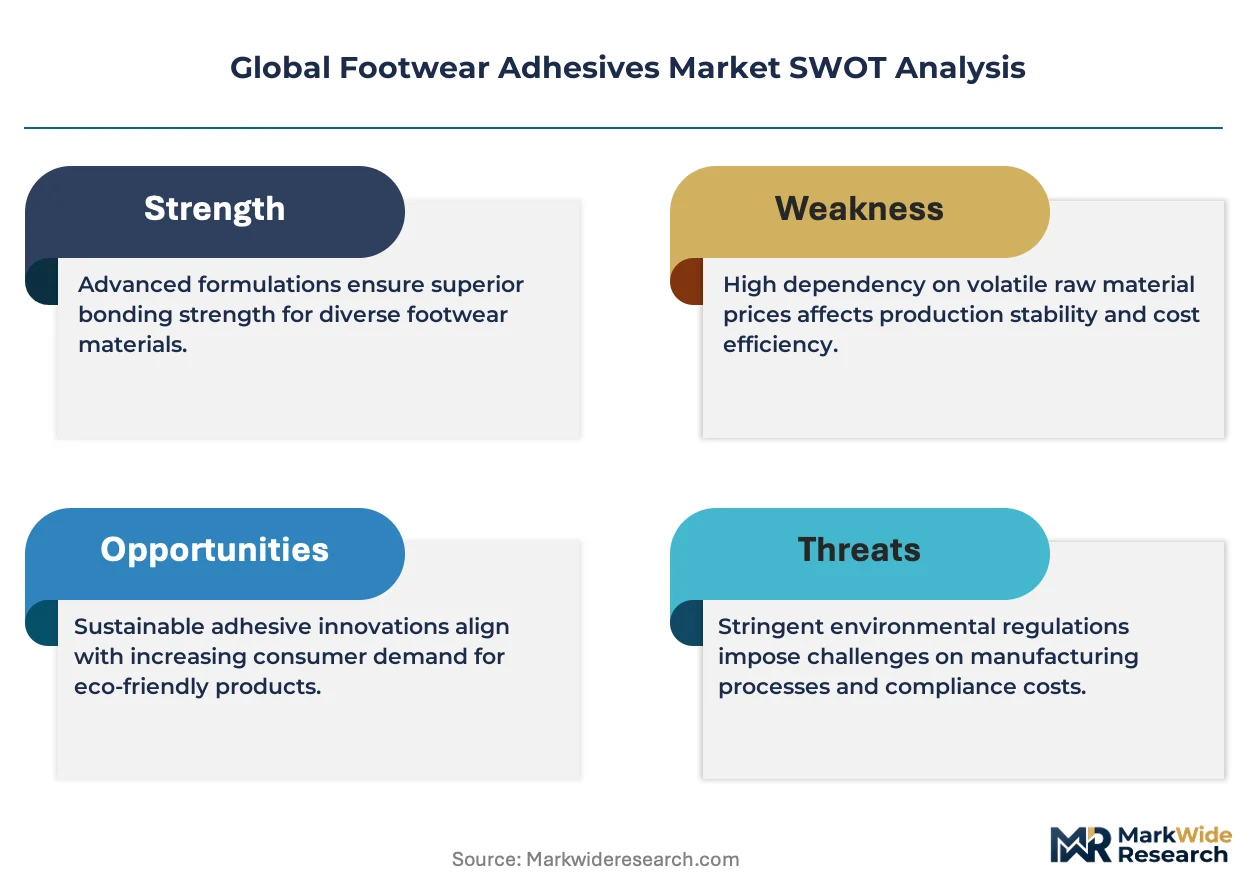
The central force shaping the footwear adhesives market is a regulatory-driven substitution away from high-VOC solvent-based products. This shift, led by frameworks like Europe's REACH, is compelling chemical innovation toward safer, compliant water-based and hot-melt formulations.
Growth Catalysts
- Performance Athletic Footwear:Demand from sports footwear producers for adhesives with high peel strength, flexibility, and durability to bond advanced polymers and technical textiles continues to expand.
- Bio-Based Formulations:Growing consumer and brand focus on sustainability is creating demand for adhesives derived from renewable resources, opening new avenues for product development and market differentiation.
- Manufacturing Consolidation:The concentration of footwear production in Southeast Asian hubs like Vietnam and Indonesia drives demand for high-volume, process-efficient adhesives suitable for automated assembly lines.
Market Restraints
- Raw Material Volatility:The market is sensitive to price fluctuations in petrochemical feedstocks, such as the isocyanates and polyols used to produce polyurethane adhesives, which can compress manufacturer margins.
- Divergent Regulatory Standards:Navigating the conflicting technical requirements and compliance timelines of the EU's REACH, China's GB standards, and US EPA rules creates significant R&D and administrative cost burdens.
- Performance Trade-offs:While safer, some water-based adhesives exhibit longer curing times or lower initial green strength compared to solvent-based incumbents, posing a barrier to adoption in high-speed manufacturing environments.
Strategic Opportunities
- Smart Footwear Integration:The emergence of footwear with embedded sensors and electronics creates an opportunity for specialized conductive or thermally managed adhesives designed to bond and protect electronic components.
- Adhesives for Circularity:Developing novel bonding agents that allow for easy, non-destructive disassembly of shoe components at end-of-life would enable footwear recycling and support circular economy business models.
- Automation-Ready Adhesives:Formulating adhesives, such as UV-curable systems, specifically for high-precision robotic application can unlock significant process efficiencies and quality improvements for large-scale manufacturers.
Industry Challenges
- Workforce Reskilling:Transitioning from traditional solvent-based cementing to water-based or hot-melt systems requires significant retraining of factory personnel on new application techniques, equipment, and quality control protocols.
- Supply Chain Adaptation:Shifting to new adhesive technologies necessitates reconfiguring supply chains, as water-based systems may have different storage requirements and shelf lives than solvent-based products.
- Qualification Delays:The lengthy process of testing and qualifying new adhesive formulations with major footwear brands can slow the introduction of innovative, more sustainable products into the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Footwear Adhesives Market |
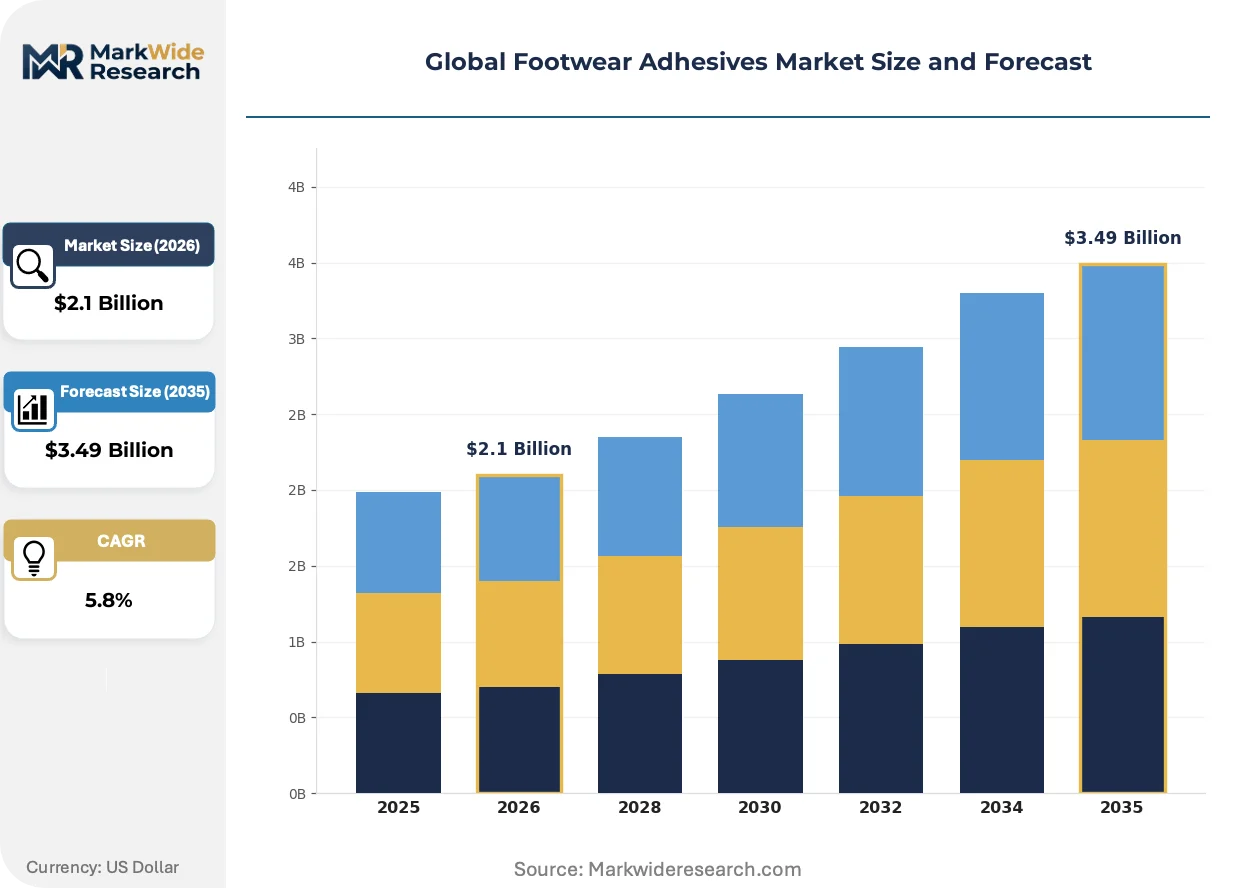
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Hot Melt, Reactive, UV Cure, Pressure Sensitive Application: Sole Bonding, Upper Attachment, Midsole Assembly, Insole Fixation, Decorative Components, Reinforcement End User: Footwear Manufacturers, Orthopedic Specialists, Custom Shoemakers, Sports Equipment Producers, Industrial Fabricators, Repair Workshops Technology: Polyurethane, Epoxy, Acrylic, Silicone, Neoprene, Styrene-Butadiene |
| Companies Covered | Sika AG, Huntsman Corporation, Henkel AG & Co. KGaA, Pidilite Industries, Jubilant Industries Ltd, H.B. Fuller Company, 3M Company, Eastman Chemical Company, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Footwear Adhesives Market Strategic Shifts & Innovations
Material science is being fundamentally reoriented by a dual focus on environmental safety and manufacturing automation. This is creating a market where adhesive performance is now defined by a balance of bond strength, regulatory compliance, and process efficiency.
Hot-melt polyurethane reactive adhesives provide a solvent-free, high-performance bonding solution. Major footwear producers in automated manufacturing environments are adopting these systems for sole attachment due to their fast setting times and strong final bonds. This technology is consolidating the supply base around providers who offer integrated systems of advanced adhesives and compatible dispensing equipment.
China's national GB standards for hazardous substances in consumer products are becoming progressively stricter. This directly compels factories across Asia that supply global brands to reformulate adhesives, eliminating restricted chemicals. The athletic footwear segment, with its use of diverse materials, is most impacted and is accelerating its shift to compliant water-based and hot-melt technologies.
Brand-led demand for supply chain transparency and verified compliance with internal restricted substances lists is a significant behavioral shift. This changes procurement criteria from a simple price-per-unit focus to a total cost of compliance, benefiting suppliers with superior regulatory support and traceability. This trend is most visible in North American and European markets where chemical safety is a key component of brand reputation.
Global Footwear Adhesives Market Segmentation
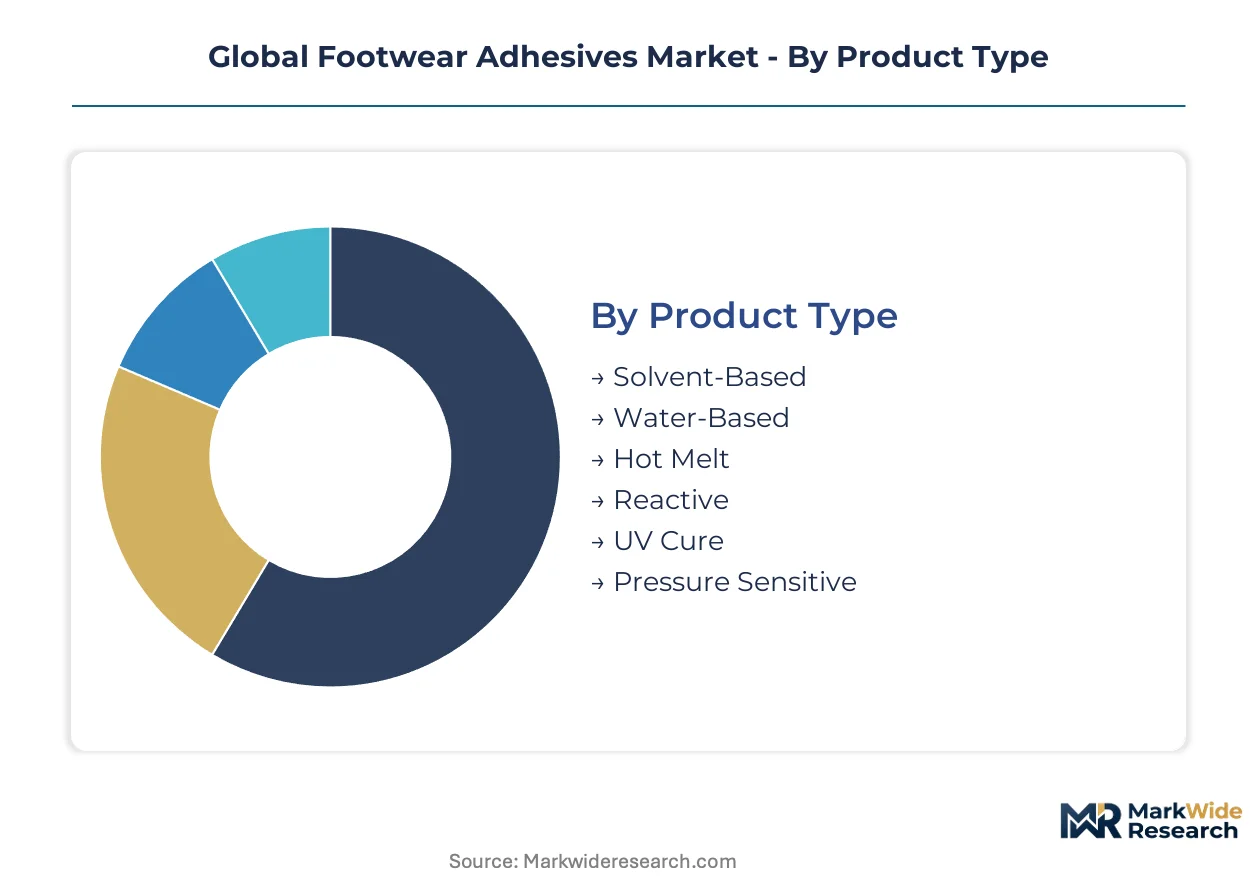
The global footwear adhesives market categorizes products and applications to address diverse manufacturing requirements and consumer demands. Understanding these segments reveals how regulatory pressures and material innovation shape product development across the industry. Each segment reflects specific performance needs and operational considerations for footwear production.
Product Type:
Product type segmentation reveals a clear shift from high-volume, cost-effective formulations to premium, high-performance solutions. Regulatory compliance and manufacturing efficiency drive demand for specific adhesive chemistries.
- Water-Based:These adhesives utilize water as a solvent, significantly reducing volatile organic compound emissions. Footwear manufacturers increasingly adopt water-based systems to comply with environmental regulations like Europe's REACH and China's GB standards.
- Hot Melt:Applied in a molten state, hot melt adhesives offer fast setting times and strong bonds without solvents. Major footwear brands use these for high-speed automated assembly lines, particularly in sole attachment processes.
- Solvent-Based:Traditional solvent-based adhesives provide high initial tack and strong bonds but contain volatile organic compounds. Their market share is declining due to environmental regulations and health concerns in manufacturing hubs.
- Reactive:Reactive adhesives form strong, durable bonds through chemical reactions, ideal for specialized athletic and safety footwear applications.
- UV Cure:UV cure adhesives polymerize rapidly under ultraviolet light, enabling fast production cycles for specific component bonding.
- Pressure Sensitive:These adhesives form a bond upon light pressure application, suitable for temporary holding or non-structural applications.
Today's leader: Water-Based. Tomorrow's challenger: Hot Melt.
Application:
Application segments highlight the functional diversity of adhesives across the footwear construction process, from core structural integrity to aesthetic detailing. Each application demands specific adhesive properties.
- Sole Bonding:This primary application requires adhesives with exceptional peel strength, flexibility, and durability to permanently attach the outsole to the upper. Advanced polyurethane formulations dominate this critical segment.
- Decorative Components:Adhesives for decorative components need precise application and strong, non-staining bonds for attaching emblems, trims, and other aesthetic elements. Reactive adhesives often provide the necessary precision for these specialized tasks.
- Upper Attachment:Adhesives for upper attachment join various materials like leather, textiles, and synthetics to form the shoe's main body. Water-based systems are gaining traction here due to their versatility.
- Midsole Assembly:Bonding multiple layers of foam and cushioning materials for the midsole requires adhesives offering cushioning compatibility and long-term resilience.
- Insole Fixation:Adhesives secure the insole within the shoe, demanding good adhesion to diverse materials and resistance to moisture.
- Reinforcement:Specialized adhesives reinforce stress points or bond protective layers, requiring high tensile strength and impact resistance.
Sole Bonding applications represent the largest volume, while Decorative Components are expanding most quickly as customization increases.
End User:
The end-user segmentation showcases varied demand drivers, from large-scale industrial production to highly specialized custom work. Each user type prioritizes different aspects like volume, customization, or specific performance needs.
- Footwear Manufacturers:This segment comprises large-scale producers of athletic, casual, and formal footwear, demanding high-volume, process-efficient adhesives for automated assembly lines. Henkel AG & Co. KGaA serves these industrial clients globally.
- Sports Equipment Producers:These manufacturers require high-performance adhesives for specialized athletic footwear, focusing on durability, flexibility, and bonding advanced technical textiles. Arkema supplies advanced reactive adhesives to this discerning segment.
- Orthopedic Specialists:Orthopedic specialists use adhesives for custom-made inserts and medical footwear, prioritizing biocompatibility and precision bonding for patient-specific solutions.
- Custom Shoemakers:Artisanal shoemakers and small-batch producers require versatile adhesives for diverse materials and intricate hand assembly processes.
- Industrial Fabricators:This category includes companies producing specialized footwear for industrial safety or specific work environments, requiring robust, chemical-resistant bonds.
- Repair Workshops:Repair services utilize a range of general-purpose and specialized adhesives for restoring damaged footwear, emphasizing strong, lasting repairs.
Footwear Manufacturers constitute the largest end-user group, whereas Sports Equipment Producers exhibit the highest growth in demand for innovative formulations.
Technology:
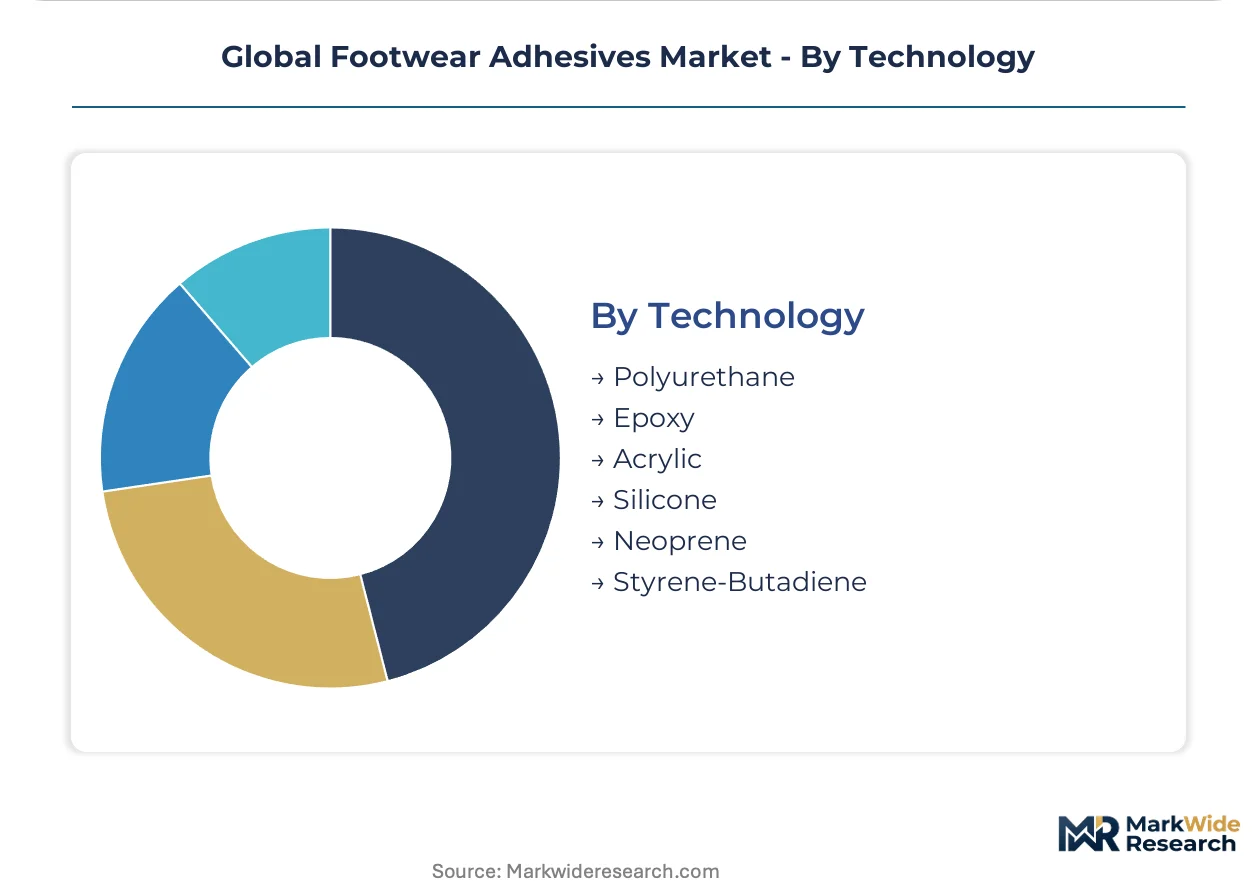
Technology segmentation highlights the chemical backbone of footwear adhesives, influencing performance characteristics, material compatibility, and regulatory compliance. Polyurethane remains a foundational technology, with acrylic and reactive systems gaining prominence.
- Polyurethane:Polyurethane adhesives offer excellent flexibility, strong adhesion to diverse substrates, and high peel strength, making them widely used for sole bonding and general assembly. Water-based polyurethane systems are displacing solvent-based versions.
- Acrylic:Acrylic adhesives provide good environmental resistance and versatility, suitable for bonding various plastics and textiles in footwear construction. Their fast curing properties are beneficial for production efficiency.
- Epoxy:Epoxy adhesives deliver high strength and rigidity, often used in specialized footwear applications requiring extreme durability or structural integrity.
- Silicone:Silicone adhesives offer flexibility, heat resistance, and waterproofing properties, suitable for specific protective or sealing applications in footwear.
- Neoprene:Neoprene-based contact adhesives provide strong initial tack and good resistance to heat and moisture, traditionally used for bonding rubber and leather.
- Styrene-Butadiene:Styrene-butadiene rubber (SBR) adhesives are cost-effective and offer good adhesion for general-purpose footwear assembly.
Polyurethane technology currently holds the largest market share, while Acrylic-based solutions are gaining share due to their versatility and performance attributes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's highly skilled workforce and established infrastructure anchor significant footwear manufacturing capacity, driving demand for advanced adhesive solutions. This concentration supports both high-volume production and specialized athletic footwear segments. Regulatory shifts and sustainability mandates influence product development across these key geographies.
Vietnam
Demand for process-efficient hot melt adhesives continues to expand for automated assembly lines. The government supports foreign investment in high-tech manufacturing through various incentives. Ho Chi Minh City and Binh Duong province host major footwear production hubs serving global brands.
China
Footwear manufacturers in China require compliant water-based and hot-melt technologies due to strict environmental standards. China’s GB standards impose stringent limits on hazardous substances in consumer goods. The Yangtze River Delta region remains a critical center for footwear production and adhesive innovation.
United States
Demand for specialized adhesives for performance athletic and safety footwear drives innovation in the US market. The US EPA monitors air quality standards related to solvent emissions, influencing formulation choices. Oregon's "Athletic & Outdoor" cluster, particularly around Portland, fosters advanced material and adhesive development.
Germany
German footwear manufacturers prioritize high-performance and environmentally compliant adhesive systems for premium and technical footwear. Europe's REACH regulation accelerates the shift away from high-VOC solvent-based products across the continent. The Pirmasens region, a historical footwear center, continues to innovate in specialized adhesive applications.
India
India's growing domestic footwear market and export ambitions create demand for cost-effective yet compliant adhesive solutions. The country's national environmental policies are gradually tightening restrictions on industrial emissions. Chennai and Agra are significant footwear manufacturing clusters driving adhesive consumption.
Global Footwear Adhesives Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the footwear adhesives market. This structure exhibits consolidation among global chemical giants and fragmentation among regional specialists. Strategic archetypes include diversified chemical conglomerates, specialized adhesive formulators, and local niche players catering to specific material requirements. Dominant competitive moves involve portfolio diversification into sustainable solutions and strategic partnerships with major footwear brands.
Diversified chemical conglomerates like Henkel AG & Co. KGaA and H.B. Fuller Company represent scale-driven players with extensive global supply chains. Henkel AG & Co. KGaA, a German AG, anchors a strong position through its broad product portfolio. H.B. Fuller Company, a US-based company, excels in hot melt adhesive systems for large-scale footwear manufacturers. Arkema, a French public limited company, exemplifies specialization in advanced reactive adhesives for technical footwear applications.
| Leading Market Players |
|---|
| Sika AG |
| Huntsman Corporation |
| Henkel AG & Co. KGaA |
| Pidilite Industries |
| Jubilant Industries Ltd |
| H.B. Fuller Company |
| 3M Company |
| Eastman Chemical Company |
| Arkema |
| Others |
Cost & Logistics Intelligence
Water-based adhesive adoption, driven by environmental regulations, is simultaneously reshaping manufacturing cost economics and concentrating supply chains around compliant chemical producers. This transition influences both material procurement and final product pricing for footwear manufacturers.
Pricing Analysis
Contract-based long-term offtake pricing structures dominate the footwear adhesives market for large manufacturers. Price differentiation stems from specialized performance attributes like high peel strength for athletic footwear and regulatory compliance certifications for European markets. Pricing pressure stems from raw material volatility, particularly in petrochemical feedstocks, impacting manufacturer margins. Footwear Manufacturers are highly price-sensitive due to volume, while Sports Equipment Producers prioritize performance and are less sensitive.
Supply Chain Analysis
Reverse logistics for footwear adhesives currently focus on waste management rather than material recovery, reflecting the non-disassemblable nature of many current bonds. Geographic supply concentration for adhesive production centers on chemical manufacturing hubs in Germany, the United States, and China. The supply chain relies heavily on petrochemical feedstocks like isocyanates and polyols. Commodity price volatility presents a significant structural risk. Distribution runs through a network of specialized chemical distributors and direct sales to large footwear manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The footwear adhesives market acts as a regulatory compounder, with Europe's REACH regulation driving continuous innovation toward safer, compliant formulations. This framework necessitates ongoing adaptation across the value chain.
For Market Incumbents:Deepen research and development into advanced bio-based and UV-curable adhesive systems to counter the threat of stricter environmental regulations. Invest in capacity expansion for water-based polyurethane systems in key manufacturing hubs like Vietnam to maintain market share. Strengthen existing relationships with major footwear manufacturers by offering integrated solutions, including dispensing equipment and technical support, to defend against new entrants.
For New Entrants and Emerging Players:A price-point gap exists between high-performance specialized adhesives and basic commodity formulations, offering an entry point for innovative solutions. Target the rapidly expanding decorative components application segment, which benefits from customization trends. The most penetrable segment remains small-to-medium custom shoemakers and repair workshops, where versatility and lower volume pricing are valued. Offer flexible packaging and application support as a primary go-to-market angle.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional specialists offering traditional solvent-based products, presenting an opportunity for strategic pivots. The market exhibits long-term viability, driven by continuous material innovation and regulatory shifts over the next decade. Target acquisition profiles should focus on companies with strong R&D in water-based or hot-melt polyurethane technologies. Monitor the pace of new compliance mandates in emerging footwear manufacturing regions for early signals of market disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based Adhesive R&D | Develop sustainable alternatives to petrochemical-derived adhesives, appealing to brands with strong ESG commitments. |
| Expand Water-Based Production Capacity | Meet growing demand from Asian manufacturing hubs like Vietnam complying with environmental standards. |
| Form Strategic Partnerships with Robotics Firms | Integrate UV-curable adhesives with automated dispensing equipment for high-speed assembly lines. |
| Acquire Reactive Adhesive Specialists | Enhance portfolio for high-performance athletic footwear applications, a segment with high growth. |
| Develop Disassemblable Bonding Solutions | Enable footwear recycling and support circular economy models, addressing brand sustainability goals. |
Research Approach
Coverage spans Asia-Pacific, Europe, and North America, with primary inputs from each region informing the analysis. This involved combining in-depth interviews with R&D directors, procurement managers, and production supervisors from leading footwear manufacturers and adhesive suppliers. Secondary validation utilized customs data, chemical industry reports, and regulatory filings from the US EPA and ECHA. The approach employed both bottom-up market sizing and top-down validation.
Rate-of-change decomposition was applied to project market evolution across the analysis window, considering both volume and value drivers. The framework modeled segmentation dimensions including product type, application, end-user, and technology. Compound annual growth rates were derived through a multi-variable regression analysis. Key industry-specific forecast inputs included anticipated shifts in regulatory compliance and advancements in athletic footwear material science.
Caveats apply where unforeseen geopolitical events or rapid technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding raw material stability and the pace of regulatory enforcement. Practitioners should monitor the development of new bio-based chemistries and global trade policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Aqueous Acrylic Binders Market