
 Curing Adhesives Market | 2026-2036
Curing Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Curing Adhesives Market Intelligence
Subscription-based adhesive performance monitoring is hardening into a standard procurement requirement for tier-one automotive suppliers. Henkel AG & Co. KGaA leverages its global formulation database to anchor long-term service contracts with German OEMs. 3M Company competes through embedded sensor-compatible adhesive platforms that sustain recurring calibration revenue streams. Dow Chemical Company dominates moisture-curing silicone supply for construction customers seeking predictive maintenance add-ons.
Curing adhesives are polymer-based bonding agents that undergo irreversible chemical cross-linking through thermal, photochemical, or catalytic activation to achieve structural integrity, with epoxy systems typically delivering shear strengths exceeding 20 MPa after full cure. These materials permanently join dissimilar substrates in load-bearing assemblies where mechanical fastening introduces stress concentrations or weight penalties. Epoxy formulations occupy the highest-margin tier in electronics and aerospace bonding due to their thermal stability and dielectric performance. UV-curing acrylics represent the fastest-expanding curing method segment as electronics miniaturization demands rapid, low-temperature processing without thermal damage to sensitive components. Polyurethane adhesives lead construction applications where moisture-cure chemistry tolerates ambient humidity variability on job sites.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants restrict solvent content in industrial adhesive formulations, compelling reformulation toward 100% solids and UV-curable systems. REACH registration requirements in Europe mandate full substance toxicity documentation, raising compliance costs that favor established suppliers with dedicated regulatory affairs teams. OSHA workplace exposure limits for isocyanates in polyurethane production drive capital investment in enclosed mixing equipment and automated dispensing. Stakeholders must monitor evolving state-level green chemistry initiatives in California and New York that extend beyond federal minimums to restrict specific curing catalyst chemistries.
Market Dynamics
Automotive OEMs are systematically replacing mechanical fasteners with bonded joints to reduce vehicle weight and assembly complexity, compressing specification cycles from 18 months to under 12 months for new adhesive qualifications.
Growth Catalysts
- EPA NESHAP solvent restrictions:Industrial manufacturers face mandatory volatile organic compound reductions, forcing rapid adoption of 100% solids and UV-curable formulations in coating and assembly operations.
- Electronics miniaturization:Semiconductor packaging demands low-temperature bonding that preserves sensitive components, accelerating UV-curing acrylic specifications in consumer device manufacturing.
- German automotive specification programs:Integrated adhesive qualification systems at major OEMs lock in multi-year supply agreements with performance-guaranteed service tiers.
Market Restraints
- Epoxy resin supply concentration:Bisphenol-A and specialty amine hardener production clusters in China and Germany expose formulators to feedstock volatility and logistics disruptions.
- REACH substance documentation costs:Full toxicity dossier requirements for novel curing catalysts extend registration timelines to 24-36 months, blocking mid-tier suppliers from European market entry.
- Mechanical fastening substitution limits:Primary structural joints in heavy-load aerospace applications still require bolted redundancy, capping adhesive penetration in wing and fuselage assemblies.
Strategic Opportunities
- India construction sector expansion:Infrastructure investment and urban housing drives demand for moisture-curing polyurethanes in climate-variable job site conditions.
- EU Green Deal sustainable chemistry incentives:Bio-based epoxy hardeners and recyclable thermoset formulations qualify for preferential procurement in public infrastructure tenders.
- Embedded sensor integration:Adhesive platforms with integrated strain and temperature monitoring enable predictive maintenance service contracts in wind turbine blade manufacturing.
Industry Challenges
- Formulation chemist talent scarcity:Cross-disciplinary expertise spanning polymer science, rheology, and regulatory compliance commands premium compensation, constraining R&D team expansion.
- Multi-certification timeline compression:Simultaneous OEM qualification, FAA airworthiness approval, and automotive crash-test validation creates resource bottlenecks for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curing Adhesives Market |
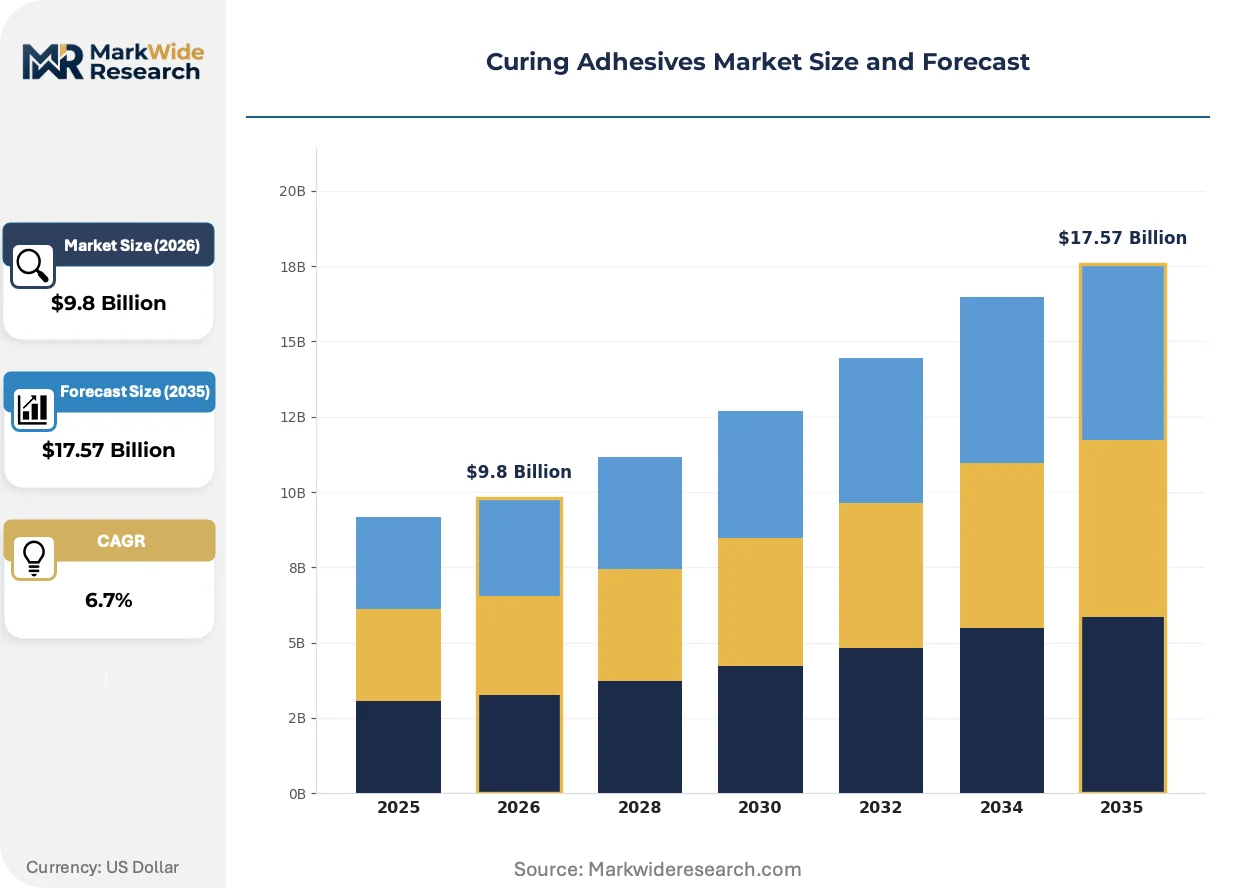
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Construction, Electronics, Aerospace Type: Epoxy, Polyurethane, Silicone, Acrylic Curing Method: Heat, UV Light, Moisture, Chemical End User: Manufacturers, Contractors, Distributors, Retailers |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Dow Chemical Company, H.B. Fuller Company, Sika AG, Dymax Corporation, Tosoh Corporation, DELO Industrie Klebstoffe GmbH & Co. KGaA, Arkema S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curing Adhesives Market Strategic Shifts & Innovations
Digital process control and closed-loop curing monitoring are compressing quality assurance cycles while enabling real-time specification compliance in high-volume manufacturing environments.
AI-driven dispensing robotics is automating bead placement and cure monitoring in automotive battery pack assembly, reducing defect rates and enabling traceable quality documentation for OEM audit requirements. Tier-one suppliers in Germany and China are deploying these systems at scale. The technology is automating manual inspection steps that previously required 15-20% of line labor.
REACH authorization requirements for diisocyanates in polyurethane production mandate enhanced worker protection protocols and exposure monitoring across European manufacturing facilities. Industrial users must implement enclosed mixing systems and medical surveillance programs. Construction adhesive applicators in France and Germany face the steepest compliance cost increases.
Subscription-based performance monitoring contracts are displacing traditional spot-buy procurement in tier-one automotive supply chains. Adhesive suppliers now bundle formulation supply with continuous shear-strength testing and environmental degradation tracking. This model concentrates in German OEM supply bases where long-term service integration anchors supplier relationships.
Curing Adhesives Market Segmentation
Curing adhesives serve divergent performance requirements across bonding applications. Segmentation reveals where formulation complexity commands premium pricing versus where commodity chemistry dominates procurement decisions.
Application:
Volume concentrates in construction and automotive, while premium margins accrue to electronics and aerospace specifications.
- Automotive:Bonded assembly lines at German OEMs and Chinese EV manufacturers drive structural adhesive specifications for lightweight chassis and battery enclosures. Specification cycles have compressed to under 12 months as mechanical fastener replacement accelerates.
- Construction:Moisture-curing polyurethanes dominate climate-variable job sites in India and Germany where ambient humidity tolerance determines application windows. Infrastructure investment and urban housing expansion sustain volume demand despite regulatory pressure on isocyanate exposure.
- Electronics:Semiconductor packaging and consumer device miniaturization demand low-temperature processing without thermal damage to sensitive components.
- Aerospace:Primary structural joints in wing and fuselage assemblies still require bolted redundancy, capping adhesive penetration despite high performance specifications.
Today's leader: Construction. Tomorrow's challenger: Electronics.
Type:
Epoxy formulations anchor the premium tier through thermal stability and dielectric performance, while polyurethane and silicone compete on cost-adjusted functionality.
- Epoxy:Bisphenol-A and specialty amine hardener systems deliver shear strengths exceeding 20 MPa after full cure. Electronics and aerospace bonding specifications lock in multi-year supply agreements with performance-guaranteed service tiers at German OEMs.
- Polyurethane:Moisture-cure chemistry tolerates ambient humidity variability on construction job sites. REACH authorization requirements for diisocyanates mandate enhanced worker protection protocols across European manufacturing facilities.
- Silicone:Moisture-curing formulations dominate construction applications seeking predictive maintenance add-ons and weathering resistance.
- Acrylic:UV-curing systems represent the fastest-expanding type segment as electronics miniaturization demands rapid processing capabilities.
Epoxy commands the margin premium. Acrylic is climbing the fastest on volume expansion.
Curing Method:
Customer procurement patterns separate high-volume heat-cure operations from precision UV applications where defect costs dominate total cost of ownership.
- Heat:Thermal activation systems remain the baseline for structural bonding in automotive and aerospace where cure completeness validates airworthiness and crash-test requirements.
- UV Light:Photochemical curing enables rapid, low-temperature processing without thermal damage to sensitive semiconductor components. AI-driven dispensing robotics is automating bead placement and cure monitoring in automotive battery pack assembly.
- Moisture:Ambient humidity activation dominates construction job sites and field repair applications where controlled heating is impractical.
- Chemical:Catalytic activation systems serve specialized industrial applications requiring room-temperature cure with extended working times.
Heat cure retains the volume base. UV light is gaining share fastest on electronics demand.
End User:
Direct manufacturer relationships concentrate specification power, while distributor and retail channels serve fragmented maintenance and repair demand.
- Manufacturers:Tier-one automotive suppliers and electronics OEMs operate integrated adhesive qualification programs that lock in multi-year supply agreements. Subscription-based performance monitoring is hardening into a standard procurement requirement.
- Contractors:Construction applicators in France and Germany face the steepest REACH compliance cost increases for diisocyanate exposure monitoring and medical surveillance programs.
- Distributors:Technical distribution channels bridge formulation suppliers with mid-tier manufacturers lacking dedicated materials engineering staff.
- Retailers:Consumer and small-contractor sales concentrate in general-purpose epoxy and polyurethane formulations with standardized packaging and application instructions.
Manufacturers dictate specifications. Contractors represent the regulatory pressure point.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's integrated adhesive qualification programs contrast with India's fragmented contractor-driven procurement, illustrating how specification power concentrates in automotive OEM clusters while construction demand disperses across emerging markets.
United States
Automotive battery pack assembly lines and aerospace structural bonding sustain premium epoxy demand. EPA NESHAP regulations restrict solvent content in industrial formulations, accelerating UV-curable system adoption. Detroit and Seattle manufacturing corridors anchor specification relationships with tier-one suppliers.
Germany
Integrated adhesive qualification programs at major OEMs compress specification cycles below 12 months. REACH authorization requirements for diisocyanates mandate enhanced worker protection protocols in polyurethane production. The Stuttgart and Munich automotive clusters lock in multi-year supply agreements with performance-guaranteed service tiers.
China
EV manufacturers expand bonded chassis and battery enclosure assembly to reduce vehicle weight. MEE enforcement of volatile organic compound limits tightens solvent-based formulation production permits. Shanghai and Shenzhen electronics corridors drive UV-curing acrylic specifications for semiconductor packaging.
India
Infrastructure investment and urban housing expansion sustain moisture-curing polyurethane volume in climate-variable job sites. BIS certification requirements for construction chemicals create compliance barriers for imported formulations. Mumbai and Delhi construction markets concentrate contractor procurement despite regulatory fragmentation.
Japan
Semiconductor packaging miniaturization demands low-temperature bonding without thermal damage to sensitive components. METI industrial standards guide adhesive performance specifications in electronics manufacturing. The Osaka-Kyoto-Kobe manufacturing belt anchors precision UV-curing system deployment.
Curing Adhesives Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with formulation complexity determining margin capture. The vendor base organizes around three archetypes: diversified chemical conglomerates with global regulatory affairs infrastructure, mid-cap adhesive specialists with OEM-embedded service contracts, and regional formulators competing on cost-adjusted functionality. Consolidation pressure intensifies as REACH documentation costs and multi-certification timelines favor established players with dedicated compliance teams. Strategic moves concentrate on backward integration into specialty amine hardener supply and technology licensing partnerships for UV-curing platform expansion.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow Chemical Company exemplify the regulatory infrastructure archetype, occupying positions where formulation databases anchor long-term OEM relationships. 3M Company represents the embedded-technology tier, with sensor-compatible platforms enabling recurring service revenue streams. These three entities illustrate how scale and specification integration concentrate competitive advantage in tier-one automotive and electronics supply chains.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Dow Chemical Company |
| H.B. Fuller Company |
| Sika AG |
| Dymax Corporation |
| Tosoh Corporation |
| DELO Industrie Klebstoffe GmbH & Co. KGaA |
| Arkema S.A |
| Others |
Cost & Logistics Intelligence
Epoxy-silicone performance divergence separates premium formulations commanding multi-year service contracts from commodity polyurethanes priced on spot resin indices, with this bifurcation mapping directly onto supply chain configurations where German and Chinese specialty chemical clusters anchor high-margin tiers while regional blenders serve price-sensitive construction markets.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade epoxy resins, compressing margins for non-differentiated formulations. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified epoxies from automotive-grade polyurethanes and construction commodity silicones. Pricing pressure stems from REACH registration cost recovery requirements in Europe. Construction contractors exhibit highest price sensitivity, while automotive OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs require qualified backup suppliers for all structural adhesive tiers, fragmenting procurement across Henkel, Dow, and 3M platforms. Bisphenol-A and specialty amine hardener production concentrates in China, Germany, and the United States. Feedstock volatility in epoxy resin supply creates single-source vulnerability during logistics disruptions. Distribution runs through technical distributors bridging formulation suppliers with mid-tier manufacturers lacking dedicated materials engineering staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA NESHAP solvent restrictions compound demand for compliant formulations, transforming regulatory compliance into a recurring revenue anchor for suppliers with pre-qualified 100% solids and UV-curable platforms.
For Market Incumbents: To counter mid-tier entrants exploiting REACH documentation cost barriers, incumbents should accelerate backward integration into specialty amine hardener supply and lock in multi-year performance-monitoring contracts with German OEMs. Certification investment in FAA airworthiness approvals creates switching costs for aerospace specifications. For New Entrants and Emerging Players: Enter via India's infrastructure-driven construction sector, where BIS certification gaps create procurement friction for imported formulations and moisture-curing polyurethane demand outpaces qualified local supply. Target contractor-direct distribution bypassing fragmented technical distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH substance documentation timelines extend to 24-36 months, favoring acquisition of mid-cap specialists with existing EU regulatory dossiers and embedded OEM service contracts. Watch for diisocyanate authorization enforcement intensity as inflection indicator for polyurethane segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardener Supply | Captive amine production insulates Henkel and Dow from Chinese feedstock volatility. |
| Embedded Sensor Platform Development | 3M's strain-monitoring adhesives enable predictive maintenance subscription revenue in wind turbine manufacturing. |
| REACH Registration Dossier Acquisition | Buying mid-tier specialists with existing EU toxicity documentation accelerates market entry timelines. |
| AI-Driven Dispensing Robotics Deployment | Automated bead placement reduces automotive battery pack defect rates and satisfies OEM audit traceability requirements. |
| Bio-Based Hardener Formulation Partnership | EU Green Deal incentives reward suppliers qualifying sustainable chemistry for public infrastructure tenders. |
Research Approach
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market combining interviews with adhesive formulation chemists, automotive OEM procurement directors, construction contractor operations managers, and technical distribution channel partners. Secondary validation draws from EPA NESHAP regulatory filings, REACH substance registration databases, ECHA authorization lists, and customs trade data for epoxy resin and hardener flows. Bottom-up segment sizing triangulates against top-down chemical industry production estimates.
Rate-of-change decomposition separates volume growth from mix-shift effects across the analysis window. Segmentation dimensions include curing method, adhesive chemistry type, end-use application, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed capacity expansions and OEM specification pipeline data. Forecast inputs incorporate automotive bonded assembly line conversion rates and electronics miniaturization-driven UV-curing adoption curves.
Inputs from German automotive OEM qualification databases and Chinese EV manufacturer specification pipelines were available through the study window; gaps in Indian construction contractor procurement records introduce uncertainty bands for moisture-curing polyurethane demand estimates. Forecasts reflect documented assumptions on REACH enforcement intensity and EPA NESHAP compliance timelines. Deviation in diisocyanate authorization scope or MEE VOC permit enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market