
 India Waterproofing Solutions Market | 2026-2036
India Waterproofing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
India Waterproofing Solutions Market Insights
Multi-sourcing of polymer binders is restructuring procurement patterns across waterproofing formulators. Pidilite Industries Ltd. leverages its captive distribution network to reach tier-2 contractors directly. Sika AG anchors its position through specification-grade liquid-applied systems for commercial basements. Asian Paints Ltd. competes by extending its decorative paint dealer base into construction chemicals counters.
Waterproofing solutions encompass barrier systems applied to building substrates to prevent moisture ingress, typically formulated with bituminous compounds, acrylic polymers, or cementitious blends that achieve elastomeric elongation exceeding 200 percent. Their primary purpose is to protect structural concrete, roofing assemblies, and below-grade walls from hydrostatic pressure and climatic water damage. Membrane systems dominate value pools in commercial basements and podium slabs where long-term warranty terms command premium positioning. Liquid-applied polyurethane technology is displacing sheet membranes in complex geometries across terrace applications. Cementitious coatings sustain volume leadership in mass residential construction due to lower application skill requirements and compatibility with Indian masonry substrates.
BIS mandates for construction chemical performance standards, alongside state-level RERA enforcement on defect liability periods, are elevating certified product specification in organized real estate. The CEA's building energy codes indirectly amplify demand through cool roof membrane requirements in commercial developments. Stakeholders must monitor how evolving green building council ratings and municipal rainwater harvesting mandates reshape product performance specifications and installation protocols.
Market Dynamics
Multi-sourcing of polymer binders is restructuring procurement patterns across waterproofing formulators, while BIS certification requirements and state-level RERA enforcement on defect liability periods elevate certified product specification in organized real estate. These forces compress margins for uncertified suppliers while rewarding specification-grade system providers.
Growth Catalysts
- Monsoon Severity in Western States:Maharashtra, Gujarat, and Karnataka accelerate building envelope investments as rainfall intensity damages untreated concrete structures.
- CEA Building Energy Codes:Cool roof membrane requirements in commercial developments indirectly amplify demand for reflective waterproofing systems.
- Liquid-Applied Polyurethane:Terrace applications favor this technology for complex geometries where sheet membranes fail to conform.
Market Restraints
- Petrochemical Price Volatility:Acrylic polymer and polyurethane resin costs fluctuate with crude oil derivatives, squeezing formulator margins.
- Import Dependence for Specialty Additives:Silane-modified polymers and high-grade bitumen modifiers concentrate supply in Southeast Asian chemical hubs.
- Cementitious Performance Ceiling:Elongation below 15 percent limits crack-bridging capability versus elastomeric alternatives.
Strategic Opportunities
- Tier-2 Contractor Direct Access:Captive distribution networks bypass traditional dealer channels to reach smaller builders in secondary cities.
- Green Building Council Ratings:LEED and IGBC point systems reward low-VOC and recycled-content membranes with specification preference.
- Rainwater Harvesting Mandates:Municipal requirements in Bangalore and Chennai integrate waterproofed storage tanks into building designs.
Industry Challenges
- Applicator Skill Deficit:Proper membrane installation demands certified technicians, yet training infrastructure lags demand in tier-3 towns.
- BIS Certification Timelines:Product testing and approval cycles stretch 8-14 months, delaying market entry for reformulated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Waterproofing Solutions Market |
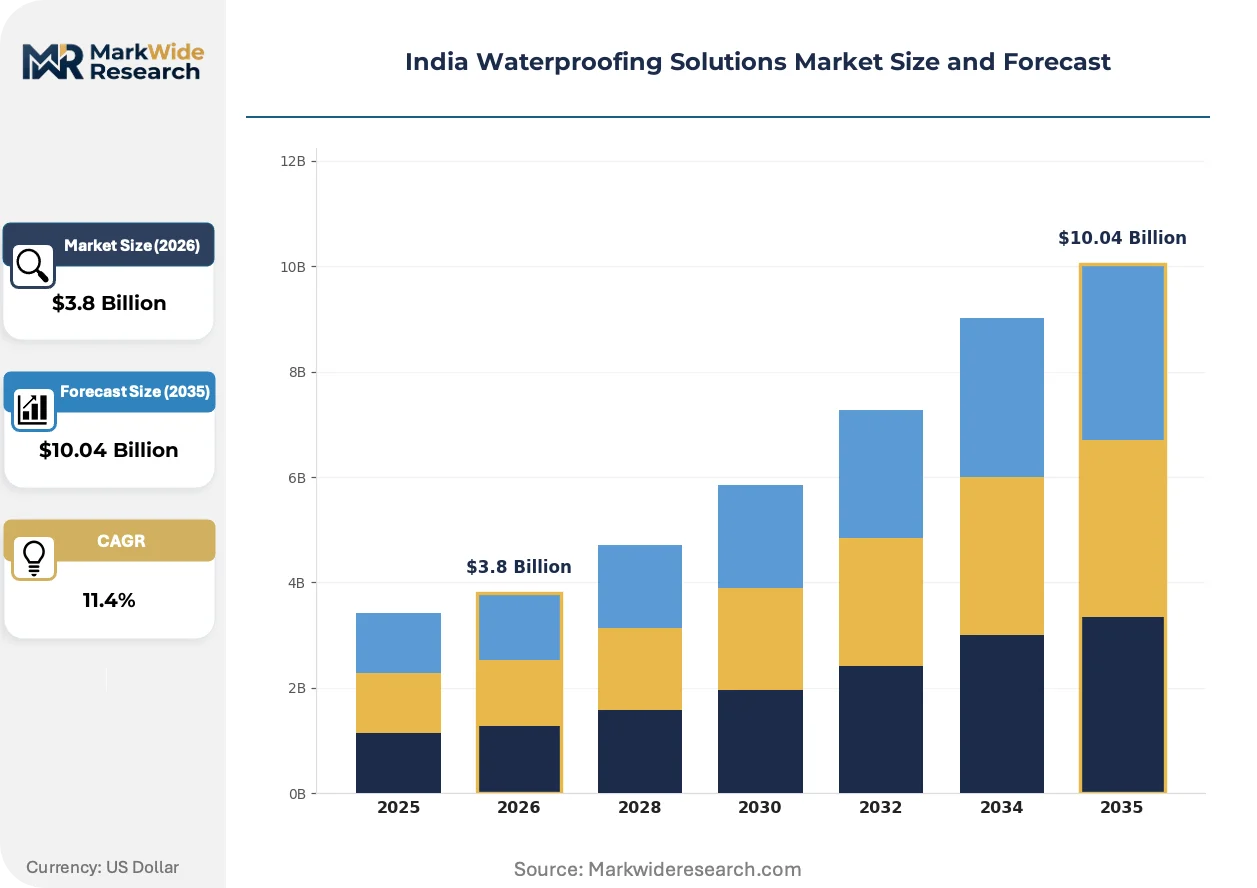
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane, Coatings, Sealants, Grouts Application: Roofing, Basements, Walls, Terraces Technology: Liquid Applied, Sheet, Cementitious, Polyurethane End User: Construction, Infrastructure, Residential, Commercial |
| Companies Covered | Pidilite Industries Ltd., Sika AG, Asian Paints Ltd., Berger Paints India, MAPEI S.p.A., Fosroc India, Dr. Fixit, Ardex Endura, Sunanda Global, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Waterproofing Solutions Market Trends and Innovations
Formulation chemistry and application methodology are converging to address India's dual pressures of monsoon severity and thermal cycling. Three developments dominate competitive positioning.
Self-healing polymer-modified bitumen is electrifying commercial basement specifications. The material autonomously seals micro-cracks through encapsulated rejuvenating agents. Large-format retail developers in Mumbai and Hyderabad specify these membranes for 10-year warranty coverage. This capability is electrifying the shift from commodity bitumen sheets to performance-guaranteed systems.
BIS construction chemical performance standards tighten product qualification thresholds. The regulator mandates elongation, adhesion, and UV resistance testing for membrane certification. Real estate developers under RERA defect liability pressure now exclude uncertified products from tender documents. Maharashtra and Karnataka project specifications reflect this compliance filter most aggressively.
Specification-grade buyers now unbundle material supply from installation service. Tier-1 contractors negotiate direct membrane procurement while retaining specialized applicators for warranty-critical work. This bifurcation fragments the traditional single-source supplier model. Bangalore commercial projects exhibit this pattern most visibly, with separate contracts for product and labor.
India Waterproofing Solutions Market Segmentation
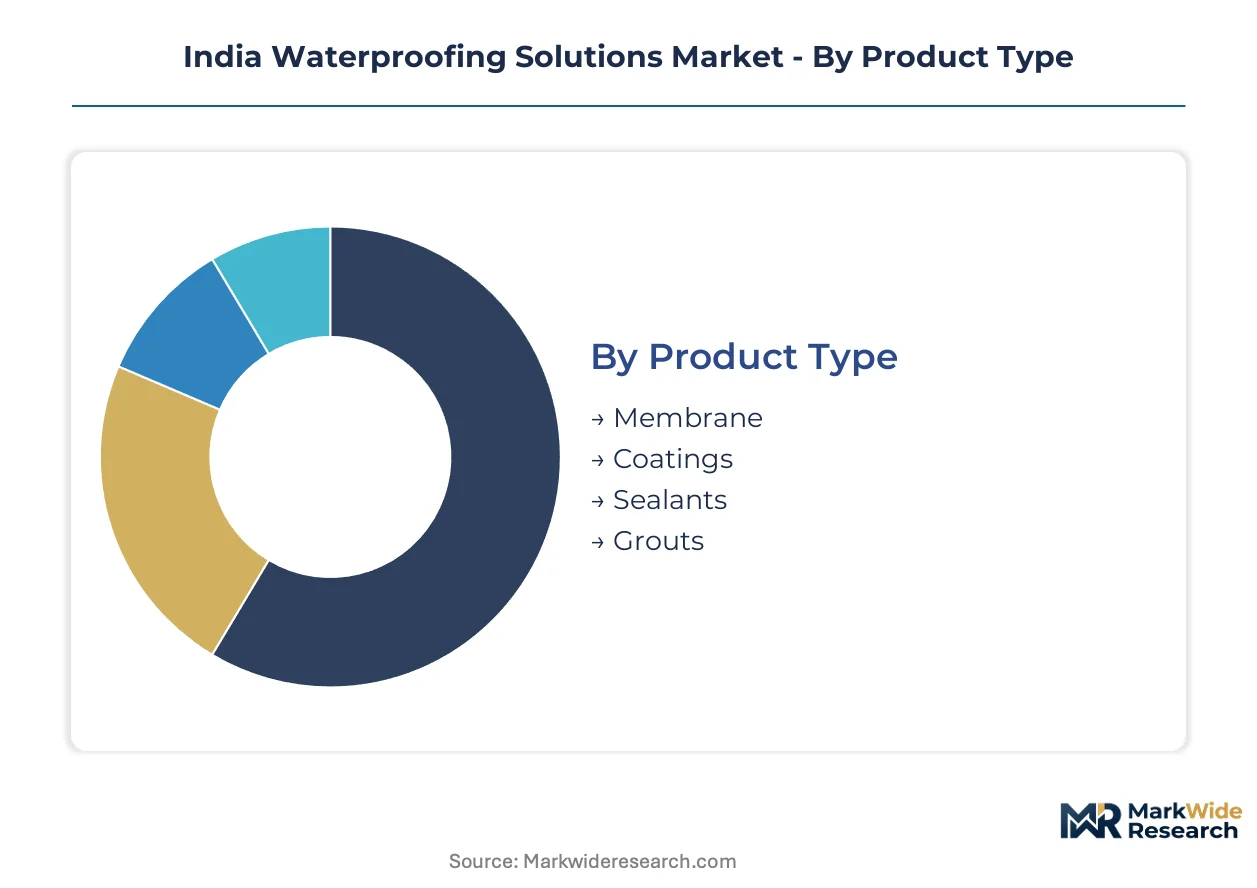
Waterproofing specification in India diverges sharply by substrate geometry, warranty duration, and applicator skill availability. Upgrade cycles from cementitious baselines to elastomeric systems now define procurement patterns across organized real estate.
Product Type:
Replacement cycles accelerate where BIS certification mandates and RERA defect liability periods intersect, pushing specifiers toward warranty-backed systems.
- Membrane:Polymer-modified bitumen and TPO sheets deliver elongation exceeding 300 percent for commercial basements and podium slabs. Maharashtra and Karnataka commercial developers specify these for 10-year warranty coverage where hydrostatic pressure demands crack-bridging assurance.
- Coatings:Acrylic and polyurethane liquid systems conform to complex geometries on terraces and irregular substrates. Bangalore residential towers favor these for ease of application on curved surfaces where sheet membranes fail to seal.
- Sealants:Polyurethane and silicone formulations address expansion joints and penetrations in structural concrete. Mass housing projects in Gujarat deploy these at construction joints to meet municipal water-tightness inspections.
- Grouts:Cementitious and epoxy injection systems repair existing cracks in aging structures. Mumbai rehabilitation contractors specify these for heritage building restoration where full membrane replacement proves cost-prohibitive.
Volume placements concentrate in Coatings; the faster expansion belongs to Membrane.
Application:
Geographic rainfall intensity and building typology dictate specification grade across India's construction corridors.
- Roofing:Cool roof membranes with reflective coatings dominate commercial specifications under CEA energy codes. Gujarat and Rajasthan commercial developments specify these to reduce air-conditioning loads while meeting waterproofing performance thresholds.
- Basements:Pre-applied and post-applied sheet membranes protect against hydrostatic pressure in deep excavations. Mumbai's coastal high-rises require dual-layer systems where groundwater tables sit within meters of foundation slabs.
- Walls:Cementitious brush-applied systems address above-grade masonry in mass residential construction. Tier-2 cities across Karnataka deploy these for cost containment on multi-story housing blocks.
- Terraces:Liquid polyurethane systems accommodate drainage slopes and planter boxes in mixed-use developments. Hyderabad commercial projects specify these for integrated waterproofing-landscaping assemblies.
Basements command the highest specification grade; Terraces show the steepest technology shift from sheet to liquid systems.
Technology:
Application methodology and substrate compatibility determine technology selection across India's divergent construction practices.
- Liquid Applied:Polyurethane and polyurea systems spray or roll onto complex geometries without seams. Pune automotive manufacturing facilities specify these for chemical-resistant flooring that doubles as waterproofing.
- Sheet:Prefabricated bituminous and synthetic membranes require torch or adhesive installation by certified technicians. Organized real estate in Mumbai mandates these for basement warranty compliance.
- Cementitious:Two-component acrylic-modified cement blends brush onto masonry with minimal skill requirements. Mass housing across Maharashtra uses these for cost-sensitive terrace waterproofing.
- Polyurethane:Moisture-cure and water-based formulations deliver seamless elastomeric films. Bangalore IT parks specify these for green roof assemblies where root resistance and waterproofing integrate.
Cementitious systems retain volume leadership; Polyurethane is climbing the fastest on specification-grade projects.
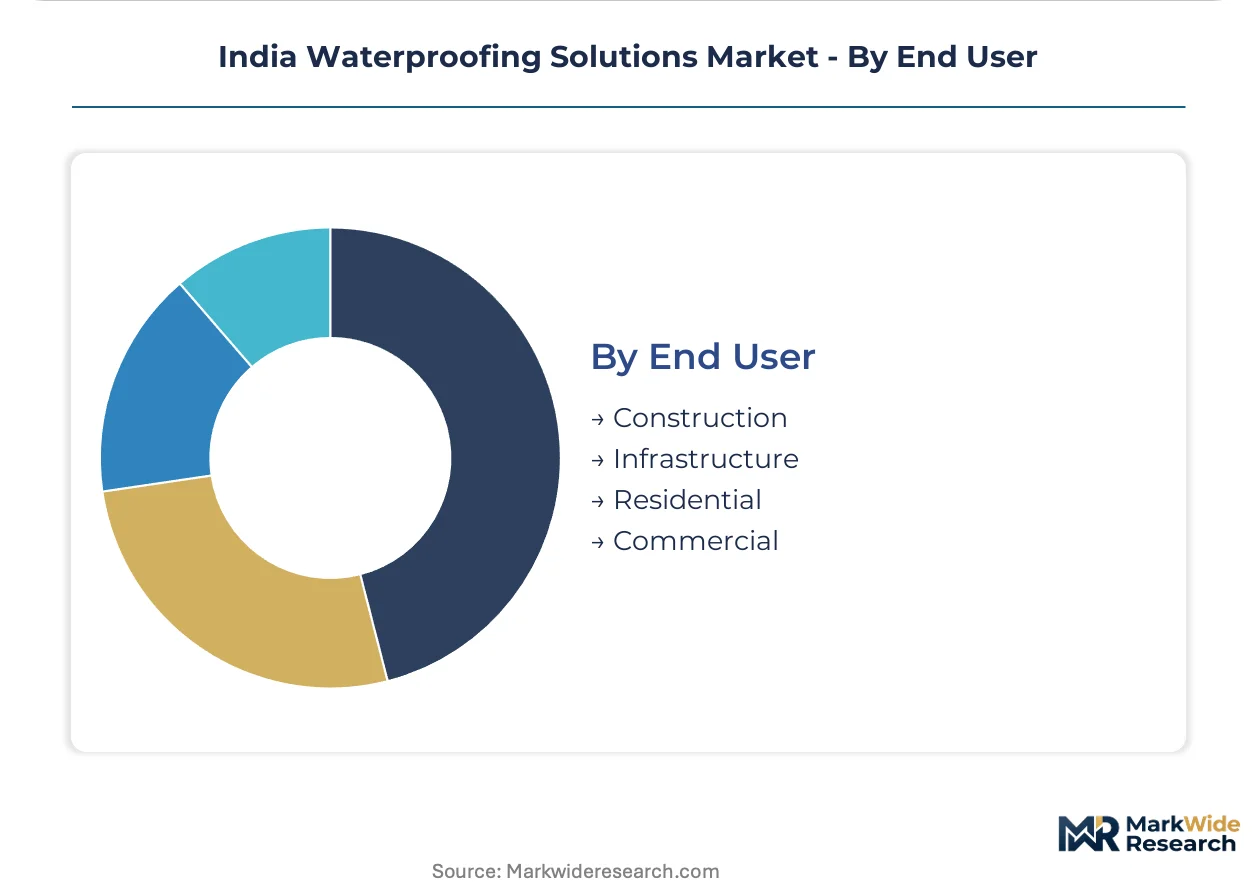
End User:
Procurement sophistication and defect liability exposure separate end-user segments across India's construction value chain.
- Construction:General contractors source certified systems for RERA-compliant residential towers. Karnataka and Maharashtra project specifications increasingly exclude uncertified products from tender documents.
- Infrastructure:Metro rail, airports, and water treatment plants specify 15-20 year performance warranties. Mumbai Metro and Bangalore Airport expansions drive membrane demand for below-grade structures.
- Residential:Individual homeowners and small builders prioritize cost over certification in unorganized markets. Tier-3 towns across Gujarat show persistent demand for economy-grade cementitious products.
- Commercial:Mall developers and office park operators specify cool roof and green building-certified systems. LEED and IGBC point systems in Hyderabad and Chennai reward low-VOC membrane selection.
Construction channels move the highest product tonnage; Infrastructure projects are expanding most quickly on a value basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bitumen feedstock from Gujarat refineries anchors waterproofing supply chains across western India. Monsoon intensity varies sharply by latitude, driving divergent specification patterns from coastal Maharashtra to inland Karnataka.
Maharashtra
Mumbai's coastal high-rises demand dual-layer membrane systems where groundwater tables sit within meters of foundation slabs. BIS construction chemical certification mandates exclude uncertified products from organized real estate tenders. The Mumbai-Pune corridor concentrates commercial basement projects specifying 10-year warranty coverage.
Gujarat
Ahmedabad and Surat commercial developments specify cool roof membranes to reduce air-conditioning loads under CEA energy codes. State-level urban development authorities enforce water-tightness inspections at construction joints. The Vadodara-Ankleshwar industrial belt drives chemical-resistant flooring specifications for manufacturing facilities.
Karnataka
Bangalore residential towers favor liquid polyurethane systems for curved terrace geometries where sheet membranes fail to seal. Municipal rainwater harvesting mandates integrate waterproofed storage tanks into building designs. The Whitefield-Electronic City corridor anchors IT park green roof assemblies requiring root-resistant waterproofing.
Tamil Nadu
Chennai's mixed-use developments specify integrated waterproofing-landscaping assemblies for podium terraces. Coastal humidity accelerates membrane degradation, elevating UV resistance requirements in procurement documents. The Sriperumbudur-Oragadam automotive cluster demands chemical-resistant flooring doubling as waterproofing.
Telangana
Hyderabad commercial projects unbundle material supply from installation service, fragmenting traditional single-source supplier models. RERA defect liability pressure pushes tier-1 contractors toward certified system providers. The Gachibowli-HITEC City corridor concentrates specification-grade liquid-applied membrane demand.
India Waterproofing Solutions Market Competitive Landscape
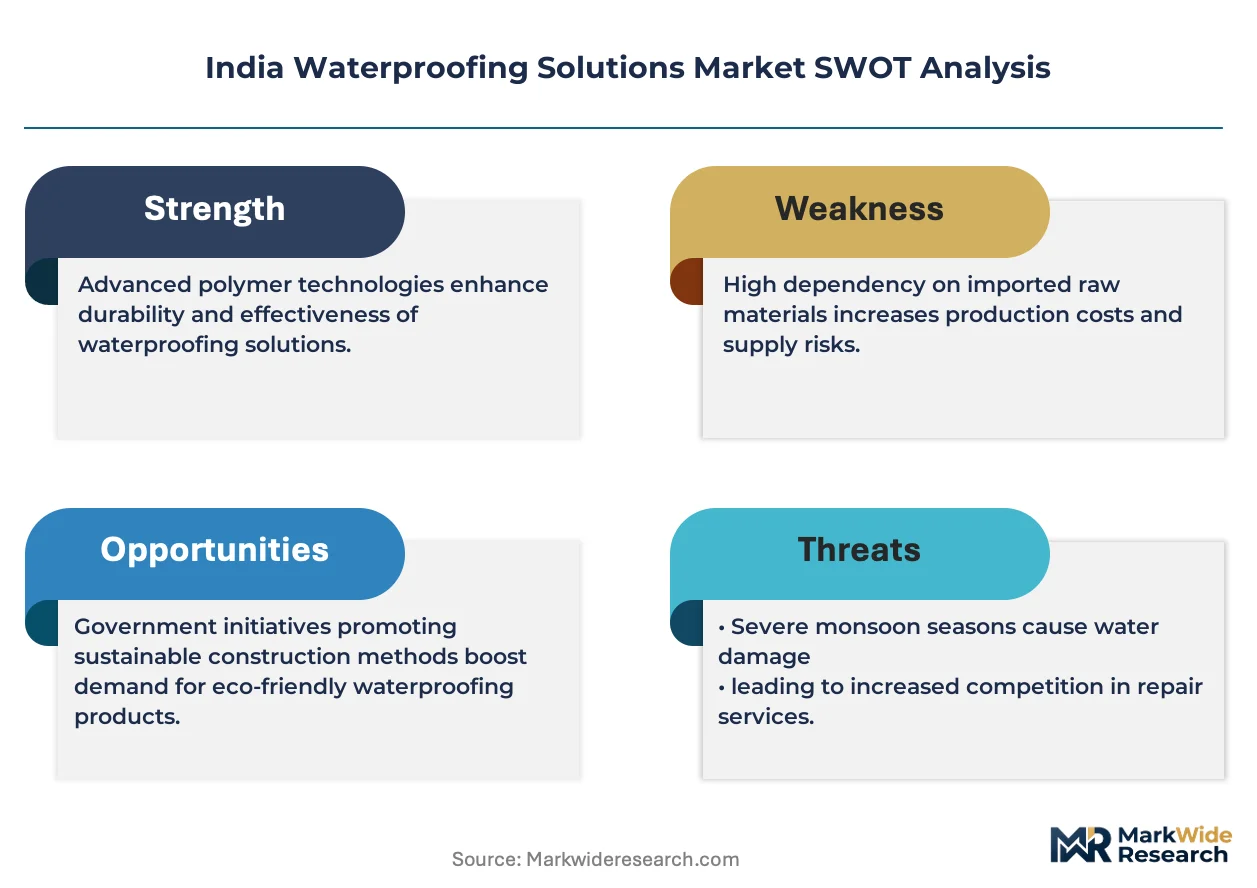
Global majors compete with regional champions across distribution reach and specification-grade system depth. The vendor base organizes into three tiers: multinational chemical conglomerates with captive R&D, domestic paint and adhesive specialists leveraging dealer networks, and regional applicator-integrators bundling labor with commodity products. Consolidation pressure intensifies as BIS certification timelines and warranty liability costs squeeze uncertified suppliers. Dominant competitive moves include backward integration into polymer binder production and direct-to-contractor distribution bypassing traditional dealer channels.
Within the multinational tier, Sika AG and MAPEI S.p.A. exemplify specification-grade system providers anchoring commercial basement and infrastructure segments. Among domestic champions, Pidilite Industries Ltd. occupies a position defined by captive distribution networks reaching tier-2 contractors directly. Asian Paints Ltd. represents the paint-specialist archetype extending decorative dealer bases into construction chemicals counters.
| Leading Market Players |
|---|
| Pidilite Industries Ltd. |
| Sika AG |
| Asian Paints Ltd. |
| Berger Paints India |
| MAPEI S.p.A. |
| Fosroc India |
| Dr. Fixit |
| Ardex Endura |
| Sunanda Global |
| Others |
Pricing and Supply Chain Analysis
IGBC and LEED certification requirements for low-VOC membranes gate both qualified supply access and premium-tier pricing power, compressing margins for uncertified formulators while rewarding specification-grade system providers with warranty-backed positioning. BIS construction chemical standards further stratify the market, as RERA defect liability pressure pushes organized real estate toward certified products that command 15-25 percent pricing premiums over commodity alternatives.
Pricing Analysis
Warranty bundling versus unbundled material supply defines the dominant pricing structure, with tier-1 contractors increasingly separating membrane procurement from specialized applicator contracts. Price differentiation rests on BIS certification grade and after-sales service depth, with certified systems capturing premium positioning. Cost compression in the cementitious tier is intensifying because of petrochemical volatility and import dependence for silane-modified polymers. Individual homeowners and small builders in tier-3 towns show the highest price sensitivity, while infrastructure developers with 15-20 year warranty requirements demonstrate the least.
Supply Chain Analysis
Refurbishment and remediation service flows for aging structures create secondary demand channels that parallel new construction supply chains. Polymer binder production concentrates in India, South Korea, and Singapore, with acrylic and polyurethane resins drawing from crude oil derivative feedstocks. Specialty additives including bitumen modifiers and silane-modified polymers hinge on Southeast Asian chemical hub capacity. Single-source vulnerability for high-grade modifiers elevates supply risk. Distribution runs through captive networks reaching tier-2 contractors directly alongside traditional dealer channels serving mass residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward control over polymer binder production separates specification-grade leaders from margin-squeezed commodity suppliers. Players are pursuing captive resin capacity to insulate formulator margins from petrochemical volatility.
For Market Incumbents: Hedge against import-dependent additive supply by securing long-term offtake agreements with Southeast Asian chemical producers or investing in domestic silane-modified polymer capacity. Cementitious coating commoditization from unorganized competitors demands reinforcement of BIS certification moats and direct-to-contractor channel control to preserve specification access in organized real estate.
For New Entrants and Emerging Players: Tier-2 contractor networks represent the most penetrable channel archetype, as incumbent dealer relationships in tier-1 cities present high switching costs. White-space targets include municipal rainwater harvesting mandates in Bangalore and Chennai, and heritage building restoration grouting in Mumbai where specialized application skills limit incumbent dominance. A specification-grade liquid-applied polyurethane launch targeting IT park green roof assemblies offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Sustained BIS certification timeline compression is the leading indicator that regulatory compliance scale will consolidate the vendor base toward integrated formulator-applicator models. The five-to-ten year viability window favors acquisition targets with captive distribution networks and certified product portfolios over pure-play commodity manufacturers. Monitor state-level RERA enforcement intensity as the primary inflection signal for certification-driven specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Binders | Captive resin capacity insulates margins from petrochemical volatility and import dependence. |
| BIS Certification Acceleration | Compressed approval timelines lock out reformulated competitors from organized real estate tenders. |
| Tier-2 Distribution Network Expansion | Direct contractor access bypasses dealer concentration in Mumbai and Bangalore corridors. |
| Green Building Certification Alignment | LEED and IGBC point systems drive specification preference for low-VOC membrane systems. |
| Applicator Training Infrastructure Buildout | Certified technician pipelines address skill deficits that constrain warranty-backed installation capacity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with waterproofing formulator R&D directors, tier-1 contractor procurement heads, municipal building code enforcement officers, and specialty chemical distributor principals. Secondary sources encompassed BIS construction chemical standards documentation, CEA building energy code circulars, state RERA authority defect liability guidelines, and import-export statistics for acrylic polymers and polyurethane resins. Bottom-up volume modeling across product types, applications, and end-user segments was cross-validated through top-down construction spending allocation analysis.
Data-stream reconciliation aligned project-level specification data with channel shipment reports and end-user procurement surveys across the analysis window. Segmentation dimensions modeled included product chemistry, application substrate, technology methodology, and regional construction intensity. CAGRs were derived from regression analysis of historical specification-grade adoption rates and forward projection of RERA enforcement trajectories. Forecast inputs incorporated monsoon severity indices and green building certification penetration curves.
Caveats apply where petrochemical price volatility, BIS certification timeline delays, or state-level regulatory enforcement gaps could materially shift the outlook. Practitioners should monitor state RERA authority staffing levels and specialty additive import tariff adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Marine Sealants Market