
 South America Epoxy Adhesives Market | 2026-2036
South America Epoxy Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Epoxy Adhesives Market Analytics
Buyer concentration among Brazilian wind turbine OEMs and Tier-1 automotive suppliers is recalibrating procurement volumes and technical specifications across the value chain. Henkel AG & Co. KGaA leverages its São Paulo technical center to sustain localized formulation support for aerospace-grade applications. Sika AG anchors its position through construction-focused distribution networks penetrating Brazil's infrastructure pipeline. Dow competes on thermally conductive variants tailored to electronics assembly in southern Brazil.
South America epoxy adhesives comprise thermosetting polymers formed from epoxide resin and polyamine hardener reactions, delivering shear strengths exceeding 20 MPa and chemical resistance for load-bearing industrial joints. These materials primarily bond metal, composite, and ceramic substrates in applications requiring dimensional stability under thermal cycling and mechanical stress. Two-part formulations dominate volume consumption due to adjustable cure profiles and room-temperature processing flexibility, while UV-curable grades capture premium positioning in electronics micro-assembly where rapid line speeds command margin premiums. Thermally conductive variants are gaining share as electric vehicle battery module assembly expands in Brazil and Argentina.
ANVISA regulates industrial chemical exposure limits and adhesive emissions standards for workplace safety and environmental release in Brazil. REACH-aligned substance restrictions from MERCOSUR technical committees shape import compliance and local formulation requirements across member states. Argentina's national chemical regulator enforces labeling and hazard communication protocols affecting cross-border product registration. Stakeholders must monitor evolving biocide restrictions and carbon border adjustment preparations affecting raw material sourcing decisions.
Market Dynamics
Brazil's ANVISA volatile organic compound emission limits are forcing adhesive formulators to reconfigure resin-hardener systems, compressing cure windows while preserving shear strength thresholds above 20 MPa for wind blade structural bonding.
Growth Catalysts
- Wind energy blade assembly:Turbine OEMs in Brazil's southeastern corridor specify high-modulus epoxy systems for carbon fiber spar cap bonding, with demand concentrated among Tier-1 suppliers in São Paulo and Minas Gerais states.
- REACH-aligned MERCOSUR technical committees:Harmonized substance restrictions across Argentina, Brazil, Paraguay, and Uruguay are streamlining cross-border product registration, reducing compliance duplication for multi-country adhesive portfolios.
- Thermally conductive formulations:Electric vehicle battery module assembly in Brazil and Argentina is pulling heat-dissipating epoxy grades into thermal interface material applications, displacing mechanical fastening in pack construction.
Market Restraints
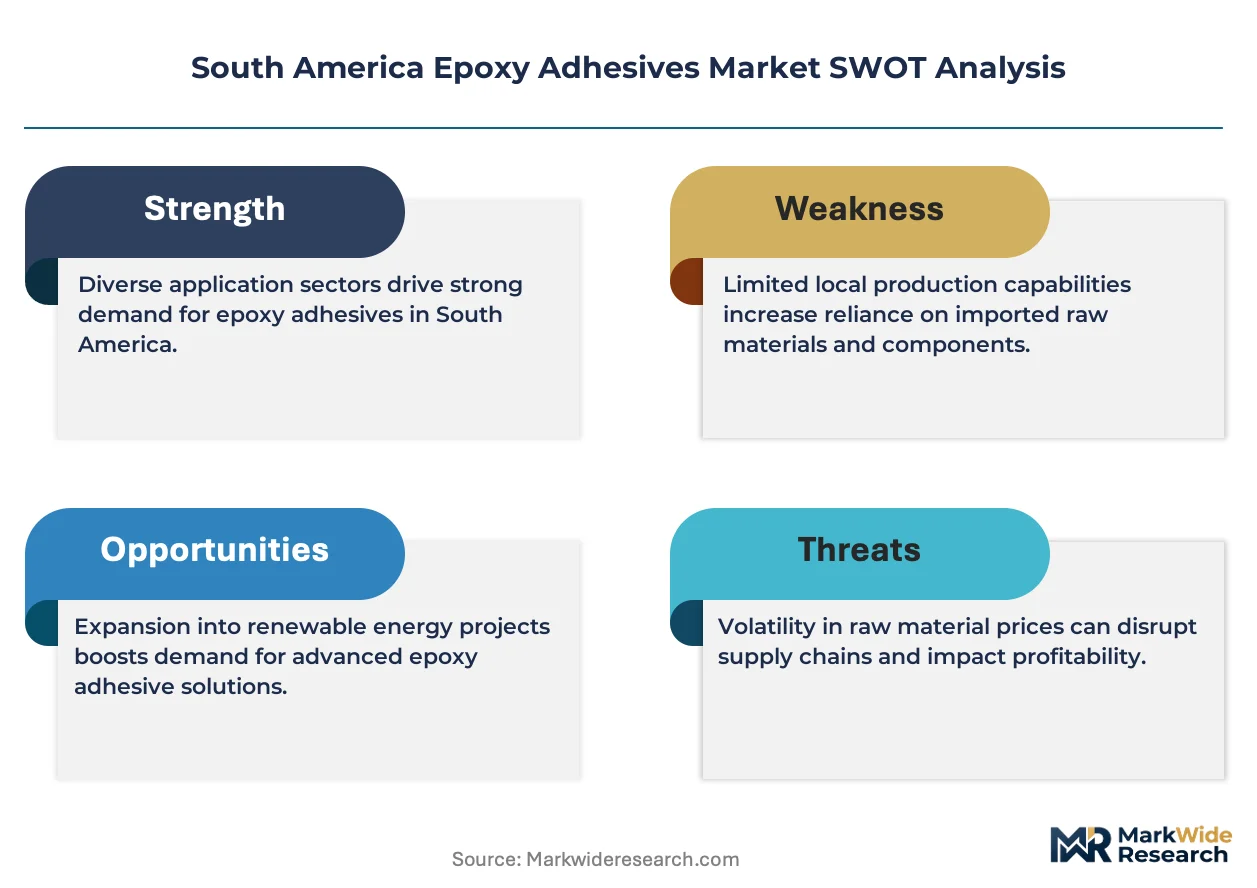
- Petrochemical feedstock volatility:Epichlorohydrin and bisphenol-A price swings tied to naphtha cracking economics in the US Gulf Coast transmit directly to South American formulation costs, squeezing margin stability for regional blenders.
- Import dependency for specialty hardeners:Aliphatic amine and anhydride curing agents concentrate among European and Asian suppliers, exposing Brazilian formulators to currency fluctuation risk and extended lead times.
- Two-part mixing precision requirements:Manual dispensing errors in field applications generate void formation and cohesive failure modes, limiting adoption in remote wind farm construction sites lacking controlled-environment facilities.
Strategic Opportunities
- Argentina's underpenetrated automotive electronics cluster:Cordoba and Buenos Aires provinces host expanding PCB assembly operations seeking UV-curable epoxy encapsulants for moisture barrier protection in sensor modules.
- ANVISA low-emission certification pathway:Early compliance with pending solvent-free adhesive standards positions formulators for preferential procurement from Brazilian aerospace maintenance, repair, and overhaul facilities.
- Construction adhesive specification convergence:Sika AG's distribution infrastructure penetration creates channel templates for structural glazing and anchoring epoxy systems in Brazil's infrastructure pipeline, enabling follower entry.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce limited polymer science graduates with epoxy rheology expertise, forcing manufacturers to recruit from European technical centers at premium compensation.
- ANVISA registration timeline compression:New adhesive product approvals now require 18-24 month toxicological review cycles, delaying revenue recognition for reformulated low-VOC grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Epoxy Adhesives Market |
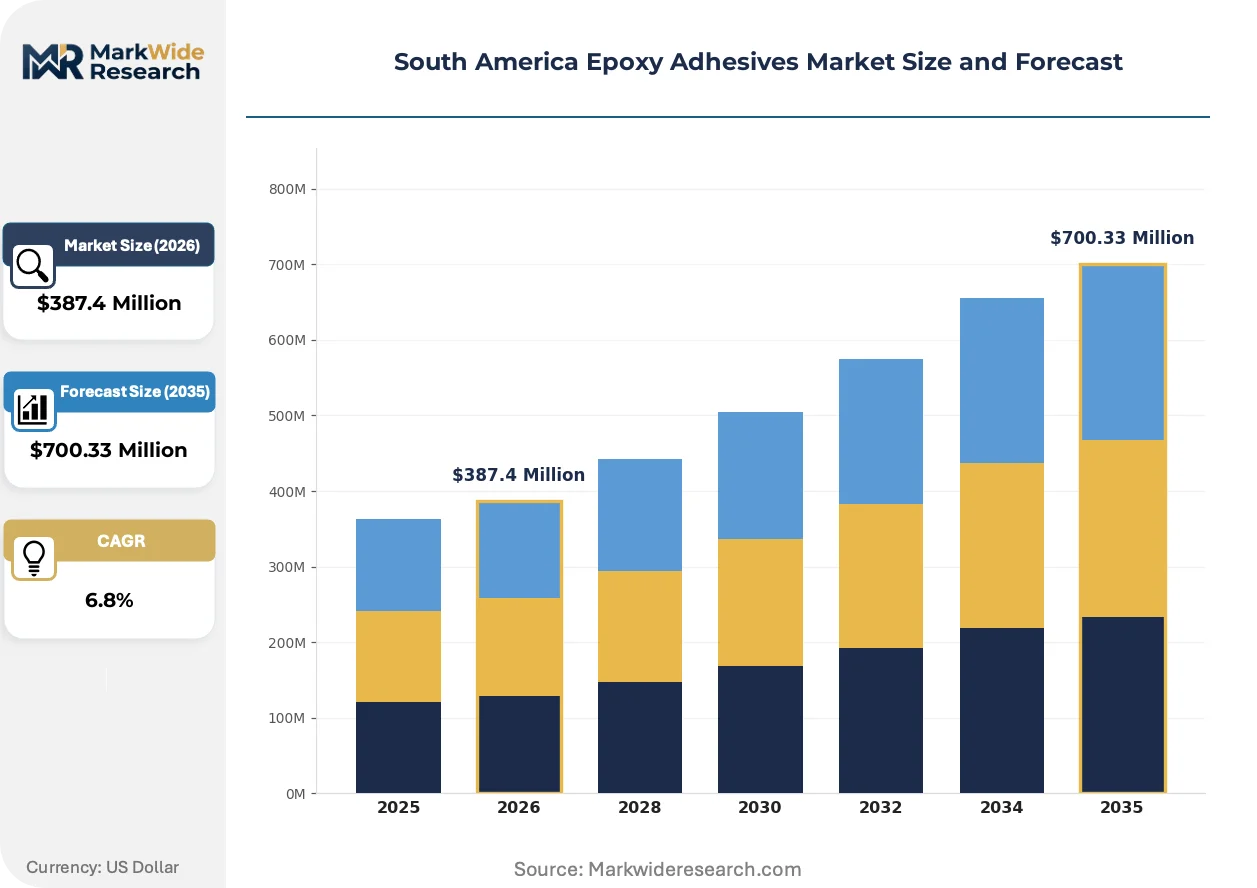
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Part, One-Part, UV-Curable, Thermally Conductive End Use Industry: Aerospace, Automotive, Electronics, Construction Form: Liquid, Paste, Film, Capsule Application: Structural Bonding, Electrical Insulation, Coatings, Potting |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Arkema Group, Huntsman International LLC, Dow, Ashland, Hexion, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Epoxy Adhesives Market Evolving Landscape
Epoxy adhesive technology in South America is converging around cure chemistry flexibility, regulatory pre-compliance, and procurement centralization among large OEM buyers. These shifts are compressing supplier margins while rewarding technical service capabilities.
Hybrid epoxy-urethane systems are unifying the load-bearing capacity of thermoset epoxies with the impact resistance of polyurethanes in wind blade root bonding applications. Vestas and Siemens Gamesa turbine assembly lines in Brazil's Ceará and Rio Grande do Norte states are qualifying these materials for lightning strike protection integration. This convergence is unifying previously separate adhesive specification categories into single-product platforms, reducing inventory complexity for blade manufacturers.
ANVISA's alignment with EU REACH substance restrictions is accelerating biocide-free hardener development for construction-grade epoxies used in Brazil's humid coastal infrastructure projects. Formulators must eliminate MIT and CMIT preservatives from two-part systems without compromising pot life stability in tropical storage conditions. Brazilian construction chemical distributors are responding by segmenting inventory into climate-zone-specific SKUs with modified amine packages.
Consolidated procurement among Brazilian wind turbine OEMs is compressing supplier qualification cycles from 24 months to 12 months while demanding captive technical service presence. Henkel AG's São Paulo technical center model is being replicated by competitors seeking specification lock-in. This concentration is most visible in the southeastern manufacturing corridor, where three OEMs control over eighty percent of annual adhesive volume for nacelle assembly.
South America Epoxy Adhesives Market Segmentation
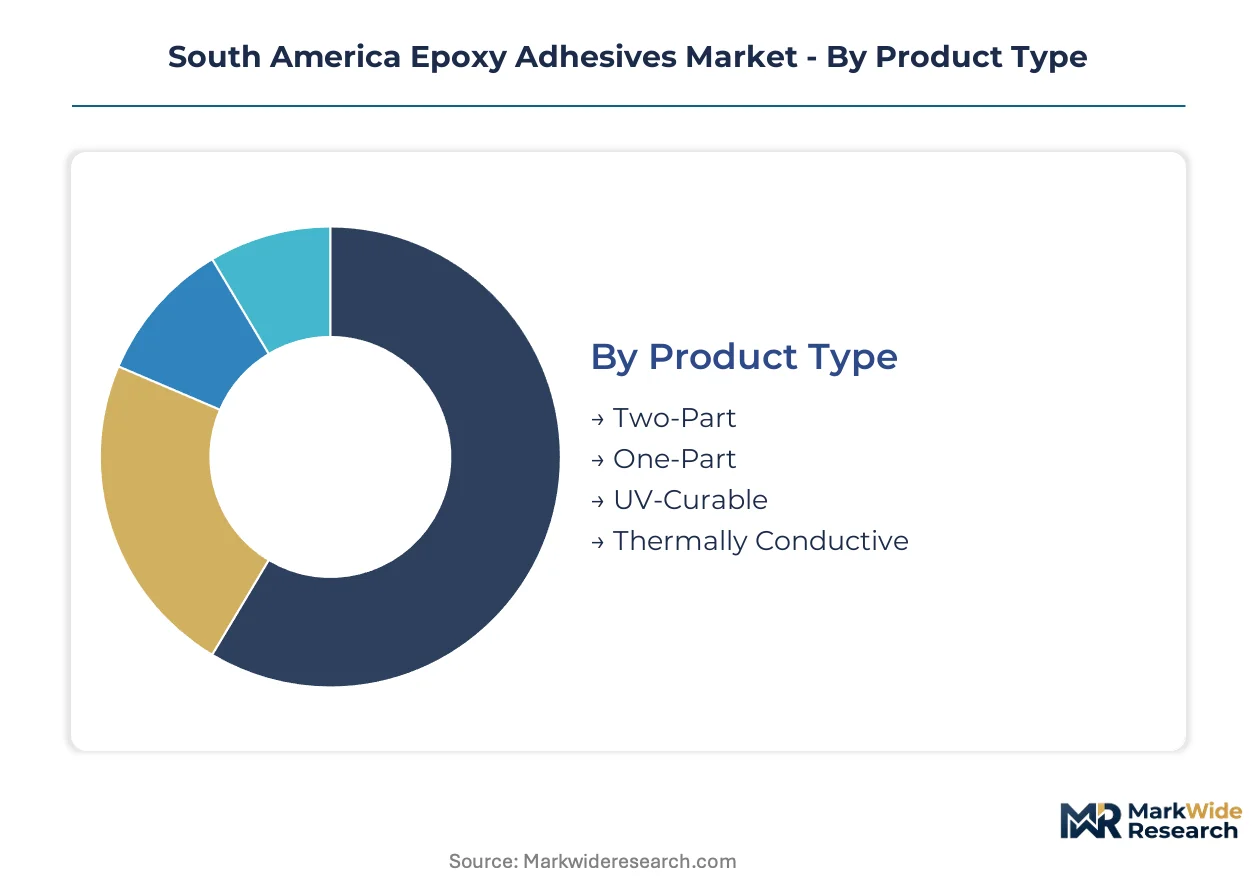
Segmentation in South America epoxy adhesives reveals how formulation chemistry, application requirements, and regulatory constraints fragment procurement patterns across industrial buyers. Understanding these divisions exposes where margin concentrates and where technical service investments yield specification lock-in.
Product Type:
Supply concentration among Brazilian formulators favors two-part systems with established hardener supply chains, while specialty curing technologies remain import-dependent.
- Two-Part:Epoxide resin and polyamine hardener systems dominate volume through adjustable cure profiles and room-temperature processing. São Paulo and Minas Gerais wind blade manufacturers specify these grades for carbon fiber spar cap bonding requiring shear strength thresholds above 20 MPa. ANVISA VOC limits are compressing cure windows while preserving mechanical performance.
- Thermally Conductive:Boron nitride or alumina-filled formulations dissipate heat in electric vehicle battery module assembly across Brazil and Argentina. These grades displace mechanical fastening in pack construction as thermal interface materials gain specification share.
- One-Part:Pre-catalyzed systems eliminate field mixing errors in controlled-environment manufacturing.
- UV-Curable:Rapid-cure grades serve electronics micro-assembly in southern Brazil where line speed commands margin premiums.
Two-Part absorbs the bulk of installed capacity; Thermally Conductive is expanding most quickly.
End Use Industry:
Customer procurement centralization varies sharply by sector, with wind energy OEMs consolidating volumes while construction remains fragmented across regional distributors.
- Automotive:Tier-1 suppliers in Brazil's southeastern corridor specify epoxy systems for structural bonding and composite joining in lightweight vehicle programs. Electric vehicle battery module assembly is pulling thermally conductive grades into thermal management applications.
- Construction:Structural glazing and anchoring applications in Brazil's infrastructure pipeline drive demand for climate-zone-specific formulations. Sika AG's distribution penetration creates channel templates for specification capture in humid coastal projects requiring biocide-free hardeners.
- Aerospace:Maintenance, repair, and overhaul facilities in São Paulo seek ANVISA low-emission certified adhesives for airframe bonding.
- Electronics:PCB assembly operations in Cordoba and Buenos Aires provinces demand UV-curable encapsulants for moisture barrier protection in sensor modules.
Construction commands the widest SKU proliferation; Automotive is climbing the fastest on electrification tailwinds.
Form:
Manufacturing process constraints and application precision requirements segment form selection across manual versus automated dispensing environments.
- Liquid:Low-viscosity grades flow into complex joint geometries in wind blade root bonding. Vestas and Siemens Gamesa assembly lines in Ceará and Rio Grande do Norte specify these for lightning strike protection integration.
- Paste:Thixotropic formulations maintain position on vertical surfaces in structural glazing and concrete anchoring. Brazilian construction chemical distributors segment inventory by tropical climate zones to preserve pot life stability.
- Film:Pre-cured sheets enable controlled-thickness bonding in aerospace composite lamination.
- Capsule:Single-dose packaging reduces mixing errors in remote wind farm construction sites lacking controlled-environment facilities.
Liquid captures the highest volume throughput; Paste is gaining share fastest on infrastructure project specifications.
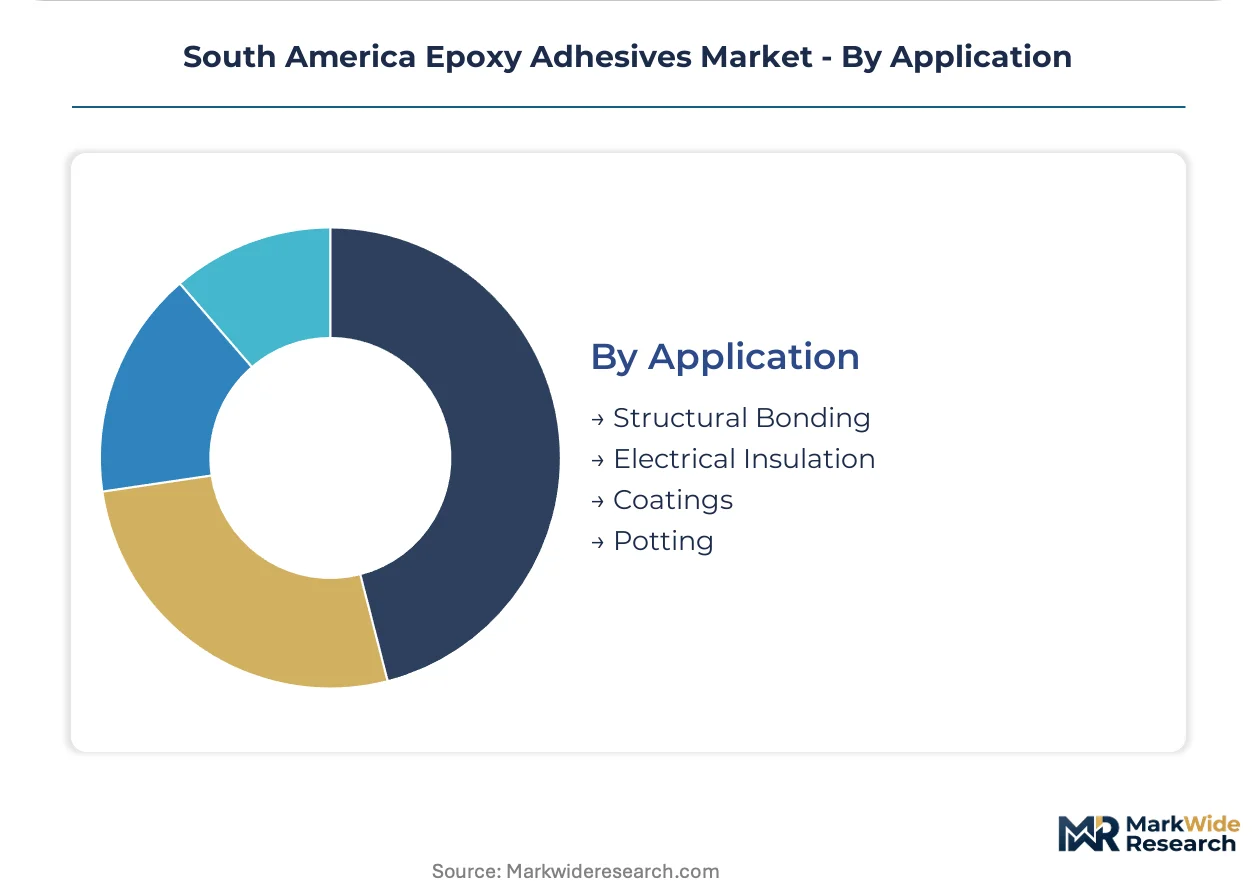
Application:
Performance requirements and failure mode consequences stratify adhesive selection across load-bearing versus protective functions.
- Structural Bonding:High-modulus systems transfer loads across dissimilar substrates in wind energy blade assembly. Hybrid epoxy-urethane formulations unify thermoset strength with polyurethane impact resistance for root bonding applications.
- Potting:Encapsulation compounds protect electronics from thermal cycling and moisture ingress in automotive sensor modules. Argentina's expanding PCB assembly cluster is pulling demand for UV-curable grades with rapid line speed compatibility.
- Electrical Insulation:Dielectric-grade formulations isolate high-voltage components in electric vehicle power electronics.
- Coatings:Protective layers deliver chemical resistance for industrial equipment in Brazil's manufacturing corridor.
Structural Bonding anchors the majority of formulation R&D investment; Potting is expanding most quickly on electronics localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along Brazil's southeastern coast anchors epoxy adhesive production capacity, with naphtha-derived epichlorohydrin supply chains clustering near Santos port logistics. Argentine formulators access bisphenol-A through Paraná River bulk chemical terminals, while Chilean distributors rely on Valparaíso maritime routes for Asian hardener imports.
Brazil
Wind turbine blade assembly in Ceará and Rio Grande do Norte states consumes high-modulus epoxy systems for carbon fiber spar cap bonding. ANVISA's volatile organic compound emission limits compress cure windows for industrial adhesives while preserving shear strength thresholds. São Paulo and Minas Gerais manufacturing corridors concentrate Tier-1 automotive suppliers specifying structural bonding solutions for lightweight vehicle programs.
Argentina
Electric vehicle battery module assembly in Córdoba and Buenos Aires provinces pulls thermally conductive epoxy grades into thermal interface material applications. The national chemical regulator enforces labeling and hazard communication protocols affecting cross-border product registration from Brazilian suppliers. PCB assembly operations in Greater Buenos Aires seek UV-curable encapsulants for moisture barrier protection in automotive sensor modules.
Chile
Mining equipment maintenance operations in Antofagasta and Santiago Metropolitan regions specify chemical-resistant epoxy coatings for industrial machinery protection. The country's environmental regulator monitors workplace chemical exposure limits for adhesive applications in copper processing facilities. Valparaíso port logistics enable distribution of European-sourced specialty hardeners to northern mining clusters.
Colombia
Infrastructure pipeline projects in Bogotá and Antioquia departments drive demand for structural anchoring and concrete repair epoxy systems. The national infrastructure agency specifies climate-zone-adapted formulations for humid tropical construction conditions. Medellín manufacturing zones host emerging automotive electronics assembly operations requiring potting compounds for thermal management.
Uruguay
Renewable energy component assembly in Montevideo and Canelones departments qualifies epoxy adhesives for wind tower auxiliary systems. MERCOSUR technical committee alignment streamlines import compliance for Brazilian-manufactured adhesive formulations. The free trade zone near Montevideo port attracts regional distribution operations serving southern cone markets.
South America Epoxy Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue thermally conductive and low-emission specialty formulations. The market structure concentrates among multinational chemical conglomerates with Brazilian technical service presence, while regional blenders compete on construction-grade volume. Three archetypes dominate: integrated petrochemical suppliers with captive resin production, construction-focused distributors with climate-zone logistics, and electronics-specialized formulators with UV-cure capabilities. Competitive moves center on ANVISA pre-compliance certification and captive technical center deployment in São Paulo state.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA, Sika AG, and Dow occupy positions reflecting distinct strategic anchors. Henkel exemplifies the technical service-intensive archetype through localized formulation support infrastructure. Sika represents construction-centric distribution penetration with climate-segmented inventory management. Dow sits within the materials science tier, competing on thermally conductive variants for electronics and electric vehicle applications. These three anchors illustrate how multinational players calibrate regional presence against regulatory pre-compliance and end-use specialization requirements.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| Arkema Group |
| Huntsman International LLC |
| Dow |
| Ashland |
| Hexion |
| Others |
Value Network & Pricing Analysis
Multinational chemical conglomerates with captive Brazilian technical centers exercise pricing discipline through volume bundling and specification lock-in, while family-owned regional blenders compete on construction-grade spot pricing. ANVISA compliance investments create tiered cost structures that separate pre-certified suppliers from reformulation laggards.
Pricing Analysis
Volume concentration among three wind turbine OEMs in Brazil's southeastern corridor squeezes margin on two-part structural bonding systems, while thermally conductive grades for electric vehicle battery assembly retain pricing power through formulation complexity. Three-tier pricing structure across aerospace-certified, industrial-standard, and construction-economy levels reflects ANVISA certification status and technical service bundling. Cost compression in standard-grade construction epoxies intensifies because of petrochemical feedstock volatility and import-dependent hardener costs. Tier-1 automotive suppliers exhibit lowest price sensitivity due to specification switching costs, while regional construction distributors negotiate aggressively on volume commitments.
Supply Chain Analysis
Brazil's local-content requirements for wind energy component sourcing reshape raw material procurement toward domestic epichlorohydrin from Santos port petrochemical clusters. Specialty aliphatic amine and anhydride curing agents draw from German and Chinese suppliers, exposing formulators to currency fluctuation risk. Single-source vulnerability concentrates in European hardener imports for aerospace-grade formulations. Distribution runs through Sika AG's climate-segmented construction networks and Henkel's technical-service-anchored direct accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's pending solvent-free adhesive standards erect a cost-of-compliance barrier that rewards early certification investment and strands non-compliant inventory. This regulatory moat favors incumbents with toxicological review expertise and dedicated regulatory affairs teams.
For Market Incumbents: To counter margin compression from petrochemical feedstock volatility, secure captive epichlorohydrin supply through backward integration into Brazilian naphtha cracking economics or long-term offtake agreements with Santos port resin producers. Simultaneously, deploy São Paulo technical center capacity to accelerate ANVISA pre-certification for low-emission grades, converting compliance lead time into specification lock-in at Brazilian aerospace MRO facilities. For New Entrants and Emerging Players: ANVISA's 18-24 month registration timeline in Brazil opens a window for Argentina's underpenetrated automotive electronics cluster, where Cordoba and Buenos Aires PCB assembly operations seek UV-curable encapsulants with shorter regulatory pathways. Target thermally conductive formulations for electric vehicle battery module assembly as the most penetrable segment, leveraging Buenos Aires province manufacturing incentives and MERCOSUR technical committee alignment for streamlined cross-border registration. For Investors and Strategic Acquirers: Distressed-cycle entries favor Brazilian construction-grade blenders with established ANVISA product registrations and climate-zone distribution infrastructure in São Paulo state. Long-term viability hinges on electrification tailwinds sustaining thermally conductive epoxy demand across the analysis window. Watch for ANVISA registration timeline compression announcements as the inflection signal for consolidation urgency among formulation specialists lacking regulatory bandwidth.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Certification Investment | Early compliance with pending solvent-free standards locks in aerospace MRO procurement preference. |
| Captive Hardener Supply Agreement | Long-term offtake with European suppliers mitigates currency exposure on aliphatic amine imports. |
| Technical Center Expansion | São Paulo formulation support infrastructure replicates Henkel's specification capture model. |
| Climate-Zone SKU Segmentation | Biocide-free hardener packages tailored to Brazil's humid coastal conditions reduce field failure rates. |
| Hybrid Epoxy-Urethane Development | Vestas and Siemens Gamesa blade root bonding qualification unifies previously separate adhesive categories. |
Research Methodology
Independent corroboration across ANVISA regulatory filings, MERCOSUR technical committee documentation, and Brazilian customs trade data underwrites the qualitative findings on formulation reformulation pressures. Primary interviews with adhesive formulators, wind turbine OEM procurement leads, and construction chemical distributors combined with secondary validation from SEC 10-K disclosures of multinational suppliers and ACC regional reports. Bottom-up volume estimates from end-use application sizing and top-down cross-checks against petrochemical feedstock consumption patterns ensure analytical consistency.
Comparable-period anchoring to historical wind energy installation rates and automotive production volumes calibrates the projection framework across the analysis window. Segmentation dimensions span product type chemistry, end-use industry procurement centralization, and regional regulatory cluster alignment. CAGRs derive from elasticity-adjusted demand curves incorporating electric vehicle battery assembly localization and ANVISA compliance cost pass-through assumptions. Forecast inputs include naphtha-derived epichlorohydrin price trajectories and hardener import dependency ratios.
Caveats apply where ANVISA registration timeline extensions or MERCOSUR substance restriction revisions could materially shift the outlook for new product commercialization. Feedstock price volatility and currency fluctuation risk on European hardener imports represent additional forecast sensitivity factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market