
 Modified Polypropylene Market | 2026-2036
Modified Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Polypropylene Market Intelligence
A capital-intensity divergence between integrated resin producers and specialized compounders is rotating competitive advantage toward those with captive polypropylene supply. LyondellBasell Industries Holdings B.V. leverages its upstream propylene integration to secure feedstock cost positions across North American and European compounding networks. SABIC anchors its modified polypropylene portfolio on high-heat automotive grades, sustaining technical partnerships with tier-one suppliers in the Middle East and Asia.
Modified polypropylene denotes base polypropylene resin chemically or physically altered through copolymerization, elastomer blending, or filler reinforcement to achieve enhanced impact resistance, thermal stability, or dimensional precision beyond standard homopolymer specifications. The material serves primarily as a lightweight structural substitute for engineering plastics and metals in injection-molded automotive components, appliance housings, and flexible packaging films. Copolymer formulations, particularly block and impact copolymers, command expanding share in automotive bumper and dashboard applications where low-temperature ductility requirements have tightened. Granule form dominates merchant sales due to compatibility with conventional extrusion and blow molding lines, though fiber-grade modified polypropylene is gaining traction in nonwoven textile applications.
REACH registration requirements and the EU F-Gas Regulation constrain additive chemistries available to European compounders, while China's GB standards and MIIT automotive material directives establish domestic performance benchmarks that foreign suppliers must meet for vehicle platform qualification. FDA food-contact regulations in the United States and EFSA migration limits in Europe shape formulation choices for packaging-grade modified polypropylene, particularly regarding nucleating agents and clarifier packages. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical recycling infrastructure investments, as these will determine which modification technologies retain cost and compliance advantages across regional supply chains.
Market Dynamics
Automotive lightweighting mandates are compressing material substitution cycles, forcing compounders to validate impact-modified grades against metal benchmarks under accelerated OEM qualification timelines.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Battery housing manufacturers in Germany and France now specify recycled-content modified polypropylene to preempt compliance costs on imported components.
- China MIIT automotive material directives:Domestic EV platforms require flame-retardant grades for battery enclosures, pulling capacity expansion from Sinopec and local compounders.
- Elasomer blending advances:Ethylene-octene copolymer compatibilization improves low-temperature ductility, opening dashboard applications previously reserved for ABS.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker margins swing with crude differentials, compressing compounder spreads when resin producers pass through less than full cost movements.
- Specialized additive supply concentration:Phosphorus-based flame retardants and nucleating agents concentrate among Japanese and German chemical suppliers, creating single-source vulnerability.
- REACH authorization bottlenecks:ECHA scrutiny of halogenated flame retardants delays formulation approvals for European automotive programs by 12-18 months.
Strategic Opportunities
- India BIS certification alignment:Appliance manufacturers seeking import substitution create demand for glass-filled grades in washing machine tubs and air conditioner housings.
- Chemical recycling feedstock integration:Pyrolysis-derived propylene enables post-consumer content claims for packaging-grade copolymers targeting EFSA migration-compliant food contact.
- Direct OEM compounding partnerships:Bypassing traditional distributor networks, compounders establish on-site satellite operations at Volkswagen, BYD, and Stellantis assembly plants.
Industry Challenges
- Automotive qualification cadence compression:OEMs now demand PPAP submission within 18 months versus historical 36-month windows, straining validation lab capacity.
- Legacy ERP integration with traceability platforms:Batch-level digital passports for recycled content require middleware development that mid-tier compounders lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Polypropylene Market |
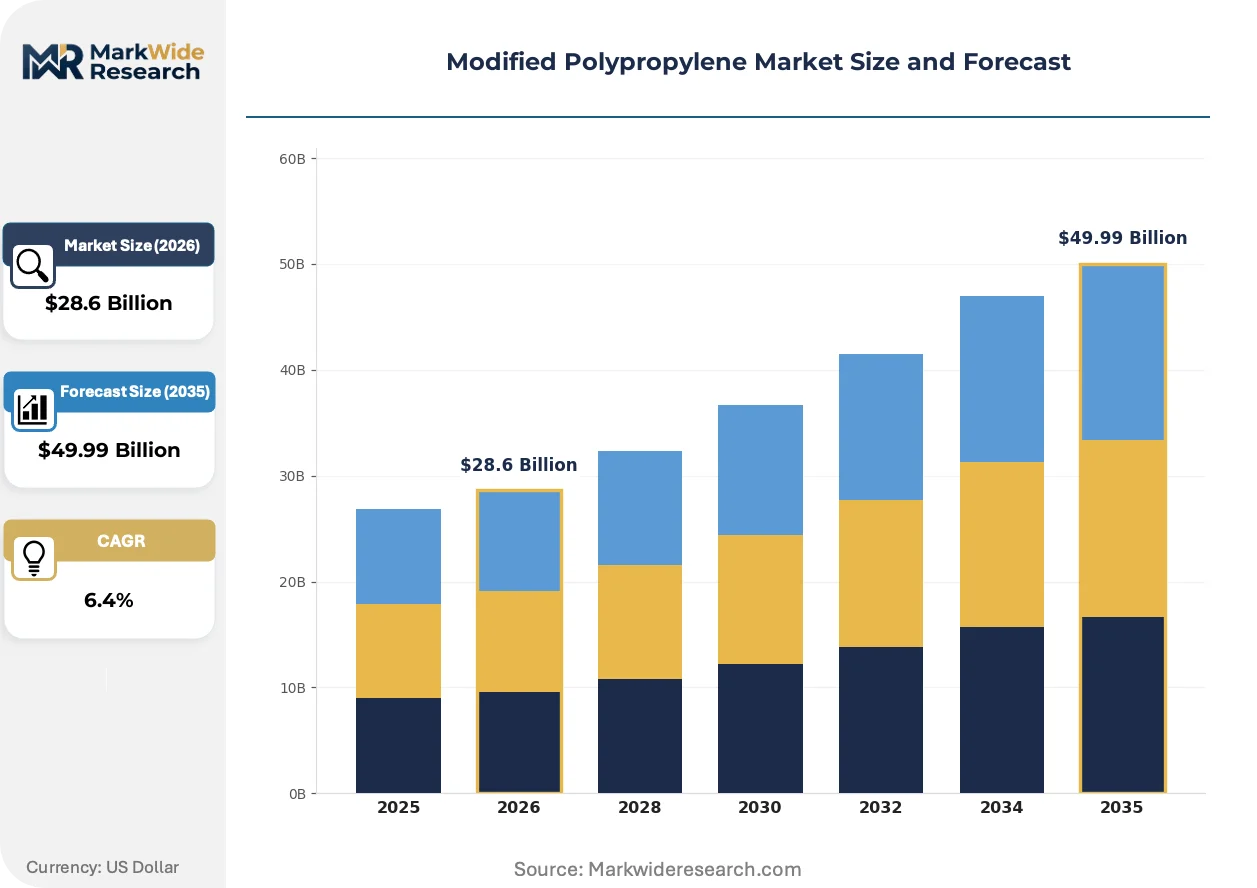
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Block Copolymer, Impact Copolymer End Use Industry: Packaging, Automotive, Consumer Goods, Textiles Form: Sheets, Films, Fibers, Granules Technology: Injection Molding, Blow Molding, Extrusion, Thermoforming |
| Companies Covered | Borealis AG, Trinseo, LyondellBasell Industries Holdings B.V., Sumitomo Chemical Co., Ltd., Repsol, SABIC, Solvay, Washington Penn Plastics Co., Ltd., ExxonMobil Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Polypropylene Market Strategic Shifts & Innovations
Formulation science is splitting along performance-versus-sustainability axes, with divergent R&D investment patterns emerging between integrated resin producers and independent compounders.
Long-chain branched polypropylene rheology modifiers are bifurcating the extrusion coating segment. Food packaging converters running high-speed lines adopt these grades to reduce melt fracture and enable downgauging. The technology is compressing demand for conventional high-melt-strength homopolymers in European and North American flexible packaging markets.
REACH SVHC candidate list expansion is forcing reformulation of mineral-filled grades. ECHA's 2024 additions include certain talc sources and colorant carriers, compelling compounders to requalify automotive interior specifications. Suppliers with pre-validated alternative filler packages capture tier-one supplier preference in German and French OEM programs.
Specification consolidation among battery OEMs is shortening approved materials lists. CATL and BYD now mandate unified grade families across multiple cell formats, displacing fragmented SKU proliferation. Procurement teams at Korean and Chinese EV manufacturers prioritize compounders offering technical service co-location over price-only bidding.
Modified Polypropylene Market Segmentation
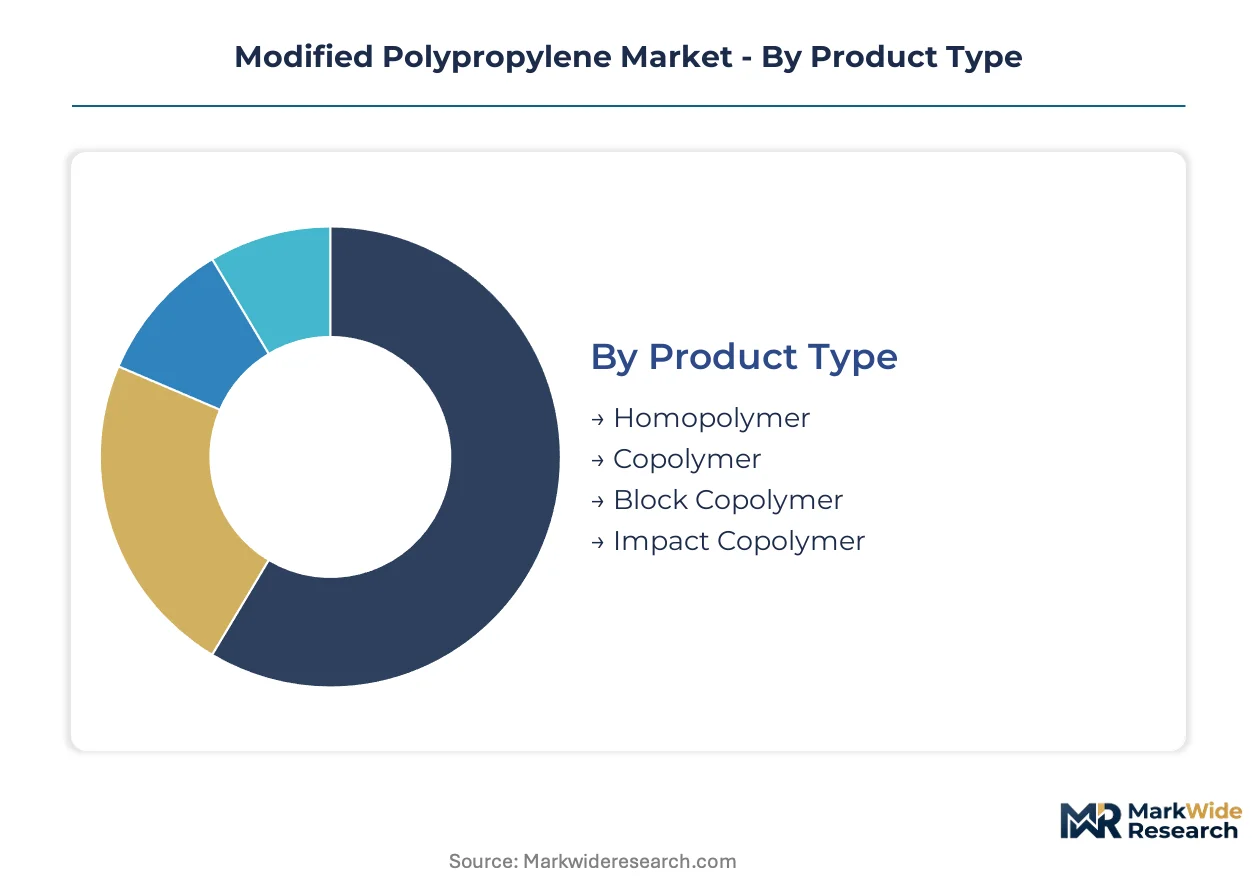
Modified polypropylene formulations diverge sharply in margin structure, with automotive qualification requirements and regulatory compliance layers creating distinct value tiers across product categories. Understanding these segmentation boundaries reveals where compounders capture premium pricing versus where volume commoditization pressures dominate.
Product Type:
Margin pools concentrate in impact-modified and high-heat formulations where OEM qualification barriers limit supplier entry.
- Homopolymer:Stiff, crystalline polypropylene with high tensile strength serves rigid packaging and household appliance housings. Demand clusters in China for injection-molded food containers and storage bins, though price competition from unmodified resin constrains compounding value-add.
- Copolymer:Random copolymerization with ethylene introduces flexibility and optical clarity, opening medical packaging and transparent food containers. European converters specify these grades for EFSA-compliant food contact applications where nucleating agent selection determines migration test outcomes.
- Block Copolymer:Segmented polymer architecture delivers balanced stiffness and impact resistance for automotive interior panels.
- Impact Copolymer:Elastomer-rich formulations achieve sub-zero ductility for bumper systems and battery enclosures in electric vehicles.
The dominant share belongs to copolymer grades, while impact copolymer formulations are closing the gap fastest.
End Use Industry:
Application-specific performance requirements fragment pricing power, with automotive and packaging presenting opposing margin dynamics.
- Packaging:Flexible films and rigid containers demand FDA and EFSA migration compliance, particularly for nucleating agents and clarifier packages. North American converters prioritize downgauging compatibility with high-speed form-fill-seal lines.
- Automotive:Battery housing specifications from CATL and BYD mandate flame-retardant grades with thermal runaway resistance. German OEM qualification protocols compress supplier lists to compounders with satellite technical service operations.
- Consumer Goods:Appliance manufacturers in India specify glass-filled grades for washing machine tubs under BIS certification alignment.
- Textiles:Melt-blown and spunbond nonwoven fibers serve hygiene and filtration applications with exacting denier consistency.
Automotive applications command premium pricing, though packaging volumes sustain the broadest supplier base.
Form:
Physical presentation determines logistics economics and processing equipment compatibility across regional supply chains.
- Granules:Pelletized resin dominates merchant sales due to compatibility with conventional extrusion and blow molding infrastructure. Compounders in China scale granule production to serve domestic EV battery housing demand under MIIT automotive material directives.
- Fibers:Melt-spun filaments gain traction in nonwoven textile applications for medical and filtration end-uses.
- Sheets:Calendered and extruded sheet serves thermoformed packaging and automotive interior trim.
- Films:Cast and blown film grades target flexible packaging converters with downgauging requirements.
Granule shipments retain volume leadership, while fiber-grade modified polypropylene is expanding most quickly in technical textile applications.
Technology:
Processing method selection locks in formulation requirements, with injection molding commanding the most stringent rheological specifications.
- Injection Molding:High-shear processing demands precise melt flow index control and thermal stability for thin-wall automotive components. Tier-one suppliers specify long-chain branched grades to reduce cycle times in bumper and dashboard production.
- Extrusion:Sheet and film extrusion lines require broad molecular weight distribution for gauge uniformity. REACH SVHC restrictions on certain talc sources force reformulation of mineral-filled extrusion grades for European automotive interior specifications.
- Blow Molding:Parison stability requirements favor high-melt-strength copolymers for hollow container production.
- Thermoforming:Deep-draw applications need balanced orientation and shrinkage control for appliance housings and food trays.
Injection molding absorbs the largest formulation development investment, while extrusion applications present the steepest expansion trajectory for sustainable content claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese compounders absorb feedstock volatility with minimal margin compression, while European processors face acute cost sensitivity from energy-intensive naphtha cracking. Indian demand exhibits intermediate elasticity, responsive to BIS certification timelines but insulated from crude-linked swings by domestic refinery integration.
China
Electric vehicle battery housing specifications from CATL and BYD drive flame-retardant grade absorption, with Sinopec scaling compounding capacity in Ningbo and Tianjin. MIIT automotive material directives mandate thermal runaway resistance standards that foreign suppliers must meet for platform qualification. The Yangtze River Delta cluster concentrates domestic compounder expansion to serve BYD's Shenzhen assembly operations and SAIC Motor's Shanghai engineering centers.
Germany
OEM lightweighting protocols at Volkswagen and BMW compress supplier qualification windows to 18 months, favoring compounders with satellite technical service operations. ECHA REACH authorization scrutiny of halogenated flame retardants delays formulation approvals by 12-18 months for interior specifications. The Ruhr industrial corridor hosts BASF and Lanxess compounding facilities serving battery housing manufacturers in Stuttgart and Munich.
United States
FDA food-contact regulations shape nucleating agent selection for packaging-grade formulations targeting high-speed form-fill-seal lines. LyondellBasell leverages Houston refinery integration to secure propylene cost positions across North American compounding networks. The Gulf Coast petrochemical corridor anchors merchant granule production for automotive tier-one suppliers in Detroit and appliance manufacturers in the Midwest.
India
Appliance manufacturers seeking import substitution create demand for glass-filled grades in washing machine tubs and air conditioner housings under BIS certification alignment. The country's national automotive regulator mandates material traceability for vehicle platform qualification, extending validation timelines. Gujarat's chemical manufacturing belt concentrates compounding capacity to serve Mahindra & Mahindra's Mumbai engineering operations and LG Electronics' Pune appliance plants.
Japan
METI industrial standards establish performance benchmarks for medical packaging applications where random copolymer optical clarity determines specification acceptance. Phosphorus-based flame retardant supply concentration among domestic chemical suppliers creates single-source vulnerability for automotive programs. The Chubu region around Nagoya hosts Sumitomo Chemical compounding facilities serving Toyota's nearby assembly operations and tier-one interior suppliers.
Modified Polypropylene Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding feedstock economics and specialized compounders owning formulation IP. The market structure concentrates around petrochemical majors with captive polypropylene supply and independent compounders with OEM qualification relationships. Three archetypes dominate: upstream-integrated producers, automotive-focused specialists, and packaging-grade merchants. Capacity expansion and direct OEM compounding partnerships represent the dominant competitive moves, displacing traditional distributor networks.
Among European integrated producers, Borealis AG and Repsol exemplify upstream-backward positions securing feedstock cost advantages across continental compounding networks. SABIC anchors the Middle East-based supply vector, while LyondellBasell Industries Holdings B.V. occupies the North American scale-driven tier with Houston refinery integration. Trinseo and Washington Penn Plastics Co., Ltd. represent independent compounder archetypes built on automotive qualification depth and technical service proximity rather than captive resin supply.
| Leading Market Players |
|---|
| Borealis AG |
| Trinseo |
| LyondellBasell Industries Holdings B.V. |
| Sumitomo Chemical Co., Ltd. |
| Repsol |
| SABIC |
| Solvay |
| Washington Penn Plastics Co., Ltd. |
| ExxonMobil Corp. |
| Others |
Cost & Logistics Intelligence
Forty-five-day compounder inventory cycles in automotive supply chains concentrate pricing power with resin producers holding captive propylene supply, while spot buyers absorb margin compression during feedstock volatility. This lead-time band separates qualified suppliers with OEM platform lock-in from merchant compounders exposed to naphtha-cracker margin swings.
Pricing Analysis
After-sales technical service contracts and satellite compounding operations drive lifetime value capture beyond base resin transactions. Contract-based long-term offtake dominates automotive tiers, where OEM qualification barriers sustain premium-mid-economy pricing differentiation across impact-modified, high-heat, and commodity grades. Cost compression in standard homopolymer segments intensifies as Chinese domestic compounders scale capacity under MIIT directives. Tier-one automotive suppliers exhibit lowest price sensitivity due to platform validation requirements, while appliance manufacturers in India show highest elasticity responsive to BIS certification timelines.
Supply Chain Analysis
China and Saudi Arabia anchor global propylene derivative production, with Sinopec and SABIC controlling upstream feedstock positions that downstream compounders must negotiate. Modified polypropylene formulation draws from ethylene-octene copolymer elastomers, phosphorus-based flame retardants, and talc filler packages concentrated among Japanese and German chemical suppliers. Single-source vulnerability in specialized additive supply creates qualification bottlenecks when ECHA REACH authorization delays alternative sourcing. Distribution runs through direct OEM compounding partnerships displacing traditional distributor networks, particularly at Volkswagen, BYD, and Stellantis assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around CATL, BYD, and Volkswagen procurement teams now mandating unified grade families and satellite technical service co-location, fragmenting supplier lists and compressing compounder margins.
For Market Incumbents: Shield formulation IP positions by deepening captive propylene integration at Houston and Ningbo hubs, while accelerating REACH-compliant flame retardant pre-validation to preempt ECHA authorization delays. Prioritize direct OEM compounding partnerships over distributor channel maintenance, as platform standardization at battery OEMs displaces fragmented SKU relationships. For New Entrants and Emerging Players: Technical service co-location gaps in the Ruhr corridor and Yangtze River Delta present white-space entry points where incumbents under-serve mid-tier automotive programs. Target glass-filled appliance grades in Gujarat under BIS certification alignment, leveraging India's import substitution momentum with localized compounding operations at Pune and Mumbai industrial belts. For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-capture play because automotive lightweighting mandates sustain demand for impact-modified grades while chemical recycling infrastructure investments determine which compounders retain compliance advantages. Acquisition targets center on independent compounders with OEM qualification depth and pyrolysis-derived propylene integration capabilities. The signal to watch is EFSA migration-compliant food contact certification for post-consumer content claims in packaging-grade copolymers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | LyondellBasell's Houston refinery integration secures feedstock cost positions across North American compounding networks. |
| Direct OEM Compounding Partnership | Satellite operations at Volkswagen and BYD assembly plants bypass distributor networks and lock in platform qualification. |
| REACH-Compliant Flame Retardant Pre-Validation | Alternative filler packages capture tier-one supplier preference as ECHA SVHC candidate list expansion forces reformulation. |
| Chemical Recycling Feedstock Integration | Pyrolysis-derived propylene enables post-consumer content claims for EFSA migration-compliant packaging-grade copolymers. |
| Automotive Technical Service Co-Location | German OEM qualification protocols compress supplier lists to compounders with satellite operations in Stuttgart and Munich. |
Research Approach
A spread of perspectives from resin plant managers, Tier 1 automotive procurement leads, appliance manufacturer R&D directors, and distribution channel partners converged on the working assumptions shaping demand elasticity and substitution dynamics. Primary fieldwork combined with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases enabled bottom-up and top-down triangulation across the analysis window.
Segmentation dimensions modeled include copolymer grade tier, end-use industry concentration, physical form presentation, and processing technology requirements. CAGRs were derived from production capacity expansion announcements, OEM platform launch timelines, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated MIIT automotive material directive implementation pace and ECHA REACH authorization bottleneck resolution.
Underlying assumptions cover propylene feedstock cost pass-through elasticity, OEM qualification cadence compression sustainability, and chemical recycling infrastructure deployment, with deviation risk concentrated in naphtha-cracker margin volatility and halogenated flame retardant regulatory restrictions. Recalibration cycles align with material shifts in EU Green Deal carbon-border adjustment implementation and battery OEM specification consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
South Korea Recycled Plastics Market