
 Polymer Colorant Market | 2026-2036
Polymer Colorant Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Colorant Market Insights
Buyer concentration across the polymer colorant value chain is broadening as mid-sized packaging converters and automotive tier-two suppliers diversify their supplier rosters beyond legacy incumbents. BASF leverages its integrated pigments and additives portfolio to serve multinational plastics processors with consistent batch-to-batch performance. Clariant sustains leadership in halogen-free colorant systems for electrical and electronics applications. RTP Company specializes in engineered color concentrates that meet exacting thermal stability requirements for under-hood automotive components.
Polymer colorants encompass pigments, dyes, masterbatches, and functional additives that impart color, opacity, or special visual effects to thermoplastic and thermoset resins, typically processed via extrusion compounding, injection molding, or blow molding at temperatures between 180°C and 320°C. Masterbatches dominate volume flows due to their handling efficiency and reduced dust exposure on converter production floors. Pigments command premium positioning in outdoor durable goods where UV stability and weathering resistance determine product lifespan. Dyes retain niche occupancy in transparent packaging and certain textile fiber applications where clarity and migration resistance matter.
FDA food-contact regulations in the United States, REACH chemical registration requirements in Europe, and BIS certification standards in India each constrain which colorant chemistries gain market access and dictate migration testing protocols for packaging end uses. EPA and ECHA frameworks are progressively restricting legacy heavy-metal pigments, forcing reformulation investments across the supply base. Stakeholders must monitor evolving state-level extended producer responsibility laws and polymer recycling content mandates, as these will determine which colorant technologies remain compatible with mechanically recycled feedstock streams.
Market Dynamics
REACH and RoHS compliance in Europe is redirecting formulation priorities toward heavy-metal-free alternatives, compressing legacy pigment portfolios while opening substitution pathways for organic and complex inorganic colorants across packaging and electrical applications.
Growth Catalysts
- Recycled-content mandates:Packaging manufacturers in Asia-Pacific are expanding colorant procurement for mechanically reprocessed polyethylene and polypropylene streams. This creates demand for colorants compatible with variable feedstock quality.
- ECHA heavy-metal restrictions:Progressive tightening of cadmium and lead pigment exemptions under REACH Annex XVII is forcing reformulation investments that favor compliant alternatives.
- Automotive under-hood thermal requirements:Engineered color concentrates meeting 300°C+ stability thresholds are penetrating powertrain and electrical component applications as OEMs consolidate supplier bases.
Market Restraints
- Titanium dioxide supply concentration:Pigment production clusters in China create input cost volatility and geopolitical exposure for white and pastel colorant formulations.
- Migration testing protocols:FDA food-contact regulations and EFSA compliance requirements impose lengthy certification timelines that delay new colorant commercialization by 18-24 months.
- Masterbatch substitution pressure:Liquid colorant systems are capturing share in high-volume blow molding operations where equipment retrofits justify switching costs.
Strategic Opportunities
- India domestic processing scale-up:BIS certification standards and PLI scheme incentives for polymer processing are creating localized demand for compliant colorant supply.
- Halogen-free electrical systems:IEC 61215-1 and UL 94 V-0 standards for flame-retardant electronics are opening formulation white space for phosphorus-based colorant-additive hybrids.
- Digital color matching platforms:Cloud-based spectrophotometry and AI-driven shade prediction are compressing development cycles for custom masterbatch orders.
Industry Challenges
- Colorimetric expertise scarcity:Formulation chemists capable of balancing opacity, thermal stability, and regulatory compliance across polymer matrices command premium compensation and limited availability.
- Multi-jurisdiction registration burden:Separate dossier requirements for EPA, ECHA, and China's MEE create fixed cost barriers for mid-tier colorant suppliers seeking geographic expansion.
- Legacy equipment incompatibility:Existing extrusion lines optimized for pelletized masterbatches require capital-intensive retrofits to handle liquid or low-dust powder colorant formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Colorant Market |
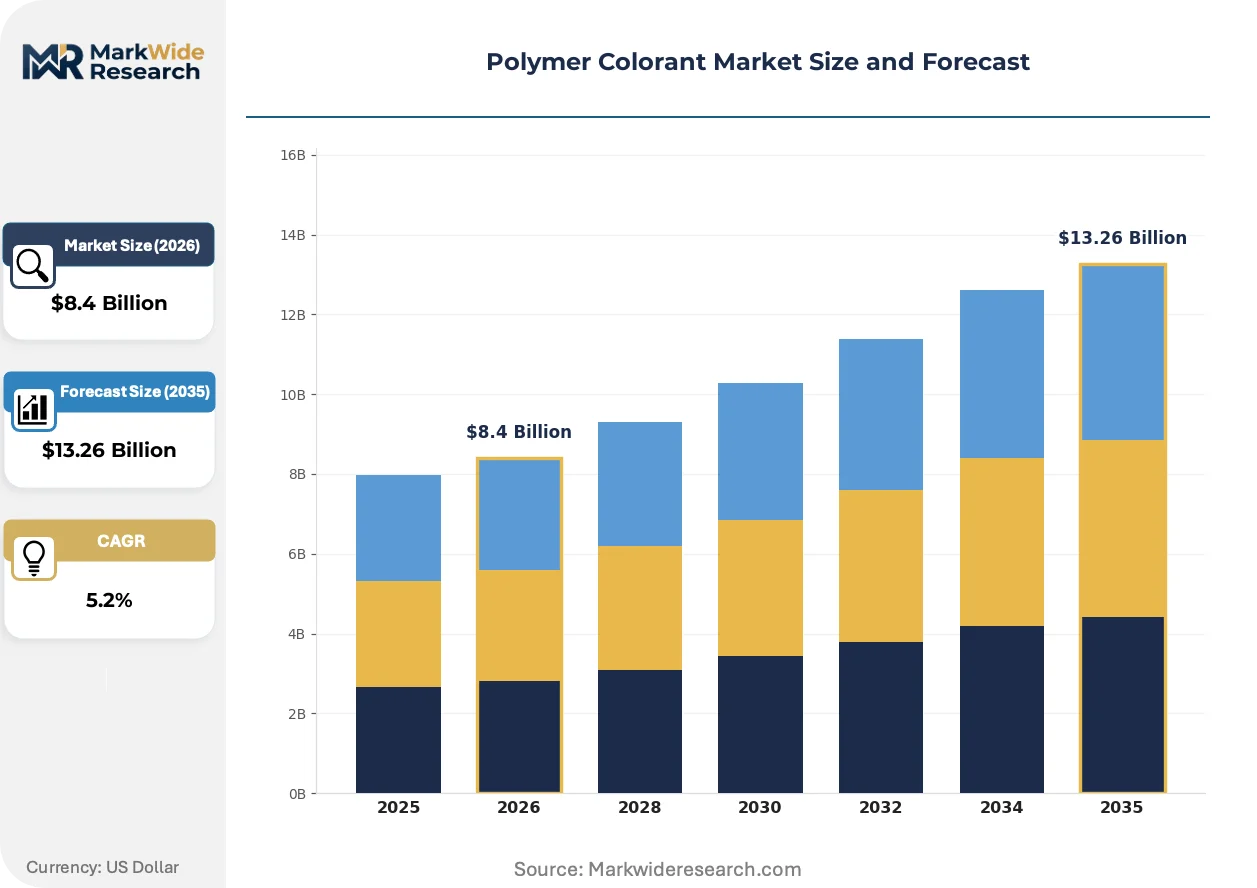
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pigments, Dyes, Masterbatches, Additives Application: Plastics, Coatings, Inks, Textiles End User: Automotive, Consumer Goods, Construction, Packaging Delivery Mode: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | BASF, Clariant, TOYO INK SC HOLDINGS CO. LTD., Sensient Technologies, Pidilite, RTP Company, Huntsman, PolyOne, Chr. Hansen Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Colorant Market Trends and Innovations
Reformulation chemistry, regulatory compliance automation, and procurement platform digitization are converging to compress product development cycles and reshape how converters specify colorant systems across thermoplastic applications.
Near-infrared reflective pigments are electrifying the outdoor durable goods segment by enabling dark-colored polymer surfaces that reduce heat buildup. Roofing and automotive exterior component manufacturers are specifying these formulations to meet solar reflectance index targets without sacrificing aesthetic range. The technology is compressing demand for conventional carbon black in weathering-critical applications.
ECHA's 2023-2025 restriction roadmap for intentionally added microplastics is forcing masterbatch producers to redesign carrier resin systems and additive packages. Compounders serving single-use packaging must now document biodegradation pathways or shift to approved alternatives. German and French packaging converters are accelerating qualification of bio-based carrier resins to preempt enforcement timelines.
Specification behavior among mid-sized processors is fragmenting as digital marketplaces and distributor private-label programs erode legacy technical-service relationships. Tier-two automotive suppliers and regional packaging converters are sourcing standard colors through e-procurement platforms while reserving direct mill relationships for complex custom formulations. This bifurcation is most pronounced in China's Yangtze River Delta polymer processing cluster.
Polymer Colorant Market Segmentation
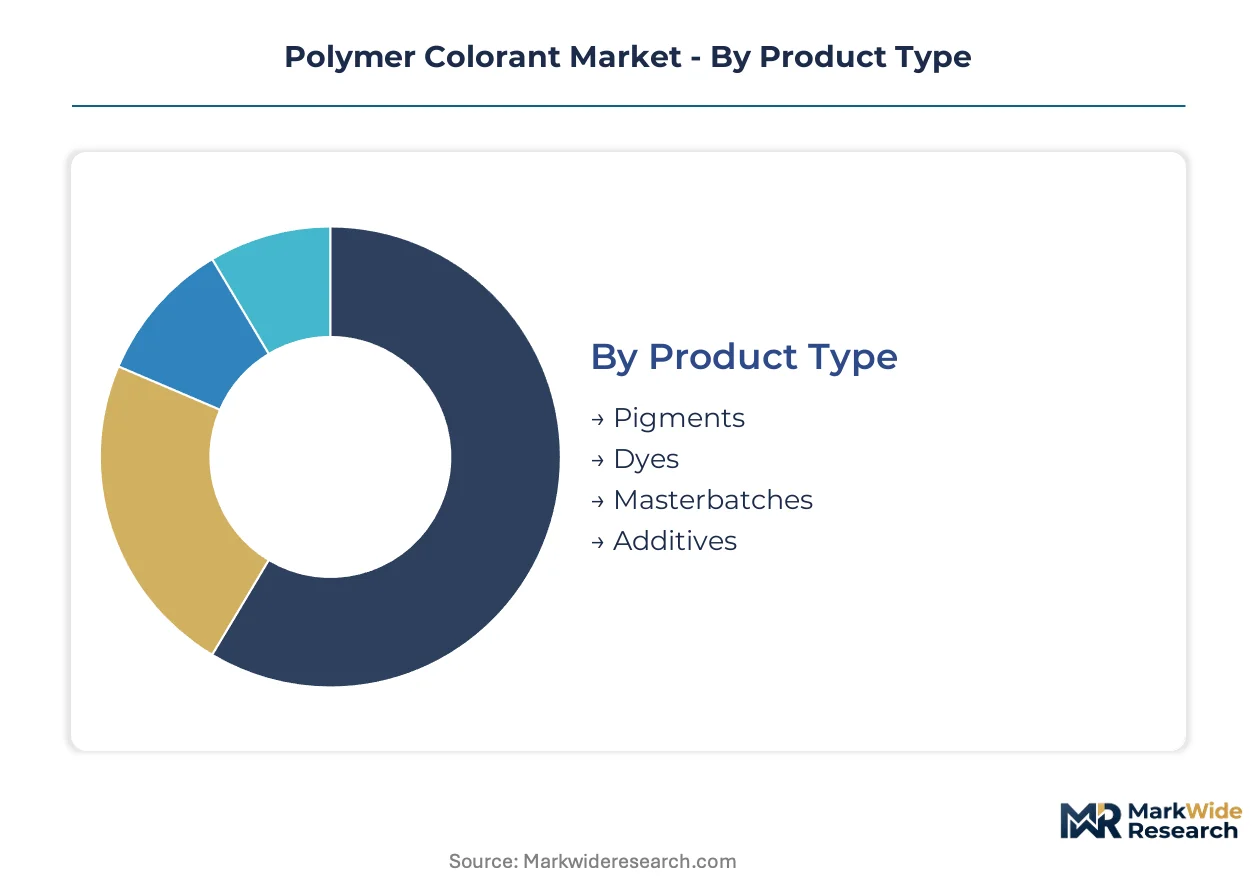
Polymer colorant procurement patterns diverge sharply across formulation types and delivery channels. Converter scale, regulatory exposure, and thermal performance requirements determine which segments capture margin versus volume.
Product Type:
Supply concentration in titanium dioxide and complex inorganic pigments shapes competitive dynamics across formulation categories.
- Masterbatches:Concentrated colorant pellets disperse uniformly into base resins during extrusion. Packaging manufacturers in China and India specify these for handling efficiency and reduced dust exposure on high-speed production floors.
- Pigments:Insoluble particulate colorants deliver opacity and UV resistance for outdoor durable goods. Demand concentrates in automotive exterior components and construction materials where weathering performance determines warranty exposure.
- Dyes:Soluble organic molecules penetrate polymer matrices for transparent effects. Textile fiber producers and specialty packaging converters specify these where clarity and migration resistance outweigh thermal stability requirements.
- Additives:Functional modifiers including optical brighteners and processing aids complement colorant systems. Compounders integrate these to meet flame-retardant and near-infrared reflective specifications in electrical and roofing applications.
Masterbatches absorb the bulk of installed capacity; additives are expanding most quickly.
Application:
Cost tier differentiation separates commodity volume plays from specification-driven premium positions.
- Plastics:Thermoplastic and thermoset resins consume the majority of colorant volume across injection molding, blow molding, and extrusion compounding. REACH and RoHS compliance in Europe is redirecting formulation priorities toward heavy-metal-free alternatives in electrical housings and automotive interiors.
- Coatings:Polymer-based protective and decorative films require colorants with solvent compatibility and film-formation stability. Construction and industrial equipment manufacturers specify these for corrosion protection combined with brand-color consistency.
- Inks:Printing applications demand fine particle size and low viscosity compatibility. Flexible packaging converters in Germany and India qualify these for high-speed gravure and flexographic presses.
- Textiles:Synthetic fiber dyeing and nonwoven coloration require migration-resistant chemistries. Polyester and polypropylene fiber producers specify disperse dyes and pigment dispersions for apparel and geotextile applications.
Plastics commands the dominant share of formulation investment; coatings is climbing the fastest on construction and automotive refinish demand.
End User:
Customer type determines whether procurement flows through distributor networks or direct technical-service relationships.
- Packaging:Food-contact and consumer goods containers drive volume demand for FDA-compliant and BIS-certified colorant systems. Recycled-content mandates in Asia-Pacific are expanding procurement for mechanically reprocessed polyethylene and polypropylene streams.
- Automotive:OEMs and tier suppliers specify engineered color concentrates meeting 300°C+ thermal stability for under-hood components. Powertrain and electrical system consolidation is compressing supplier bases toward integrated pigment-additive portfolios.
- Consumer Goods:Appliances, electronics housings, and personal care packaging require consistent batch-to-batch performance. Brand owners specify custom masterbatches through direct mill relationships for complex formulations.
- Construction:Roofing, siding, and infrastructure applications prioritize UV stability and solar reflectance. Near-infrared reflective pigments are displacing conventional carbon black in weathering-critical specifications.
Packaging absorbs the bulk of volume flows; automotive is gaining share fastest on thermal performance premiums.
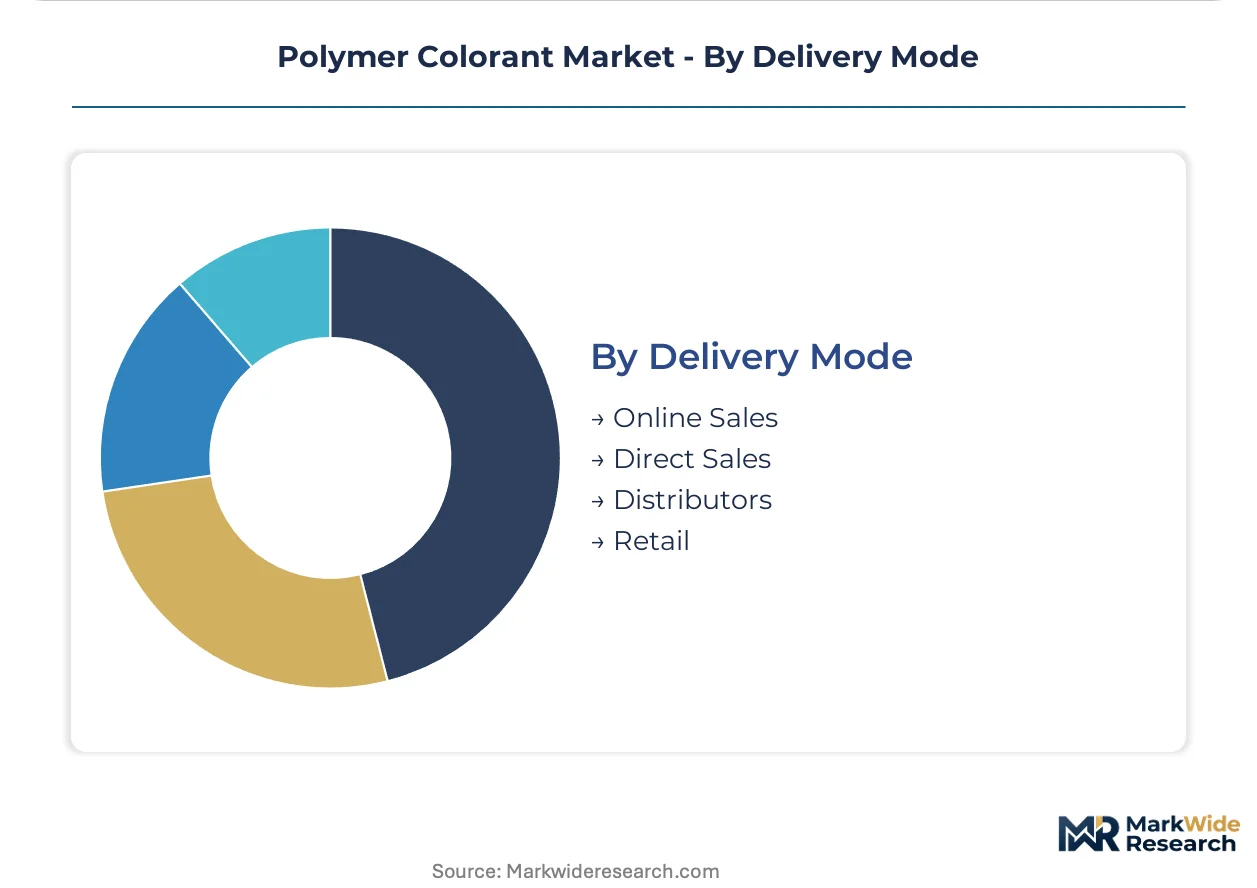
Delivery Mode:
Channel maturity separates legacy distributor networks from emerging digital procurement platforms.
- Distributors:Regional chemical distributors maintain inventory positions and technical service capabilities for mid-sized converters. These relationships persist where formulation expertise and just-in-time delivery outweigh price transparency.
- Direct Sales:Major compounders and multinational processors contract directly with colorant manufacturers for custom formulations. Automotive tier-one suppliers and large packaging groups specify through dedicated account management.
- Online Sales:Digital marketplaces and e-procurement platforms capture standard-color volume from price-sensitive processors. China's Yangtze River Delta polymer processing cluster shows pronounced adoption for commodity masterbatch grades.
- Retail:Small-lot sales through industrial supply channels serve maintenance, repair, and small-batch prototyping needs. Independent molders and specialty compounders source through these channels for operational flexibility.
Distributors retain the bulk of relationship value; online sales is expanding most quickly among mid-sized processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China, India, and Germany as these countries scale domestic polymer processing capacity. Packaging converters in Asia-Pacific are expanding colorant procurement for recycled-content plastics. REACH and RoHS compliance in Europe is redirecting formulation priorities toward heavy-metal-free alternatives.
China
Packaging manufacturers in the Yangtze River Delta are expanding colorant procurement for mechanically reprocessed polyethylene and polypropylene streams. MEE oversight of chemical registrations constrains which colorant chemistries gain production licenses. The Pearl River Delta polymer processing cluster is qualifying masterbatches compatible with variable recycled feedstock quality.
Germany
Automotive tier-one suppliers specify engineered color concentrates meeting 300°C+ thermal stability for under-hood powertrain components. ECHA's progressive tightening of cadmium and lead pigment exemptions under REACH Annex XVII forces reformulation investments. The North Rhine-Westphalia chemical corridor is consolidating supplier bases toward integrated pigment-additive portfolios.
India
BIS certification standards and PLI scheme incentives for polymer processing are creating localized demand for compliant colorant supply. FSSAI migration testing protocols for food-contact applications impose certification timelines that delay new colorant commercialization. The Gujarat petrochemical belt is scaling masterbatch production for domestic packaging converters.
United States
FDA food-contact regulations constrain which colorant chemistries gain market access for packaging end uses. EPA frameworks are progressively restricting legacy heavy-metal pigments, forcing reformulation investments across the supply base. The Texas Gulf Coast polymer processing corridor is retrofitting extrusion lines for liquid colorant systems in high-volume blow molding operations.
Japan
Electronics manufacturers specify halogen-free colorant systems for electrical housings under IEC 61215-1 and UL 94 V-0 standards. METI oversight of chemical safety ensures rigorous compliance documentation for imported colorant formulations. The Kansai industrial region is qualifying phosphorus-based colorant-additive hybrids for flame-retardant applications.
Polymer Colorant Market Competitive Landscape
German producers anchor one tier; Swiss and American specialists hold differentiated positions in thermal stability and regulatory compliance. The vendor base spans integrated chemical conglomerates, independent masterbatch compounders, and regional distributors. Three archetypes dominate: integrated pigment-additive portfolios, halogen-free electrical system specialists, and engineered concentrate formulators. Capacity expansion and portfolio diversification toward heavy-metal-free alternatives represent the dominant competitive moves.
Within the integrated chemical tier, BASF and Clariant exemplify multinational scale advantages. RTP Company occupies a position among engineered concentrate specialists serving exacting thermal stability requirements. These three anchors represent distinct strategic postures: integrated raw material control, regulatory compliance leadership, and application-specific formulation depth.
| Leading Market Players |
|---|
| BASF |
| Clariant |
| TOYO INK SC HOLDINGS CO. LTD. |
| Sensient Technologies |
| Pidilite |
| RTP Company |
| Huntsman |
| PolyOne |
| Chr. Hansen Holding |
| Others |
Pricing and Supply Chain Analysis
Liquid colorant system adoption in high-volume blow molding operations simultaneously compresses per-kilogram colorant costs and disintermediates traditional masterbatch compounders from equipment-retrofit decisions. This production-method transition concentrates procurement leverage among converters with capital to retrofit extrusion lines, fragmenting pricing power across pelletized and liquid delivery formats.
Pricing Analysis
Volume-margin splits separate commodity masterbatch grades from engineered color concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal stability performance. Pricing pressure stems from titanium dioxide supply volatility originating in Chinese production clusters. Small-scale packaging converters exhibit highest price sensitivity, while automotive tier-one suppliers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for custom formulations, while regional distributors serve mid-tier converters with standard grades. Raw material supply concentrates in China for titanium dioxide, Germany for complex inorganic pigments, and India for organic dye intermediates. Production draws from petrochemical feedstocks, mineral ore concentrates, and specialty chemical additives. Single-source vulnerability in white pigment inputs creates exposure to MEE environmental enforcement actions. Distribution runs through chemical distributors, direct mill relationships, and emerging digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as compounders pursue backward integration into pigment synthesis to secure supply continuity and compress formulation costs.
For Market Incumbents: Hedge against liquid colorant substitution by retrofitting service capabilities for equipment integration support. Defend position through captive supply of complex inorganic pigments and halogen-free additive packages. Prioritize certification investments for REACH Annex XVII compliance to maintain European market access against reformulation mandates. For New Entrants and Emerging Players: E-procurement platforms for standard masterbatch grades offer the lowest barrier to customer acquisition. Target India's Gujarat petrochemical belt where BIS certification requirements create localization premiums for domestic compounders. Pursue digital color matching partnerships to compress development cycles for mid-sized processors. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty compounders with thermal stability expertise and regulatory compliance portfolios. Five-to-ten year viability favors players with integrated pigment-additive capabilities serving automotive under-hood specifications. Monitor ECHA restriction timelines for cadmium and lead pigment exemptions as inflection indicators for reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive titanium dioxide supply insulates compounders from Chinese export volatility and MEE enforcement. |
| Halogen-Free Formulation Development | Phosphorus-based colorant-additive hybrids unlock UL 94 V-0 electrical housing specifications for Japanese electronics manufacturers. |
| Digital Color Matching Platform Launch | AI-driven spectrophotometry compresses custom masterbatch development cycles for Yangtze River Delta packaging converters. |
| Recycled-Feedstock Compatible Masterbatch Expansion | Variable-quality polyethylene and polypropylene streams from Asia-Pacific mandates require reformulated carrier resin systems. |
| Regional Distribution Partnership | Local inventory positions in India's Gujarat belt reduce FSSAI certification timelines for food-contact colorant commercialization. |
Research Methodology
Independent corroboration across plant managers at masterbatch compounders, procurement leads at automotive tier suppliers, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and chemical registration databases established supply-side and demand-side triangulation. Bottom-up capacity assessments and top-down end-use consumption estimates were reconciled to anchor volume figures.
Comparable-period anchoring to historical production and consumption data established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including formulation type, end-use industry, thermal performance tier, and regional production hub. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology substitution patterns. Forecast inputs incorporated polymer processing capacity expansion timelines and ECHA restriction roadmap enforcement schedules.
The model holds under stable regulatory enforcement timelines and continued polymer processing capacity growth in China, India, and Germany; deviation in REACH exemption withdrawals or titanium dioxide supply disruptions would shift trajectory. Forecasts reflect assumptions about recycled-content mandate implementation rates and liquid colorant equipment retrofit adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Global Cosmetic Pigments Market