
 Plastic Recycling Market | 2026-2036
Plastic Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Recycling Market Intelligence
The divergence between food-grade recycled polymers and lower-quality mixed plastic flakes is repositioning the value chain. This split creates distinct opportunities for specialized and large-scale operators. Indorama Ventures Public Company Limited specializes in high-purity PET recycling for beverage bottles. Meanwhile, integrated waste management firms like Veolia Environnement S.A. and Waste Management Inc. leverage their vast collection networks to process a wide spectrum of plastic waste streams.
Plastic recycling is the process of recovering scrap or waste plastic and reprocessing the material into useful products. The process involves sorting by polymer type, cleaning to remove contaminants, and then shredding and melting it into pellets for reuse. Recycled PET (rPET) from packaging applications represents the largest and most mature segment, driven by bottle-to-bottle loops. Mechanical recycling remains the dominant process for materials like HDPE and PP, while chemical recycling is an emerging solution for difficult-to-recycle mixed plastic streams.
Regulatory frameworks are a primary market catalyst, with the EU Green Deal mandating recycled content in new products. In parallel, directives from the US Environmental Protection Agency (EPA) and China's national policies on waste import and circular economy development shape regional collection and processing standards. The critical decision for stakeholders is how to invest in advanced sorting and chemical recycling technologies to meet these evolving quality and volume requirements.
Market Dynamics
The market is defined by a structural bifurcation between high-value, food-grade polymers and low-grade mixed plastics. This quality divide, driven by regulation, dictates investment priorities and competitive positioning across the value chain.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal compels manufacturers to use recycled plastics, creating sustained demand for rPET and rHDPE.
- Packaging Sector Demand:Brand owners in food, beverage, and consumer goods actively seek high-purity recycled polymers to meet sustainability targets.
- Chemical Recycling Advancement:Innovations in pyrolysis are enabling conversion of mixed plastic waste into valuable feedstocks, expanding material supply.
Market Restraints
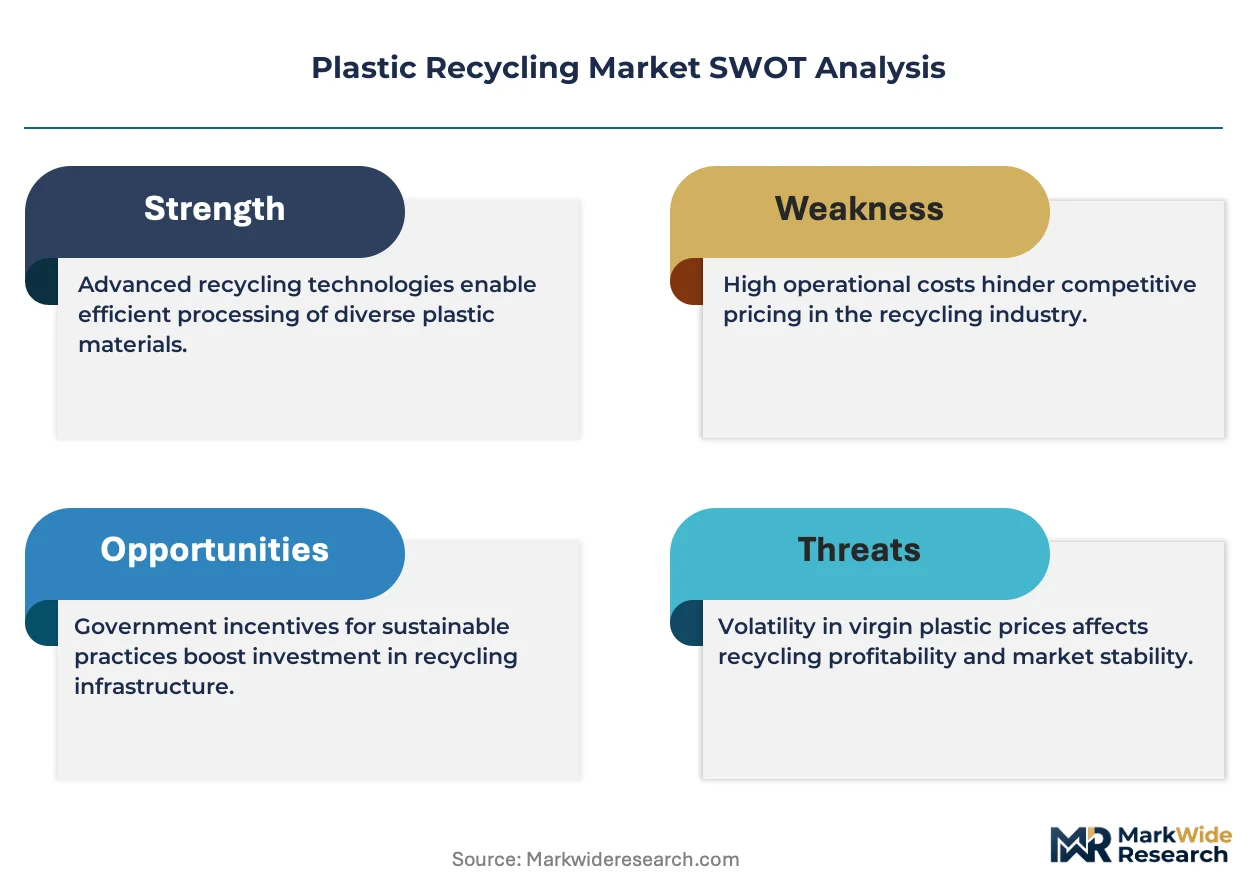
- Feedstock Contamination:The inconsistent quality of post-consumer waste remains a barrier, increasing processing costs and limiting end-use applications for mechanically recycled materials.
- Collection Infrastructure Gaps:In many regions outside Europe, underdeveloped collection and sorting infrastructure limits the volume of high-quality, segregated plastics available.
- Technical Processing Limits:Mechanical recycling degrades polymers like PET over successive cycles, limiting their use in high-performance applications without adding virgin material.
Strategic Opportunities
- Advanced Sorting Technologies:Investment in AI-driven robotics and digital watermarking unlocks access to food-grade and other high-margin markets.
- Non-Packaging Applications:Expanding recycled plastic use in durable goods like automotive components, construction materials, and textiles represents a significant volume opportunity.
- Emerging National Policies:Circular economy policies in Asia and the Americas are creating new, regulated markets for recycled content.
Industry Challenges
- Capital Intensity:Building advanced chemical recycling facilities and upgrading material recovery plants with new sorting equipment requires substantial upfront investment.
- Lack of Harmonized Standards:Divergent national standards for food-contact compliance and "recycled" definitions create complexity and trade barriers for global operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Recycling Market |
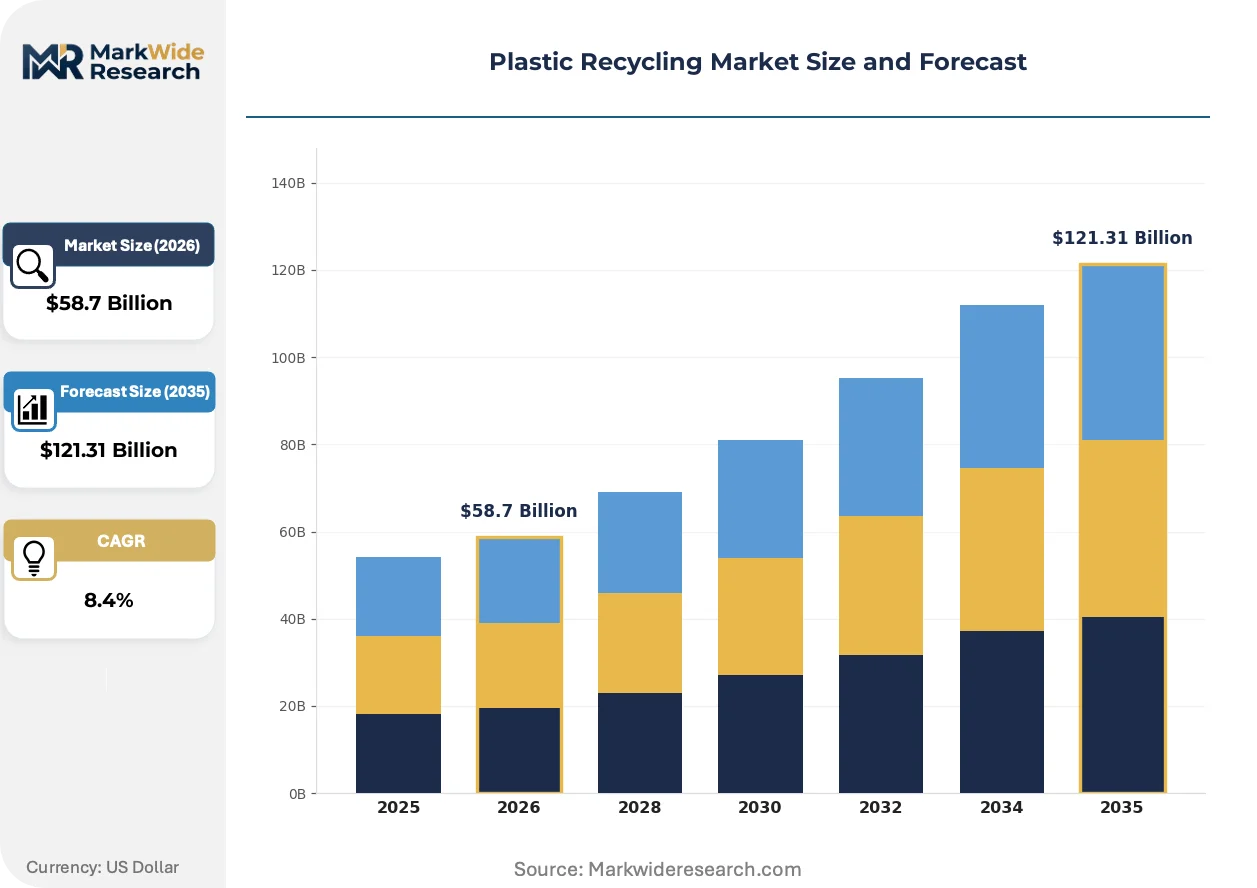
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plastic Type: PET, HDPE, PVC, LDPE, PP, PS Recycling Process: Mechanical, Chemical, Pyrolysis, Depolymerization, Solvent-Based, Energy Recovery End Use Industry: Packaging, Construction, Textiles, Electronics, Consumer Goods, Agriculture Collection Method: curbside Pickup, Drop-off Centers, Buy-back Programs, Deposit Return Schemes, Community Collection |
| Companies Covered | Veolia Environnement S.A., Indorama Ventures Public Company Limited, Waste Management Inc., SUEZ SA, Republic Services Inc., B&B Plastics Inc., Plastipak Holdings Inc., MBA Polymers Inc., KW Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Recycling Market Strategic Shifts & Innovations
A fundamental shift toward quality and traceability is redefining plastic recycling. The industry is moving beyond simple volume recovery to prioritize high-purity polymers that can displace virgin materials, driven by process innovation and policy.
Digital sorting technology, using AI-powered scanners and chemical markers, enables precise separation of polymers. Large-scale material recovery facilities adopt these systems to produce feedstock pure enough for food-grade applications. This capability is consolidating the value chain, concentrating power with operators who deliver certified, high-specification recycled resins.
The European Union's Single-Use Plastics Directive serves as a global benchmark, mandating recycled content in products like beverage bottles. This regulation creates guaranteed demand for materials such as rPET, insulating recyclers from virgin polymer price volatility. The beverage and packaging segments are most impacted, securing long-term supply contracts in response.
Consumer packaged goods companies are moving from spot-market purchasing to securing supply via multi-year offtake agreements. This change involves contracting directly with recycling processors, often before a facility is built. The practice is most prominent for food-grade rPET and rHDPE in North America and Europe to meet public sustainability goals.
Plastic Recycling Market Segmentation
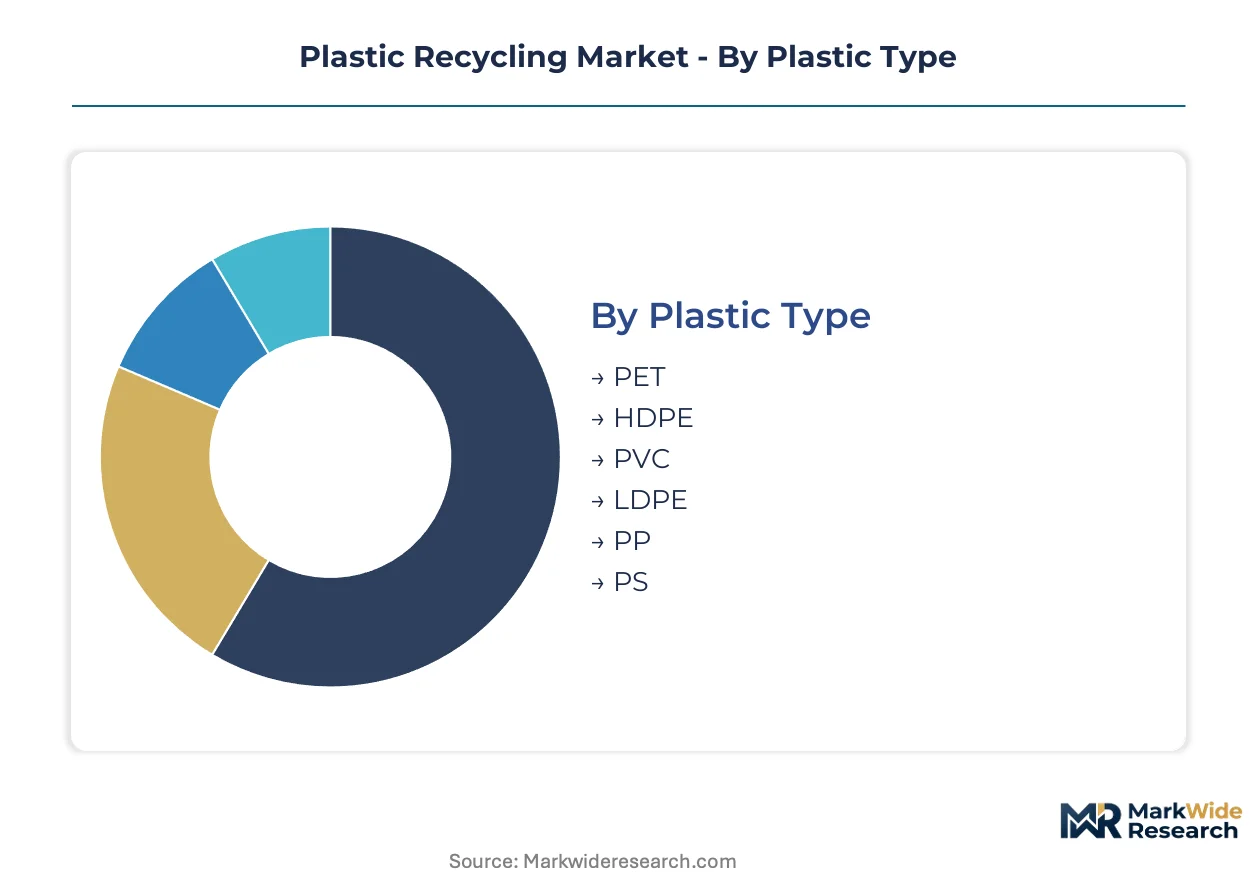
Understanding the Plastic Recycling Market requires a granular examination of its diverse segments. This segmentation reveals how different plastic types, recycling technologies, and end-use applications shape value creation. Identifying these distinct areas allows stakeholders to target investments and develop tailored strategies across the evolving recycling landscape.
Plastic Type:
The plastic type segmentation highlights the spectrum from highly standardized, easily recyclable polymers to those requiring specialized processing.
- PET:Polyethylene terephthalate (PET) is a thermoplastic polymer for beverage bottles and food containers due to clarity and barrier properties. Demand for recycled PET (rPET) concentrates in packaging across Europe, driven by EU Green Deal mandates.
- HDPE:High-density polyethylene (HDPE) is a robust, opaque thermoplastic for milk jugs and detergent bottles. Mechanical recycling of HDPE is mature, with significant demand from construction and consumer goods in China.
- PVC:Polyvinyl chloride (PVC) recycling faces challenges due to complex additives, primarily used in pipes.
- LDPE:Low-density polyethylene (LDPE) processes into film products, with recycling focused on industrial waste.
- PP:Polypropylene (PP) is a versatile thermoplastic for automotive components, needing advanced sorting.
- PS:Polystyrene (PS) recycling, including foam, uses chemical methods for new packaging.
Most installed capacity flows through PET. Expansion is steepest in PP.
Recycling Process:
This category differentiates processes based on their technological maturity and commercial scalability within the plastic recycling ecosystem.
- Mechanical:Mechanical recycling sorts, washes, shreds, and melts plastic waste into pellets for reuse. This process dominates for HDPE and PP, driven by lower capital intensity in Germany.
- Chemical:Chemical recycling breaks down polymers into monomers or valuable chemicals, creating virgin-quality plastics. Pyrolysis innovations expand feedstock options for mixed plastics, gaining investment in Asia.
- Pyrolysis:Pyrolysis converts mixed plastic waste into oils and gases, serving as feedstocks.
- Depolymerization:Depolymerization breaks down polymers like PET into monomers, allowing reconstitution of high-purity material.
- Solvent-Based:Solvent-based recycling dissolves target polymers from mixed waste, purifying them.
- Energy Recovery:Energy recovery incinerates plastic waste to generate heat or electricity, an alternative to landfilling.
Supply concentration for established processes resides with Mechanical recycling. New investment targets Chemical recycling pathways.
End Use Industry:
This segment categorizes plastic recycling by the primary application areas where recycled materials find their utility.
- Packaging:The packaging industry utilizes recycled plastics for bottles, containers, and films, reducing virgin material consumption. Brand owners in food and beverage, particularly in the US, drive demand for high-purity rPET.
- Construction:Recycled plastics incorporate into construction materials like pipes, insulation, and decking. Non-packaging applications represent a significant volume opportunity for mechanically recycled HDPE and PP in developing economies.
- Textiles:Recycled PET spins into fibers for synthetic fabrics, used in apparel and carpets.
- Electronics:Recycled plastics find use in electronic casings and components, supporting sustainable integration.
- Consumer Goods:Recycled content integrates into household items and toys, responding to consumer demand.
- Agriculture:Agricultural applications include greenhouse films and irrigation pipes, utilizing recycled plastics.
High-margin applications concentrate in Packaging, especially for food-grade content. Volume growth underpins Construction materials.
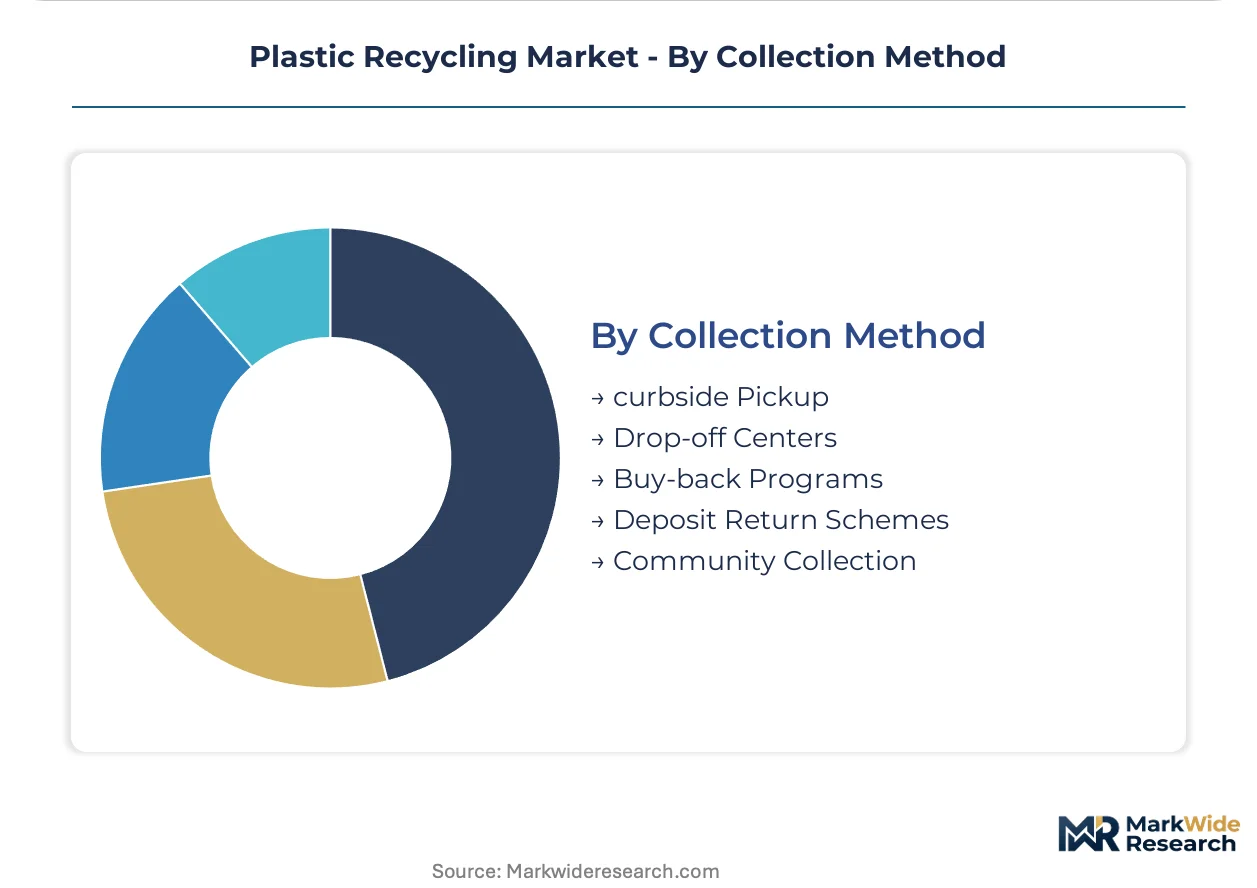
Collection Method:
This category delineates the various mechanisms employed to gather post-consumer plastic waste, impacting collection efficiency and material quality.
- Curbside Pickup:Curbside pickup collects commingled or source-separated recyclables directly from residential households. This method offers convenience but often results in higher contamination rates in urban centers like London.
- Drop-off Centers:Drop-off centers provide locations for consumers to bring sorted plastic waste, yielding cleaner material.
- Buy-back Programs:Buy-back programs offer financial incentives for returning plastic waste, ensuring higher purity.
- Deposit Return Schemes:Deposit return schemes add a refundable fee, incentivizing consumers to return empty beverage containers. These schemes are highly effective for collecting high-quality PET bottles, exemplified across Scandinavia.
- Community Collection:Community collection relies on local volunteer efforts to gather plastic waste.
Household participation is central to Curbside Pickup. Regulatory frameworks drive Deposit Return Schemes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Germany actively invests in mechanical recycling infrastructure, China's demand for high-quality recycled polymers is rapidly expanding. This regional divergence highlights varying maturity levels and investment priorities across global plastic recycling markets. Regulatory frameworks and evolving consumer preferences significantly influence these regional trajectories.
Germany
Demand for mechanically recycled HDPE and PP is strong from the automotive and consumer goods sectors. The country's Verpackungsgesetz (Packaging Act) mandates high recycling rates and recycled content. Industrial centers like North Rhine-Westphalia concentrate advanced mechanical recycling facilities, processing significant volumes of post-consumer plastics.
China
China's domestic demand for recycled content is rising, driven by its dual carbon goals and national circular economy policies. Manufacturers in coastal industrial zones are seeking high-quality recycled polymers for packaging and textiles. Investment in chemical recycling technologies is expanding to process difficult-to-recycle mixed plastic streams.
United States
The packaging industry, particularly food and beverage brand owners, drives demand for high-purity rPET. Directives from the US Environmental Protection Agency (EPA) encourage increased plastic recycling infrastructure and innovation. States like California lead in establishing recycled content mandates, fostering a concentrated market for rPET in beverage bottles.
Sweden
Sweden's highly effective Deposit Return Schemes (DRS) ensure a clean, high-volume feedstock of PET bottles for bottle-to-bottle recycling loops. The country's environmental policies prioritize circularity and resource efficiency in packaging. Scandinavian countries, including Sweden, demonstrate best practices in high-quality plastic collection and reprocessing.
India
Emerging national policies on waste management and plastic pollution are creating new markets for recycled content in India. The construction sector and consumer goods manufacturers are increasing their use of recycled HDPE and PP. Major urban centers like Mumbai and Delhi are developing collection and sorting infrastructure to meet this nascent demand.
Plastic Recycling Market Key Industry Players
Top-tier vendors anchor large-scale, integrated waste management and recycling services, while specialized operators focus on high-purity polymer streams. The market structure exhibits a dual nature, with capital-intensive chemical recycling facilities coexisting with established mechanical recycling plants. Key strategic archetypes include integrated waste managers, specialized polymer recyclers, and technology providers. Capacity expansion and strategic partnerships dominate competitive moves.
Specialists in high-purity PET recycling, such as Indorama Ventures Public Company Limited, often focus on specific polymer types for bottle-to-bottle loops. Meanwhile, integrated waste management firms like Veolia Environnement S.A. and Waste Management Inc. leverage their vast collection networks. These large operators process a wide spectrum of plastic waste streams, often serving diverse end-use industries with both mechanically and chemically recycled materials.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Indorama Ventures Public Company Limited |
| Waste Management Inc. |
| SUEZ SA |
| Republic Services Inc. |
| B&B Plastics Inc. |
| Plastipak Holdings Inc. |
| MBA Polymers Inc. |
| KW Plastics |
| Others |
Cost & Logistics Intelligence
Energy costs influence processing fees for recycled plastics, impacting final pellet prices for downstream packaging manufacturers. This cost component flows from utility providers through recycling facilities, ultimately affecting the competitiveness of recycled content against virgin materials.
Pricing Analysis
Capacity additions in Europe are reshaping price floors for high-purity rPET. The dominant pricing model for food-grade recycled polymers shifts towards contract-based long-term offtake agreements. Price differentiation stems from certification levels for food contact and the volume scale of purchases. Pricing pressure intensifies on lower-grade mixed plastics due to feedstock contamination. Packaging brands are less price-sensitive for certified rPET, while construction materials manufacturers prioritize cost-effectiveness.
Supply Chain Analysis
Workforce availability in collection and sorting centers across Europe and North America influences the consistency of feedstock supply. The supply chain for recycled plastics draws from post-consumer waste streams, heavily dependent on robust collection infrastructure. Geographic concentration for high-quality rPET feedstock centers on Scandinavia and the US, while mechanical recycling for HDPE and PP is strong in Germany and China. A structural risk involves the inconsistent quality of post-consumer waste. Distribution runs through direct contracts with brand owners for high-purity materials and bulk sales to compounders for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic recycling market is transitioning into a late-cycle quality story, driven by a pronounced demand-shift towards premium, food-grade recycled polymers. This shift prioritizes material purity and traceability over mere volume recovery, redefining competitive landscapes.
For Market Incumbents: Lock in long-term supply agreements with major brand owners to secure demand for high-purity rPET and rHDPE. Invest in advanced sorting technologies like AI-driven robotics to mitigate feedstock contamination and maintain quality. This defends against emerging chemical recycling technologies and ensures compliance with EU Green Deal mandates. Focus R&D on depolymerization to expand feedstock options for difficult-to-recycle streams.
For New Entrants and Emerging Players: Begin with specialized chemical recycling solutions targeting mixed plastic waste streams, particularly in Asia where infrastructure is emerging. The most penetrable segment lies in processing difficult-to-recycle plastics like PS and mixed films, converting them into valuable feedstocks. A strong go-to-market angle involves offering virgin-quality output for non-packaging applications such as automotive components. Partner with technology providers for pyrolysis innovations.
For Investors and Strategic Acquirers: Consolidation pressure builds where advanced sorting and chemical recycling technologies require substantial capital intensity. Long-term viability over a five-to-ten-year window favors vertically integrated operators controlling both collection and reprocessing. Target acquisition archetypes include specialized polymer recyclers with proprietary depolymerization or solvent-based technologies. The signal to watch is the widespread adoption of digital watermarking across packaging supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (Chemical Recycling) | Increases supply of virgin-quality polymers for diverse applications, meeting regulatory demand. |
| Backward Integration (Collection/Sorting) | Secures consistent, high-quality feedstock, reducing processing costs and contamination risks. |
| Advanced Sorting Technology Investment | Unlocks access to food-grade markets by improving material purity, critical for brand owners. |
| Long-term Offtake Agreements | Stabilizes revenue streams and provides demand certainty for recycled content producers. |
| Green Certification Program | Enhances market access and brand reputation, particularly in sustainability-driven European markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Interviews with recycling plant managers, brand owner sustainability leads, waste management executives, and regulatory policy advisors informed the analysis. Secondary data from EU Green Deal reports, EPA directives, China's national policies, and company 10-K filings provided market context. This approach ensured robust bottom-up and top-down triangulation.
Historical market performance across comparable periods anchored the forecast framework over the projection horizon. The analytical model segmented the market by plastic type, recycling process, end-use industry, collection method, and regional regulatory cluster. Compound Annual Growth Rates (CAGRs) were derived from projected shifts in demand and supply. Key forecast inputs included evolving recycled content mandates and global virgin polymer prices.
Several conditions sit outside the modeled scope, including unforeseen policy reversals and rapid technological obsolescence in recycling. The forecasts reflect assumptions regarding regulatory stability and continued investment trends. Material deviation in global trade policies or significant shifts in virgin plastic pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market