
 Polymer Binders Market | 2026-2036
Polymer Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Binders Market Analysis
Specialized polymer chemist availability is bifurcating the competitive landscape, separating firms with captive formulation expertise from commodity-dependent operators. BASF SE leverages its Ludwigshafen integrated site to sustain captive acrylic acid supply for binder production. Dow anchors North American emulsion capacity through its Freeport, Texas manufacturing complex. Wacker Chemie AG differentiates via silicone-acrylic hybrid technologies for high-performance coatings.
Polymer binders are film-forming resins that adhere pigment particles to substrates and cohesive layers to one another, typically comprising acrylic, styrene-butadiene, or vinyl acetate copolymers with glass transition temperatures engineered between minus twenty and plus sixty degrees Celsius for specific flexibility and hardness requirements. Acrylic emulsions dominate architectural coatings due to superior UV resistance and water repellency, while styrene-butadiene latex retains cost advantages in carpet backing and paper saturation where odor and yellowing tolerance is higher. Waterborne formulations are displacing solventborne systems across all major applications as VOC regulations tighten and drying energy costs favor aqueous dispersion technologies.
EPA VOC limits under 40 CFR Part 59, REACH Annex XVII restrictions on hazardous substances, and China's GB standards for architectural coatings collectively reshape product development priorities and market access conditions for polymer binder suppliers. ECHA's ongoing restriction proposals for microplastics and formaldehyde releasers are forcing reformulation of certain adhesive and sealant grades before enforcement deadlines. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification costs.
Market Dynamics
Waterborne acrylic emulsion capacity expansion in China is compressing regional cost structures and forcing Western suppliers to defend margin positions through formulation specialization rather than commodity scale.
Growth Catalysts
- EPA VOC limits under 40 CFR Part 59:Architectural coatings manufacturers in the United States are reformulating solventborne systems to waterborne acrylic emulsions to maintain market access.
- Exterior coatings demand:Construction sector specification of waterborne acrylic binders for durability and UV resistance is accelerating replacement of alkyd and urethane systems.
- China infrastructure investment:State-funded transportation and residential projects are concentrating regional demand for compliant emulsion technologies.
Market Restraints
- Propylene and acrylic acid price volatility:Feedstock cost swings compress margin predictability for emulsion producers without captive monomer supply.
- Specialized polymer chemist scarcity:Formulation expertise concentration in Germany, Japan, and select US industrial clusters limits technical service scalability.
- REACH Annex XVII microplastics restriction:ECHA's pending enforcement is forcing adhesive and sealant grade reformulation ahead of compliance deadlines.
Strategic Opportunities
- India construction chemicals penetration:BIS certification requirements and infrastructure spending are opening specification opportunities for compliant waterborne systems.
- Silicone-acrylic hybrid technology:Convergence of silicone weatherability with acrylic cost structures enables premium exterior coating positioning.
- Direct technical service to mid-tier applicators:Bypassing traditional distributor channels captures specification influence in fragmented regional construction markets.
Industry Challenges
- Glass transition temperature calibration:Matching Tg engineering to substrate-specific flexibility and hardness requirements demands iterative formulation testing.
- Multi-jurisdiction certification redundancy:Divergent VOC limits across EPA, REACH, and China's GB standards create stranded inventory risk for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Binders Market |
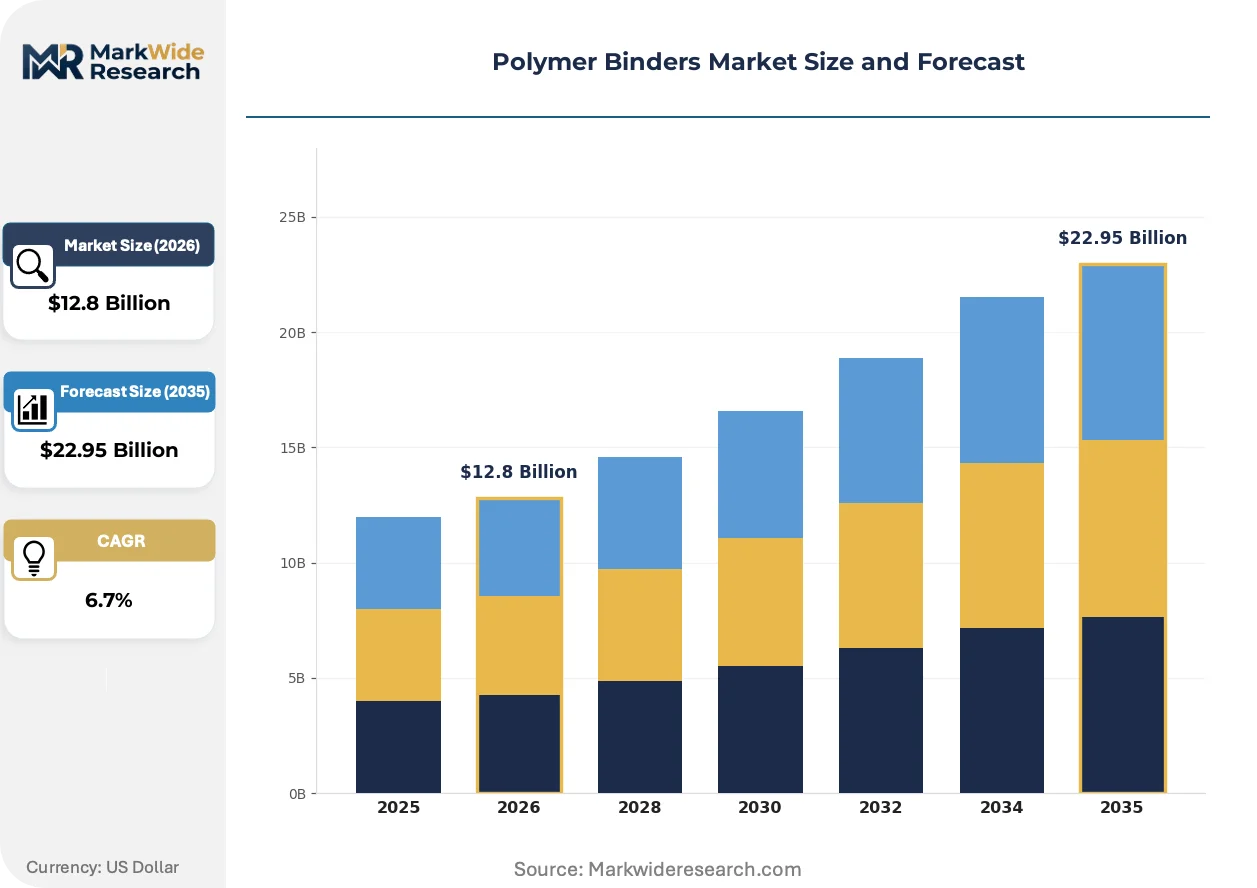
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Styrene-Butadiene, Polyvinyl Acetate, Ethylene-Vinyl Acetate Application: Coatings, Adhesives, Sealants, Plastics End User: Construction, Automotive, Consumer Goods, Electronics Form: Waterborne, Solventborne, Powder, Emulsion |
| Companies Covered | Arkema, Dairen Chemical Corporation, BASF SE, The Lubrizol Corporation, Toagosei Co. Ltd., Wacker Chemie AG, Dow, Trinseo, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Binders Market Emerging Trajectories
Formulation science is pivoting toward hybrid chemistries and process intensification as energy costs and regulatory thresholds harden competitive requirements for film-forming resin suppliers.
Self-crosslinking acrylic emulsion technology is fragmenting the architectural coatings supply base. These systems eliminate external crosslinker addition, reducing mixing complexity and VOC contribution. Premium residential and commercial exterior applicators in Germany and Japan are specifying self-crosslinking grades for durability guarantees. The technology is fragmenting traditional two-component coating segments by collapsing formulation steps into single-package delivery.
REACH Annex XVII restrictions on formaldehyde releasers are compressing adhesive and sealant product development timelines. ECHA's restriction proposals force reformulation of interior-grade wood adhesives and carpet backing binders before enforcement deadlines. European flooring and furniture manufacturers are accelerating supplier audits to secure compliant styrene-butadiene and vinyl acetate alternatives.
Specification influence is migrating toward certified applicator networks. Large-scale infrastructure contractors in China and India are consolidating procurement through pre-qualified vendor lists with BIS or GB standard compliance documentation. This concentration is compressing distributor margins and favoring binder suppliers with captive technical service capacity in target construction clusters.
Polymer Binders Market Segmentation
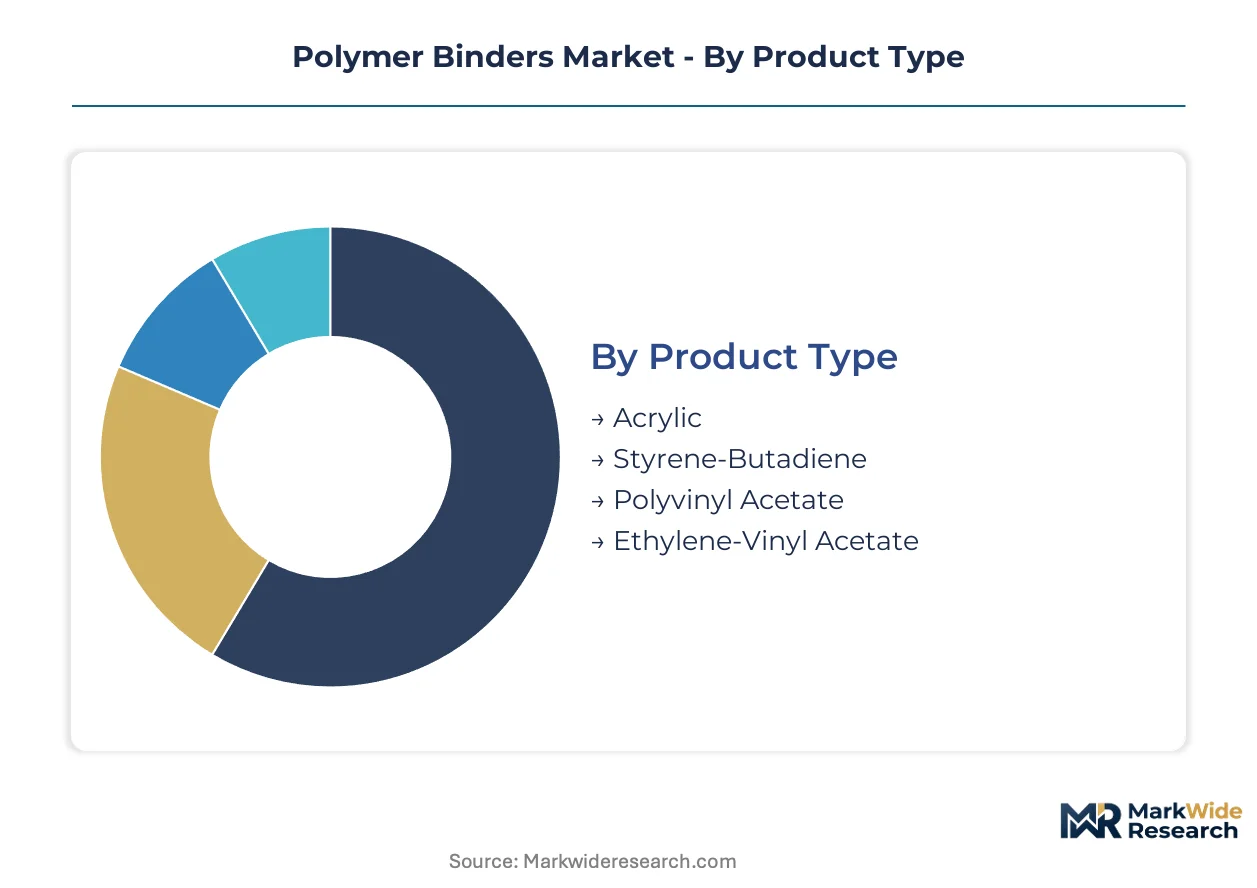
Polymer binder formulation choices cascade through specification chains, determining compliance eligibility, application performance, and margin structure. Substitution pressure across chemistries and delivery forms is intensifying as VOC regulations harden and energy costs favor aqueous systems.
Product Type:
Acrylic emulsions face the strongest substitution threat from hybrid silicone-acrylic systems in premium exterior coatings, while styrene-butadiene latex defends share in cost-sensitive industrial applications.
- Acrylic:UV-resistant copolymers with engineered glass transition temperatures between minus twenty and plus sixty degrees Celsius dominate architectural coatings specifications. Demand concentrates in China infrastructure projects and Germany residential renovation, driven by REACH and EPA VOC limits compressing solventborne alternatives.
- Styrene-Butadiene:Cost-optimized latex with higher odor and yellowing tolerance retains volume in carpet backing and paper saturation. Procurement clusters in US Southeast manufacturing corridors and Indian textile processing zones, constrained by feedstock propylene price volatility.
- Polyvinyl Acetate:Interior wood adhesive grades face ECHA formaldehyde releaser restrictions forcing reformulation timelines.
- Ethylene-Vinyl Acetate:Hot-melt and packaging applications in consumer goods assembly.
Styrene-butadiene anchors the volume base while acrylic gains share at the steepest rate.
Application:
Margin structures diverge sharply across application tiers, with coatings commanding formulation premiums and adhesives facing commoditization pressure from private-label competition.
- Coatings:Architectural and industrial film-forming systems represent the revenue concentration point, with exterior durability specifications driving silicone-acrylic hybrid adoption. Demand clusters in China state-funded transportation infrastructure and India commercial construction, shaped by BIS certification requirements and GB standard compliance.
- Adhesives:Wood bonding and assembly applications face REACH Annex XVII microplastics restrictions compressing product development cycles. European flooring manufacturers are accelerating supplier audits to secure compliant alternatives ahead of enforcement deadlines.
- Sealants:Construction joint and automotive gap-filling grades subject to multi-jurisdiction VOC limit divergence.
- Plastics:Polymer modification and compatibilization in packaging and durable goods.
Coatings generates the highest value per ton while adhesives expands most quickly on unit volume.
End User:
Customer concentration patterns favor direct technical service models, with large contractors consolidating procurement through pre-qualified vendor lists.
- Construction:Infrastructure and residential specification drives waterborne emulsion displacement of solventborne systems. Procurement concentrates through certified applicator networks in China and India, with BIS and GB documentation requirements filtering supplier access.
- Automotive:OEM and refinish coatings demand Tg-calibrated flexibility for plastic substrate adhesion.
- Consumer Goods:Packaging and furniture assembly applications.
- Electronics:Encapsulation and protective coating grades.
Construction absorbs the dominant volume share while automotive climbs fastest on electrification-driven lightweighting needs.
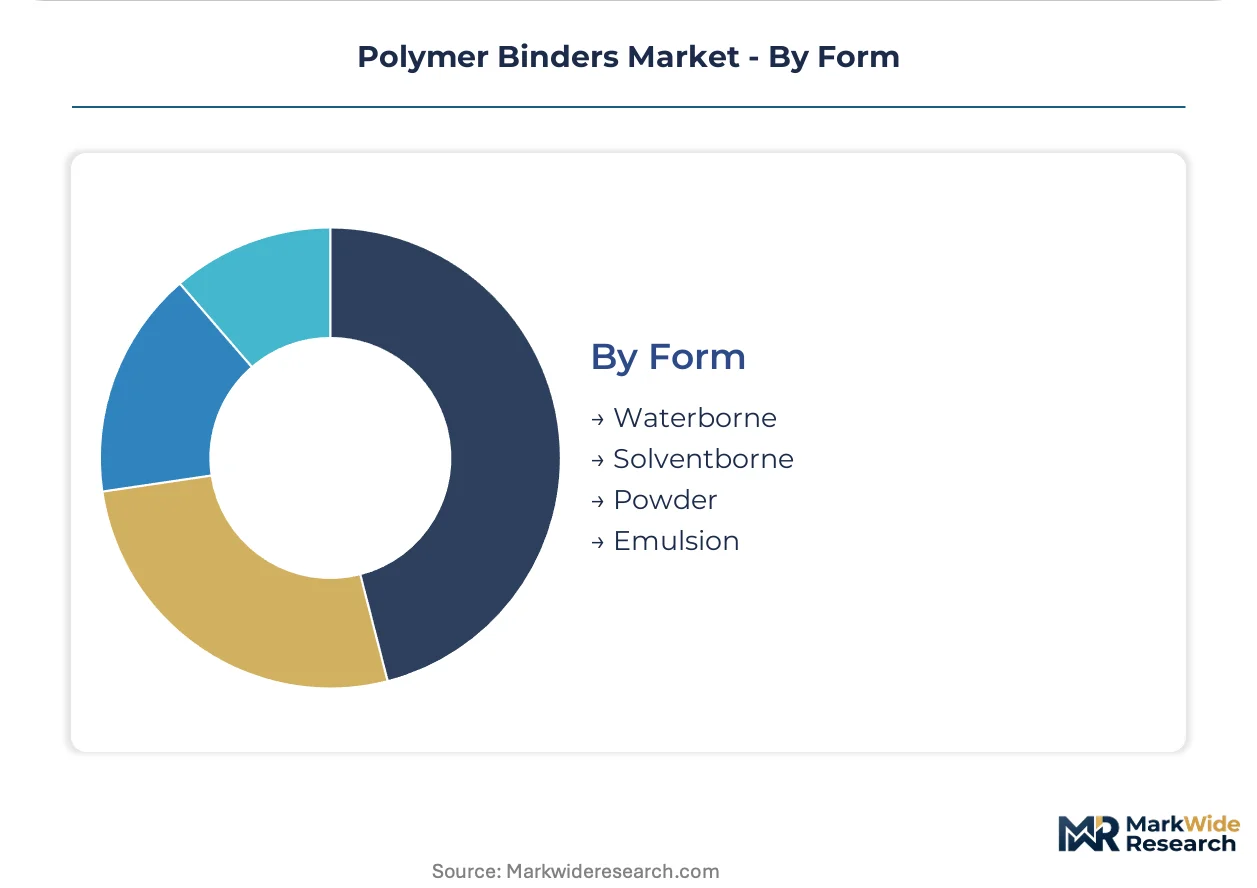
Form:
Process energy requirements and drying infrastructure investments are reconfiguring form selection across manufacturing footprints.
- Waterborne:Emulsion and dispersion technologies capture specification share as VOC regulations tighten and drying energy costs favor aqueous systems. EPA 40 CFR Part 59 compliance and REACH restrictions are redirecting formulation spending toward compliant emulsion technologies in US and European architectural markets.
- Solventborne:High-performance industrial and automotive refinish grades retain niche positions where humidity control and substrate compatibility demand solvent carriers.
- Powder:Zero-VOC industrial coating applications in metal finishing.
- Emulsion:Liquid delivery systems for on-site dilution and application.
Waterborne holds the installed capacity base while powder posts the steepest expansion trajectory on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC limits under 40 CFR Part 59 anchor North American compliance architecture, while China's GB standards and REACH Annex XVII restrictions collectively reshape formulation priorities across three continents. Regional demand clusters around infrastructure corridors where certified applicator networks consolidate procurement.
United States
Exterior coatings demand from residential construction and transportation infrastructure drives waterborne acrylic emulsion consumption. EPA 40 CFR Part 59 compliance deadlines force solventborne system replacement across architectural markets. The Gulf Coast petrochemical corridor around Freeport, Texas anchors domestic emulsion manufacturing capacity.
Germany
Residential renovation specifications and automotive OEM coatings sustain premium binder demand. REACH Annex XVII restrictions on formaldehyde releasers compress adhesive product development timelines. The Ludwigshafen chemical complex maintains integrated acrylic acid supply for captive binder production.
China
State-funded transportation infrastructure and residential construction concentrate regional emulsion demand. GB standards for architectural coatings redirect formulation spending toward compliant waterborne technologies. The Yangtze River Delta manufacturing cluster expands domestic emulsion capacity, compressing cost structures.
India
Infrastructure spending and commercial construction penetration open specification opportunities for compliant waterborne systems. BIS certification requirements filter supplier access through pre-qualified vendor lists. Western and Southern industrial corridors around Maharashtra and Gujarat attract technical service investment from multinational suppliers.
Japan
Premium residential exterior applicators specify self-crosslinking acrylic grades for durability guarantees. METI energy efficiency standards favor aqueous dispersion technologies over solventborne alternatives. The Kansai industrial region around Osaka maintains formulation expertise clusters for high-performance coating development.
Polymer Binders Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive monomer supply separating margin-stable operators from feedstock-exposed competitors. BASF SE and Dow anchor the integrated tier through Ludwigshafen and Freeport manufacturing complexes respectively. Three archetypes dominate: integrated petrochemical players with captive acrylic acid, hybrid technology specialists leveraging silicone-acrylic convergence, and regional emulsion producers competing on cost. Competitive moves concentrate on formulation specialization to defend margin positions against Chinese capacity expansion, and direct technical service deployment to capture specification influence in fragmented construction markets.
Among European integrated players, BASF SE and Wacker Chemie AG occupy positions at opposite ends of the technology spectrum, with the former exemplifying petrochemical integration and the latter representing hybrid specialty approaches. Dow anchors North American capacity through its Texas manufacturing presence. Dairen Chemical Corporation and Toagosei Co. Ltd. sit within the Asia-Pacific specialist tier, reflecting regional supply chain concentration around China and Japan respectively.
| Leading Market Players |
|---|
| Arkema |
| Dairen Chemical Corporation |
| BASF SE |
| The Lubrizol Corporation |
| Toagosei Co. Ltd. |
| Wacker Chemie AG |
| Dow |
| Trinseo |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between acrylic acid producers and emulsion manufacturers lock in feedstock access and strip out price volatility for integrated operators like BASF SE, while spot-exposed competitors absorb margin compression from propylene cost swings. These contract structures concentrate purchasing power among buyers with captive monomer supply or multi-year supply commitments, fragmenting the competitive landscape between margin-stable integrated players and commodity-dependent regional producers.
Pricing Analysis
Contract-based long-term offtake dominates procurement between integrated petrochemical players and major emulsion manufacturers, with spot transactions filling residual volume for smaller regional producers. Price differentiation rests on certification grade—EPA 40 CFR Part 59 and REACH Annex XVII compliance tiers command premiums over basic formulations—and volume scale, where infrastructure contractors in China negotiate consolidated pricing through pre-qualified vendor lists. Pricing pressure stems from Chinese domestic capacity expansion compressing regional cost structures, particularly for standard-grade acrylic emulsions. Mid-tier applicators in India exhibit the highest price sensitivity, while German automotive OEM coatings buyers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites the bulk of acrylic acid and propylene feedstock flows from Middle Eastern and Asian petrochemical hubs to emulsion manufacturing clusters in China, Germany, and the United States. Supply concentrates in China, Germany, and the US Gulf Coast, with the Yangtze River Delta and Ludwigshafen anchoring regional production. Raw material dependencies center on propylene, acrylic acid, and styrene monomer, with feedstock cost volatility transmitting directly to emulsion pricing. Single-source vulnerability from concentrated acrylic acid production creates structural risk for non-integrated binders producers. Distribution runs through certified applicator networks in construction markets, bypassing traditional distributor channels in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions are expanding faster than base emulsion sales, as construction contractors in China and India outsource compliance documentation and application engineering to binder suppliers. This service-attach layer reconfigures vendor relationships from transactional supply toward ongoing specification partnerships.
For Market Incumbents: Compound formulation specialization advantages by embedding technical service teams within certified applicator networks in Maharashtra and Gujarat industrial corridors. Invest in silicone-acrylic hybrid R&D to defend premium positioning against Chinese commodity expansion. Backward integration into captive acrylic acid supply remains the critical lever for margin stability as propylene volatility intensifies.
For New Entrants and Emerging Players: Differentiate on BIS certification speed and localized technical service rather than emulsion volume scale. Target India's Western and Southern construction corridors where infrastructure spending outpaces compliant supply availability. Pursue direct specification relationships with mid-tier contractors outside pre-qualified vendor lists as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid technology specialists with silicone-acrylic convergence capabilities and established GB standard compliance documentation for China access. Long-term viability hinges on regulatory adaptation capacity across multi-jurisdiction VOC limits. Watch ECHA microplastics enforcement timelines as the signal for adhesive and sealant grade reformulation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive monomer supply insulates margins from propylene volatility at Freeport and Ludwigshafen complexes. |
| Silicone-Acrylic Hybrid R&D Investment | Convergence technology commands premium positioning in exterior coatings specifications across German and Japanese markets. |
| Direct Technical Service Deployment | Bypassing distributor channels captures specification influence in fragmented India and China construction markets. |
| Multi-Jurisdiction Certification Investment | EPA, REACH, and GB standard compliance documentation filters supplier access to pre-qualified vendor lists. |
| Long-term Supply Agreement with Infrastructure Contractors | Consolidated procurement through state-funded China transportation projects anchors volume commitments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymer chemists at emulsion manufacturers, procurement leads at architectural coatings formulators, technical service directors at multinational suppliers, and plant managers at integrated petrochemical complexes. Secondary validation drew from SEC 10-K filings, ECHA restriction proposal documentation, customs trade data for acrylic acid and emulsion flows, and BIS certification registries. Bottom-up demand modeling across construction, automotive, and adhesive applications was triangulated against top-down capacity assessments from major manufacturing clusters.
Across the analysis window, forecasts were constructed using a segmented analytical framework spanning chemistry type, application tier, end-use industry, and regional regulatory cluster. CAGRs were derived from iterative reconciliation of demand-pull factors—EPA and REACH compliance deadlines, China infrastructure spending cycles—with supply-push dynamics including domestic capacity expansion and feedstock cost trajectories. Industry-specific inputs incorporated glass transition temperature engineering requirements for substrate-specific applications and VOC limit divergence across jurisdiction boundaries.
Material uncertainties—ECHA microplastics enforcement timing, propylene price volatility amplitude, and BIS certification backlog duration—sit outside the modeled envelope and could revise trajectory assumptions. Practitioners should keep alternative scenarios live as regulatory enforcement schedules and feedstock cost regimes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market