
 Global Construction Plastics Market | 2026-2036
Global Construction Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Plastics Market Analysis
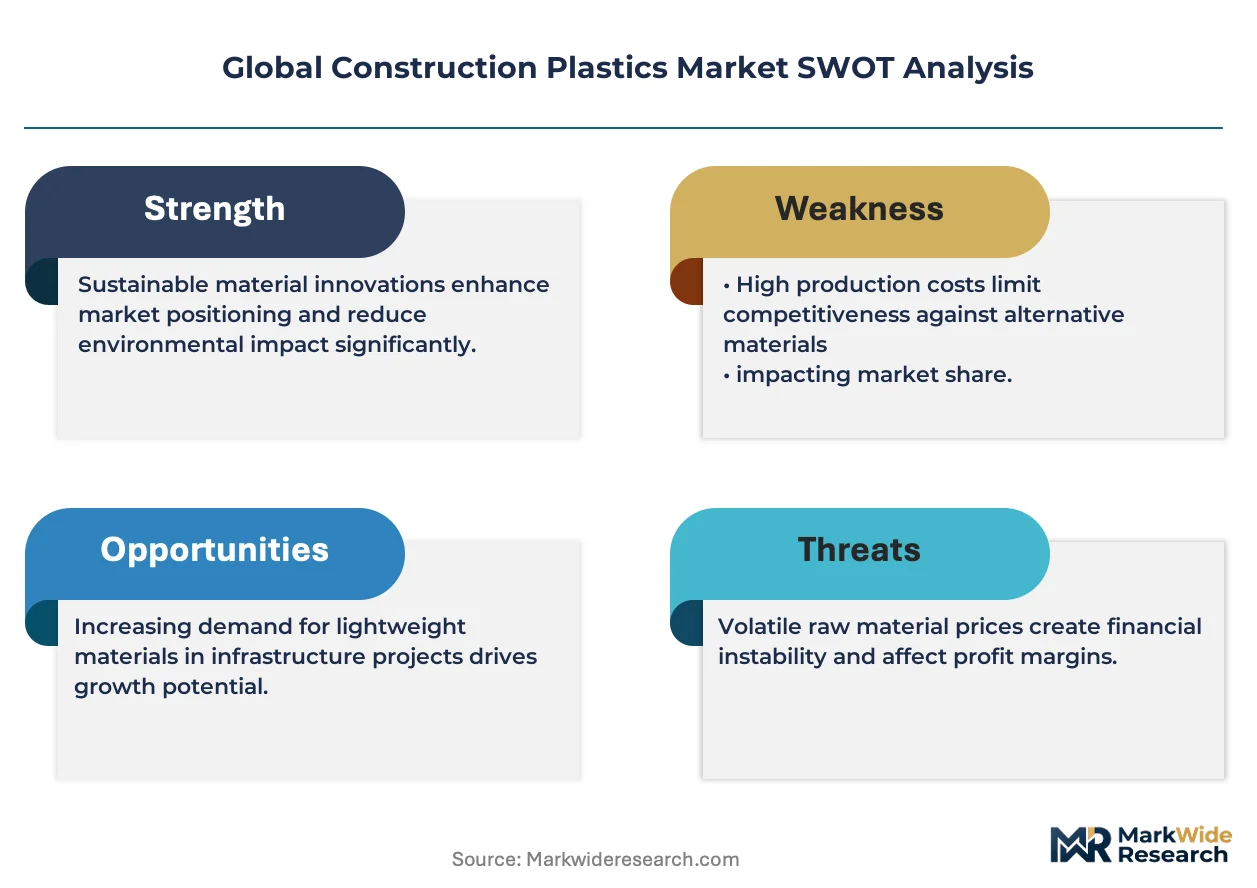
Construction plastics distribution through regional building-material wholesalers is fragmenting as direct-to-contractor platforms and manufacturer-owned depots gain share. BASF leverages its integrated polyamide and polyurethane supply chains to secure specification-grade positions in European commercial facades. SABIC anchors Middle Eastern and Asian project pipelines through localized compounding operations that reduce landed costs for infrastructure developers. Dow competes aggressively in North American residential plumbing with high-density polyethylene resins certified to NSF/ANSI standards.
Construction plastics encompass thermoplastic and thermoset polymers formulated with additives for load-bearing, thermal insulation, moisture resistance, and dimensional stability in built environments, typically processed through extrusion, injection molding, or thermoforming to achieve specified fire ratings and compressive strengths. Polyvinyl chloride dominates plumbing and roofing membranes due to decades of code acceptance and installed-base familiarity, though polyethylene is displacing legacy materials in potable water and geothermal piping where flexibility and fusion welding reduce failure rates. Residential end users generate the largest volume pull, while commercial and institutional segments concentrate margin pools in custom-colored, flame-retardant formulations that command specification premiums.
REACH in Europe, the EU Green Deal embodied carbon thresholds, and EPA stormwater regulations in the United States are reshaping material selection by restricting phthalate plasticizers and mandating recycled content disclosures in public procurement. China's GB standards and MIIT energy-efficiency codes enforce minimum thermal performance in building envelopes, channeling demand toward expanded polystyrene and polypropylene insulation boards. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned product development pipelines.
Market Dynamics
Embodied carbon thresholds in public procurement are forcing polymer producers to reconfigure feedstock sourcing and certification workflows before specification eligibility expires.
Growth Catalysts
- REACH chemical restrictions:Phased phthalate bans in the European Union accelerate substitution toward bio-based plasticizers in flexible PVC membranes.
- Geothermal piping uptake:Polyethylene fusion welding reduces failure rates in residential ground-source heat pumps across Germany and the Netherlands.
- MIIT energy-efficiency codes:China's thermal performance mandates channel demand toward expanded polystyrene insulation in northern provincial construction.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins swing with crude differentials, compressing polypropylene compounder margins in Asian export markets.
- Chlor-alkali supply concentration:European PVC resin production clusters along the Rhine corridor, exposing downstream extruders to river logistics disruptions.
- Recycled-content contamination limits:Food-contact migration thresholds block post-consumer polyethylene reintegration in potable water piping.
Strategic Opportunities
- Modular construction penetration in India:Prefabricated wall panel demand creates specification pathways for flame-retardant polypropylene composites.
- EU Green Deal public procurement:Recycled-content disclosure mandates open tender advantages for verified mass-balance polymers.
- Digital twin integration:Building information modeling platforms embed material traceability, rewarding suppliers with blockchain-verified supply chains.
Industry Challenges
- Polymer welding technician scarcity:Fusion certification programs lag polyethylene piping deployment in North American residential markets.
- Fire rating recertification timelines:Updated ASTM E84 testing protocols delay commercial membrane approvals by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Plastics Market |
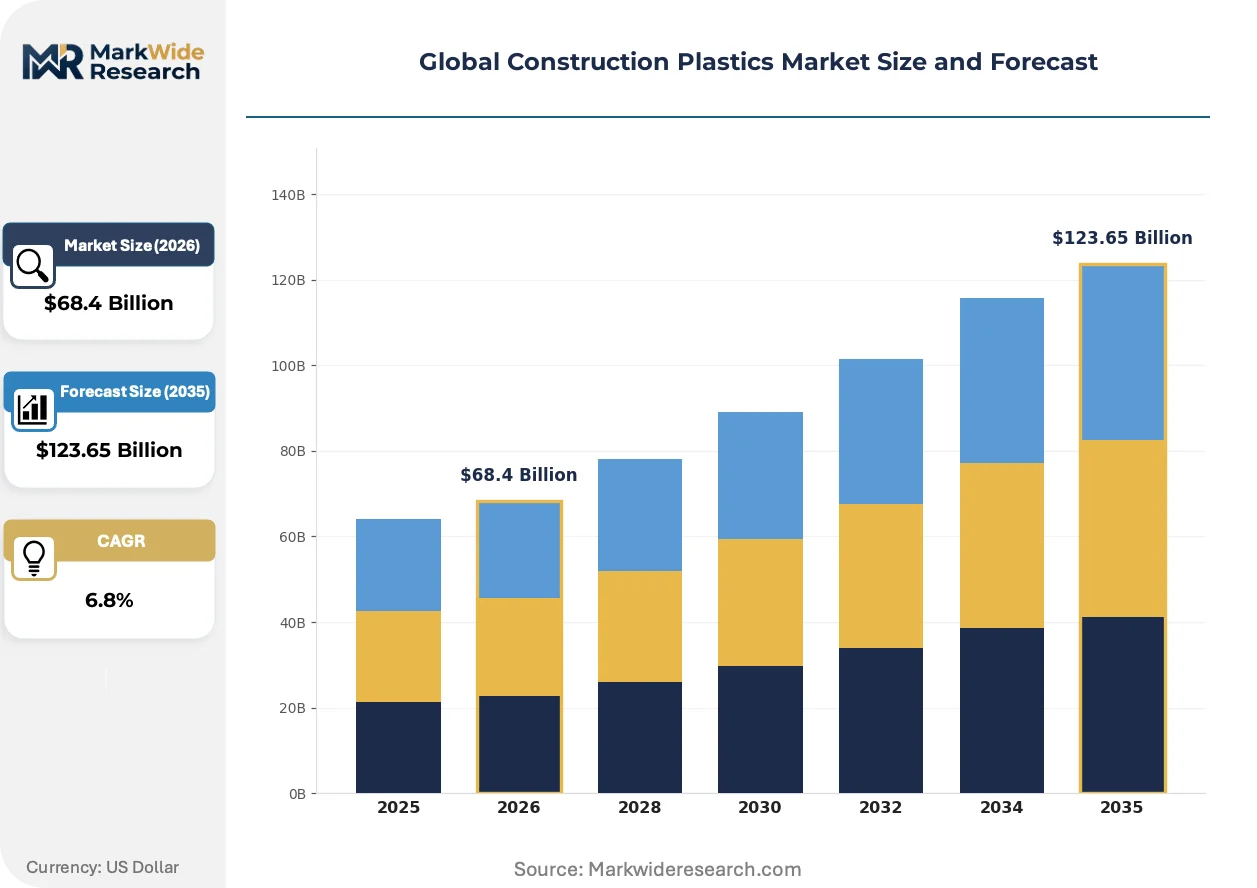
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Roofing, Flooring, Plumbing, Insulation End User: Residential, Commercial, Institutional, Industrial Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | BASF, SABIC, Dow, LyondellBasell Industries Holdings B.V., Borealis GmbH, Formosa Plastics Corporation, INEOS, Solvay, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Plastics Market Emerging Trajectories
Material science convergence with digital specification platforms is compressing product development cycles and redefining competitive advantage around traceability rather than commodity scale.
Polymer matrix composites incorporating recycled carbon fiber and bio-epoxy resins are hybridizing structural profiles for load-bearing facade elements. Commercial architects in Copenhagen and Singapore specify these hybrids for curtainwall spandrels where thermal bridging penalties now exceed material cost premiums. The technology is hybridizing supply chains, forcing resin compounders to partner with aerospace waste aggregators for fiber feedstock security.
The EU Green Deal embodied carbon thresholds now mandate Environmental Product Declarations for structural polymers in public works above 10 million euros. This policy compresses allowable cradle-to-gate emissions for PVC and polystyrene insulation by 40 percent against 2020 baselines. German and French contractors respond by sourcing mass-balance certified resins through BASF and INEOS circular economy portfolios, locking in multi-year offtake agreements.
Specification decisions increasingly migrate from general contractors to asset owners and their sustainability consultants, disintermediating traditional distributor relationships. This shift concentrates purchasing power among European pension funds and Asian sovereign wealth vehicles with net-zero portfolio mandates. The pattern is most visible in London and Sydney commercial tower developments where owner-operators now require ISO 14040 lifecycle data for all polymer-containing assemblies.
Global Construction Plastics Market Segmentation
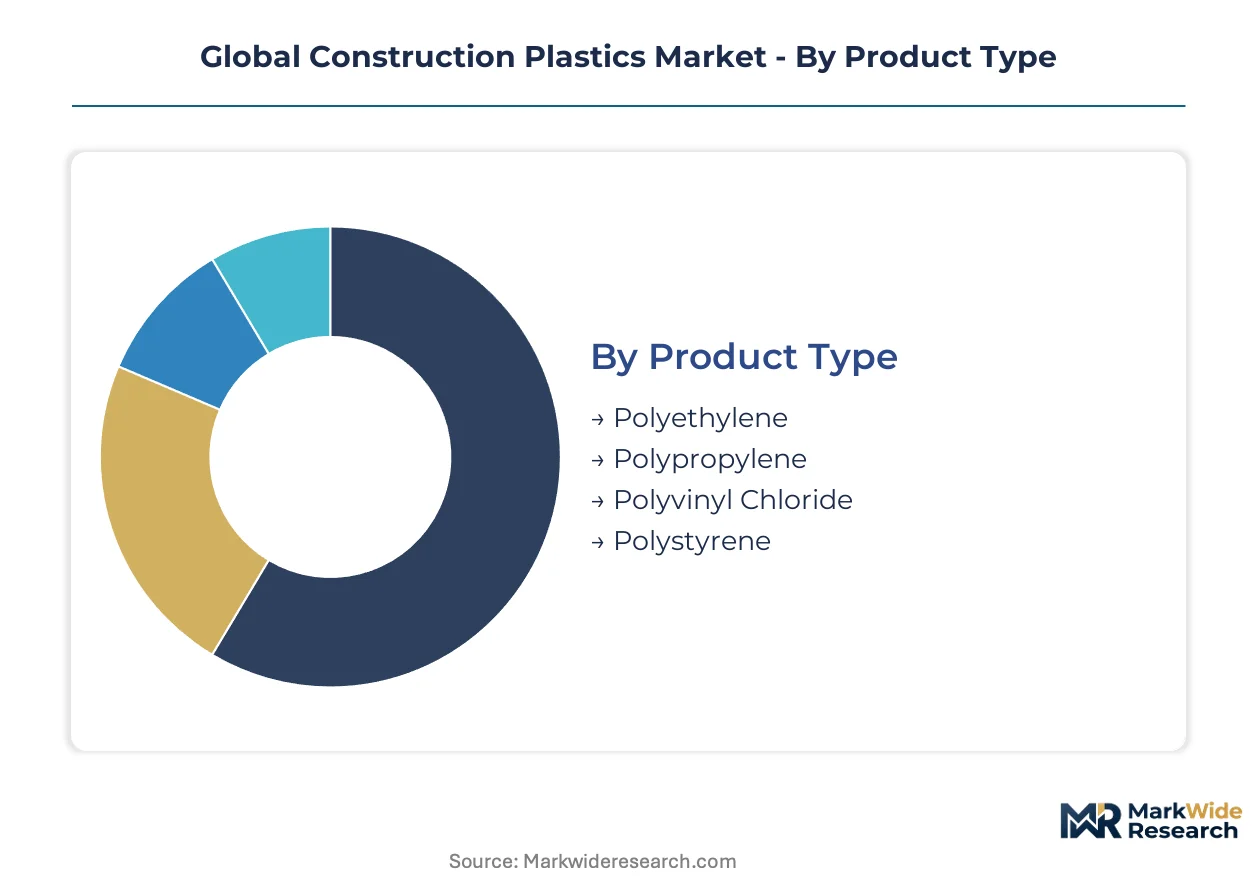
Segmentation in construction plastics reveals how material specifications diverge across building codes, climate zones, and procurement channels. Understanding these splits enables suppliers to align compounding investments with the highest-margin specification pathways.
Product Type:
The use-case spectrum spans flexible membranes for weatherproofing to rigid structural profiles demanding fire-rated performance.
- Polyethylene:Linear low-density and high-density grades dominate potable water piping and geothermal ground-loop systems. German and Dutch residential developers specify PE100 and PE4710 resins for fusion-welded distribution networks that eliminate joint failure risks in ground-source heat pump installations.
- Polyvinyl Chloride:Rigid and plasticized formulations serve plumbing drainage, window profiles, and single-ply roofing membranes. REACH phthalate restrictions are accelerating bio-based plasticizer adoption in European flexible PVC for commercial roofing, while unplasticized PVC maintains code acceptance for soil-waste-vent stacks across North American residential construction.
- Polypropylene:Homopolymer and copolymer grades with mineral reinforcement find structural application in HVAC ducting and prefabricated wall panels. Flame-retardant PP compounds are gaining specification in Indian modular construction projects where MIIT-equivalent fire codes are tightening.
- Polystyrene:Expanded and extruded variants provide thermal insulation in building envelopes. China's GB 50176 energy-efficiency mandates channel demand toward EPS boards in northern provincial housing programs targeting envelope performance upgrades.
The dominant share belongs to Polyvinyl Chloride, while Polyethylene is closing the gap fastest.
Application:
Cost tier stratification separates commodity weatherproofing from specification-grade systems commanding engineering review.
- Plumbing:Pressure-rated piping systems for potable water, drainage, and geothermal circulation represent the highest volume application. NSF/ANSI 14 and 61 certifications gate North American residential specification, while European contractors prioritize KIWA and DVGW approvals for polyethylene fusion systems.
- Insulation:Thermal and acoustic barrier materials in walls, roofs, and foundations command premium pricing for fire-rated and low-embodied-carbon formulations. EU Green Deal procurement thresholds are shifting specification toward mass-balance certified polystyrene and polyisocyanurate alternatives in German and French public housing.
- Roofing:Single-ply membranes and liquid-applied coatings protect commercial and industrial building envelopes. TPO and PVC membrane demand concentrates in US Sun Belt states where cool-roof reflectance ratings reduce HVAC loads.
- Flooring:Resilient sheet, tile, and luxury vinyl plank products serve residential renovation and commercial fit-out markets. California Department of Public Health VOC emission standards (CDPH Section 01350) restrict phthalate content in flexible flooring specified for schools and healthcare.
Plumbing commands the largest volume position, though Insulation exhibits the steepest expansion trajectory as thermal code adoption accelerates.
End User:
Customer type determines specification complexity, with asset-owner procurement teams displacing general contractor material selection.
- Residential:Single-family and multi-family housing generates baseline demand for piping, siding, and insulation in new construction and renovation. US EPA stormwater regulations drive permeable paver and rainwater harvesting system uptake in suburban developments.
- Commercial:Office, retail, and hospitality projects concentrate margin in custom-color, flame-retardant, and LEED-contributing formulations. Singapore and Copenhagen commercial towers specify recycled carbon fiber-polymer hybrids for curtainwall spandrels where thermal bridging penalties outweigh material premiums.
- Institutional:Schools, hospitals, and government buildings impose stringent fire, emissions, and lifecycle disclosure requirements. EU Green Deal EPD mandates above 10 million euro contract values lock in mass-balance certified suppliers for German and French public works.
- Industrial:Manufacturing facilities and warehouses utilize chemical-resistant flooring, ventilation ducting, and secondary containment systems. Food and beverage processors require FDA-compliant polyethylene for potable water and washdown applications.
Residential absorbs the greatest tonnage, yet Institutional procurement is gaining share fastest through sustainability-linked tender requirements.
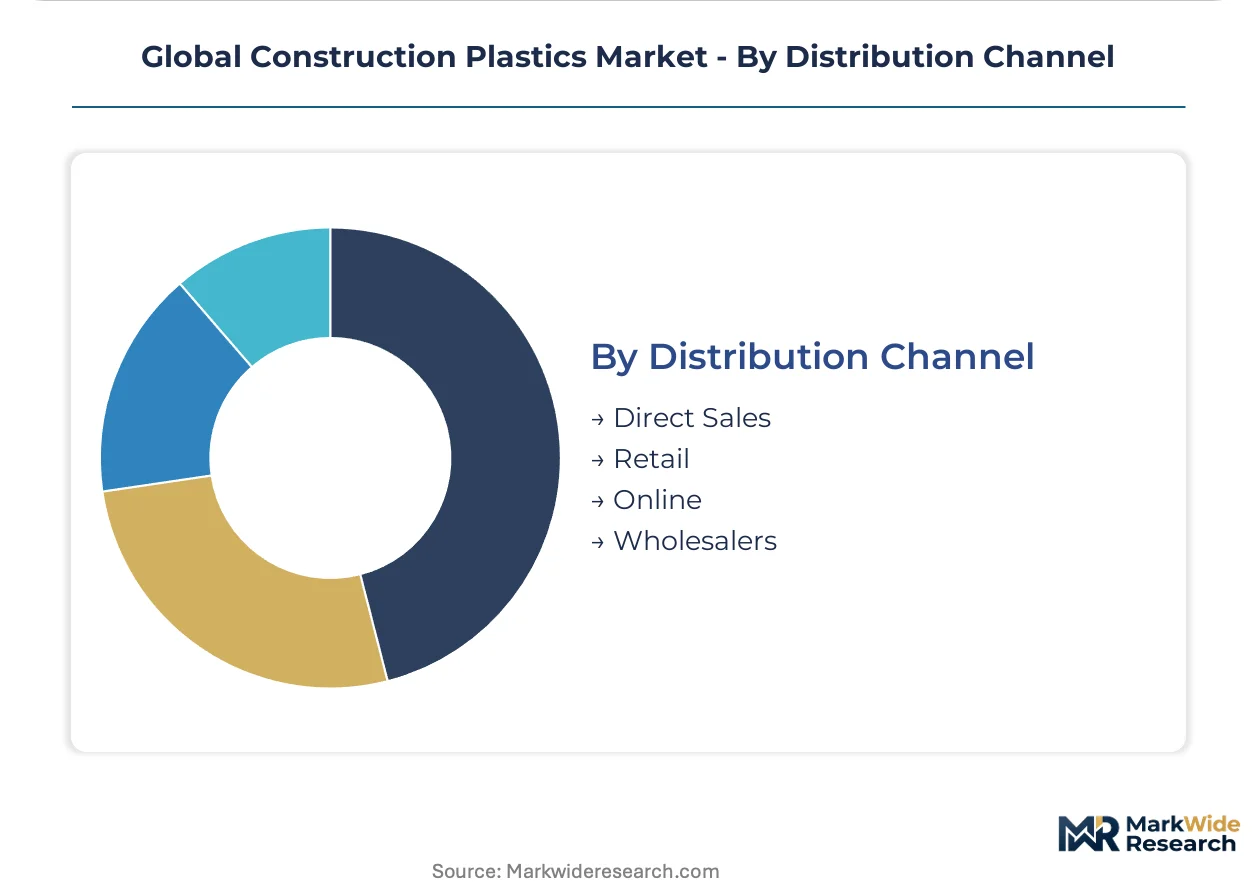
Distribution Channel:
Supply concentration patterns favor direct relationships with large developers over fragmented wholesale intermediaries.
- Direct Sales:Manufacturer-to-contractor and manufacturer-to-developer relationships secure specification control for complex commercial and institutional projects. BASF and SABIC deploy technical sales engineers to embed polyamide and polyurethane systems in European and Middle Eastern facade specifications.
- Wholesalers:Regional building-material distributors maintain inventory breadth for residential contractors and small commercial builders. Rhine corridor PVC resin clusters expose these intermediaries to barge logistics disruptions.
- Retail:Big-box home improvement and specialized trade counters serve renovation and repair demand. US residential plumbing fittings and insulation batts move through this channel for contractor and DIY pickup.
- Online:Digital procurement platforms and manufacturer-direct e-commerce gain traction among mid-sized contractors seeking price transparency. Building information modeling integration enables material traceability verification for sustainability consultants.
Direct Sales holds the leading position, while Online channels are climbing the fastest as digital specification platforms compress procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German specification-grade resin markets while Chinese volume producers compete on landed cost across Asian infrastructure tenders. European REACH mandates and embodied carbon thresholds create regulatory premiums that Asian exporters struggle to capture without mass-balance certification investments.
China
MIIT energy-efficiency codes enforce minimum thermal performance in northern provincial housing programs, channeling demand toward expanded polystyrene insulation boards. GB standards compliance gates domestic specification eligibility for public works contractors. The Yangtze River Delta cluster around Shanghai anchors compounding operations serving modular construction projects across Jiangsu and Zhejiang provinces.
United States
EPA stormwater regulations drive permeable paver and rainwater harvesting system uptake in suburban residential developments across Sun Belt states. NSF/ANSI 14 and 61 certifications gate polyethylene piping specification in potable water applications. The Gulf Coast petrochemical corridor concentrates chlor-alkali and PVC resin production, exposing downstream extruders to hurricane-season logistics disruptions.
Germany
EU Green Deal embodied carbon thresholds mandate Environmental Product Declarations for structural polymers in public works above 10 million euros, compressing allowable cradle-to-gate emissions by 40 percent against 2020 baselines. REACH phased phthalate bans accelerate bio-based plasticizer adoption in flexible PVC membranes. The Rhine corridor clusters European PVC resin production, creating river-dependent supply vulnerabilities for Ludwigshafen and Cologne compounders.
India
Urban housing programs and infrastructure renewal intensify demand for piping and weatherproofing systems across metropolitan construction markets. BIS standards enforcement tightens quality gates for imported polyethylene and polypropylene compounds. The Gujarat industrial corridor hosts compounding facilities serving prefabricated wall panel demand from Mumbai and Delhi-NCR modular construction projects.
Saudi Arabia
Localized petrochemical feedstock availability supports cost-competitive polyolefin production for Middle Eastern and Asian export markets. SAMR-equivalent building code adoption in neighboring Gulf states expands addressable market for Saudi-origin resins. The Jubail industrial city anchors SABIC compounding operations that reduce landed costs for infrastructure developers across the GCC region.
Global Construction Plastics Market Vendor Landscape
Integrated petrochemical conglomerates and specialized compounders split the market along specification complexity lines. The vendor base concentrates among ten to twelve resin producers with backward integration into feedstock refining and cracking operations. Three strategic archetypes dominate: Gulf-based feedstock-advantaged producers, European regulatory-compliance specialists, and Asian volume-scale compounders. Competitive intensity centers on mass-balance certification investments and direct-to-contractor platform development.
Within the integrated-conglomerate tier, BASF and SABIC exemplify divergent geographic anchoring strategies. BASF occupies a position as a European regulatory-compliance archetype, leveraging Ludwigshafen-based polyamide and polyurethane supply chains for specification-grade facade positions. SABIC represents the feedstock-advantaged Gulf producer model, with Jubail operations serving Middle Eastern and Asian project pipelines through localized compounding. Dow sits within the North American residential-specialist archetype, competing in high-density polyethylene resins certified to NSF/ANSI standards for plumbing applications.
| Leading Market Players |
|---|
| BASF |
| SABIC |
| Dow |
| LyondellBasell Industries Holdings B.V. |
| Borealis GmbH |
| Formosa Plastics Corporation |
| INEOS |
| Solvay |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
The Rhine corridor petrochemical cluster around Ludwigshafen and Cologne anchors European PVC resin capacity, with barge-dependent logistics creating periodic pricing volatility that downstream compounders pass through to specification-grade membrane contracts. This geographic concentration amplifies buyer power asymmetries between integrated producers and fragmented extruders.
Pricing Analysis
The customization-premium spread separates configured-to-order flame-retardant polypropylene compounds from standard polyethylene pipe resins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with mass-balance EPD verification commanding specification premiums in German public procurement. Cost compression in standard-grade polyethylene intensifies as Asian volume producers expand export capacity. Residential contractors exhibit highest price sensitivity, while institutional sustainability consultants prioritize verified lifecycle data over unit economics.
Supply Chain Analysis
Export-control regimes on advanced polymer catalyst technologies limit proprietary metallocene polyethylene licensing flows from US and European licensors to unaffiliated Asian compounders. Production gravity centers on China, Germany, and Saudi Arabia, with feedstock drawn from naphtha-cracking complexes and localized ethane derivatives. Single-source vulnerability concentrates in chlor-alkali electrolysis capacity along the Rhine corridor. Distribution runs through direct-to-contractor platforms for commercial projects, while residential channels rely on regional building-material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction plastics demand tracks residential construction cycles, with German and Dutch ground-source heat pump installation rates signaling near-term inflection points for polyethylene piping specification.
For Market Incumbents: Insulate specification-grade positions by deepening backward integration into bio-based plasticizer supply chains ahead of REACH phase-out deadlines. Secure multi-year mass-balance certification offtake agreements with European public housing developers. Defend against Asian volume producers by embedding technical sales engineers in BIM-enabled contractor platforms. For New Entrants and Emerging Players: Indian modular construction markets offer underpenetrated pathways for flame-retardant polypropylene composite specification, with BIS standard enforcement creating quality gates that favor compliant compounders. Target prefabricated wall panel producers in the Gujarat industrial corridor with localized compounding partnerships. Establish go-to-market presence through direct technical engagement with Mumbai and Delhi-NCR project developers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core construction polymer assets amid portfolio rebalancing toward specialty materials. Long-term viability hinges on mass-balance certification infrastructure and direct-channel control rather than commodity scale. Monitor German public procurement EPD disclosure rates as the inflection signal for verified circular-economy polymer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mass-Balance Certification Investment | Secures specification eligibility under EU Green Deal procurement thresholds above 10 million euros. |
| Direct-to-Contractor Platform Development | Bypasses wholesale intermediaries and captures BIM-embedded material traceability premiums. |
| Backward Integration into Bio-Plasticizers | Locks in REACH-compliant feedstock security for flexible PVC membrane production. |
| Localized Compounding in India | Reduces landed costs for modular construction projects in Mumbai and Delhi-NCR corridors. |
| Recycled Carbon Fiber Partnership | Secures aerospace waste feedstock for hybrid structural profiles in Copenhagen and Singapore facades. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymer compounders, technical sales engineers at resin producers, procurement managers at modular construction developers, and sustainability consultants advising European pension funds. Secondary validation drew from ECHA REACH registration databases, EU Tenders Electronic Daily procurement records, customs trade flows, and SEC filings of listed petrochemical conglomerates. Bottom-up volume estimates triangulated against top-down construction spending correlations.
Calibration against historical specification-grade premium realizations and infrastructure tender award patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include polymer chemistry, application function, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating MIIT code adoption timelines and EPA stormwater enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Saudi feedstock-advantaged producers or accelerated REACH phase-outs would shift outcomes beyond modeled ranges. Cross-checking against EU Tenders Electronic Daily award data and BIS import license registrations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
China Plastics Market